
 Library Management Software Market | 2026-2036
Library Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Library Management Software Market Outlook
Cloud-native specification tiers is bifurcating the competitive landscape between legacy on-premises vendors and API-first platforms. Ex Libris leverages deep vertical integration across discovery, analytics, and resource sharing to sustain its position in research-intensive institutions. SirsiDynix anchors its footprint through long-term municipal contracts with public library networks. EBSCO Information Services differentiates via tight control over content aggregation pipelines that feed directly into its management layer.
Library management software comprises integrated systems for acquisition, cataloging, circulation, serials control, and patron administration, typically built on MARC21 or BIBFRAME bibliographic standards with Z39.50 or SRU/SRW search-retrieval protocols. These platforms automate physical and digital asset workflows while exposing REST APIs for interoperability with learning management systems and institutional repositories. Cloud-based deployment now captures the fastest expansion as libraries shed server maintenance burdens, though on-premises installations retain durable share among corporate libraries with strict data residency rules. Academic libraries represent the deepest margin pool due to multi-module subscriptions spanning course reserves, electronic resource management, and research analytics.
FCC guidelines shape broadband subsidy programs that determine which libraries can sustain bandwidth-hungry cloud migrations, while GDPR and the EU AI Act impose cross-border constraints on patron behavioral analytics and automated recommendation engines. ISO 28560 RFID data standards govern physical collection tracking interoperability across hardware vendors. Stakeholders must weigh cloud migration timelines against evolving data sovereignty rulings and the interoperability demands of next-generation linked open data initiatives.
Market Dynamics
Cloud-native migration is compressing deployment cycles across academic and public library networks, forcing incumbent vendors to re-architect legacy stacks while API-first entrants capture greenfield installations with modular subscription models.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European academic libraries are accelerating procurement of platforms with built-in patron data anonymization and algorithmic audit trails, creating replacement demand for non-compliant legacy systems.
- FCC broadband subsidy expansion:Rural library districts in the United States are leveraging E-Rate program upgrades to fund bandwidth infrastructure capable of sustaining cloud-native management platforms.
- Consortium purchasing consolidation:University systems in California, Texas, and New York are negotiating enterprise-wide licenses that displace individual institutional contracts, concentrating vendor revenue into fewer but larger accounts.
Market Restraints
- Data sovereignty fragmentation:Cross-border patron record storage faces conflicting rulings between GDPR's right-to-erasure and US CLOUD Act discovery obligations, complicating multi-national academic deployments.
- On-premises technical debt:Municipal public libraries with 15-20 year-old SirsiDynix or Innovative Interfaces installations lack internal DevOps capacity to execute cloud migrations without expensive third-party systems integrators.
- Z39.50 protocol lock-in:Legacy bibliographic search-retrieval infrastructure persists in 40% of installed bases, delaying SRU/SRW and BIBFRAME adoption that would enable modern API interoperability.
Strategic Opportunities
- India's National Digital Library infrastructure:Ministry of Education funding for unified academic repository networks creates demand for scalable cloud platforms with multi-language cataloging support and UPI-integrated fine payment modules.
- Linked open data convergence:Integration of BIBFRAME 2.0 bibliographic models with Wikidata entity reconciliation is enabling next-generation discovery layers that displace traditional OPAC interfaces in research-intensive institutions.
- RFID-integrated self-service workflows:ISO 28560-compliant hardware-software bundles are penetrating mid-size public library systems that previously deferred capital expenditure on automated materials handling.
Industry Challenges
- MARC21-to-BIBFRAME migration expertise:Cataloging departments face acute shortages of metadata specialists capable of executing semantic web transformations while maintaining day-to-day acquisition and serials control operations.
- API security certification timelines:Vendor development cycles are extending 8-14 months to complete SOC 2 Type II and ISO 27001 audits required by university procurement offices, delaying feature releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Library Management Software Market |
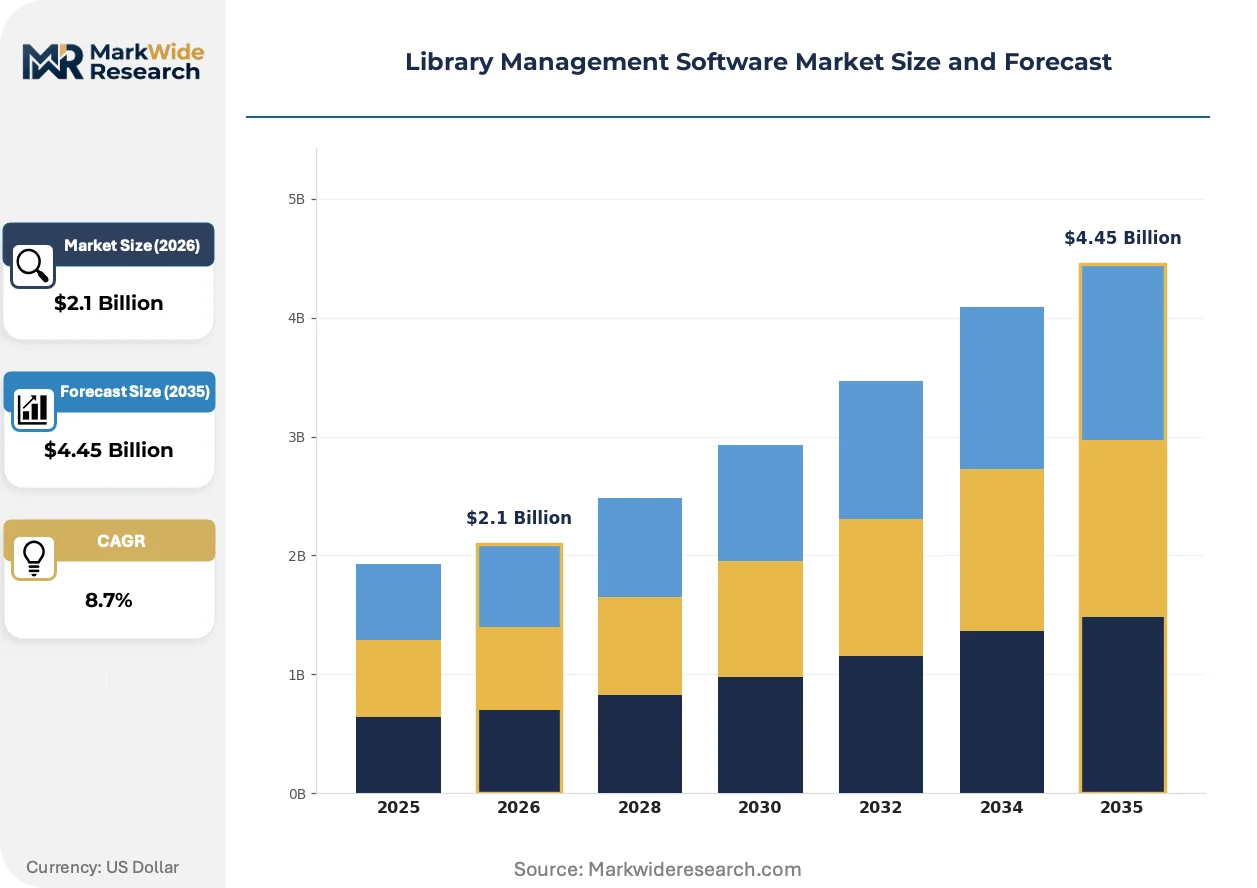
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Academic Libraries, Public Libraries, Special Libraries, Corporate Libraries Functionality: Cataloging, Circulation Management, User Management, Reporting Integration: ERP Systems, CRM Software, Discovery Tools, RFID Systems |
| Companies Covered | ProQuest, SirsiDynix, Axiell Group, Innovative Interfaces, Ex Libris, Follett, Civica, EBSCO Information Services, CR2 Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Library Management Software Market Strategic Shifts
Artificial intelligence is embedding into core workflow automation, compressing the boundary between discovery interfaces and back-office management systems while regulatory pressure on algorithmic transparency reshapes vendor development priorities.
Edge computing architectures for library branch networks are miniaturizing. Distributed processing nodes now handle patron authentication and circulation transactions locally before syncing to central cloud repositories, reducing latency for rural installations with intermittent connectivity. Academic library consortia in Australia and Canada are piloting these deployments to maintain service continuity during backbone outages.
GDPR Article 22 restrictions on automated decision-making are forcing European vendors to retrofit recommendation engines with explicit human-in-the-loop controls for patron reading suggestions. This regulatory friction is diverting R&D resources from feature innovation toward compliance engineering, disproportionately affecting vendors with heavy EU academic exposure.
Subscription fatigue among mid-size public libraries is driving unbundling of integrated library system modules. Kansas and Ohio library networks are negotiating à-la-carte contracts separating discovery layers from circulation management, enabling best-of-breed procurement that fragments vendor account control.
Library Management Software Market Segmentation
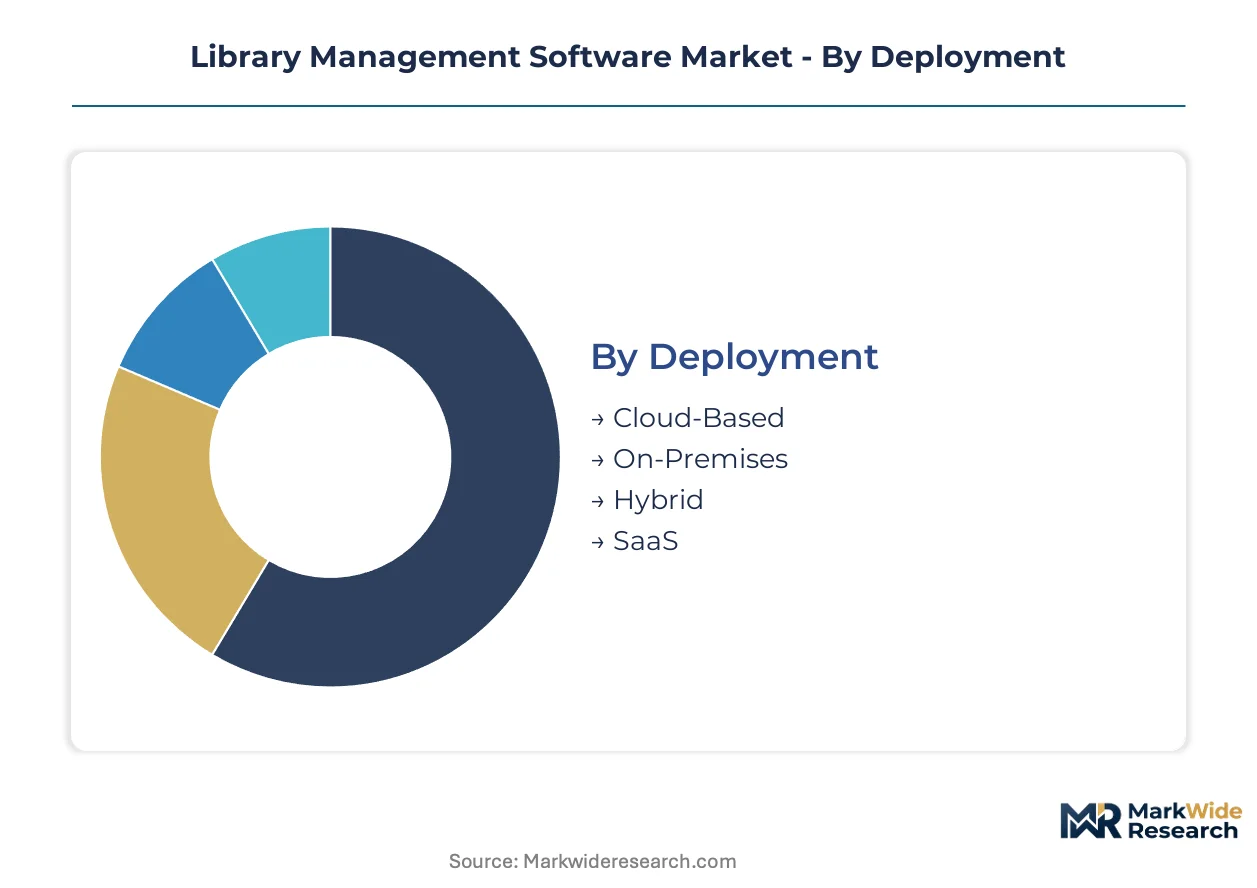
Library management software procurement patterns diverge sharply across deployment models and institutional types, with margin concentration following the complexity of multi-module subscriptions rather than transaction volume alone.
Deployment:
Margin pools concentrate in recurring subscription architectures that shift infrastructure burden from library IT staff to vendor operations teams.
- Cloud-Based:Multi-tenant architectures with automatic security patching and elastic compute scaling dominate research university procurement in the United States and Australia. California State University system consolidated 23 campuses onto a single cloud-native platform, eliminating per-site server maintenance contracts.
- SaaS:Pre-configured workflow templates with API marketplaces accelerate deployment for mid-size public libraries lacking dedicated systems administrators. Kansas library networks negotiate à-la-carte module subscriptions that separate discovery layers from circulation management.
- On-Premises:Air-gapped installations persist among corporate legal libraries with strict data residency requirements.
- Hybrid:Split architectures keep sensitive patron records local while offloading discovery indexes to cloud infrastructure.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
End User:
Application intensity varies by institutional mission, with research workflows demanding deeper analytics integration than community lending operations.
- Academic Libraries:Multi-module subscriptions spanning course reserves, electronic resource management, and research analytics command premium pricing tiers. University consortiums in Texas and New York drive collective purchasing power that concentrates vendor revenue into enterprise-wide licenses.
- Public Libraries:Municipal budget cycles and E-Rate subsidy dependencies shape procurement timing for cloud migration projects.
- Special Libraries:Medical and law firm collections require specialized taxonomies and compliance audit trails.
- Corporate Libraries:Knowledge management integration with internal document repositories differentiates vendor selection criteria.
Academic Libraries capture the deepest margin pool, with Public Libraries expanding most quickly through federal broadband infrastructure programs.
Functionality:
Volume concentration follows workflow automation depth, with modules touching physical collection movement generating more transactions than metadata management tools.
- Circulation Management:Self-service kiosk integration and automated materials handling drive hardware-software bundle sales in mid-size public systems. ISO 28560 RFID compliance requirements govern interoperability across scanner and sorter vendors.
- Cataloging:BIBFRAME 2.0 semantic web transformations require specialized metadata expertise that constrains migration timelines.
- User Management:GDPR Article 22 compliance mandates human-in-the-loop controls for automated reading recommendations.
- Reporting:Patron behavioral analytics face cross-border constraints between European erasure rights and US discovery obligations.
Circulation Management maintains installed base dominance, while Cataloging is gaining share fastest through linked open data initiatives.
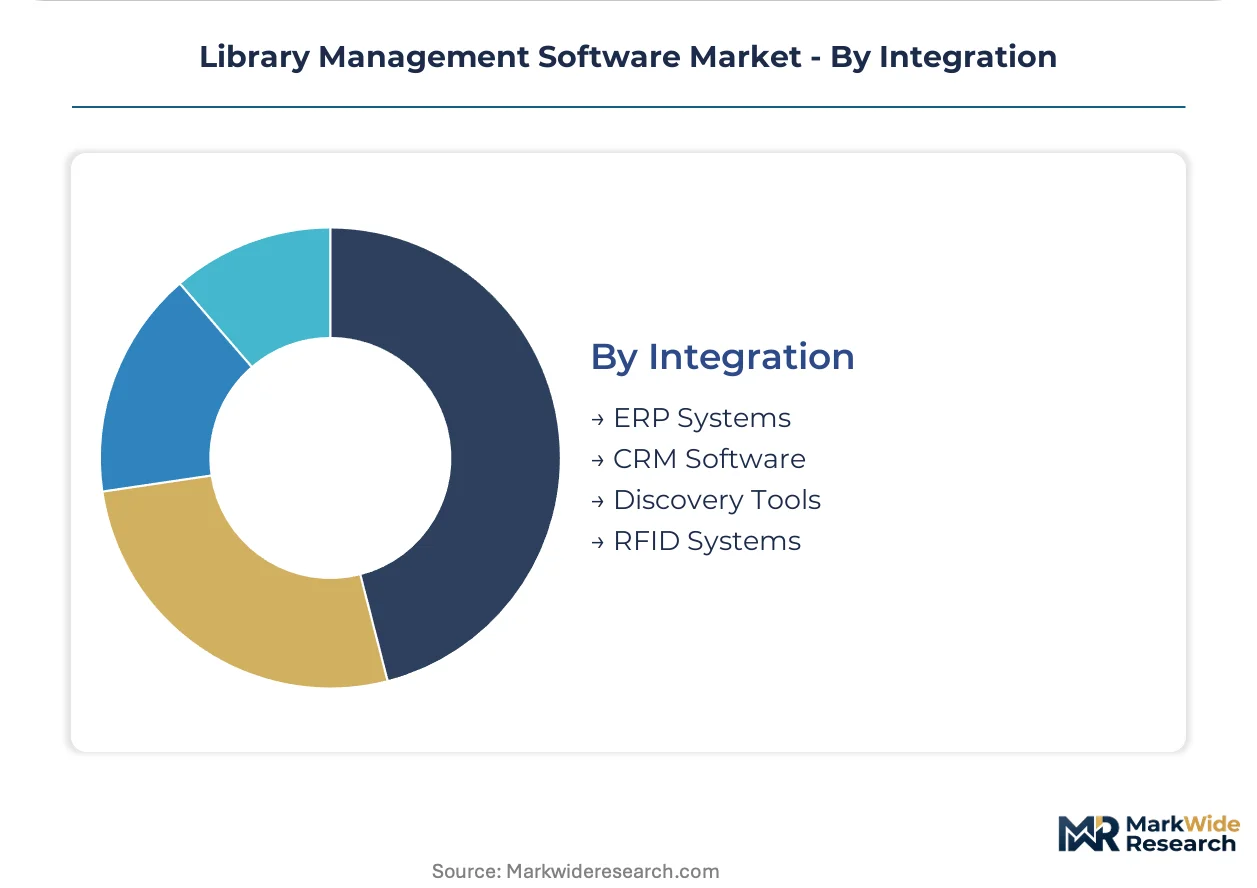
Integration:
Customer type determines interoperability priority, with learning management system connectivity essential for academic procurement and RFID hardware compatibility decisive for public library selections.
- RFID Systems:ISO 28560 data standards enable mixed-vendor environments where libraries upgrade hardware without replacing management platforms. Australian and Canadian consortia pilot edge computing nodes that handle authentication locally before cloud sync.
- Discovery Tools:Content aggregation pipelines feed directly into management layers, creating vendor lock-in through exclusive index licensing.
- ERP Systems:Financial module integration streamlines acquisition workflows for university procurement offices.
- CRM Software:Patron communication automation supports fundraising and program marketing in foundation-supported libraries.
RFID Systems anchor physical collection automation, with Discovery Tools climbing the fastest as next-generation OPAC replacements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Library management software trade flows concentrate in knowledge-intensive economies with dense research infrastructure. Import dependency characterizes emerging academic systems, while mature markets generate platform exports through vendor headquarters concentration.
United States
University consortiums in California, Texas, and New York negotiate enterprise-wide licenses that displace individual institutional contracts. FCC E-Rate broadband subsidies enable rural library districts to fund cloud migration infrastructure. The Boston-Cambridge research corridor anchors vendor development activity for research-intensive institutional deployments.
Germany
Academic libraries accelerate procurement of platforms with built-in patron data anonymization capabilities. GDPR Article 22 and the EU AI Act impose strict algorithmic audit requirements for automated recommendation engines. The Baden-Württemberg university cluster drives standardization demands across southwestern state library networks.
United Kingdom
Municipal public library networks seek modular subscription models to unbundle discovery layers from circulation management. The UK Information Commissioner's Office enforces GDPR-derived data protection standards for cross-border patron record processing. The Greater London Authority coordinates procurement for borough library systems seeking cloud-native replacements.
India
Ministry of Education funding for National Digital Library infrastructure creates demand for scalable platforms with multi-language cataloging support. The University Grants Commission mandates digital repository interoperability standards for affiliated institutions. The Delhi-NCR academic corridor concentrates pilot deployments for UPI-integrated fine payment modules.
Australia
Academic library consortia pilot edge computing architectures to maintain service continuity during backbone outages. The Office of the Australian Information Commissioner applies privacy principles governing patron behavioral analytics. The Melbourne-Sydney university axis drives collective purchasing power for cloud-native platform consolidation.
Library Management Software Market Competitive Environment
Concentration sits with vertically integrated platform vendors controlling content aggregation pipelines and discovery layer integration. The market structure divides between legacy on-premises incumbents with long-term municipal contracts and API-first entrants capturing greenfield cloud installations. Two strategic archetypes dominate: research-intensive specialists bundling analytics with resource sharing, and public network generalists anchoring through multi-decade service relationships. Competitive moves center on consortium license consolidation and modular unbundling responses to subscription fatigue.
Within the integrated platform tier, Ex Libris and EBSCO Information Services exemplify archetypes combining management layers with captive content pipelines. SirsiDynix occupies a position representing legacy incumbents with durable municipal public library footprints. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| ProQuest |
| SirsiDynix |
| Axiell Group |
| Innovative Interfaces |
| Ex Libris |
| Follett |
| Civica |
| EBSCO Information Services |
| CR2 Technologies |
| Others |
Value Chain & Pricing Dynamics
Enterprise-wide consortium licensing locks in multi-year supply access for cloud-native platforms while compressing price visibility for individual institutions negotiating outside collective frameworks. California State University system contracts demonstrate how bulk procurement eliminates per-site server maintenance variability and stabilizes vendor revenue forecasting across the analysis window.
Pricing Analysis
University consortiums anchor three-tier subscription pricing across premium, standard, and economy levels differentiated by module breadth and analytics depth. Premium tiers bundle electronic resource management with research analytics for R1 institutions, while economy tiers serve rural public libraries with circulation-only configurations. Pricing pressure stems from municipal budget compression in mid-size public systems, driving unbundled à-la-carte procurement that fragments vendor account control. Public library networks exhibit highest price sensitivity due to E-Rate subsidy dependencies, whereas research-intensive institutions prioritize functionality over cost.
Supply Chain Analysis
Software inventory cycles compress to quarterly release schedules as cloud-native vendors automate security patching and elastic compute provisioning. Development talent concentrates in the United States, Israel, and India, with Bangalore and Tel Aviv emerging as satellite engineering hubs for platform localization. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Singapore, creating single-source vulnerability to regional backbone outages. Distribution runs through direct enterprise sales teams for academic consortia and value-added resellers for fragmented public library networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native disruption is compressing deployment cycles while GDPR Article 22 and the EU AI Act impose algorithmic audit requirements that reshape vendor R&D priorities. This regulatory inflection creates replacement demand for non-compliant legacy systems and opens white-space for API-first entrants.
For Market Incumbents: Consolidate municipal public library relationships through multi-decade service contract extensions before API-first competitors capture greenfield cloud installations. Acquire specialized metadata consultancies to address MARC21-to-BIBFRAME migration expertise shortages threatening customer retention. Prioritize SOC 2 Type II and ISO 27001 certification fast-tracks to satisfy university procurement office requirements.
For New Entrants and Emerging Players: GDPR-compliant algorithmic audit trails fast-track European academic library penetration where legacy vendors face retrofitting delays. Target India's National Digital Library infrastructure where Ministry of Education funding creates scalable demand for multi-language cataloging platforms. Lead with UPI-integrated fine payment modules and Wikidata-linked discovery layers as differentiated go-to-market anchors.
For Investors and Strategic Acquirers: Capital is best deployed toward API-first platforms with modular subscription architectures capturing consortium purchasing consolidation. Long-term viability hinges on vertical integration depth across content aggregation pipelines and discovery layer control. Watch for FCC E-Rate subsidy expansion signals indicating rural broadband infrastructure readiness for cloud migration acceleration.
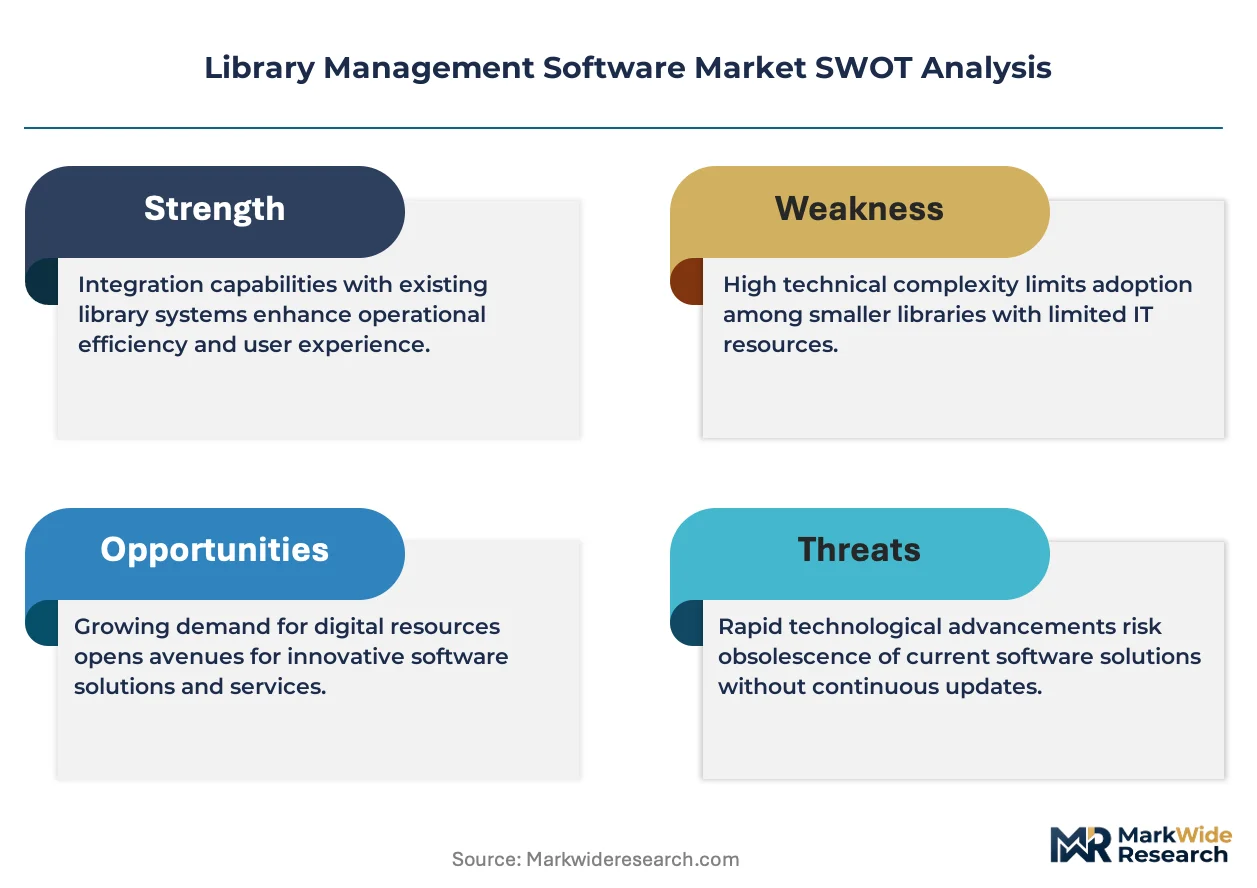
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable modular unbundling responses to subscription fatigue in Kansas and Ohio networks. |
| Acquisition of Specialist Firm | Metadata consultancy purchases address acute BIBFRAME migration expertise shortages constraining cataloging departments. |
| Geographic Expansion | India's National Digital Library infrastructure creates demand for scalable cloud platforms with UPI-integrated payments. |
| Strategic Partnership | Hyperscaler alliances secure elastic compute capacity for California State University system consolidated deployments. |
| Product Launch | Edge computing nodes for Australian and Canadian consortia maintain service continuity during backbone outages. |
Study Parameters
Operator-level perspectives from university library CIOs, municipal public library directors, consortium procurement officers, and metadata specialists anchored the qualitative base. Primary interviews combined with secondary validation drawn from FCC E-Rate program disclosures, university system RFP documentation, GDPR regulatory filings, and ISO 28560 RFID standard publications. Bottom-up campus-level deployment tracking triangulated against top-down vendor revenue segmentation.
Sensitivity analysis tested forecast robustness across cloud migration acceleration scenarios and regulatory compliance cost variations. The modeling framework segmented by deployment architecture, institutional type, module functionality, and integration complexity throughout the forecast period. CAGRs derived from installed base replacement cycles, greenfield procurement velocity, and subscription renewal rate trajectories. Inputs included E-Rate subsidy allocation patterns and EU AI Act implementation timelines.
Underlying assumptions cover broadband infrastructure readiness, regulatory enforcement consistency, and metadata specialist labor availability, with deviation risk concentrated in data sovereignty ruling fragmentation between GDPR and US CLOUD Act obligations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Nosql Database Market
Software & Services
Chatbot Builder Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Global App Builder Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Professional Service Automation Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Live Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Identity Resolution Software Market
Software & Services
Online Recruitment Software Market