
 Sales Training Software Market | 2026-2036
Sales Training Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Training Software Market Intelligence
Revenue from post-deployment coaching and analytics is reconfiguring how vendors capture lifetime value in the Sales Training Software Market. Highspot leverages AI-powered content recommendations to anchor enterprise accounts. Gong sustains differentiation through conversation intelligence that captures and analyzes sales calls. Mindtickle competes by integrating readiness scoring with revenue operations workflows.
Sales training software encompasses cloud-hosted and on-premises platforms that deliver structured curricula, skills assessment, and performance analytics through interactive modules, video role-play, and gamified progress tracking to improve seller effectiveness and quota attainment. Cloud-based deployment leads structural adoption as enterprises prioritize scalability and remote accessibility over capital-intensive on-premises installations. Subscription-based pricing dominates commercial relationships, while gamification features capture disproportionate R&D investment as vendors seek engagement differentiation.
US employers face OSHA training documentation requirements and SEC disclosure standards that elevate audit-ready certification tracking in financial services deployments. India's BIS information security guidelines and Germany's GDPR-aligned data residency expectations shape product architecture for multinational rollouts. Stakeholders must weigh interoperability against proprietary ecosystem lock-in when selecting platforms.
Market Dynamics
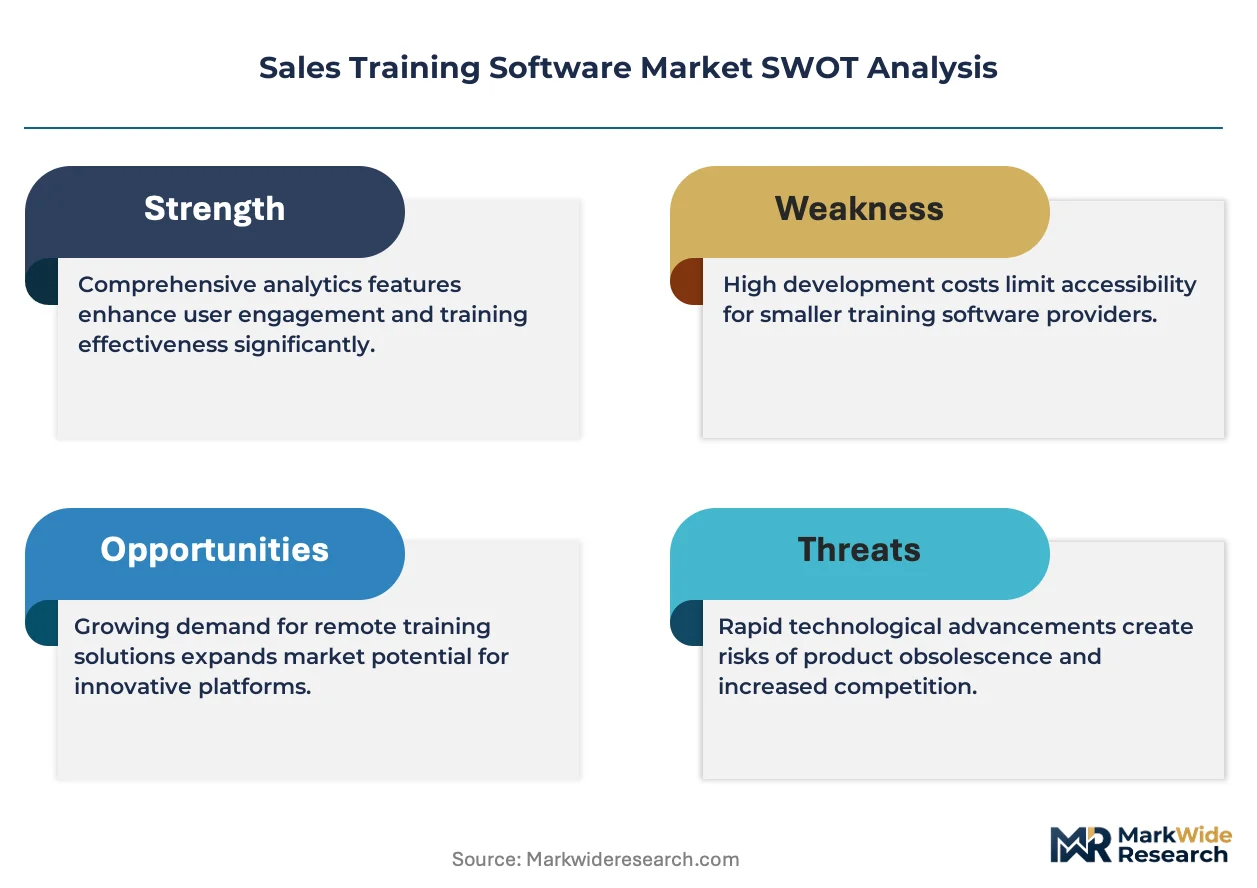
AI-powered conversation intelligence is collapsing the traditional separation between training delivery and live sales execution, forcing vendors to re-architect platforms around real-time coaching rather than static content libraries.
Growth Catalysts
- OSHA Documentation Mandates:US employers in manufacturing and logistics verticals require audit-ready certification tracking for workplace safety training, creating demand for platforms with automated compliance logging.
- Pharmaceutical Field Force Expansion:Life sciences companies deploy AI-driven role-play modules to accelerate rep onboarding for specialty therapeutic areas with complex clinical protocols.
- GDPR-Aligned Data Residency:Germany's strict localization requirements push multinationals toward European-hosted instances, expanding addressable market for regional cloud providers.
Market Restraints
- Enterprise Integration Costs:CRM and revenue operations system connectivity demands specialized engineering resources that inflate total cost of ownership beyond subscription fees.
- Data Sovereignty Fragmentation:Conflicting national storage requirements across India, Germany, and the United States complicate single-tenant architecture for global rollouts.
- Skills Assessment Standardization Gap:Absence of industry-recognized competency frameworks forces buyers to build custom evaluation rubrics, extending procurement cycles.
Strategic Opportunities
- India's BPO-Adjacent Market:Customer experience outsourcing hubs in Bangalore and Hyderabad represent underpenetrated demand for accent-neutralization and objection-handling training modules.
- SEC Climate Disclosure Rules:Emerging requirements for ESG reporting in financial services create openings for sustainability-focused sales certification content.
- Voice-to-Text Convergence:Integration of natural language processing with video coaching platforms enables automated feedback generation without human reviewer bottlenecks.
Industry Challenges
- Instructional Design Talent Scarcity:Shortage of professionals who combine adult learning expertise with technical platform administration limits content quality at scale.
- Multi-System Authentication Complexity:Single sign-on implementation across corporate identity providers, learning management systems, and revenue operations stacks creates deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Training Software Market |
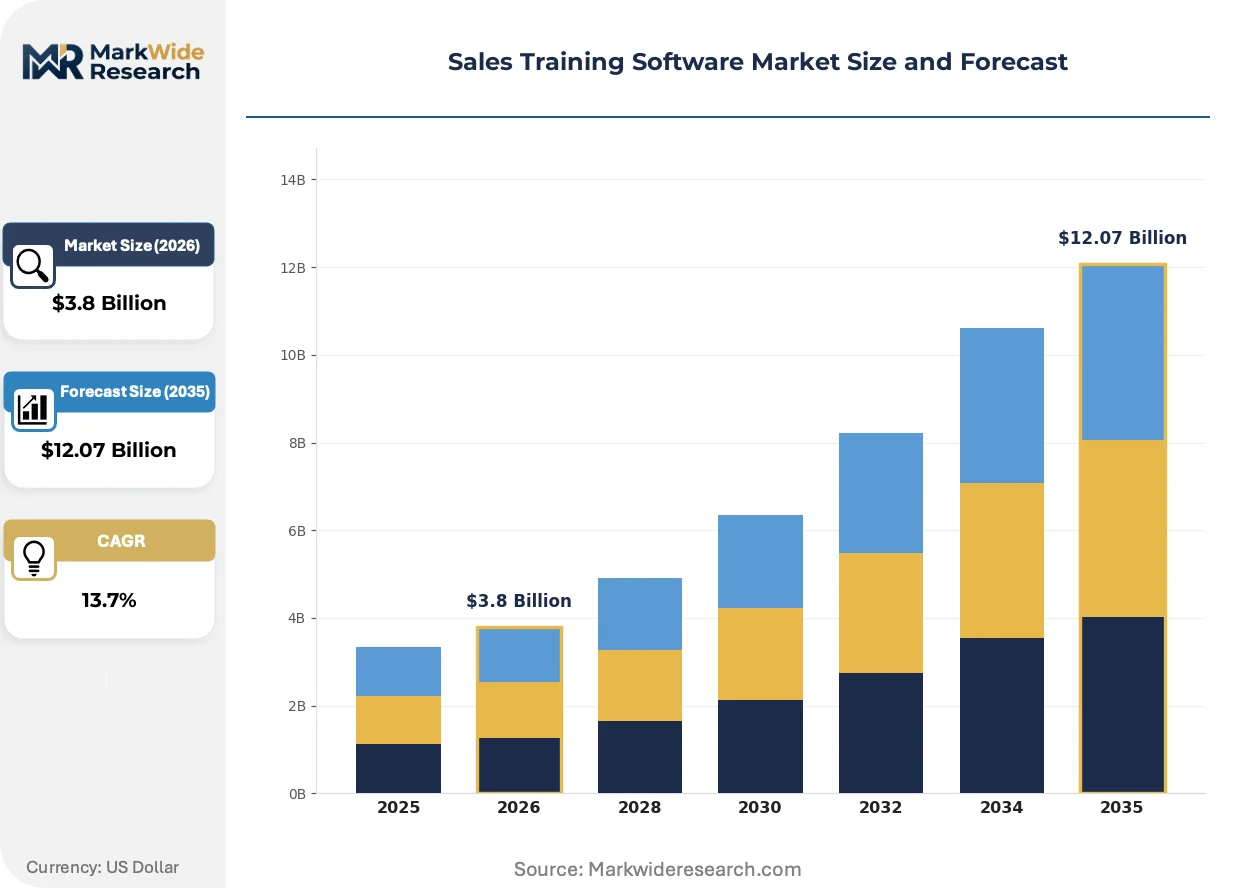
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premises, Hybrid, Web-hosted User Type: Corporations, Small Enterprises, Startups, Educational Institutions Feature Set: Gamification, Performance Tracking, Interactive Content, Feedback Mechanisms Pricing Model: Subscription-based, One-time License, Freemium, Pay-per-Use |
| Companies Covered | Highspot, 360Learning, Retorio, iSpring Learn, Bigtincan, Allego, Gong, CoachHub, Mindtickle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Training Software Market Strategic Shifts & Innovations
Generative AI is compressing content production timelines while simultaneously elevating buyer expectations for personalization, creating a capability arms race among platform providers.
Real-time conversation intelligence is collapsing the distinction between training environments and live customer interactions. Sales organizations embed AI coaching directly into video conferencing platforms, capturing actual prospect calls for immediate skill gap analysis. Pharmaceutical and financial services buyers now demand this capability as table stakes, compressing pricing power for vendors lacking native integration.
The EU AI Act's risk classification framework is reshaping product development priorities for vendors serving European enterprises. High-risk system designations for automated decision-making in hiring and performance evaluation trigger mandatory conformity assessments. German and French deployments increasingly require human-in-the-loop architectures for coaching recommendations, forcing architectural retrofits.
Buyer procurement committees now mandate proof-of-concept pilots before enterprise commitments, extending sales cycles but reducing implementation failure rates. Procurement teams evaluate platforms against specific quota-attainment improvement metrics rather than engagement analytics alone. This shift is most pronounced in United States technology and financial services verticals, where CFO involvement in training software selection has doubled.
Sales Training Software Market Segmentation
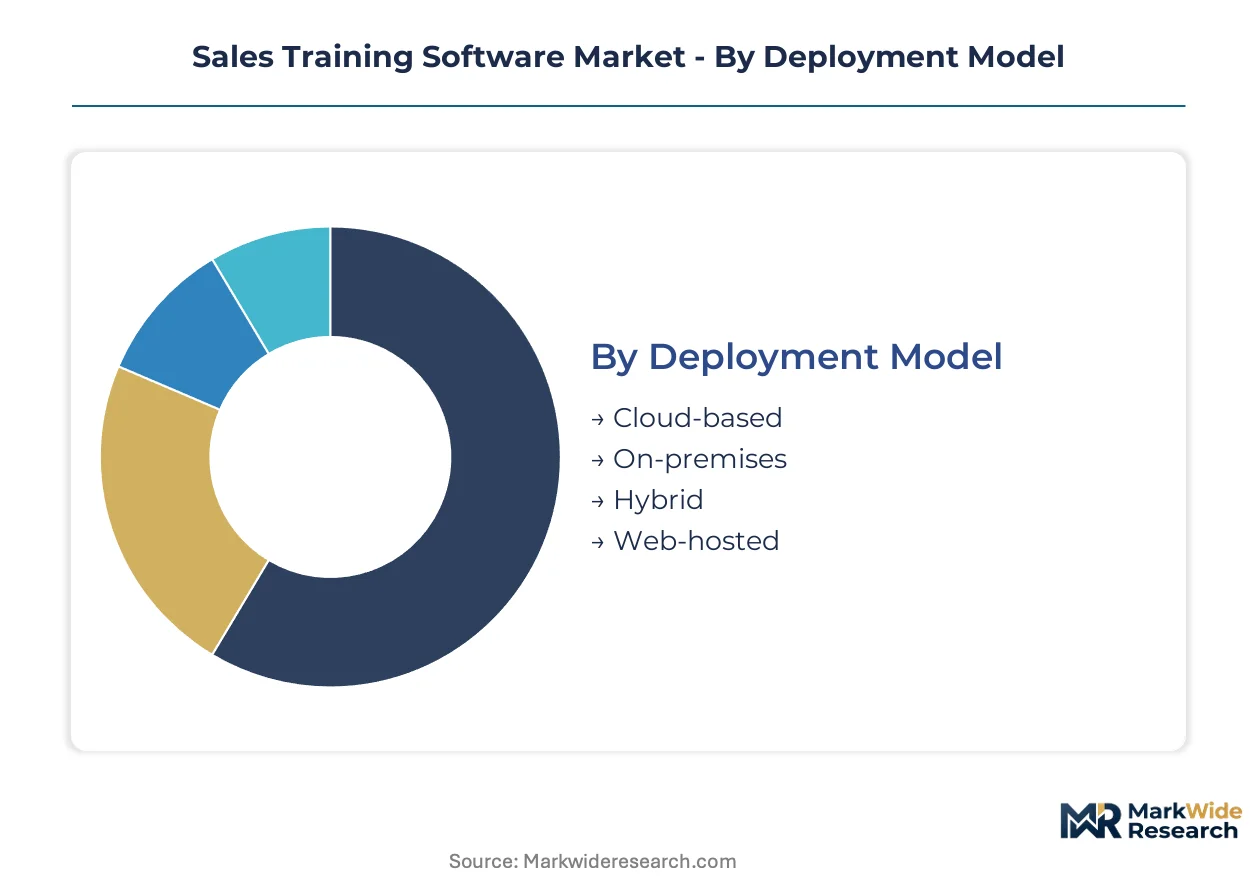
Deployment architecture determines service intensity and renewal economics in the Sales Training Software Market. Platform configuration directly shapes integration complexity, data residency compliance, and long-term vendor relationships across pharmaceutical and financial services verticals.
Deployment Model:
After-sales service intensity peaks with cloud-based implementations requiring continuous uptime guarantees and security patch management.
- Cloud-based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling through AWS, Azure, or Google Cloud infrastructure. Demand concentrates in United States technology and financial services firms prioritizing remote accessibility and rapid deployment without capital expenditure.
- On-premises:Single-tenant installations within client data centers provide maximum control over sensitive conversation recordings and performance data. German pharmaceutical and banking buyers favor this model to satisfy GDPR data localization requirements and internal audit protocols.
- Hybrid:Split architectures host core learning management on-premises while leveraging cloud analytics for AI coaching modules.
- Web-hosted:Browser-accessible platforms without dedicated mobile applications serve cost-conscious small enterprise segments.
Cloud-based holds the largest share; momentum sits with hybrid configurations bridging compliance and flexibility.
User Type:
Customer lifetime value varies dramatically across organizational maturity stages, with corporations demanding enterprise-grade customization.
- Corporations:Fortune 500 deployments integrate sales training platforms with existing Salesforce, SAP, or Oracle ecosystems through API connections. United States and German life sciences companies drive demand for AI-powered role-play certification tracking aligned with FDA and EMA promotional material guidelines.
- Small Enterprises:Mid-market buyers prioritize out-of-box functionality with minimal IT overhead. India's expanding BPO sector in Bangalore and Hyderabad represents concentrated demand for accent-neutralization and objection-handling modules.
- Startups:Venture-backed technology firms favor freemium entry points with rapid scaling paths.
- Educational Institutions:Business schools and corporate training centers adopt platforms for sales curriculum delivery.
Corporations dominate current revenue; small enterprises are expanding most quickly as vertical-specific templates reduce implementation friction.
Feature Set:
Development resource allocation tilts toward engagement mechanics that differentiate renewal conversations.
- Gamification:Leaderboards, badges, and competitive challenges sustain seller motivation through extended onboarding programs. Financial services buyers in New York and London mandate these features for millennial and Gen Z workforce retention.
- Performance Tracking:Real-time dashboards correlating training completion with quota attainment provide CFO-visible ROI documentation. Pharmaceutical field force managers rely on these tools to demonstrate rep readiness before specialty therapeutic launches.
- Interactive Content:Branching scenarios and video role-play replace static PowerPoint modules.
- Feedback Mechanisms:Peer review and manager coaching loops close skill gaps.
Performance tracking commands the largest investment; gamification features gain share fastest among retention-focused buyers.
Pricing Model:
Revenue predictability and customer acquisition cost structures diverge sharply across commercial frameworks.
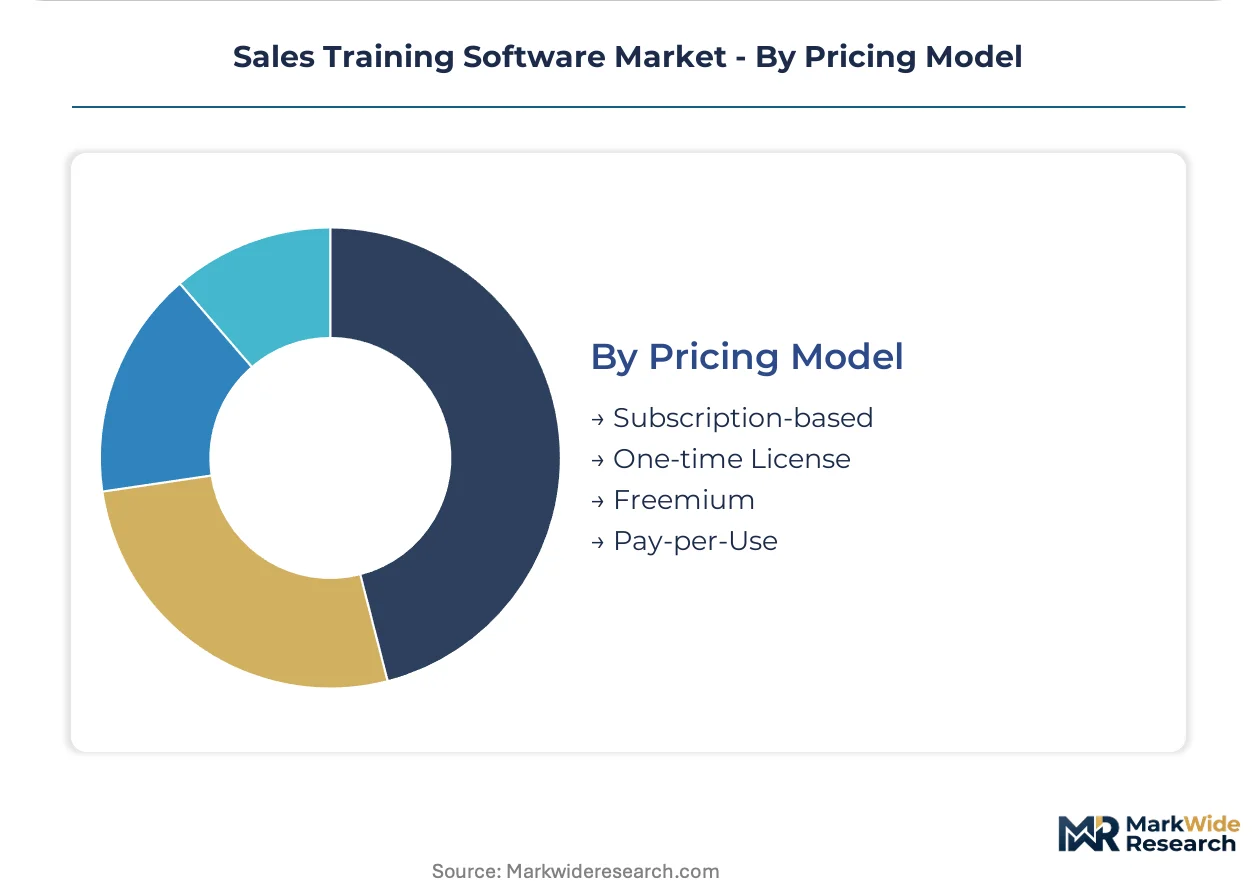
- Subscription-based:Annual or monthly recurring revenue models dominate enterprise relationships, with pricing tiers scaling by user count and feature depth. United States technology vendors pioneered this structure, now standard across German and Indian competitive alternatives.
- One-time License:Perpetual purchase with maintenance contracts persists in security-sensitive German banking and public sector deployments.
- Freemium:Limited-feature entry points convert to paid tiers through usage thresholds.
- Pay-per-Use:Consumption-based billing aligns costs with actual training delivery.
Subscription-based anchors vendor valuations; freemium models show the steepest expansion trajectory among startup and small enterprise penetration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States buyers prioritize real-time conversation intelligence embedded in live sales workflows, while German and Indian adopters emphasize compliance documentation and scalable onboarding for outsourced workforces respectively.
United States
Financial services and pharmaceutical verticals drive demand for AI-powered coaching modules that integrate with Salesforce and Microsoft Teams environments. SEC disclosure standards and OSHA training documentation requirements elevate audit-ready certification tracking as a procurement priority. Enterprise deployments concentrate in New York, San Francisco, and Boston where quota-attainment metrics dominate vendor evaluation criteria.
Germany
Pharmaceutical field forces and banking institutions require GDPR-aligned data residency with on-premises or European-hosted cloud instances. The EU AI Act's risk classification framework mandates human-in-the-loop architectures for automated coaching recommendations. Industrial demand clusters in Frankfurt's financial district and Munich's life sciences corridor where EMA promotional material guidelines shape platform specifications.
India
BPO and customer experience outsourcing hubs in Bangalore and Hyderabad represent concentrated demand for accent-neutralization and objection-handling training modules. BIS information security guidelines influence product architecture for multinational rollouts. Domestic technology firms in Gurgaon and Pune are expanding adoption of subscription-based platforms for millennial workforce retention.
United Kingdom
Enterprise technology and professional services sectors prioritize gamification features for Gen Z seller engagement. FCA conduct rules and emerging CSRD reporting requirements elevate compliance tracking capabilities in financial services deployments. London's fintech corridor and Manchester's regional banking centers anchor domestic demand concentration.
Japan
Life sciences and industrial equipment manufacturers seek structured curricula aligned with METI digital transformation initiatives. PMDA regulatory documentation requirements for pharmaceutical sales forces necessitate specialized certification tracking. Demand concentrates in Tokyo's corporate headquarters and Osaka's medical device manufacturing clusters where hierarchical training protocols persist.
Sales Training Software Market Key Industry Players
Capability concentration sits with specialized AI coaching vendors; scale advantage sits with established revenue operations platforms. The market exhibits tiered fragmentation where conversation intelligence specialists, content management incumbents, and integrated readiness platforms occupy distinct competitive positions. Three archetypes dominate: real-time call analysis providers, AI-powered content recommendation engines, and comprehensive readiness scoring platforms. Strategic moves center on API ecosystem expansion and vertical-specific certification template libraries.
Within the conversation intelligence archetype, Gong and Allego occupy positions that exemplify real-time coaching integration. Among content-centric platforms, Highspot anchors the AI-powered recommendation tier. Mindtickle sits within the integrated readiness category, representing vendors that combine skills assessment with revenue operations workflows. These three companies illustrate how geographic origin and platform architecture shape competitive differentiation without converging on identical capability sets.
| Leading Market Players |
|---|
| Highspot |
| 360Learning |
| Retorio |
| iSpring Learn |
| Bigtincan |
| Allego |
| Gong |
| CoachHub |
| Mindtickle |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud infrastructure across United States hyperscaler regions is compressing compute costs for SaaS vendors, forcing subscription pricing downward while simultaneously enabling AI feature expansion without proportional cost pass-through. This utilization dynamic rewards vendors with scale economics while squeezing mid-tier competitors into feature-limited tiers.
Pricing Analysis
Long-term enterprise offtake contracts dominate commercial relationships, with annual subscription tiers scaling by user count and integration depth. Price differentiation rests on certification-grade compliance modules and vertical-specific template libraries, with pharmaceutical and financial services buyers paying premiums for FDA and SEC-aligned audit trails. Cost compression in the mid-market tier is intensifying because freemium entrants are capturing startup segments with zero-touch onboarding. Small enterprises in India's BPO corridor exhibit highest price sensitivity, while German pharmaceutical buyers show lowest elasticity due to GDPR-mandated data residency requirements.
Supply Chain Analysis
Upstream feedstock for AI coaching capabilities draws from natural language processing models trained on proprietary conversation datasets, with concentration in United States, United Kingdom, and Israeli research hubs. Cloud compute infrastructure rests on AWS, Azure, and Google Cloud data centers, while mobile development talent clusters in India and Eastern Europe. Single-source vulnerability sits with NVIDIA GPU supply for real-time inference workloads. Distribution runs through direct enterprise sales teams augmented by systems integrator partnerships for Salesforce and Microsoft ecosystem deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents high-growth disruption as generative AI collapses content production timelines and elevates buyer expectations for real-time personalization. The EU AI Act's risk classification framework for automated decision-making systems creates immediate architectural compliance requirements for European deployments.
For Market Incumbents: Build data moats through proprietary conversation intelligence datasets that emerging entrants cannot replicate without years of enterprise deployment history. Incumbents should deepen API ecosystem integrations with Salesforce and Microsoft Teams to increase switching costs, while investing in human-in-the-loop architectures that preempt EU AI Act compliance retrofits. The threat of well-capitalized hyperscalers entering conversation intelligence makes vertical-specific certification template libraries a critical defensive lever.
For New Entrants and Emerging Players: Establish a beachhead in India's BPO-adjacent customer experience outsourcing market, where accent-neutralization and objection-handling modules face limited incumbent penetration. New entrants should target small enterprise segments in Bangalore and Hyderabad with consumption-based billing that aligns costs with seasonal hiring cycles. A channel-centric go-to-market approach through regional systems integrators accelerates trust-building in compliance-sensitive buyer committees.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because conversation intelligence, content management, and readiness scoring capabilities are converging toward unified revenue operations architectures. Acquisition targets should exhibit vertical-specific AI training data in pharmaceutical or financial services, plus native GDPR-compliant infrastructure. The signal to watch is CFO involvement in procurement committees shifting evaluation criteria from engagement metrics to quota-attainment ROI documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and Microsoft Teams embedding captures workflow-centric buyers in United States financial services. |
| Vertical Certification Library | FDA and EMA-aligned promotional material templates differentiate pharmaceutical field force deployments in Germany. |
| Geographic Expansion | European-hosted cloud instances satisfy GDPR data residency mandates for German banking and life sciences buyers. |
| Strategic Partnership | Systems integrator alliances reduce enterprise sales cycles and accelerate compliance documentation for SEC and OSHA requirements. |
| Acquisition of Specialist Firm | Conversation intelligence specialists add real-time coaching capabilities that pharmaceutical buyers now demand as table stakes. |
Research Approach
Cross-validation between executive interviews with sales enablement leaders and secondary analysis of vendor pricing disclosures anchors the qualitative findings. Primary fieldwork engaged chief revenue officers, sales training directors, IT procurement officers, and platform integration specialists across United States, German, and Indian deployments. Secondary sources encompassed SEC filings for publicly traded vendors, hyperscaler capex disclosures revealing infrastructure investment patterns, and compliance documentation from FDA, SEC, and EU AI Act regulatory repositories. Bottom-up user adoption modeling and top-down addressable market sizing were reconciled through iterative triangulation.
Calibration against historical subscription renewal rates and expansion revenue benchmarks shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to vendor-reported user counts and disclosed average contract values, with AI adoption curves and compliance mandate timelines as industry-specific forecast inputs.
Stress conditions across cloud infrastructure cost inflation, regulatory enforcement intensity, and enterprise IT budget contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about vendor consolidation pace and buyer procurement committee evolution. Cross-checking against third-party SaaS benchmarking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Survey and Feedback Management Software Market
Software & Services
Smartphone OS Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Performing Arts Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
RIP Color Management Software Market
Software & Services
Lead Management Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Business Email Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
DevOps Market
Software & Services
Background Removal Software Market