
 Global User Experience (UX) Market | 2026-2036
Global User Experience (UX) Market Size, Share, and Industry Trends Forecast 2026-2036
Global User Experience (UX) Market Foresight
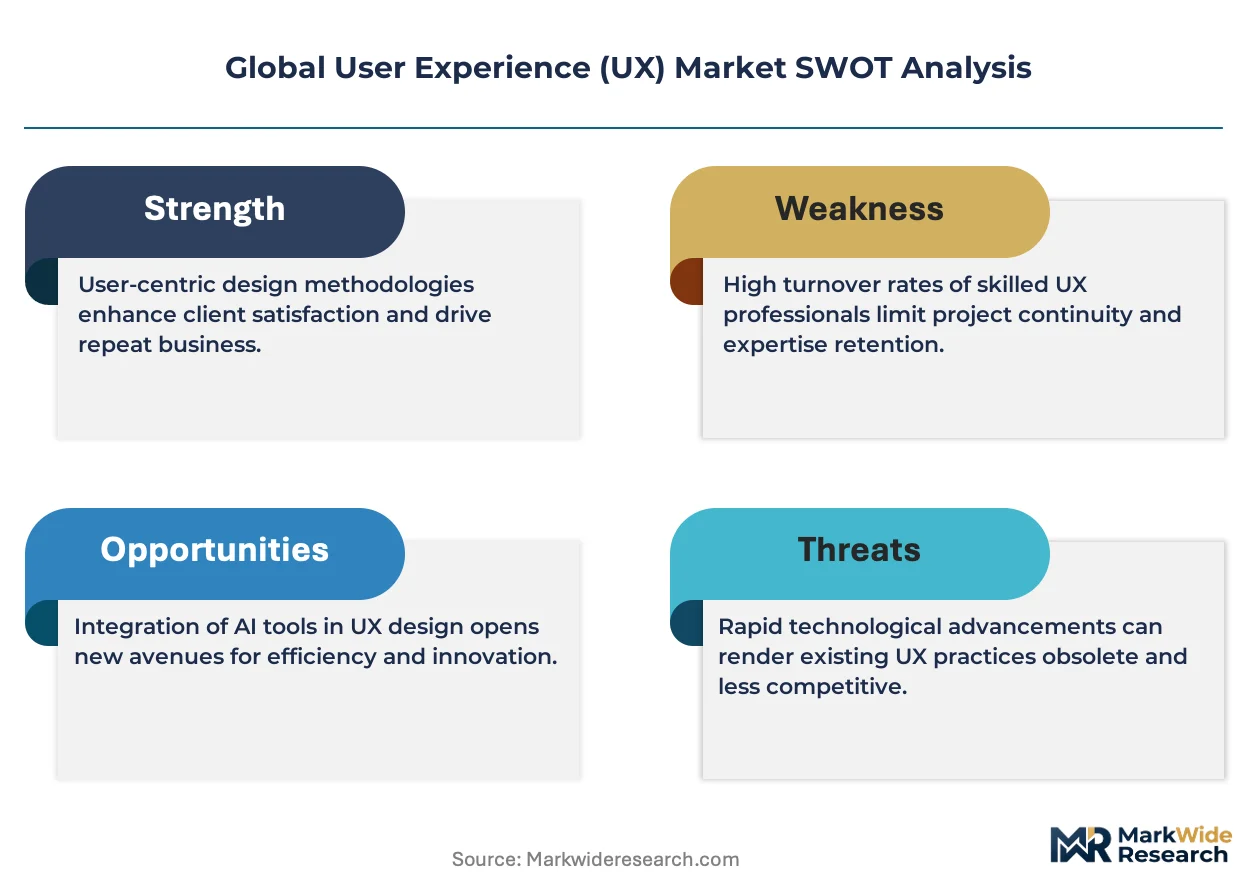
Artificial intelligence is restructuring traditional UX research methodologies, displacing manual usability testing with automated behavioral prediction tools. IDEO leverages its design-thinking heritage to anchor premium consulting engagements for Fortune 500 clients. Frog Design competes through deep specialization in hardware-software interaction for connected devices. Neuron sustains its position by dominating UX analytics for SaaS platforms seeking subscription retention improvements.
User experience encompasses the systematic design and optimization of human-computer interaction through iterative research, wireframing, and interface validation against measurable usability metrics such as task-completion rates and System Usability Scale scores. Its primary commercial purpose is reducing friction in digital product adoption to improve conversion, retention, and customer lifetime value. Interaction design services capture mature margin pools from established enterprise clients, while UX analytics represents the fastest-growing segment as product teams demand real-time behavioral telemetry. Cloud-based deployment leads volume adoption among mid-market buyers, though hybrid configurations are gaining traction in regulated industries requiring data sovereignty.
The EU AI Act, GDPR, and ISO 9241 ergonomics standards collectively shape product requirements by mandating explainable interfaces and accessibility compliance as preconditions for market access. The US FDA and FCC impose parallel constraints on medical device interfaces and connected product labeling, creating fragmented certification burdens for multinational UX vendors. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized design systems or localized compliance variants offer superior risk-adjusted returns.
Market Dynamics
Generative AI adoption is compressing UX research cycles from weeks to hours, forcing consultancies to restructure service delivery models and pricing architectures around automated behavioral prediction rather than manual ethnographic fieldwork.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises deploying algorithmic interfaces in Europe must implement explainable design patterns, creating mandatory procurement of human-centered validation services.
- Healthcare digitization:Hospital systems redesigning patient portals and clinical workflows commission dedicated UX teams to reduce cognitive load on practitioners.
- SaaS retention economics:Subscription vendors in Silicon Valley and Tel Aviv invest heavily in behavioral analytics to reduce churn and expand customer lifetime value.
Market Restraints
- Specialized talent scarcity:The shallow pool of practitioners combining behavioral science credentials with technical prototyping skills inflates project staffing costs.
- Regulatory fragmentation:Divergent accessibility requirements between the US FDA's medical device interface rules and the EU's MDR create redundant certification burdens for multinational deployments.
- AI-generated design commoditization:Automated wireframing tools threaten to collapse pricing for entry-level interface specification work.
Strategic Opportunities
- Indian enterprise SaaS expansion:Bangalore and Hyderabad-based software vendors building for global markets lack mature in-house UX functions, creating service whitespace.
- Industrial IoT convergence:The intersection of augmented reality overlays with legacy manufacturing equipment demands novel hardware-software interaction design.
- CSRD reporting integration:The EU's Corporate Sustainability Reporting Directive requires digital product carbon footprint disclosures, opening advisory services at the design stage.
Industry Challenges
- Cross-functional alignment friction:Product managers, engineers, and designers operate with misaligned success metrics, delaying release timelines.
- Accessibility certification backlog:Third-party WCAG audit providers face capacity constraints, extending compliance timelines for regulated launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global User Experience (UX) Market |
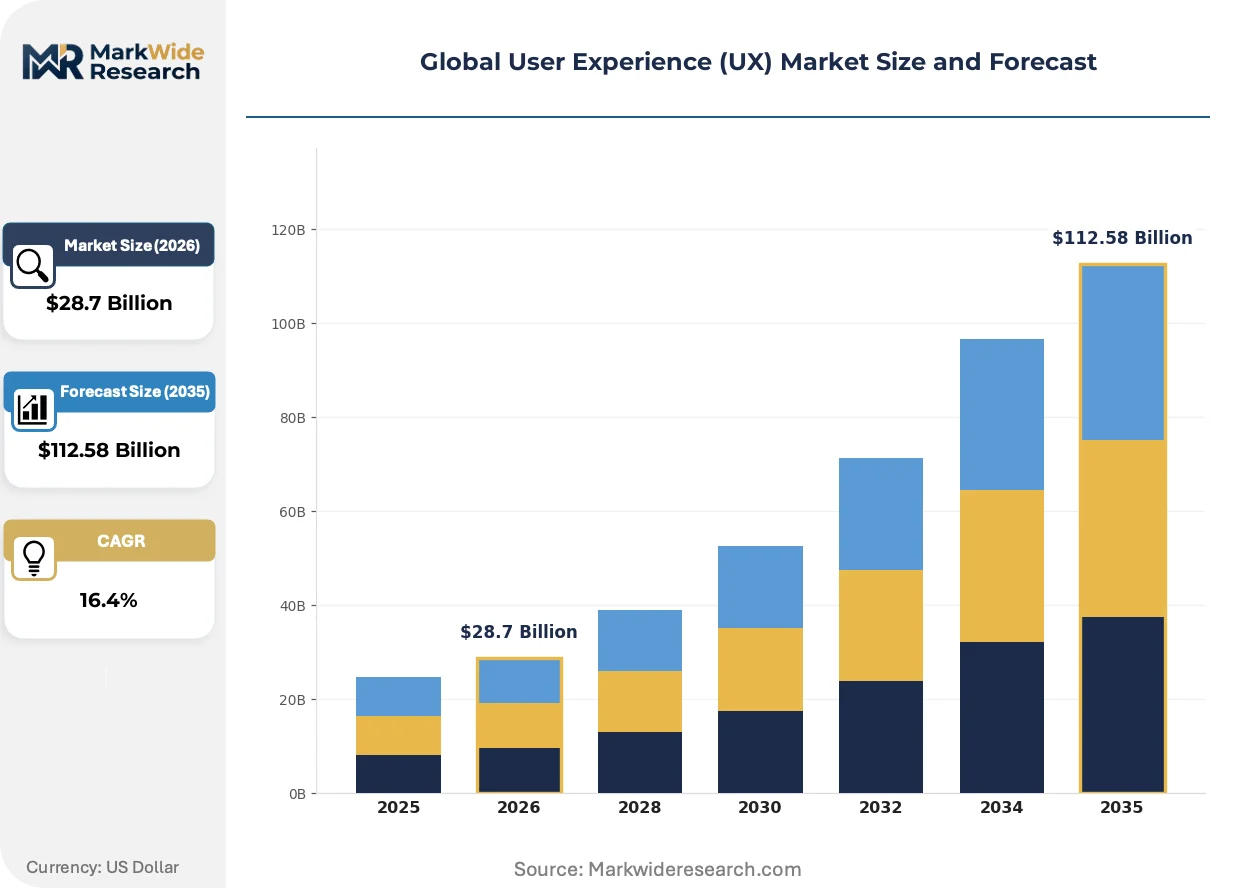
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Prototyping Tools, User Research Platforms, Interaction Design, Information Architecture, Content Strategy, UX Analytics Application: Mobile Apps, E-commerce, SaaS Platforms, Enterprise Software, Smart Devices, Wearables End User Industry: Information Technology, Telecommunications, Banking, Education, Government, Media Deployment: Cloud-based, On-premise, Hybrid, Managed Services |
| Companies Covered | Huge, Neuron, IDEO, MetaLab, UX Studio, Frog Design, Designit, Shakuro, Punchcut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global User Experience (UX) Market Shifts & Advancements
Computational design tools are collapsing traditional boundaries between research, prototyping, and deployment, enabling continuous iteration loops that treat user interfaces as perpetually evolving software rather than fixed deliverables.
AI-powered design systems are modularizing component libraries across enterprise organizations. Financial services and healthcare IT departments in London and Singapore adopt these platforms to enforce brand consistency while accelerating release velocity. The technology is modularizing how design operations scale, compressing the traditional center-of-excellence model into distributed self-service tooling.
The EU AI Act's transparency requirements for high-risk algorithmic systems reshape interface specifications across credit scoring and recruitment platforms. Developers must now embed explainability layers and human override mechanisms directly into user flows. Medical device manufacturers preparing for MDR compliance in Germany and France are advancing investments in interpretable dashboard design.
Enterprise buyers now unbundle research from execution, contracting specialized boutiques for behavioral insight while retaining implementation in-house. This bifurcation disrupts traditional full-service agency relationships. The pattern is most pronounced among Series C software vendors in Israel and the Netherlands seeking granular control over roadmap prioritization.
Global User Experience (UX) Market Segmentation
UX procurement patterns diverge sharply across solution architectures, with regulated industries demanding hybrid deployments while SaaS vendors prioritize cloud-native analytics. Segment boundaries blur as generative AI collapses traditional service categories into integrated platforms.
Solution Type:
Certification burdens fall heaviest on segments touching medical device interfaces or financial services platforms, where FDA and EMA validation requirements extend development timelines.
- Prototyping Tools:Vector-based design environments with real-time collaboration capabilities. Healthcare IT departments in Germany and France commission these tools for MDR-compliant medical dashboard development, constrained by ISO 9241 ergonomics mandates.
- User Research Platforms:Automated behavioral telemetry systems replacing manual ethnographic fieldwork. Tel Aviv-based Series C vendors deploy these to compress research cycles from weeks to hours, though GDPR consent management adds architectural complexity.
- Interaction Design:Hardware-software interface specification for connected products. FDA medical device rules and FCC labeling requirements shape deliverable formats.
- Information Architecture:Navigation system design for complex enterprise applications. Banking platforms in Singapore prioritize these services for regulatory audit trail accessibility.
- Content Strategy:Microcopy and localization frameworks for multi-market deployments. EU AI Act transparency requirements drive demand for explainable interface text.
- UX Analytics:Real-time behavioral telemetry for subscription retention optimization. Silicon Valley SaaS vendors represent the primary demand concentration.
UX Analytics sits at the top of the volume ranking, with User Research Platforms climbing the fastest.
Application:
Cost tiers stratify sharply, with Smart Devices commanding premium fees for hardware-software integration while E-commerce solutions compete on velocity and unit economics.
- Mobile Apps:Native and cross-platform interface design for iOS and Android ecosystems. Indian enterprise SaaS vendors in Bangalore outsource these capabilities to accelerate global market entry.
- E-commerce:Conversion-optimized checkout flows and product discovery systems. Netherlands-based platforms unbundle research from execution to control roadmap prioritization.
- SaaS Platforms:Subscription retention-focused dashboard and onboarding design. Behavioral analytics integration distinguishes premium engagements from commodity wireframing.
- Enterprise Software:Complex workflow optimization for regulated industries. Hybrid deployment preferences dominate due to data sovereignty requirements.
- Smart Devices:Connected product interfaces requiring FCC certification and EU CE marking. Hardware-software interaction specialization commands margin premiums.
- Wearables:Biometric data presentation and gesture-based controls. FDA interface rules constrain design freedom for health-adjacent applications.
SaaS Platforms captures the largest revenue pool, with Smart Devices expanding most quickly on industrial IoT convergence.
End User Industry:
Maturity gradients separate legacy sectors with entrenched procurement processes from technology-native buyers demanding agile engagement models.
- Information Technology:Internal tooling and customer-facing product design for software vendors. Cloud-based deployment dominates procurement patterns.
- Telecommunications:Customer self-service portals and network management dashboards. GDPR compliance shapes European operator requirements.
- Banking:Secure transaction interfaces and regulatory reporting dashboards. Explainable design patterns mandated by EU AI Act for algorithmic credit scoring.
- Education:Learning management systems and accessibility-compliant content platforms. WCAG audit backlogs delay regulated launches.
- Government:Citizen service portals with stringent accessibility and security requirements. Hybrid configurations address data classification tiers.
- Media:Content consumption interfaces and subscription management systems. Real-time personalization engines drive analytics investment.
Information Technology maintains the deepest penetration, with Banking gaining share fastest on regulatory-driven interface redesign mandates.
Deployment:
Supply concentration favors cloud-native architectures, though regulated industries sustain demand for localized infrastructure with certified data residency.
- Cloud-based:Fully managed SaaS delivery with automatic updates and elastic scaling. Mid-market buyers across all geographies default to this model for cost efficiency.
- On-premise:Self-hosted infrastructure for classified or legacy-integrated environments. Government and defense sectors in multiple countries retain this preference.
- Hybrid:Split architectures separating sensitive data processing from public-facing interfaces. German and French healthcare systems adopt this pattern for MDR compliance.
- Managed Services:Outsourced design operations with embedded vendor teams. Enterprise clients in London and Singapore deploy these for continuous iteration support.
Cloud-based deployment leads absolute volume, with Hybrid configurations gaining traction fastest on regulatory fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors global UX service procurement, with enterprise SaaS vendors and technology clusters driving premium consulting engagements across multiple jurisdictions.
United States
FDA medical device interface rules and FCC labeling requirements shape deliverable specifications for connected product designers. HIPAA compliance mandates influence patient portal redesigns across hospital systems. The San Francisco Bay Area concentrates demand from Series C software vendors investing heavily in behavioral analytics for subscription retention.
Germany
Industrial IoT convergence and legacy manufacturing equipment modernization create demand for hardware-software interaction specialists. The EU AI Act and MDR impose explainable design patterns and interpretable dashboard requirements. Munich and Berlin clusters host medical device manufacturers advancing investments in compliance-ready interface specifications.
India
Bangalore and Hyderabad-based enterprise SaaS vendors building for global markets lack mature in-house UX functions, creating service whitespace for external providers. BIS standards and emerging data localization frameworks influence deployment architecture decisions. The Karnataka technology corridor represents the fastest-growing demand concentration for mobile app interface design outsourcing.
United Kingdom
Financial services platforms in London prioritize information architecture services for regulatory audit trail accessibility. GDPR consent management adds architectural complexity to user research platform deployments. The capital's fintech cluster drives demand for explainable interface text compliant with emerging algorithmic transparency mandates.
Israel
Tel Aviv-based Series C vendors deploy automated behavioral telemetry systems to compress research cycles from weeks to hours. The country's national cybersecurity regulator influences secure transaction interface specifications. The coastal technology corridor concentrates venture-backed SaaS platforms unbundling research from execution to control roadmap prioritization.
Global User Experience (UX) Market Competitive Landscape
Portfolio diversification dominates the current landscape as consultancies restructure service delivery models around generative AI capabilities. The vendor base organizes into three tiers: premium design-thinking heritage firms, specialized analytics boutiques, and mid-market execution shops. Strategic archetypes include algorithmic prediction specialists, hardware-software integration experts, and SaaS retention-focused analytics providers. Competitive moves concentrate on M&A for capability gaps and technology licensing for automated design tooling.
Within the heritage-consulting tier, IDEO occupies a position exemplifying premium Fortune 500 engagement models rooted in ethnographic methodology. Frog Design represents hardware-software interaction specialization for connected devices, sitting within the industrial design archetype. Neuron anchors the analytics-driven segment, occupying a position among SaaS-focused behavioral telemetry providers targeting subscription retention improvements.
| Leading Market Players |
|---|
| Huge |
| Neuron |
| IDEO |
| MetaLab |
| UX Studio |
| Frog Design |
| Designit |
| Shakuro |
| Punchcut |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates for explainable interface design are forcing consultancies to absorb specialized behavioral science talent at premium rates, compressing margins on standard engagements while creating pricing power for certified compliance specialists. This procurement pressure reshapes how vendors structure service delivery and which cost components they pass through to buyers.
Pricing Analysis
Input-cost pass-through from specialized practitioner wages dominates pricing architecture in the UX services market. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 design-thinking engagements from mid-market SaaS analytics subscriptions and commodity wireframing tools. Price differentiation rests on certification level—FDA and EU MDR compliance tiers command 40-60% premiums over uncertified specifications—and customization depth. Cost compression in entry-level wireframing is intensifying because generative AI tools automate basic interface specification. SaaS platform buyers exhibit highest price sensitivity due to standardized procurement processes, while medical device manufacturers show lowest sensitivity given regulatory non-negotiability.
Supply Chain Analysis
Talent supply rests on university programs in the United States, specialized design institutes in Germany, and emerging technology corridors in India and Israel. The input base draws from behavioral science PhD pipelines, technical prototyping bootcamps, and cross-functional product management academies. Single-source vulnerability concentrates in elite design-thinking heritage firms where decades of methodology development cannot be rapidly replicated. Distribution runs through direct enterprise sales teams for premium engagements, self-service SaaS platforms for mid-market analytics, and freelance marketplaces for commodity execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market derives from automation-driven cost-down in research execution and premium-tier pricing power in regulated compliance segments. Vendors capturing both efficiencies simultaneously will outpace competitors locked in labor-intensive delivery models.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary AI-powered design tooling and embedded certification audit capabilities. Generative AI commoditization of basic wireframing threatens traditional service margins, requiring incumbents to deepen vertical integration into automated behavioral prediction platforms. Channel control through long-term enterprise SaaS contracts represents the critical lever for retention economics. For New Entrants and Emerging Players: The gap between premium heritage-consulting rates and economy-tier automated tooling prices creates whitespace for mid-market specialists. Indian enterprise SaaS vendors in Bangalore and Hyderabad lack mature in-house UX functions and represent the most penetrable buyer segment. A vertical-specific go-to-market angle—targeting MDR-compliant medical dashboard design or EU AI Act explainability layers—enables differentiation against generalist competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with analytics-driven boutiques possessing real-time behavioral telemetry IP and established Silicon Valley SaaS customer relationships. Long-term viability favors vendors with recurring revenue architectures over project-dependent consultancies. The signal to watch is consolidation velocity among Series C software vendors unbundling research from execution, indicating platformization tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding UX analytics directly into Salesforce and ServiceNow ecosystems captures enterprise procurement workflows. |
| Acquisition of Specialist Firm | Buying FDA-compliant medical interface boutiques accelerates regulated market entry for generalist consultancies. |
| Geographic Expansion | Establishing delivery centers in Bangalore and Tel Aviv accesses cost-efficient behavioral science talent pools. |
| Product Launch | Introducing AI-powered design systems modularizes component libraries for financial services IT departments in London. |
| Strategic Partnership | Aligning with cloud hyperscalers positions vendors for mid-market SaaS platform procurement decisions. |
Research Methodology
Bottom-up SaaS platform and enterprise software modeling reconciled against top-down UX consultancy revenue tracking forms the analytical core of this study. Primary interviews with CTOs at Series C software vendors, design operations leads at Fortune 500 enterprises, procurement officers at hospital systems, and regulatory affairs specialists at medical device manufacturers combined with secondary validation from SEC filings, EU AI Act implementation guidance, FDA 510(k) clearance databases, and behavioral analytics platform usage disclosures. Cross-referencing bottom-up segment builds against top-down industry aggregates ensures methodological consistency.
Historical trendline analysis across solution type, application, end-user industry, and deployment model dimensions established baseline growth patterns over the projection horizon. CAGRs derived from regression analysis against technology adoption curves, regulatory implementation timelines, and SaaS retention economics. Segmentation modeling incorporated deployment architecture preferences, certification requirement intensity, and geographic procurement concentration as forecast inputs.
Caveats apply where EU AI Act enforcement intensity, generative AI capability advances, or talent pipeline disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization trajectories and automation adoption rates. A small set of named triggers—including FDA medical device interface rule revisions, BIS data localization enforcement in India, and hyperscaler UX analytics platform launches—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Digital Signage Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
US Transcription Market