
 OTT Content Market | 2026-2036
OTT Content Market Size, Share, and Industry Trends Forecast 2026-2036
OTT Content Market Outlook
The gap between premium subscription tiers and ad-supported entry plans is repositioning how platforms allocate content budgets and technology spend. Netflix sustains its lead through original programming scale across multiple continents. Amazon Prime Video leverages its e-commerce ecosystem to bundle streaming with logistics memberships. Disney+ anchors family-oriented content libraries against adult-skewing competitors.
Over-the-top content refers to audio and video programming delivered directly to viewers via internet protocol, bypassing traditional terrestrial, satellite, or cable television distribution infrastructure, typically encoded through adaptive bitrate streaming protocols such as HLS or DASH to maintain quality across variable bandwidth conditions. The primary commercial purpose centers on direct monetization of viewer attention through subscription fees, advertising impressions, or transactional purchases without intermediary carriage agreements. Subscription-based distribution channels command the deepest revenue pools as consumers commit to recurring payments, while ad-supported tiers are capturing the fastest user growth by lowering entry barriers for price-sensitive demographics. Smart TV device categories dominate viewing hours due to superior screen real estate and integrated app ecosystems, though mobile devices drive the highest session frequency among younger user segments.
The FCC governs broadband infrastructure standards that determine streaming quality thresholds in the United States, while the EU's Digital Services Act imposes transparency requirements on recommendation algorithms and content moderation practices across European markets. India's TRAI periodically reviews net neutrality frameworks that directly affect how OTT traffic is prioritized by internet service providers. Stakeholders must monitor how fragmented regulatory approaches to content licensing, data privacy, and platform accountability reshape operational complexity across jurisdictions.
Market Dynamics
Adaptive bitrate streaming protocols are compressing infrastructure costs while fragmenting audience attention across device categories, forcing platforms to optimize encoding pipelines for bandwidth-constrained mobile networks and premium smart TV experiences simultaneously.
Growth Catalysts
- India's BIS certification tightening:Hardware standardization mandates for streaming devices are elevating quality benchmarks and accelerating replacement cycles among domestic manufacturers.
- Gen Z mobile-first consumption:Younger demographics drive session frequency through smartphone-native interfaces, expanding addressable inventory for micro-targeted advertising formats.
- Brazilian urban production scaling:Local original content creation in São Paulo and Rio de Janeiro reduces licensing dependency on foreign catalogs and captures Portuguese-language audiences across Latin America.
Market Restraints
- Content cost inflation:Exclusive programming rights and talent compensation are compressing platform margins even as subscriber acquisition costs escalate.
- Net neutrality uncertainty:India's TRAI periodic reviews create traffic prioritization ambiguity that affects streaming quality guarantees during peak consumption windows.
- CDN infrastructure concentration:Reliance on a limited set of global content delivery networks creates single-point-of-failure exposure for latency-sensitive live programming.
Strategic Opportunities
- EU Digital Services Act transparency:Recommendation algorithm disclosure requirements favor platforms with explainable AI investments, creating differentiation against opaque competitors.
- Ad-supported tier expansion:Lower entry pricing captures price-sensitive households previously excluded from subscription ecosystems, particularly in emerging markets.
- Smart TV operating system convergence:Integrated app ecosystems on Samsung Tizen and LG webOS reduce friction for direct platform relationships versus hardware-agnostic casting.
Industry Challenges
- Cross-border content licensing complexity:Territorial rights fragmentation requires territory-specific catalog curation that complicates global content strategy execution.
- Live event streaming reliability:Simultaneous viewership spikes during sports or entertainment broadcasts strain encoding and distribution capacity with limited elasticity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTT Content Market |
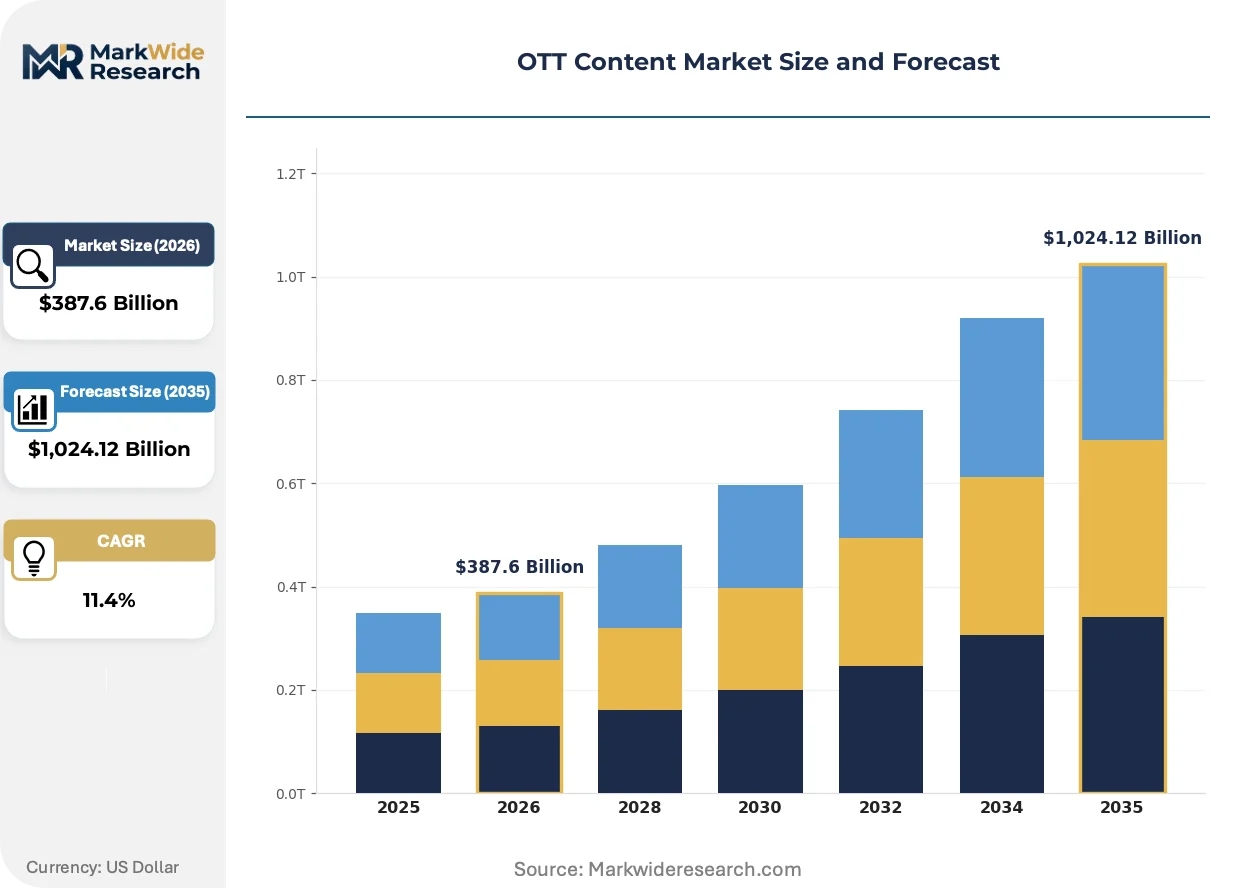
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Documentaries, Sports Distribution Channel: Subscription-Based, Ad-Supported, Transactional, Bundled Services Device Type: Smart TVs, Mobile Devices, Streaming Devices, Laptops User Demographic: Millennials, Gen Z, Families, Seniors |
| Companies Covered | Hulu, Max, Netflix, Brightcove, Peacock, Amazon Prime Video, Apple TV, Vimeo OTT, Disney+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTT Content Market Strategic Shifts
Codec efficiency improvements and edge computing deployment are redistributing processing loads between cloud infrastructure and consumer devices, reshaping capital allocation across the streaming value chain.
AV1 encoding is unifying royalty-free video compression across browser, mobile, and television endpoints. Major platforms have accelerated adoption timelines to reduce H.264 and HEVC licensing burdens. This technology shift is unifying previously fragmented codec strategies into single-format pipelines that simplify transcoding operations and reduce storage redundancy.
The EU's Digital Services Act imposes algorithmic transparency obligations on recommendation systems that shape viewer consumption patterns. Platforms must document content moderation decision criteria and provide user-facing explanation interfaces. European markets are experiencing the most immediate compliance pressure, with operational teams reconfiguring machine learning inference pipelines to satisfy audit documentation requirements.
Subscription fatigue among households is fragmenting platform loyalty and compressing average tenure durations. Consumers are rotating between services monthly rather than maintaining continuous multi-platform relationships. This behavioral shift is most pronounced in North American and Western European markets where catalog overlap and price sensitivity have intensified competitive switching.
OTT Content Market Segmentation
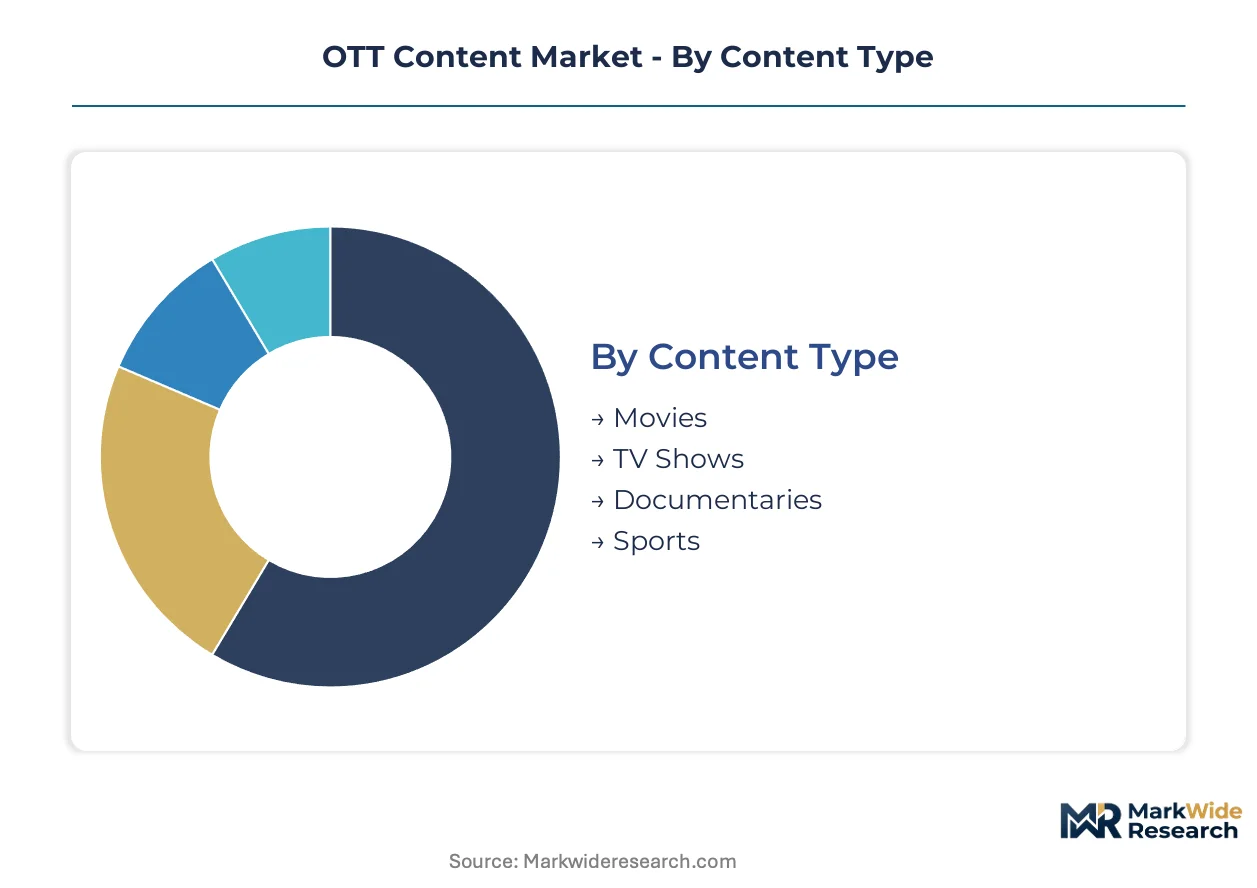
Content type and distribution channel configurations dictate platform monetization architecture, while device fragmentation and demographic targeting determine encoding pipeline investments and recommendation algorithm design. Segmentation clarity separates volume-driven ad-supported models from retention-focused subscription ecosystems.
Content Type:
Customization intensity spans from standardized episodic formats to bespoke live event productions with variable production timelines and talent cost structures.
- Movies:Feature-length productions demand theatrical window management and exclusive licensing negotiations. Demand clusters in premium subscription tiers across North American and European households seeking theatrical releases without cinema attendance.
- TV Shows:Serialized episodic content generates sustained engagement through cliffhanger structures and season-based release cadences. Binge-release models concentrate viewing in Brazilian and Indian urban centers where mobile consumption dominates session frequency.
- Documentaries:Non-fiction programming attracts niche audiences with higher educational attainment and disposable income thresholds. Production costs scale with archival licensing requirements and on-location filming logistics.
- Sports:Live event programming requires synchronous delivery infrastructure with sub-second latency guarantees. Rights acquisition costs escalate with league exclusivity and territory-specific blackout restrictions.
Most installed capacity flows through TV Shows. Expansion is steepest in Sports.
Distribution Channel:
Revenue predictability varies across payment timing, with upfront commitments enabling content budget certainty versus impression-based models requiring inventory liquidity management.
- Subscription-Based:Recurring revenue models fund multi-year original content slates and exclusive licensing agreements. Retention metrics drive personalization investments and churn reduction algorithms across mature markets.
- Ad-Supported:Lower entry pricing expands addressable households through impression monetization and programmatic insertion. Inventory scaling concentrates in mobile-first demographics where session frequency outstrips duration metrics.
- Transactional:Pay-per-view structures capture event-specific demand without ongoing platform commitment. Revenue concentration aligns with blockbuster movie releases and premium sports broadcasts.
- Bundled Services:Cross-sector packaging reduces customer acquisition costs through telecommunications or retail ecosystem integration. India's broadband providers leverage streaming inclusion to differentiate connectivity offerings.
Subscription-Based channels command the deepest revenue pools. Ad-Supported models are climbing the fastest among price-sensitive demographics.
Device Type:
Screen real estate and processing capabilities create divergent encoding requirements, from bandwidth-constrained mobile optimization to premium 4K HDR smart TV experiences.
- Smart TVs:Integrated app ecosystems and superior display specifications dominate living room consumption hours. India's BIS certification mandates for streaming hardware elevate quality benchmarks among domestic manufacturers.
- Mobile Devices:Smartphone-native interfaces drive session frequency through portrait-optimized interfaces and offline download functionality. Gen Z demographics in Brazil and India exhibit the highest per-capita mobile viewing minutes.
- Streaming Devices:Dedicated hardware bridges non-smart televisions to OTT ecosystems through HDMI connectivity. Replacement cycles accelerate with codec standardization and voice control integration.
- Laptops:Browser-based consumption persists among professional demographics and secondary screen multitasking scenarios. Adaptive bitrate protocols prioritize stability over peak resolution on variable bandwidth connections.
Smart TVs anchor the majority of viewing hours. Mobile Devices are gaining share fastest among younger user segments.
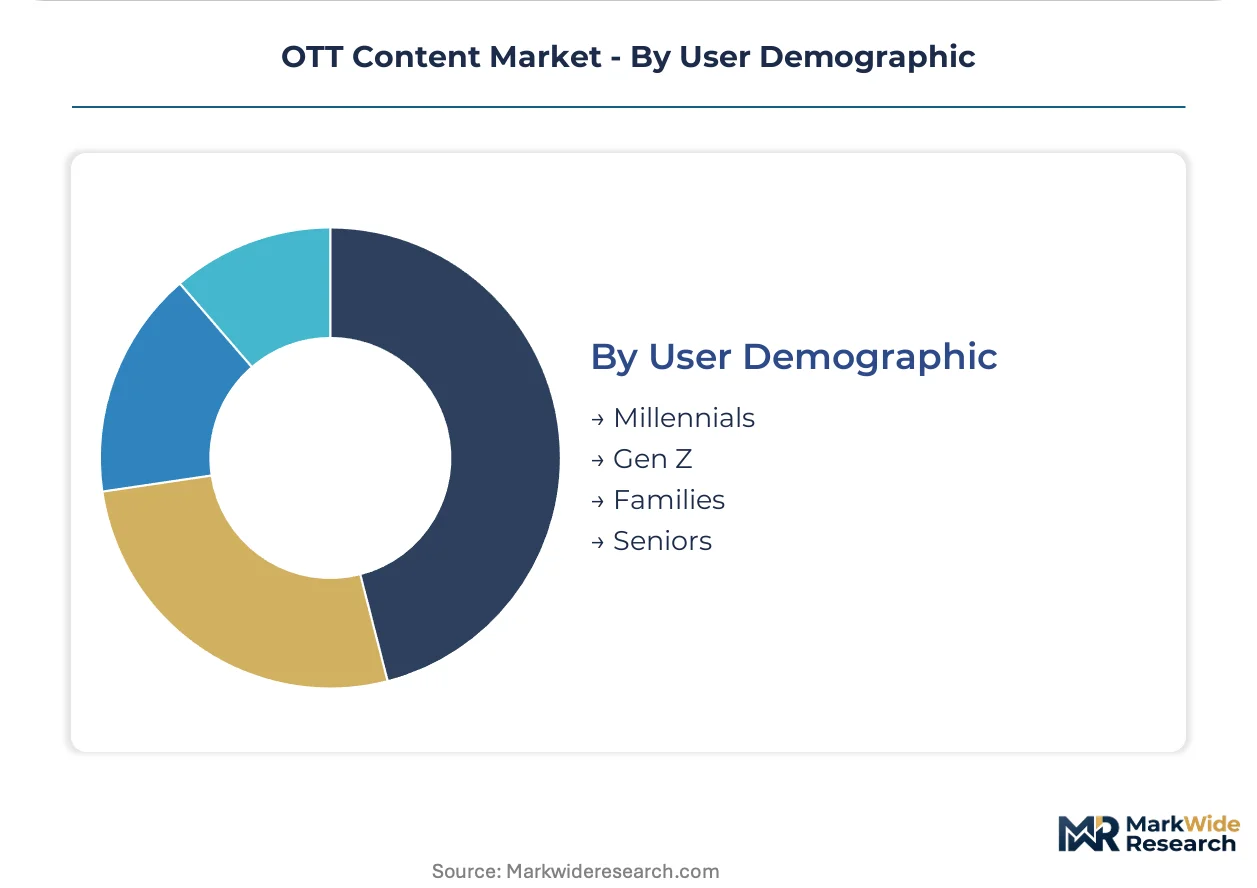
User Demographic:
Content preference divergence and payment willingness create distinct platform positioning strategies across age cohorts and household structures.
- Millennials:Cord-cutting pioneers maintain multi-platform subscriptions with high genre diversity tolerance. Preference for prestige drama and international content drives catalog breadth requirements.
- Gen Z:Native digital consumers exhibit platform rotation behavior and short-form content affinity. Mobile-first engagement patterns prioritize social sharing features and interactive viewing experiences.
- Families:Multi-generational households demand robust parental controls and age-appropriate content libraries. Disney+ and similar platforms anchor subscriptions through children's programming and co-viewing safety features.
- Seniors:Late-adopting demographics require simplified interfaces and larger text accessibility options. Documentary and classic film catalogs retain engagement through familiar intellectual property.
Families represent the stickiest subscriber base. Gen Z is expanding most quickly as mobile infrastructure penetrates emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineers and content production specialists concentrate in coastal technology corridors, driving platform engineering and original programming investment across key markets.
United States
Subscription fatigue and platform rotation behavior compress average tenure durations among multi-service households. The FCC governs broadband infrastructure standards that determine streaming quality thresholds. Los Angeles anchors original content production with major studio backlots serving global distribution pipelines.
India
Mobile-first consumption patterns among Gen Z demographics expand addressable inventory for micro-targeted advertising formats. TRAI periodically reviews net neutrality frameworks that affect traffic prioritization by internet service providers. Mumbai and Bengaluru cluster streaming platform engineering centers and domestic original production facilities.
Brazil
Urban production scaling in São Paulo and Rio de Janeiro reduces licensing dependency on foreign catalogs. ANVISA regulates advertising standards for health and pharmaceutical content across streaming platforms. São Paulo's Pinheiros district concentrates Portuguese-language original production serving Latin American expansion.
Germany
Household demand for documentary and prestige drama content drives catalog breadth requirements among educated demographics. The EU's Digital Services Act imposes transparency requirements on recommendation algorithms and content moderation practices. Berlin's Kreuzberg district hosts multiple platform localization and dubbing studios.
United Kingdom
Cord-cutting pioneers maintain multi-platform subscriptions with high genre diversity tolerance and international content affinity. GDPR compliance requirements shape data handling practices for viewer analytics and personalization engines. London's Soho district concentrates post-production facilities serving European market localization.
OTT Content Market Competitive Environment
Top-tier vendors anchor subscription-based ecosystems with multi-billion-dollar content budgets, while mid-tier platforms compete through niche positioning and regional specialization. The market structure consolidates around three to five global platforms with sufficient scale for original programming investment, while dozens of regional and genre-specific services fragment remaining viewership. Strategic archetypes include ecosystem-integrated retailers, pure-play streaming specialists, and legacy media conglomerates transitioning direct-to-consumer. Dominant competitive moves encompass exclusive sports rights acquisition and ad-supported tier launches to capture price-sensitive segments.
Among pure-play streaming specialists, Netflix and Disney+ exemplify the original programming scale archetype, while Amazon Prime Video represents ecosystem-integrated retail bundling. Brightcove and Vimeo OTT occupy positions within the technology infrastructure and white-label platform tier, serving content owners seeking direct distribution without proprietary app development. Hulu and Peacock exemplify legacy media conglomerate transitions, leveraging existing intellectual property libraries and broadcast relationships. These named entities anchor their respective competitive tiers without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Hulu |
| Max |
| Netflix |
| Brightcove |
| Peacock |
| Amazon Prime Video |
| Apple TV |
| Vimeo OTT |
| Disney+ |
| Others |
Value Chain & Pricing Dynamics
Content licensing costs cascade through subscription tiers from premium originals to ad-supported entry plans, compressing margins at the bottom while exclusive programming investments sustain pricing power at the top. India's TRAI net neutrality reviews and Brazil's ANVISA advertising standards create jurisdiction-specific cost layers that platforms must absorb or pass through geographically segmented pricing.
Pricing Analysis
The bundled-vs-unbundled service split separates ecosystem-integrated offerings from standalone subscriptions. Three-tier pricing structure across premium, standard, and economy levels captures household willingness-to-pay through feature differentiation and ad tolerance. Price differentiation rests on original content exclusivity and offline download privileges as primary drivers. Cost compression in ad-supported tiers is intensifying because programmatic inventory CPMs lag subscription ARPU conversion. Price-sensitive households in emerging markets exhibit highest elasticity, while multi-generational family plans show lowest churn sensitivity.
Supply Chain Analysis
Direct-to-consumer app ecosystems handle hyperscale viewer demand through integrated smart TV operating systems and mobile-native platforms. Geographic supply concentrates in the United States for original content production, India for engineering talent and localization, and Brazil for Portuguese-language original programming. Raw material dependencies include cloud compute capacity from hyperscalers, CDN edge nodes for low-latency delivery, and licensed music catalogs for soundtrack integration. Single-source vulnerability in global CDN infrastructure creates outage exposure during live event spikes. Distribution runs through proprietary applications on Samsung Tizen, LG webOS, and mobile app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in OTT content flows from ad-supported tier scale economies and AV1 codec adoption reducing storage and bandwidth costs. Premium subscription stickiness among family households sustains pricing power against rotation behavior.
For Market Incumbents: Hedge against subscription fatigue by diversifying revenue mix toward advertising and transactional models. Original content exclusivity remains the priority defensive lever against catalog commoditization. Capacity addition in São Paulo and Mumbai production clusters reduces licensing dependency on Hollywood output. Certification investment in India's BIS streaming hardware standards secures device ecosystem placement.
For New Entrants and Emerging Players: Niche documentary audiences represent underserved buyer archetype with high educational attainment and low price sensitivity. White-space targets include Portuguese-language nonfiction programming for Brazilian diaspora and interactive short-form content for Gen Z mobile sessions. Go-to-market angle should emphasize social sharing features and co-viewing experiences absent from incumbent platforms.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional platforms lack original programming scale to sustain subscriber acquisition against global competitors. Long-term viability favors assets with proprietary IP libraries and established localization infrastructure. Acquisition target archetype: mid-tier services with strong genre positioning and underutilized production capacity. Signal to watch: ad-supported tier conversion rates as indicator of pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Ad-Supported Tier Launch | Expands addressable households in price-sensitive Indian and Brazilian urban markets. |
| Original Content Scale-Up | Reduces licensing costs and builds defensible IP against Netflix and Disney+ catalogs. |
| AV1 Codec Migration | Eliminates H.264 and HEVC royalty burdens while unifying transcoding pipelines. |
| Smart TV OS Partnership | Secures native app placement on Samsung Tizen and LG webOS integrated ecosystems. |
| Live Sports Rights Acquisition | Captures synchronous viewing audiences with highest engagement and lowest churn. |
Study Parameters
Multiple input streams — platform engineering executives, content licensing directors, advertising operations leads, and regulatory affairs specialists — were reconciled against secondary validation. Primary interviews with CTOs at streaming services, procurement managers at CDN providers, and localization studio heads in Berlin and Mumbai informed operational cost structures. Secondary sources included TRAI regulatory filings, EU Digital Services Act implementation guidance, SEC 10-K disclosures from listed platforms, and App Annie mobile engagement data. Bottom-up subscriber and revenue modeling was cross-checked against top-down market sizing from broadband penetration and household spending analysis.
Historical growth trajectories were cross-referenced against panel input from industry participants to anchor projection assumptions. Segmentation dimensions modeled include content type, distribution channel, device category, and user demographic across the analysis window. CAGRs were derived from fitted growth curves incorporating smartphone penetration rates, smart TV replacement cycles, and original content production capacity expansion. Industry-specific forecast inputs encompassed India's BIS certification timelines and Brazil's urban production facility buildouts.
Inputs from platform financial disclosures and regulatory filings were available through the study window; gaps in private company subscriber data and regional advertising rate cards introduce uncertainty bands around emerging market projections. Forecasts reflect assumptions about net neutrality stability, codec adoption curves, and content cost inflation that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Media Streaming Market