
 Global Textiles Home Decor Market | 2026-2036
Global Textiles Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textiles Home Decor Market Outlook
Direct-to-consumer upholstery customization is rewriting margin distribution across the value chain. Mohawk Industries leverages captive carpet tufting capacity to anchor North American supply for residential builders. Williams-Sonoma differentiates through curated textile collections that occupy the premium kitchen and dining segment. Trident Group sustains large-scale terry towel and bed linen output for European hospitality procurement.
Global textiles home decor encompasses woven, knitted, and non-woven fabric products engineered for interior enhancement, typically specified by thread count, dye fastness ratings, and dimensional stability under laundering cycles. These products serve functional roles in light control, thermal insulation, surface protection, and aesthetic coordination across residential and commercial interiors. Cotton and linen materials command structural attention as sustainability certifications reshape procurement criteria, while polyester retains cost-driven volume in mass-market channels. The rugs category leads in artisanal premium positioning, whereas online retail distribution is expanding fastest as virtual room-visualization tools reduce return rates.
The US EPA regulates volatile organic compound emissions from textile finishes, pushing manufacturers toward water-based coating systems. REACH compliance in Europe restricts azo dyes and formaldehyde-based resins, directly elevating R&D costs for export-oriented mills in India and China. India's BIS certification mandates fiber content labeling and dimensional stability testing for domestic sale. Stakeholders must monitor how diverging chemical safety standards between the EU and US reshape sourcing geography and supplier qualification timelines.
Market Dynamics
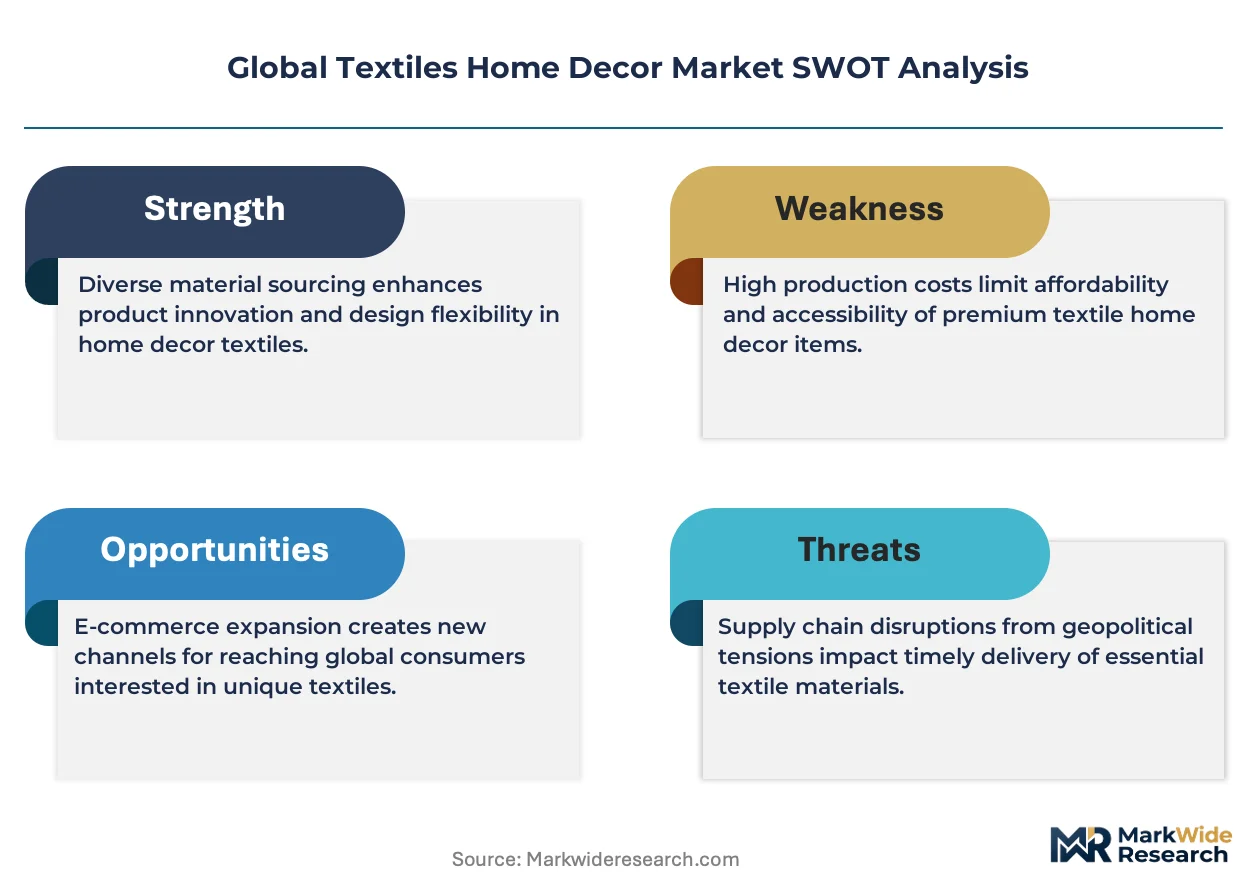
REACH chemical standards and the EU Green Deal are compressing supplier qualification timelines while rerouting procurement toward organic dye houses and recycled fiber mills in South Asia. This regulatory pressure is restructuring the competitive landscape faster than demand growth alone.
Growth Catalysts
- Hospitality refresh cycles:Premium hotel procurement teams are compressing linen replacement schedules from 36 to 24 months, creating sustained pull for high-thread-count bedding and upholstery-grade fabrics certified for commercial laundering.
- REACH compliance premiums:European buyers are paying 12-18% contract premiums for azo-free dyes and formaldehyde-compliant finishes, redirecting volume toward certified Indian and Turkish mills.
- Virtual room visualization:Augmented reality tools embedded in retailer apps are cutting return rates by enabling pre-purchase fabric placement in consumer living spaces, accelerating online channel expansion.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations in Texas and Maharashtra are compressing margins for undifferentiated commodity bedding producers unable to pass through input spikes.
- Panipat weaving concentration:Over 40% of global recycled cotton rug production sits within a 50-kilometer radius in Haryana, creating single-point vulnerability to monsoon logistics and state electricity rationing.
- Polyester substitution ceiling:Sustainability certifications are capping polyester blend share in premium hospitality procurement, limiting cost-down options for mid-tier suppliers.
Strategic Opportunities
- Brazilian market underpenetration:Domestic textile capacity in São Paulo state serves only 30% of hospitality demand, creating import substitution openings for REACH-certified Asian exporters.
- Blockchain fiber tracing:Convergence of RFID tagging and distributed ledger verification is enabling farm-to-shelf cotton provenance claims that command retail price premiums.
- India PLI scheme expansion:Production-linked incentives for man-made fiber technical textiles are subsidizing capital equipment upgrades for domestic producers targeting export markets.
Industry Challenges
- Natural dye chemistry expertise:Formulation knowledge for light-fast organic pigments resides with a shrinking cohort of European specialty chemical houses, creating talent bottlenecks for scaling compliant production.
- Dual certification timelines:Simultaneous OEKO-TEX and GOTS qualification requires 14-18 months of parallel testing, delaying market entry for new recycled fiber entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textiles Home Decor Market |
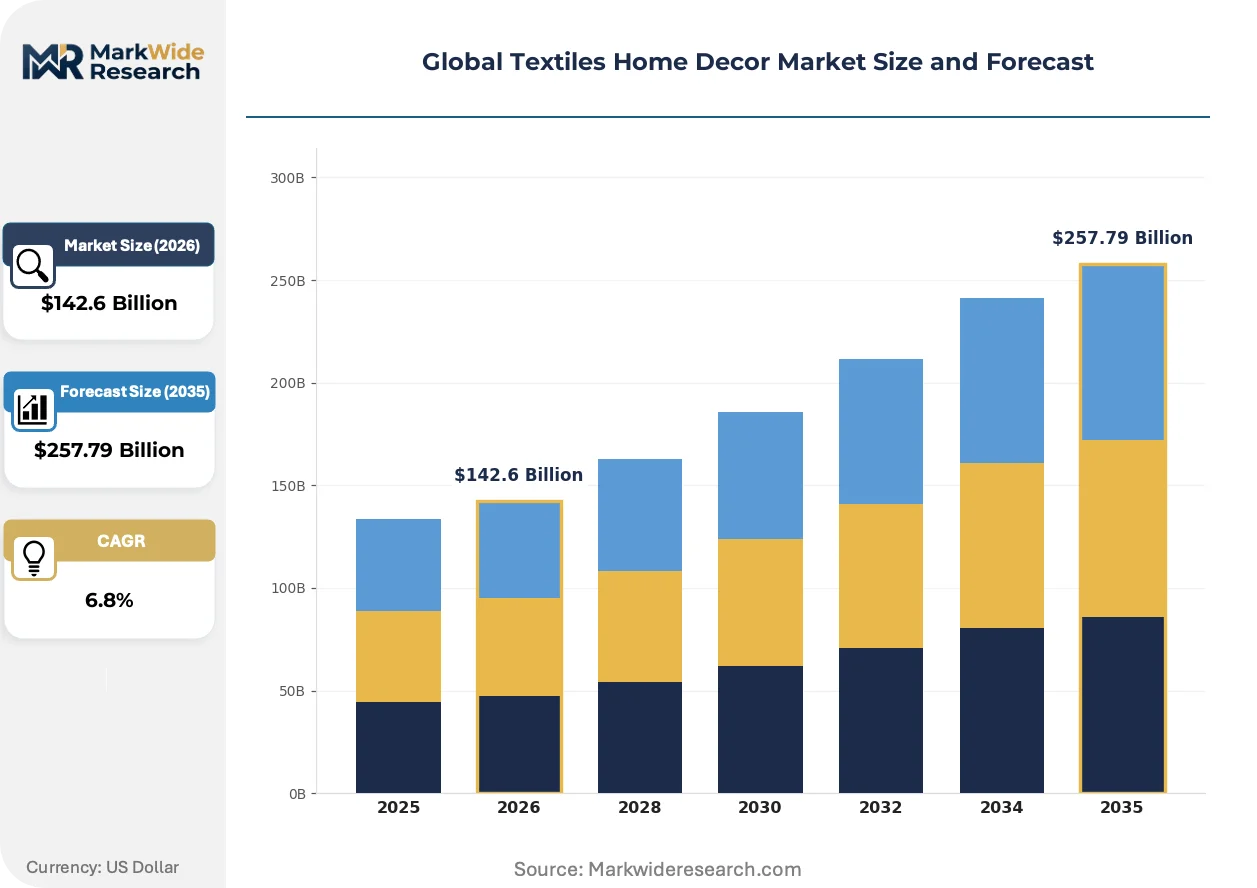
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cushions, Curtains, Rugs, Tablecloths Material: Cotton, Polyester, Linen, Silk End User: Households, Hotels, Restaurants, Offices Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | IKEA, Mohawk Industries, Williams-Sonoma, Ashley Furniture Industries, Welspun India, Trident Group, Springs Global, Shaw Industries Group, Nitori Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textiles Home Decor Market Strategic Shifts
Digital tools are compressing the traditional sampling-to-purchase cycle while regulatory chemistry constraints are forcing material science investments. These shifts are redistributing margin capture toward technology-enabled suppliers.
3D fabric rendering software is virtualizing the tactile evaluation phase of upholstery procurement. Residential interior designers and hospitality specifiers are adopting these tools at accelerating rates, reducing physical sample shipping by 60% for early-stage selection. This compression is virtualizing the role of traditional textile showrooms and reallocating marketing spend toward platform partnerships.
ECHA's 2023 restriction on PFAS in textile finishes is forcing coating reformulation across the EU import supply base. Water-based alternatives require slower drying cycles and capital-intensive curing equipment, elevating minimum efficient scale. Turkish and Portuguese finishing houses are capturing volume from smaller Indian competitors unable to fund compliance upgrades.
Direct-to-consumer customization portals are fragmenting the traditional wholesale-retail hierarchy. Mill-end brands in Karur and Panipat are launching proprietary e-commerce channels, disintermediating European buying offices that historically controlled access to Western markets. This channel shift is most visible in the United Kingdom and Germany, where boutique hospitality procurement teams now source bed linens through manufacturer-direct platforms.
Global Textiles Home Decor Market Segmentation
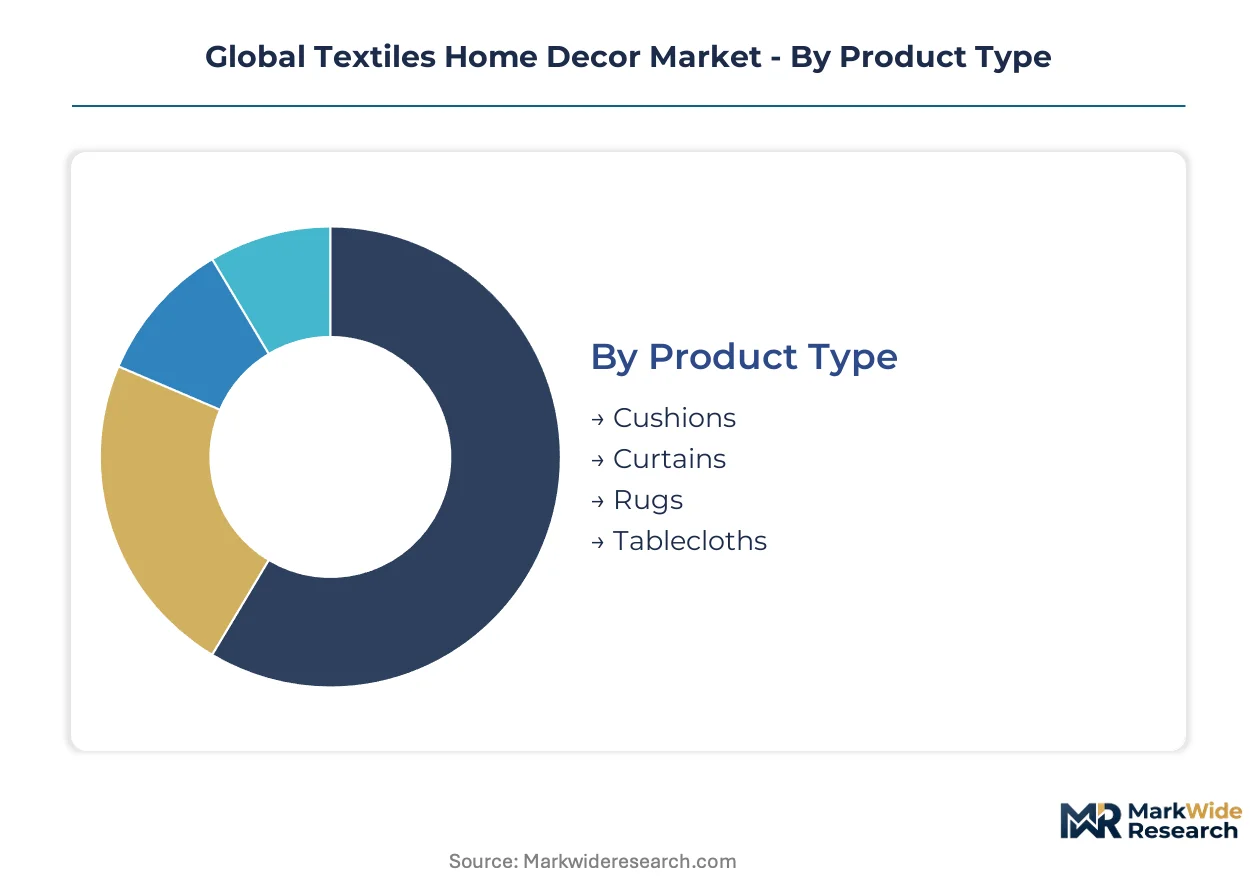
Segmentation in textiles home decor reveals how replacement cycles, certification requirements, and channel economics concentrate margin capture differently across product categories. Understanding these structural divisions exposes where procurement teams and retailers can defend position against input volatility and regulatory compression.
Product Type:
Curtains and cushions turn over fastest in residential channels, while rugs and tablecloths operate on extended replacement timelines driven by durability expectations and seasonal use patterns.
- Cushions:These accent pieces feature removable covers in 200-400 thread count cotton or linen blends, enabling frequent style refreshes without full furniture replacement. Demand clusters in UK and German direct-to-consumer channels where virtual room visualization tools accelerate impulse purchases.
- Curtains:Window treatments span sheer voiles to blackout thermal weaves, specified by light transmission coefficients and fire-retardant ratings for commercial applications. Hospitality procurement in Spain and Italy drives volume for flame-certified synthetics with 24-month replacement cycles.
- Rugs:Floor coverings anchor artisanal positioning through hand-knotted wool and recycled cotton flatweaves from Panipat clusters.
- Tablecloths:Dining textiles emphasize stain-resistant finishes and commercial laundering durability for restaurant end-use.
Rugs dominate installed base value in premium residential and hospitality segments. Cushions represent the fastest volume expansion as e-commerce penetration enables low-commitment experimentation with color and texture.
Material:
Raw material selection determines compliance pathway and margin structure, with natural fibers commanding certification premiums and synthetics retaining cost-driven mass-market volume despite sustainability headwinds.
- Cotton:GOTS-certified long-staple varieties from Maharashtra and Texas anchor high-thread-count bedding and terry towel production for European hospitality procurement teams paying REACH compliance premiums.
- Polyester:Recycled PET fiber blends from Chinese chemical recycling facilities supply mass-market curtain and cushion fills where price elasticity exceeds sustainability preference.
- Linen:Belgian and French flax cultivation supports premium upholstery and table linen with inherent antimicrobial properties prized in healthcare-adjacent hospitality.
- Silk:Mulberry silk from Karnataka weaving clusters occupies ultra-premium decorative pillow and wall hanging niches with limited scalability.
Cotton holds the largest installed base across residential and commercial applications. Linen is climbing the fastest as EU Green Deal procurement mandates elevate natural fiber share in public and hospitality tendering.
End User:
Customer type segmentation separates cyclical replacement demand from project-based specification, with hospitality and foodservice operating on compressed refresh schedules versus residential discretionary purchasing.
- Households:Individual consumers purchase through seasonal refresh cycles and relocation events, with online channel share expanding fastest in UK and US metropolitan markets where virtual visualization reduces return friction.
- Hotels:Premium hospitality procurement teams specify OEKO-TEX and GOTS-certified linens with 24-month replacement protocols, creating predictable volume for Turkish and Indian mill suppliers.
- Restaurants:Foodservice operators prioritize commercial laundering durability and stain-resistant finishes over thread count, sourcing through wholesale distributors with rapid replenishment capabilities.
- Offices:Corporate interior specification lags residential and hospitality in textile refresh frequency, with acoustic panel fabrics and reception area upholstery representing primary demand pockets.
Households represent the broadest installed base across all product categories. Hotels concentrate expansion investment as ESG-linked procurement policies mandate certified fiber sourcing.
Distribution Channel:
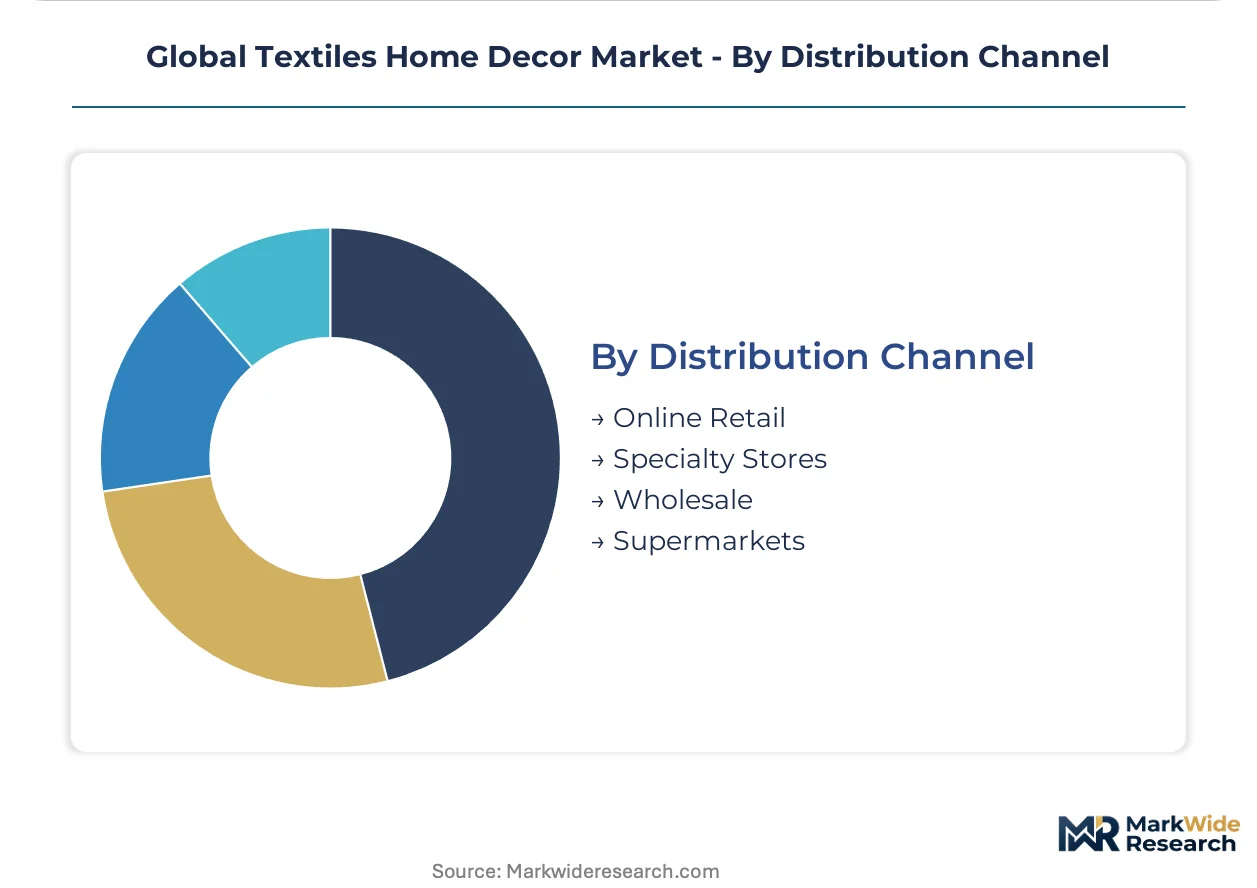
Channel structure determines margin distribution and supplier access, with direct manufacturer platforms disintermediating traditional buying offices while specialty retail retains tactile evaluation for premium upholstery.
- Online Retail:Digital platforms enable mill-direct access for Karur and Panipat producers, with augmented reality tools reducing return rates and compressing the traditional showroom-dependent selection process.
- Specialty Stores:Curated textile showrooms in Milan, Paris, and London maintain relevance for hospitality specifiers requiring physical hand-feel evaluation of upholstery-grade fabrics before volume commitment.
- Wholesale:Traditional buying offices and distributor networks retain volume in restaurant and mid-tier hotel procurement where consolidated billing and logistics coordination outweigh price optimization.
- Supermarkets:Mass-market retail captures commoditized bedding and basic curtain demand through private-label programs with limited certification requirements.
Specialty stores dominate premium upholstery specification. Online retail is gaining share fastest as direct-to-consumer platforms enable Indian weaving clusters to bypass European buying office markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: European hospitality procurement absorbs REACH compliance premiums with minimal volume contraction, while mass-market buyers in emerging economies remain acutely price-sensitive to cotton input spikes.
United States
Residential builders drive volume for carpet and upholstery through captive relationships with tufting specialists. The EPA regulates volatile organic compound emissions from textile finishes, pushing manufacturers toward water-based coating systems. Dalton, Georgia anchors North American carpet production with concentrated tufting capacity serving national distribution networks.
Germany
Hospitality procurement teams in Berlin and Munich specify OEKO-TEX certified linens with compressed 24-month replacement cycles. The EU Green Deal mandates organic fiber share in public tendering, elevating sourcing costs for hotel operators. The Ruhr Valley hosts finishing houses capturing volume from smaller competitors unable to fund PFAS-compliant coating upgrades.
India
Export-oriented weaving clusters in Panipat and Karur supply both mass-market retailers and boutique hospitality brands with recycled cotton rugs and terry towel production. The BIS certification mandates fiber content labeling and dimensional stability testing for domestic sale. Maharashtra's long-staple cotton cultivation supports GOTS-certified bedding output for European buyers paying compliance premiums.
United Kingdom
Direct-to-consumer platforms enable Indian weaving clusters to bypass traditional buying office markups, accelerating manufacturer-direct procurement. REACH chemical standards restrict azo dyes and formaldehyde-based resins, elevating R&D costs for export-oriented suppliers. London maintains curated textile showroom relevance for hospitality specifiers requiring physical hand-feel evaluation.
Brazil
Domestic textile capacity in São Paulo state serves only 30% of hospitality demand, creating import substitution openings for certified Asian exporters. The country's national textile regulator enforces fiber content standards that parallel European certification requirements. São Paulo's industrial corridor concentrates finishing capacity insufficient for coastal hospitality development in Rio de Janeiro and Bahia.
Global Textiles Home Decor Market Competitive Environment
Capability concentration sits with European specialty chemical houses and artisanal finishing operations; scale advantage sits with integrated South Asian mill complexes and North American carpet manufacturers. The vendor base spans three tiers: global diversified home furnishings conglomerates with captive textile operations, mid-scale regional weavers with certification depth, and fragmented artisanal producers serving premium niche channels. Two competitive moves dominate: backward integration into fiber recycling and coating formulation, plus direct-to-consumer platform launches that disintermediate traditional buying offices.
Within the diversified conglomerate tier, Mohawk Industries and Williams-Sonoma exemplify contrasting strategic positions. Mohawk leverages captive North American tufting capacity to anchor builder supply relationships, while Williams-Sonoma occupies curated premium positioning across kitchen and dining textiles. Among South Asian scale producers, Trident Group and Welspun India sit within the export-oriented mill segment sustaining large-volume output for European hospitality procurement. These three named entities represent the archetype spectrum: North American integrated manufacturing, Western premium retail curation, and South Asian certified bulk supply.
| Leading Market Players |
|---|
| IKEA |
| Mohawk Industries |
| Williams-Sonoma |
| Ashley Furniture Industries |
| Welspun India |
| Trident Group |
| Springs Global |
| Shaw Industries Group |
| Nitori Holdings |
| Others |
Value Chain & Pricing Dynamics
Panipat's recycled cotton rug concentration anchors margin capture for European hospitality buyers, while REACH compliance premiums redirect procurement toward certified Turkish and Portuguese finishing houses. Cotton price volatility in Maharashtra and Texas compresses undifferentiated bedding margins, forcing tiered pricing stratification across certification grades.
Pricing Analysis
After-sales service contracts for commercial laundering durability drive lifetime value in hospitality procurement. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic linens from OEKO-TEX baseline and uncertified commodity bedding. Price differentiation rests on REACH compliance premiums and virtual visualization-enabled direct channels. Cost compression in mass-market polyester blends is intensifying because sustainability certifications cap synthetic share in premium tenders. Boutique hospitality buyers show least price sensitivity; supermarket private-label consumers absorb input spikes fastest.
Supply Chain Analysis
Export-control scrutiny on PFAS-containing textile finishes limits coating chemistry flows into EU markets. Manufacturing gravity centers on India, Turkey, and Portugal, with raw material dependencies spanning Maharashtra long-staple cotton, Belgian flax, and Chinese recycled PET feedstock. Single-source vulnerability concentrates in Panipat's 50-kilometer weaving radius. Distribution runs through mill-direct platforms disintermediating European buying offices, alongside specialty showroom networks for upholstery specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among premium hotel chains concentrates buyer power, fragmenting supplier access and compressing qualification timelines for uncertified mills.
For Market Incumbents: Entrench certification depth through parallel OEKO-TEX and GOTS qualification investment, locking out smaller competitors facing 14-18 month testing timelines. Deepen upstream control over organic dye formulation partnerships with European specialty chemical houses, countering talent scarcity in light-fast natural pigment chemistry. Anchor volume through captive relationships with hospitality procurement teams executing compressed 24-month refresh cycles. For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated hospitality textile market, where São Paulo capacity serves only 30% of coastal demand. Target REACH-certified export positioning to capture import substitution openings from Asian mills. Launch mill-direct e-commerce platforms mirroring Karur and Panipat disintermediation plays, leveraging virtual room visualization tools to reduce return friction in UK and German consumer channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European finishing houses holding PFAS-compliant coating capacity and stranded Indian competitors facing compliance upgrade costs. Five-to-ten year viability favors backward integration into fiber recycling and blockchain provenance verification. Watch for ECHA chemical restriction announcements as inflection signals forcing accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Stack Investment | Parallel OEKO-TEX and GOTS qualification accelerates European hospitality procurement access. |
| Direct-to-Consumer Platform Launch | Mill-end brands bypass European buying office markups through proprietary e-commerce channels. |
| Backward Integration into Recycling | Captive recycled cotton supply secures Panipat cluster volume against monsoon logistics disruption. |
| Natural Dye Formulation Partnership | European specialty chemical house alliances lock in scarce light-fast organic pigment expertise. |
| Blockchain Provenance Deployment | RFID-distributed ledger integration enables farm-to-shelf cotton claims commanding retail premiums. |
Study Parameters
The analysis maps woven textiles, knitted upholstery, and non-woven decorative fabrics, each validated through procurement directors at premium hotel chains, sustainability compliance officers at European buying offices, and plant managers at Panipat and Karur weaving clusters. Primary interviews with hospitality specifiers, textile chemical formulators, and e-commerce platform operators combined with secondary validation from REACH restriction databases, BIS certification registries, and EU Green Deal procurement guidelines. Customs records for cotton fiber imports and hospitality sector capex disclosures anchored bottom-up and top-down triangulation.
Assumptions held fixed include regulatory enforcement timelines for PFAS restrictions and PLI scheme continuation for Indian technical textiles, while cotton price volatility and virtual visualization adoption rates varied across sensitivity runs. Segmentation dimensions spanned product type, material certification tier, end-user replacement cycle, and channel structure. CAGRs derived from installed base turnover analysis and procurement cycle compression trends, with hospitality refresh frequency and organic fiber mandate penetration as key inputs.
Sensitivities concentrate around ECHA chemical restriction announcements, monsoon disruption severity in Haryana, and virtual visualization tool adoption curves. Forecasts reflect documented assumptions on certification timeline stability and buyer consolidation trajectories. Material shifts in EU Green Deal procurement mandates or PFAS regulatory scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Bed Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Duvets Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
India Bed and Bath Linen Market