
 Bed Linen Market | 2026-2036
Bed Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Linen Market Analysis
Hospitality buyers are redrawing procurement priorities as premium residential consumers retreat from pandemic-era spending. Boll & Branch leverages direct-to-consumer organic cotton positioning to command price premiums in the bedroom textile space. WestPoint Home anchors institutional supply relationships through large-scale manufacturing capacity serving hotel and healthcare channels. Brooklinen competes on digital-native brand velocity, converting mattress and sleep-system purchasers into repeat linen buyers.
Bed linen encompasses woven and knitted textile products designed for mattress coverage, pillow encasement, and layered bedding insulation, typically specified by thread count, fiber staple length, and finishing treatments such as mercerization or sanforization to ensure dimensional stability and skin contact safety. Cotton sheets occupy the dominant material position by volume, though bamboo-derived viscose fibers are gaining fastest in moisture-wicking and thermal-regulation applications. King-size configurations command disproportionate margin contribution in North American retail, while twin and full sizes sustain higher turnover velocity in institutional and student housing procurement channels.
The US EPA and FTC enforce textile labeling and environmental marketing claims, compelling domestic sellers to substantiate organic and recycled-content assertions. The EU Green Deal and REACH chemical restrictions are reshaping dyehouse operations and finish chemistry across European supply bases. Stakeholders must monitor fiber traceability mandates and chemical disclosure thresholds as these frameworks tighten, determining which production geographies and material certifications will sustain market access.
Market Dynamics
The EU Green Deal's organic cotton certification mandates are forcing European suppliers to reconfigure sourcing networks while Indian mills capture finished-goods volume from both domestic retail and export channels. Hospitality procurement teams are compressing refresh cycles as occupancy rebounds across major travel corridors, redirecting volume from premium residential segments that retreated from pandemic-era spending.
Growth Catalysts
- EU Green Deal fiber traceability:Mandatory organic certification under REACH chemical restrictions is locking in compliant European suppliers and excluding uncertified competitors from EU market access.
- Hospitality occupancy recovery:Hotel procurement teams across Dubai, Singapore, and Miami are accelerating linen replacement schedules to match guest volume rebounds.
- Indian textile mill scaling:Domestic finished-goods output from Gujarat and Tamil Nadu clusters is absorbing export demand from Middle Eastern and African hospitality buyers.
Market Restraints
- Organic cotton input cost volatility:Certified fiber premiums fluctuate with weather-driven Indian and Egyptian crop yields, squeezing margin on fixed-price hospitality contracts.
- Dyehouse concentration in Zhejiang:Chemical finishing capacity clusters in China's eastern provinces, creating single-geography exposure for mercerization and sanforization processing.
- Bamboo viscose substitution ceiling:Moisture-wicking performance gains hit durability limits below 300 wash cycles, blocking adoption in institutional laundering environments.
Strategic Opportunities
- Saudi hospitality construction pipeline:Giga-project hotel development under Vision 2030 is generating concentrated demand for king-size configurations with accelerated delivery timelines.
- Digital-native rental housing platforms:Furnished apartment operators in Berlin and Barcelona are bundling standardized linen packages into tenant onboarding, creating recurring B2B subscription volume.
- Blockchain fiber traceability convergence:Integration of RFID tagging with distributed ledger systems is enabling real-time organic certification verification for EU customs clearance.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Testing laboratory backlogs in Frankfurt and Shanghai are extending chemical safety verification from six to fourteen weeks, delaying product launches.
- Legacy ERP integration with traceability platforms:Tier-two weavers in Pakistan's Faisalabad cluster lack technical staff to connect blockchain verification modules to existing inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Linen Market |
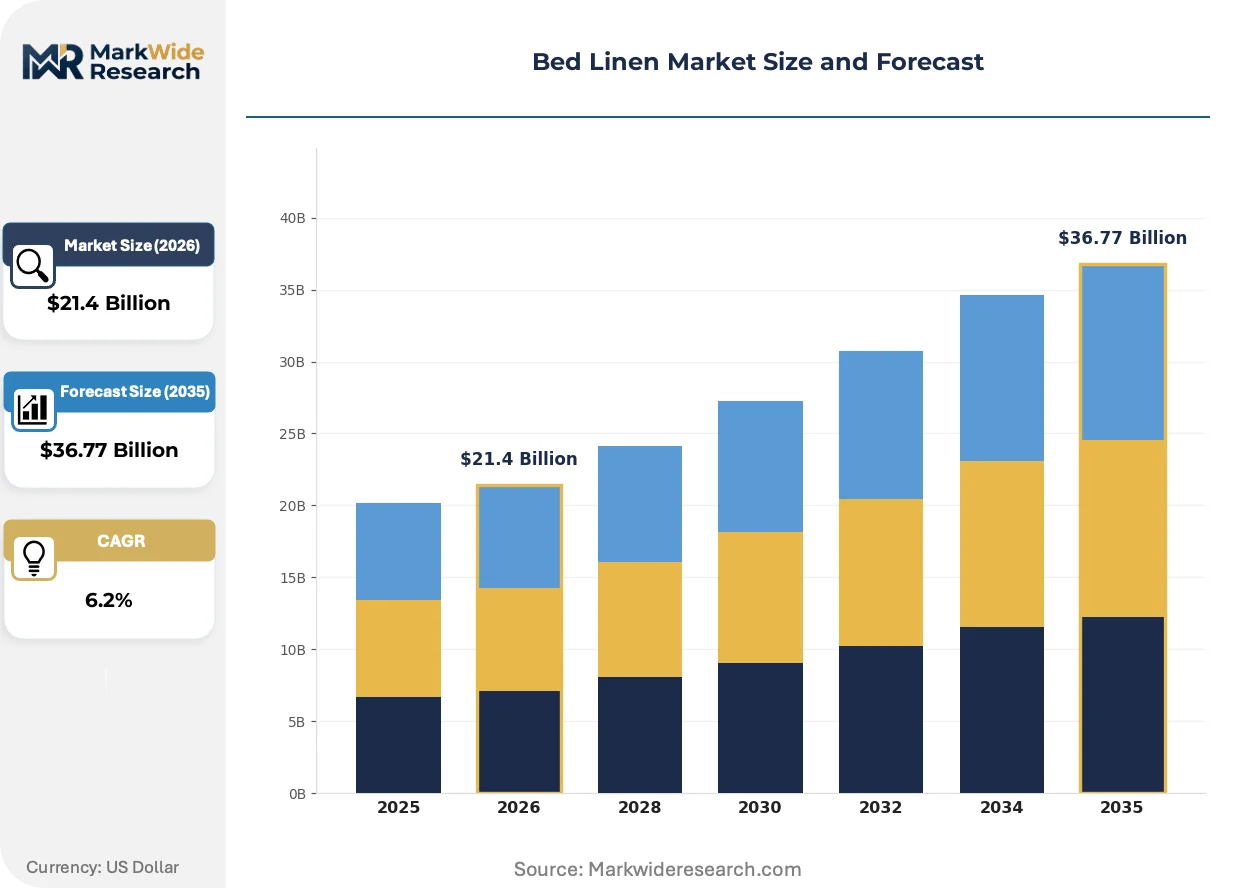
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $36.77 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Pillowcases, Comforters, Bedspreads Material: Cotton, Linen, Polyester, Bamboo Size: Twin, Full, Queen, King Pattern: Solid, Striped, Floral, Geometric |
| Companies Covered | Boll & Branch, Frette North America, Parachute Home, Celine Linen, SFERRA Fine Linens, Coyuchi, WestPoint Home, Quince, Brooklinen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Linen Market Emerging Trajectories
Digital verification technologies and regulatory chemistry mandates are compressing traditional supply chain opacity. Fiber traceability, finishing chemistry disclosure, and procurement platform automation are converging to reshape how bed linen moves from mill to mattress.
Blockchain-enabled supply chain verification is decomposing the information asymmetry that historically separated certified organic growers from downstream buyers. Luxury hospitality procurement teams in London and New York are piloting real-time fiber-origin tracking. This transparency infrastructure is compressing audit costs and locking in premium pricing for verified supply chains.
REACH chemical restrictions under the EU Green Deal are eliminating azo dyes and formaldehyde-based finishes from European-sourced product lines. Dyehouse operators in Portugal and Italy are retooling to water-based pigment systems. King-size bedding destined for German and French retail channels faces the tightest compliance timelines as 2025 enforcement windows approach.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for residential buyers. Digital-native brands are converting mattress purchasers into automated sheet replacement programs. This channel shift concentrates most visibly in North American urban markets where apartment turnover and platform-native purchasing behavior overlap.
Bed Linen Market Segmentation
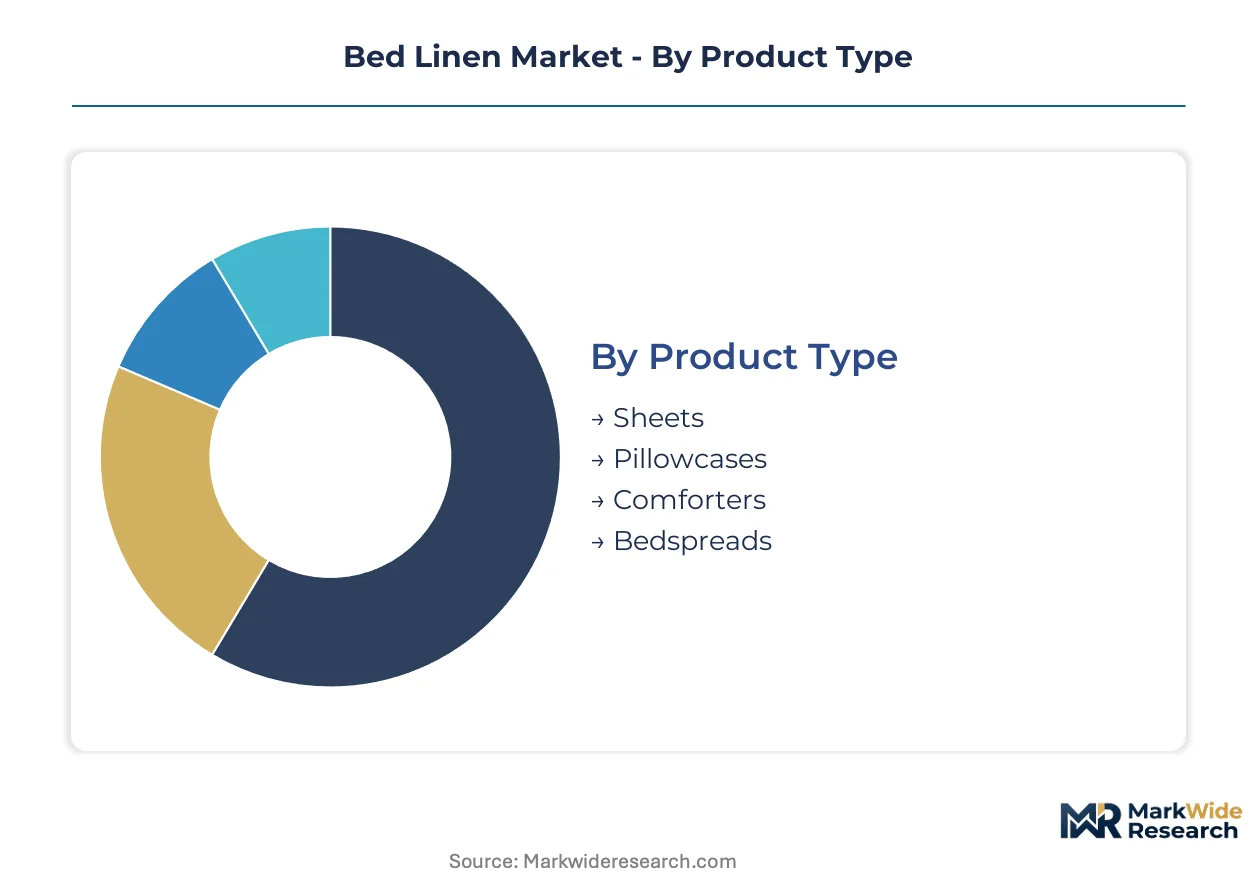
Bed linen procurement decisions fragment across technical specifications, aesthetic preferences, and end-use durability requirements. Material composition and size configuration determine margin structures, while pattern and product type drive channel placement and inventory velocity.
Product Type:
Sheets face the most intense substitution pressure from mattress toppers and integrated sleep systems, forcing standalone sheet manufacturers to defend placement through thread-count differentiation and finish innovation.
- Sheets:Woven flat and fitted panels specified by thread count, fiber staple length, and finishing treatments such as mercerization for dimensional stability. Hospitality procurement teams in Dubai and Miami are compressing refresh cycles to match occupancy rebounds, redirecting volume toward institutional-grade percale weaves.
- Pillowcases:Envelope or housewife-style closures in standard, queen, and king dimensions, often sold coordinated with sheet sets. King-size configurations command disproportionate margin contribution in North American retail channels where bedroom textile bundling drives average order value expansion.
- Comforters:Quilted insulating layers with baffle-box or channel construction, filled with down, down-alternative, or recycled polyester batting. Down-filled variants face REACH chemical restriction compliance costs for European market access.
- Bedspreads:Decorative top-of-bed coverings with woven or quilted surface texture, typically specified for hospitality visual standards rather than thermal performance. Weight and drape specifications vary by property tier in Saudi giga-project developments.
Sheets retain volume leadership; pillowcases hold the steepest expansion curve through coordinated-set purchasing behavior.
Material:
Cost tier stratification separates commodity synthetics from certified organic fibers, with mid-market blends capturing price-sensitive residential demand.
- Cotton:Upland, Pima, and Egyptian extra-long staple varieties graded by fiber length and micronaire. Organic cotton certification under EU Green Deal mandates is locking in compliant European suppliers while pressuring margin on fixed-price hospitality contracts.
- Bamboo:Viscose fiber derived from bamboo pulp, processed through closed-loop or conventional solvent systems. Moisture-wicking performance gains hit durability limits below institutional laundering thresholds, blocking adoption in hotel and healthcare channels.
- Linen:Bast fiber from flax stems, valued for breathability and characteristic slubbed texture. Portuguese and Belgian mills are retooling dyehouse operations to water-based pigment systems under REACH chemical restrictions.
- Polyester:Petrochemical-derived filament or staple fiber, often blended with cotton for wrinkle resistance and cost reduction. Recycled-content variants face FTC substantiation requirements for environmental marketing claims in US retail.
Cotton maintains volume dominance; bamboo viscose is climbing the fastest on moisture-management positioning in direct-to-consumer channels.
Size:
Application context determines size demand concentration, with residential and institutional procurement following divergent specification logic.
- King:76-by-80-inch mattress coverage, dominant in North American master bedroom configurations. Saudi Vision 2030 hospitality construction is generating concentrated demand with accelerated delivery timelines for premium properties.
- Queen:60-by-80-inch standard, the volume workhorse in US retail and apartment turnover markets. Digital-native subscription brands are converting mattress purchasers into automated sheet replacement programs at this size tier.
- Twin:38-by-75-inch specification for single-occupancy institutional use. Student housing and healthcare procurement channels sustain higher turnover velocity despite lower unit pricing.
- Full:54-by-75-inch transitional size, declining in residential preference but retained in extended-stay hotel specifications for space-constrained room layouts.
Queen retains volume leadership; king holds the steepest expansion curve through hospitality premiumization and North American residential upsizing.
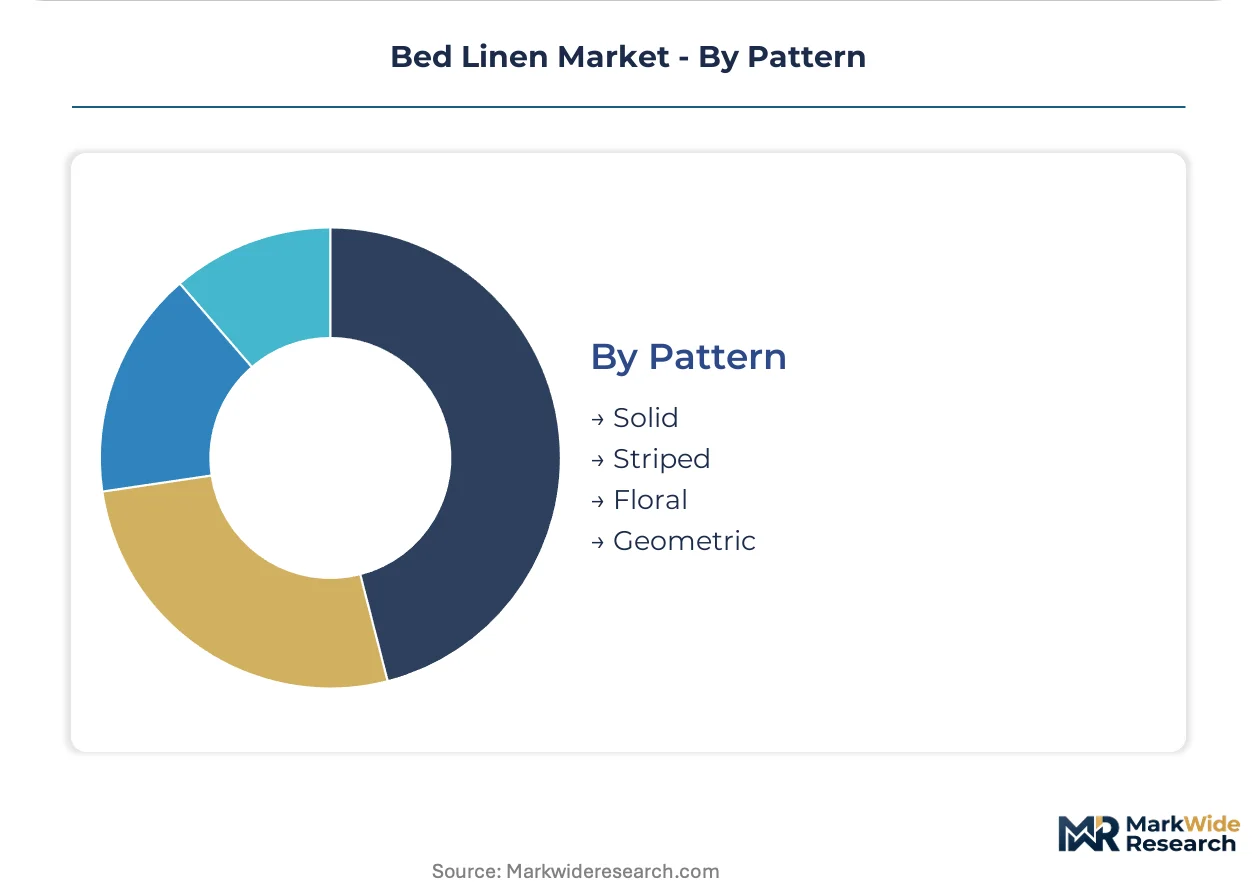
Pattern:
Customer type separates contract hospitality buyers with strict visual standards from residential purchasers exercising individual aesthetic preference.
- Solid:Undyed or uniformly dyed surface without pattern variation, specified for hospitality brand consistency and minimalist residential trends. White and neutral solids dominate hospital and hotel procurement for bleachability and replacement flexibility.
- Striped:Linear patterning through yarn-dyed construction or printed application, offering visual interest without floral complexity. Nautical and hotel-inspired stripe configurations cycle through retail trend periods with predictable regularity.
- Floral:Botanical motif through screen, digital, or rotary printing, concentrated in residential and boutique hospitality segments. REACH azo dye restrictions are eliminating certain red and orange pigment classes from European-sourced production.
- Geometric:Angular, repeating patterns including chevron, lattice, and abstract tessellation. Digital printing technology is compressing minimum order quantities, enabling short-run geometric collections for fast-fashion home textile retailers.
Solid retains volume leadership; geometric holds the steepest expansion curve through digital printing flexibility and platform-native brand velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's textile mills ship finished bed linen to Middle Eastern hospitality buyers while European procurement teams source compliant organic cotton through Portuguese and Italian dyehouse networks. Trade corridors now prioritize certification-ready supply chains over pure cost optimization.
United States
Digital-native subscription brands convert mattress purchasers into automated sheet replacement programs across urban markets. The FTC enforces textile labeling and environmental marketing claims, compelling domestic sellers to substantiate organic and recycled-content assertions. King-size configurations dominate master bedroom specifications in Southern California and Texas metro corridors.
Germany
REACH chemical restrictions under the EU Green Deal eliminate azo dyes and formaldehyde-based finishes from German retail channels. The country's national textile regulator tightens enforcement windows as 2025 compliance deadlines approach. Dyehouse operators in North Rhine-Westphalia retool to water-based pigment systems for king-size bedding destined for mass-market distribution.
India
Domestic textile mills in Gujarat and Tamil Nadu scale finished-goods output for both local retail and export channels to African and Middle Eastern buyers. The Bureau of Indian Standards monitors fiber quality and labeling compliance across the sector. Cotton processing clusters around Ahmedabad and Coimbatore absorb hospitality procurement volume as European buyers seek alternative sourcing.
Saudi Arabia
Giga-project hotel development under Vision 2030 generates concentrated demand for king-size configurations with accelerated delivery timelines. The Saudi Food and Drug Authority oversees textile safety standards for hospitality and healthcare applications. Construction corridors around Riyadh and the Red Sea coast anchor procurement volume for premium property developments.
China
Chemical finishing capacity clusters in Zhejiang province create single-geography exposure for mercerization and sanforization processing serving global bed linen supply chains. The Ministry of Ecology and Environment enforces dual carbon goals that reshape dyehouse energy profiles. Mill cities around Shaoxing and Ningbo process raw cotton imports into finished sheeting for re-export to European and North American buyers.
Bed Linen Market Vendor Landscape
Listed leaders compete with private specialists across direct-to-consumer and institutional supply channels. The vendor base stratifies into three tiers: scale-driven manufacturers serving hospitality and healthcare, digital-native brands capturing subscription revenue, and heritage specialists commanding luxury price points. Consolidation pressure concentrates among mid-market weavers lacking certification infrastructure. Dominant competitive moves include backward integration into organic cotton sourcing and strategic partnerships with blockchain traceability platforms.
Within the heritage-luxury tier, Frette North America and SFERRA Fine Linens exemplify positioning anchored in European craftsmanship narratives and hospitality supply relationships. WestPoint Home occupies a position among scale-driven manufacturers with large-scale capacity serving institutional channels. Brooklinen represents the digital-native archetype, converting mattress purchasers into repeat buyers through platform-native brand velocity and automated replenishment programs.
| Leading Market Players |
|---|
| Boll & Branch |
| Frette North America |
| Parachute Home |
| Celine Linen |
| SFERRA Fine Linens |
| Coyuchi |
| WestPoint Home |
| Quince |
| Brooklinen |
| Others |
Supply Flow & Price Mechanics
Bamboo viscose substitution for cotton in moisture-wicking residential bedding simultaneously shifts sourcing geography toward Chinese pulp processors and compresses pricing premiums in the mid-market tier, as durability limitations prevent institutional adoption and lock in cotton's grip on hospitality procurement.
Pricing Analysis
Conventional percale weaves, bamboo-derived viscose finishes, and blockchain-verified organic certifications stratify across three distinct pricing tiers in bed linen procurement. Certification grade under EU Green Deal mandates and volume scale in hospitality contracts drive price differentiation between European-compliant suppliers and uncertified competitors. Pricing pressure stems from organic cotton input cost volatility tied to Indian and Egyptian crop yields, squeezing margins on fixed-price hotel contracts. Hospitality buyers exhibit lowest price sensitivity due to brand-standard requirements, while student housing procurement teams prioritize unit economics above fiber provenance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes through Rotterdam and Hamburg are extending lead times for mercerized cotton sheeting destined for German retail channels. Finished-goods production concentrates in India, China, and Portugal, with raw cotton drawing from Gujarat spinning mills, Xinjiang ginneries, and Egyptian long-staple suppliers. Single-geography exposure in Zhejiang province for chemical finishing creates vulnerability for sanforization and mercerization processing. Distribution runs through hospitality procurement platforms, direct-to-consumer subscription channels, and mass-market retail replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospitality procurement platforms and digital-native subscription operators, fragmenting traditional wholesale relationships and forcing suppliers to absorb certification compliance costs.
For Market Incumbents: Fortify supply relationships through backward integration into organic cotton sourcing in Gujarat and Tamil Nadu clusters, locking in fiber traceability ahead of EU Green Deal enforcement windows. Defend margin position by converting hospitality clients into multi-year service contracts with embedded refresh-cycle guarantees, insulating against spot-price volatility in certified fiber markets. For New Entrants and Emerging Players: OEKO-TEX Standard 100 fast-track certification offers entry into European hospitality supply chains where testing laboratory backlogs have frozen incumbent product launches. Target furnished apartment operators in Berlin and Barcelona with standardized linen subscription packages, converting tenant onboarding into recurring B2B revenue. Deploy blockchain-verified fiber origin tracking as a differentiated procurement pitch to London and New York luxury hotel buyers. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated specialists with captive organic certification infrastructure and hospitality platform relationships. Five-to-ten year viability hinges on traceability technology deployment and REACH-compliant dyehouse retooling. Monitor blockchain-RFID integration adoption rates among Portuguese and Italian finishers as the inflection signal for premium pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Fast-Track | EU Green Deal compliance deadlines in Germany and France lock in market access for verified suppliers. |
| Blockchain Traceability Integration | RFID-distributed ledger convergence enables real-time customs clearance for Indian cotton exports. |
| Hospitality Platform Partnership | Digital procurement networks in Dubai and Miami compress refresh-cycle decision timelines. |
| Backward Cotton Sourcing | Gujarat and Tamil Nadu mill integration secures fiber supply against Egyptian crop volatility. |
| Water-Based Pigment Retooling | Portuguese and Italian dyehouses eliminate azo dye exposure ahead of REACH enforcement. |
Methodological Framework
Cross-validation between primary interviews with hospitality procurement directors, textile mill operations managers, and EU regulatory compliance officers anchors the qualitative findings against secondary validation from customs trade records, BIS fiber quality filings, and ECHA chemical restriction updates. Bottom-up demand modeling from hotel construction pipelines and residential subscription platform data converges with top-down market sizing from cotton futures pricing and finished-goods export volumes.
Sensitivity analysis across thread-count tiers, certification grades, and regional hospitality occupancy patterns shapes the analytical framework over the projection horizon. Segmentation dimensions include material composition, size configuration, pattern type, and end-use channel. CAGRs derive from fiber input cost trajectories, regulatory compliance timeline assumptions, and platform-native brand velocity coefficients in North American urban markets.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and hospitality occupancy recovery assumptions; material deviation in Indian monsoon patterns or Zhejiang dyehouse capacity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Duvets Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Table Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
United States Bed and Bath Linen Market