
 Asia-Pacific Bed and Bath Linen Market | 2026-2036
Asia-Pacific Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bed and Bath Linen Market Outlook
The capability gap between integrated spinning-weaving-finishing operations and asset-light trading houses is collapsing as raw cotton volatility and energy costs erode margins for non-integrated players. Trident Limited leverages captive cotton sourcing and in-house terry towel manufacturing to sustain margin stability across cycles. Welspun Global anchors its position through advanced open-end spinning capacity and certified sustainable product lines for hospitality chains. Indo Count Industries competes via specialized bed linen finishing and dyeing expertise directed at the North American and European export markets.
Asia-Pacific bed and bath linen encompasses woven and knitted textile products manufactured from natural and synthetic fibers, typically featuring thread counts ranging from 200 to 800 for bedding and 400 to 700 grams per square meter for terry towels, designed for hygiene, comfort, and thermal regulation in residential and commercial sleeping and bathing environments. Cotton-dominant material segments command the deepest margin pools due to premium positioning and certified organic supply chains, while microfiber blends penetrate budget hospitality procurement through durability and faster laundering cycles. Hotels and healthcare facilities represent the fastest-growing end-user channel as institutional buyers consolidate vendor relationships and demand compliance with international sustainability protocols.
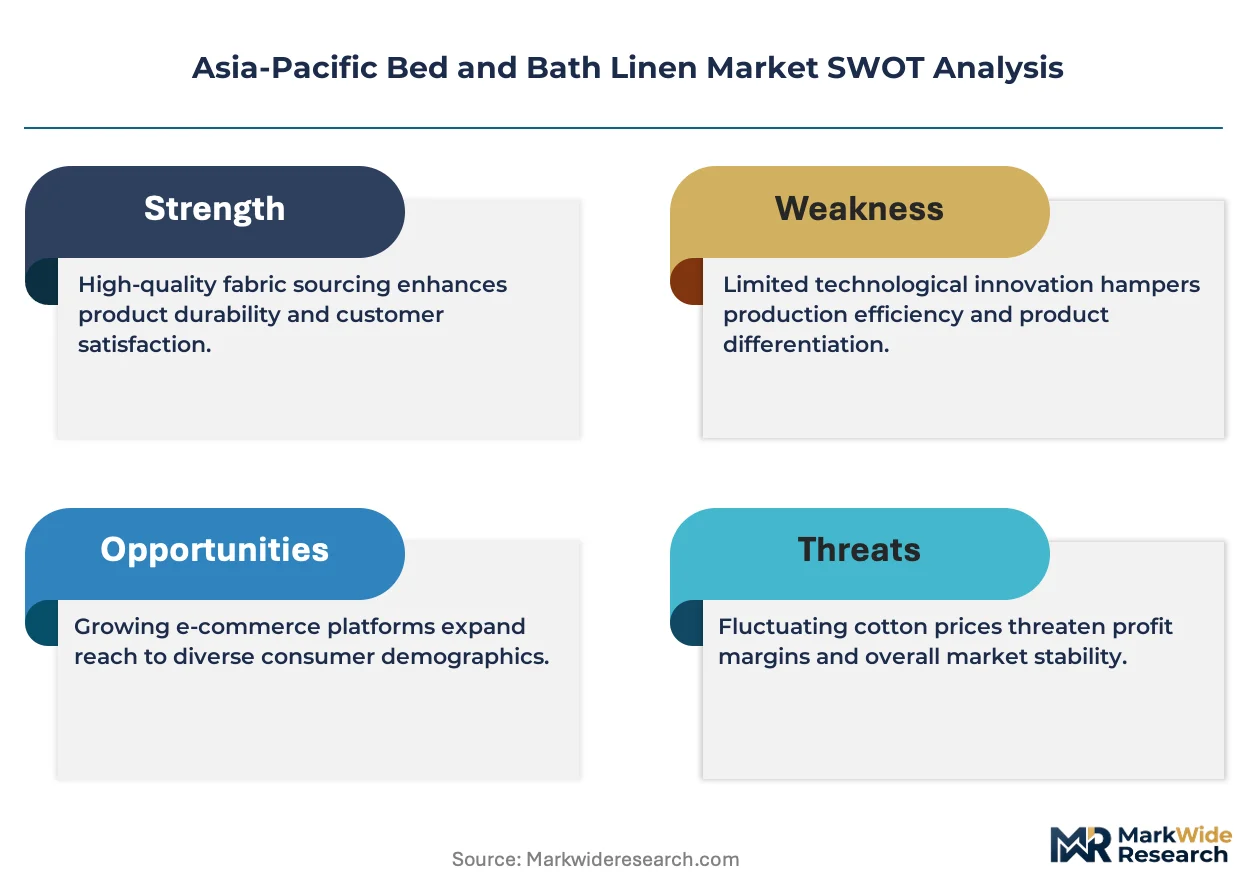
India's BIS textile standards, China's GB product safety codes, and Japan's JIS quality certifications collectively shape material specifications, chemical discharge limits, and market access requirements across the region. These frameworks push manufacturers toward OEKO-TEX and GOTS-aligned production systems, raising compliance costs for smaller mills while rewarding scaled operators with certification infrastructure. Stakeholders must monitor evolving dual carbon targets in China and India's PLI scheme incentives for technical textiles as these policies redirect capital toward energy-efficient dyeing and recycled fiber integration.
Market Dynamics
India's BIS certification tightening for textile quality is compressing margins for non-compliant mills while rewarding scaled operators with certification infrastructure, fundamentally restructuring competitive positioning across the Asia-Pacific bed and bath linen supply base.
Growth Catalysts
- China's dual carbon targets:Energy-efficient dyeing investments are accelerating facility upgrades in Zhejiang and Jiangsu provinces, pulling demand toward certified low-carbon suppliers.
- Hospitality procurement consolidation:International hotel chains expanding across India and Southeast Asia are consolidating vendor relationships toward full-service linen providers with OEKO-TEX certification.
- Recycled fiber integration:Post-consumer cotton recovery technologies are scaling in South Korea and Japan, enabling closed-loop terry towel production for institutional buyers.
Market Restraints
- Raw cotton price volatility:Unpredictable Indian monsoon patterns and US export fluctuations are eroding margin stability for non-integrated spinning operations.
- Supply concentration in Xinjiang:Geopolitical scrutiny over cotton sourcing from this region is forcing supply chain reconfigurations and compliance documentation costs.
- Technical limitation in dyeing:Waterless supercritical CO2 dyeing remains capital-intensive and scale-constrained, limiting adoption outside premium segments.
Strategic Opportunities
- Underpenetrated Vietnam:Manufacturing relocation from China is creating demand for local finishing capacity to serve export-oriented hospitality and healthcare sectors.
- India's PLI scheme for technical textiles:Government incentives are redirecting capital toward flame-retardant and antimicrobial linen development for hospital and aviation applications.
- Direct-to-hotel platform distribution:Digital procurement portals are disintermediating traditional trading houses, enabling mill-direct relationships with mid-size hotel chains.
Industry Challenges
- Skill gaps in advanced finishing:Shortages of technicians trained in digital printing and nanotechnology coating are constraining product development timelines.
- Certification timeline compression:Simultaneous BIS, OEKO-TEX, and GOTS audits are creating administrative bottlenecks for multi-market suppliers.
- Legacy ERP integration:Mill-level traceability systems struggle to interface with blockchain-based supply chain platforms demanded by European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bed and Bath Linen Market |
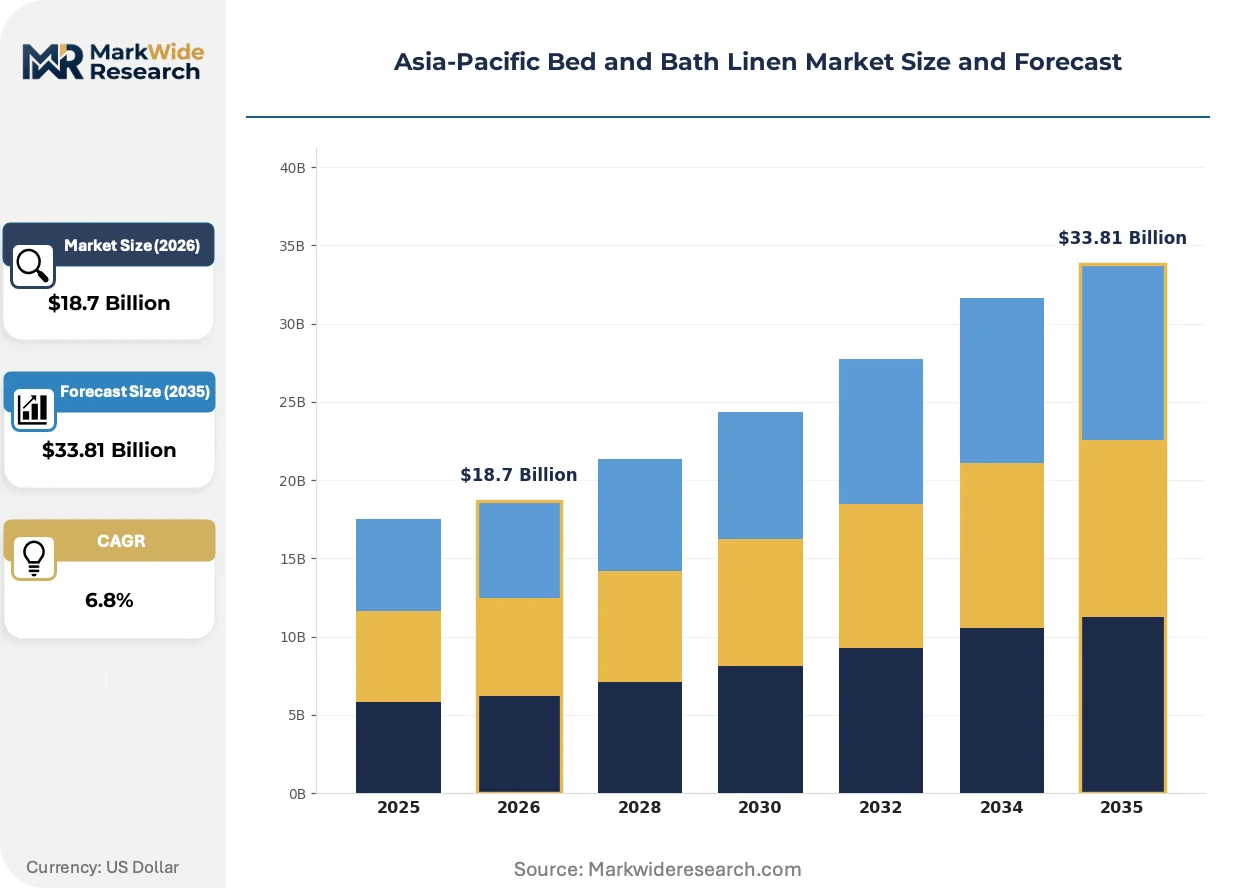
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding Sets, Towels, Bath Rugs, Pillow Covers Material: Cotton, Polyester, Linen, Microfiber End User: Residential, Hotels, Spas, Healthcare Facilities Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Trident Limited, Indo Count Industries, Welspun Global, Nantong Kelin Textiles Co Ltd, Vardhman Textiles Limited, Bombay Dyeing, Sidefu, Hangzhou Yintex Co, Raymond Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bed and Bath Linen Market Strategic Shifts
Digital traceability platforms and sustainable chemistry are converging to reshape how Asia-Pacific linen manufacturers compete on transparency and environmental credentials.
Blockchain-based cotton provenance tracking is fragmenting the traditional opaque supply chain. Luxury hotel chains and hospital procurement departments are mandating farm-to-facility visibility. This transparency infrastructure is compressing margins for trading houses unable to provide origin documentation.
Japan's METI circular economy guidelines and China's GB/T standards for textile recycling are mandating post-consumer fiber content disclosures. Manufacturers are retrofitting spinning lines for recycled cotton blends. Premium residential segments in Tokyo and Shanghai are absorbing price premiums for certified circular products.
Subscription-based linen service models are displacing ownership in Australia's aged care and Japan's hospitality sectors. Facility management companies are bundling laundering, replacement, and inventory management. Victoria and New South Wales are seeing the fastest uptake as labor costs make in-house linen management uneconomical.
Asia-Pacific Bed and Bath Linen Market Segmentation
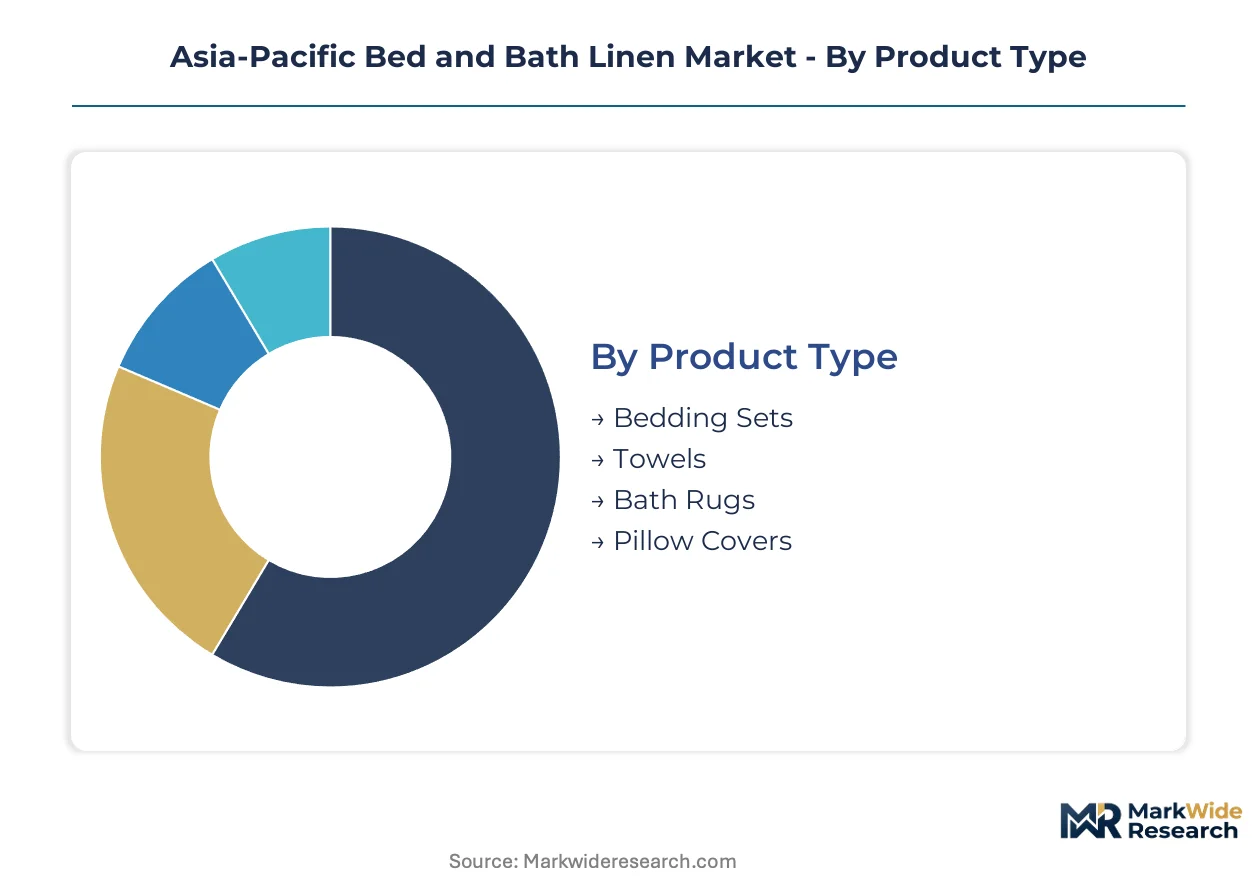
Segmentation in Asia-Pacific bed and bath linen reveals how regulatory frameworks and procurement specifications fragment demand across incompatible technical standards. BIS certification tiers, OEKO-TEX levels, and GB material codes create non-substitutable product categories that resist price arbitrage.
Product Type:
BIS textile standards and hospitality procurement specifications create divergent durability and thread count requirements across each product category.
- Bedding Sets:Woven sheeting and duvet covers with thread counts from 200 to 800 dominate premium residential and luxury hotel procurement. Demand concentrates in China's tier-one cities where renovation cycles accelerate replacement frequency.
- Towels:Terry cloth products ranging from 400 to 700 grams per square meter absorb the largest procurement volumes from institutional buyers. India's hospitality sector expansion drives specification tightening toward OEKO-TEX Standard 100 compliance.
- Bath Rugs:Non-slip backing and quick-dry surface treatments address safety protocols in healthcare and aged care facilities. Japanese JIS standards mandate specific absorption rates for commercial installations.
- Pillow Covers:Envelope and zippered constructions serve distinct laundering workflows in hotels versus residential settings. Direct-to-hotel platforms are disintermediating traditional distributor relationships for this high-frequency replacement item.
Towels handle the majority of throughput; bedding sets are gaining share fastest as premium residential renovation accelerates across the region.
Material:
Cost tier differentiation separates certified organic supply chains from commodity petrochemical-based alternatives with irreconcilable margin structures.
- Cotton:Natural fiber commanding premium positioning through GOTS and BCI certification programs. Captive sourcing from integrated spinners in India sustains margin stability against raw price volatility.
- Polyester:Synthetic staple and filament yarns deliver durability and faster drying cycles for budget hospitality procurement. China's dual carbon targets are pressuring energy-intensive polyester production in Zhejiang province.
- Linen:Bast fiber from flax cultivation offers superior thermal regulation and antimicrobial properties for luxury residential segments. Japanese and South Korean buyers absorb price premiums for European-origin flax blends.
- Microfiber:Ultra-fine denier synthetic filaments penetrate healthcare and spa sectors through lint-free performance and bleach tolerance. Recycled PET feedstock integration is scaling in South Korean manufacturing clusters.
Cotton absorbs the largest revenue pool; microfiber is expanding most quickly as institutional buyers prioritize laundering economics over tactile premium.
End User:
Application-specific durability protocols and replacement cycles create divergent vendor qualification requirements across customer types.
- Residential:Individual consumers purchasing through retail and online channels with preference for thread count and tactile quality indicators. Australia's subscription-based linen services are displacing ownership in aged care segments.
- Hotels:International chains consolidating vendor relationships toward full-service providers with certification infrastructure. India's luxury hotel sector expansion is accelerating procurement centralization.
- Spas:Wellness facilities demanding antimicrobial finishes and accelerated laundering turnaround. Thailand and Indonesia's wellness tourism recovery is rebuilding procurement volumes.
- Healthcare Facilities:Hospitals and clinics requiring flame-retardant and fluid-resistant properties under India's PLI scheme for technical textiles. Australia's public health procurement mandates local finishing capacity.
Hotels generate the largest contract volumes; healthcare facilities are climbing the fastest as technical textile incentives redirect manufacturing investment.
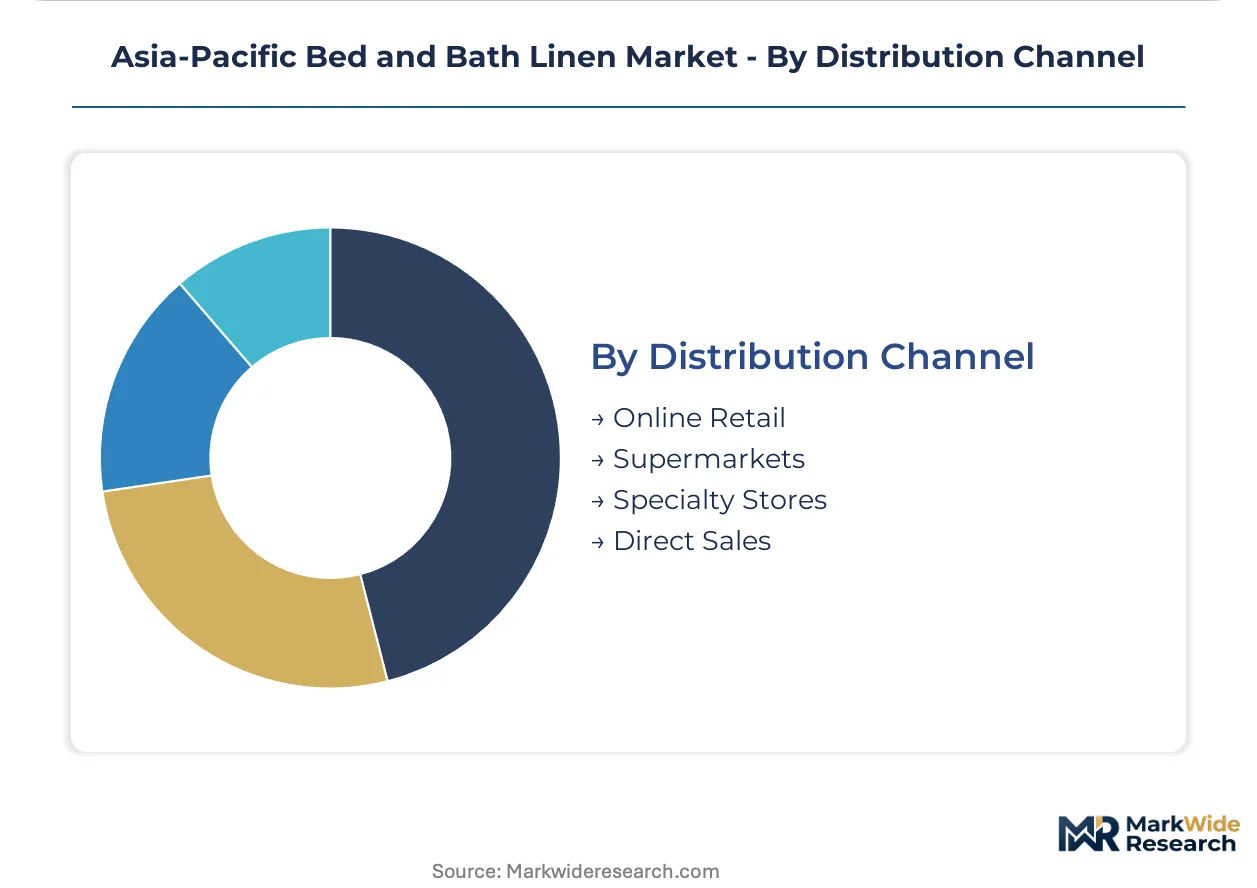
Distribution Channel:
Customer type and order scale dictate channel selection with minimal cross-channel migration for equivalent purchase occasions.
- Online Retail:E-commerce platforms capturing residential replacement purchases and small hospitality restocking. Southeast Asia's digital marketplace penetration is accelerating direct-to-consumer brand building.
- Supermarkets:Mass-market retailers distributing private-label bedding and towel sets for price-sensitive residential segments. Australia's Woolworths and Coles chains dominate volume throughput.
- Specialty Stores:Curated retail environments offering tactile evaluation and certification documentation for premium cotton and linen. Tokyo and Shanghai flagship locations anchor regional brand positioning.
- Direct Sales:Mill-direct relationships and digital procurement portals serving mid-size hotel chains and healthcare networks. Vietnam's underpenetrated hospitality sector is creating demand for local finishing capacity.
Direct sales capture the steepest expansion trajectory; supermarkets retain the largest transaction volume across mass-market residential demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan's certified organic segments while India's integrated spinners compete on volume throughput. China's dual carbon mandates are restructuring manufacturing economics across the region. Australia's subscription service models are displacing traditional ownership patterns.
China
Tier-one city renovation cycles are accelerating replacement demand for high-thread-count bedding in Shanghai and Beijing. GB standards for textile recycling and the dual carbon targets are pressuring energy-intensive dyeing operations in Zhejiang province. Manufacturing clusters in Jiangsu are retrofitting facilities for low-carbon production to maintain access to European hospitality procurement.
India
Luxury hotel sector expansion by international brands is tightening procurement specifications toward OEKO-TEX compliance. BIS certification requirements for textile quality are compressing margins for non-compliant mills while rewarding scaled operators. Integrated spinning-weaving operations in Punjab and Gujarat are consolidating market share through captive cotton sourcing.
Japan
Residential demand for European-origin flax blends is absorbing price premiums in Tokyo and Osaka premium segments. METI circular economy guidelines are mandating post-consumer fiber content disclosures across retail channels. Industrial clusters in Nagoya are developing closed-loop terry towel production for institutional buyers.
Vietnam
Manufacturing relocation from China is creating demand for local finishing capacity to serve export-oriented hospitality procurement. The underpenetrated hospitality sector is attracting mill-direct platform relationships with mid-size hotel chains. Ho Chi Minh City and Hanoi are emerging as consolidation points for regional supply chain reconfiguration.
Australia
Subscription-based linen service models are displacing ownership in Victoria and New South Wales aged care sectors. Public health procurement mandates for local finishing capacity are reshaping vendor qualification requirements. Sydney and Melbourne facility management companies are bundling laundering, replacement, and inventory management services.
Asia-Pacific Bed and Bath Linen Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific bed and bath linen supply base. The market structure fragments between integrated spinning-weaving-finishing operations and asset-light trading houses facing margin erosion from raw cotton volatility. Three archetypes dominate: vertically integrated cotton spinners with captive sourcing, specialized finishing houses targeting export certification tiers, and digital platform-native distributors disintermediating traditional channels. Competitive moves concentrate on certification infrastructure investment and mill-direct procurement portal development.
Among India-based integrated manufacturers, Trident Limited, Indo Count Industries, and Welspun Global occupy positions representing distinct strategic archetypes. Trident exemplifies the captive-sourcing model through in-house terry towel manufacturing. Indo Count sits within the export-specialist tier directed at North American and European certification requirements. Welspun anchors the sustainable product line segment for hospitality chain procurement. Chinese fabricators including Nantong Kelin Textiles and Hangzhou Yintex represent the regional finishing capacity expansion responding to supply chain relocation pressures.
| Leading Market Players |
|---|
| Trident Limited |
| Indo Count Industries |
| Welspun Global |
| Nantong Kelin Textiles Co Ltd |
| Vardhman Textiles Limited |
| Bombay Dyeing |
| Sidefu |
| Hangzhou Yintex Co |
| Raymond Group |
| Others |
Value Chain & Pricing Dynamics
Recycled cotton substitution for virgin fiber in South Korean and Japanese terry towel production is simultaneously pulling spinning capacity toward coastal industrial zones and compressing price premiums for GOTS-certified organic lines. BIS compliance costs and energy-efficient dyeing investments in Zhejiang are feeding back into supplier selection criteria for institutional buyers consolidating vendor relationships.
Pricing Analysis
Configured-to-order pricing for OEKO-TEX Standard 100 certified hospitality linens commands spreads of 40-60% above standard-grade terry towel and bedding sets. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic cotton from BCI-compliant conventional fiber and uncertified commodity grades. Price differentiation hinges on certification tier and volume scale, with procurement centralization by international hotel chains compressing margins for non-compliant trading houses. Budget hospitality segments exhibit highest price sensitivity, while luxury residential buyers in Tokyo and Shanghai absorb premiums for European-origin flax blends.
Supply Chain Analysis
Xinjiang cotton transit restrictions function as a chokepoint forcing supply chain reconfigurations and compliance documentation costs across Asia-Pacific linen manufacturing. Raw material sourcing draws from Indian captive cotton operations, Australian long-staple varieties, and US Pima exports for premium thread counts. Water-intensive dyeing processes in Jiangsu province face regulatory pressure under China's dual carbon targets, creating single-source vulnerability for energy-efficient finishing capacity. Distribution runs through mill-direct procurement portals disintermediating traditional trading houses, with Ho Chi Minh City and Hanoi emerging as consolidation points for regional supply chain reconfiguration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based linen service models in Australia's aged care and hospitality sectors represent a service-attach opportunity expanding faster than hardware ownership, with facility management companies bundling laundering, replacement, and inventory management.
For Market Incumbents: Consolidate certification infrastructure investments to defend against digital platform-native distributors disintermediating traditional channels. Capture captive cotton sourcing advantages through backward integration into Punjab and Gujarat spinning operations. Pursue OEKO-TEX and GOTS audit streamlining to reduce administrative bottlenecks from simultaneous BIS compliance requirements. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated hospitality sector where manufacturing relocation from China has created demand for local finishing capacity. Target mid-size hotel chains through digital procurement portals enabling mill-direct relationships. Build position through certified sustainable product lines aligned with international chain sustainability protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated spinning-weaving-finishing operations with certification infrastructure over asset-light trading houses facing margin erosion. Long-term viability over the next decade rests on energy-efficient dyeing investments and recycled fiber integration capabilities. Watch blockchain-based cotton provenance tracking adoption as the inflection indicator for transparency premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | BIS, OEKO-TEX, and GOTS alignment rewards scaled operators while compressing non-compliant mill margins. |
| Recycled Fiber Integration | Post-consumer cotton recovery technologies enable closed-loop production for institutional buyers under Japan's METI guidelines. |
| Digital Procurement Portal Development | Mill-direct platform relationships disintermediate traditional trading houses and capture mid-size hotel chain demand. |
| Energy-Efficient Dyeing Retrofit | Low-carbon production investments in Jiangsu maintain access to European hospitality procurement under China's dual carbon targets. |
| Subscription Service Model Launch | Laundering and inventory management bundling displaces ownership in Australia's Victoria and New South Wales aged care sectors. |
Study Parameters
Desk research of customs trade databases, BIS certification registries, and hospitality procurement specifications preceded structured interviews with textile mill operations directors, hotel procurement managers, sustainability compliance officers, and distribution channel partners. Primary fieldwork with integrated spinning-weaving operations in Punjab and Gujarat was cross-validated against secondary analysis of SEC filings from listed textile manufacturers and OEKO-TEX certification databases. Bottom-up demand modeling across residential, hospitality, spa, and healthcare end-use segments was triangulated with top-down market sizing from trade flow data.
Variance decomposition across product type, material grade, end-use application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation rather than single-point extrapolation. Forecast inputs incorporated India's PLI scheme incentive trajectories for technical textiles, China's dual carbon target implementation timelines, and hospitality sector expansion patterns by international brand footprint.
Material uncertainties — raw cotton price volatility from Indian monsoon variability, geopolitical sourcing restrictions on Xinjiang fiber, and waterless dyeing technology scale constraints — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as BIS certification enforcement intensity and blockchain traceability platform adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Duvets Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
India Bed and Bath Linen Market