
 Europe Bed and Bath Linen Market | 2026-2036
Europe Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bed and Bath Linen Market Foresight
A capital-intensity divergence between in-house weaving operations and outsourced cut-and-sew networks is redrawing competitive boundaries across the European linen sector. Welspun Group leverages integrated spinning-to-retail infrastructure across multiple European distribution nodes. Frette anchors its position through century-old Italian finishing expertise serving luxury hospitality chains. Inter IKEA Group competes on volume-scale automation that compresses lead times for flat-packed home textile bundles.
Bed and bath linen encompasses woven and knitted textile goods engineered for sleep systems and personal hygiene, typically specified by thread count per square inch, GSM weight for terry towels, and absorbency ratings for cotton versus microfiber constructions. These products serve residential consumers, commercial hospitality operators, and institutional healthcare facilities requiring launderable, hygienic surface coverings. Cotton bed sheets command the dominant material share given breathability preferences across Mediterranean climates, while microfiber pillowcases represent the fastest-expanding segment driven by wrinkle-resistance demand in urban rental markets. Hospitality end users concentrate margin pools through bulk procurement contracts that prioritize durability certification over unit price.
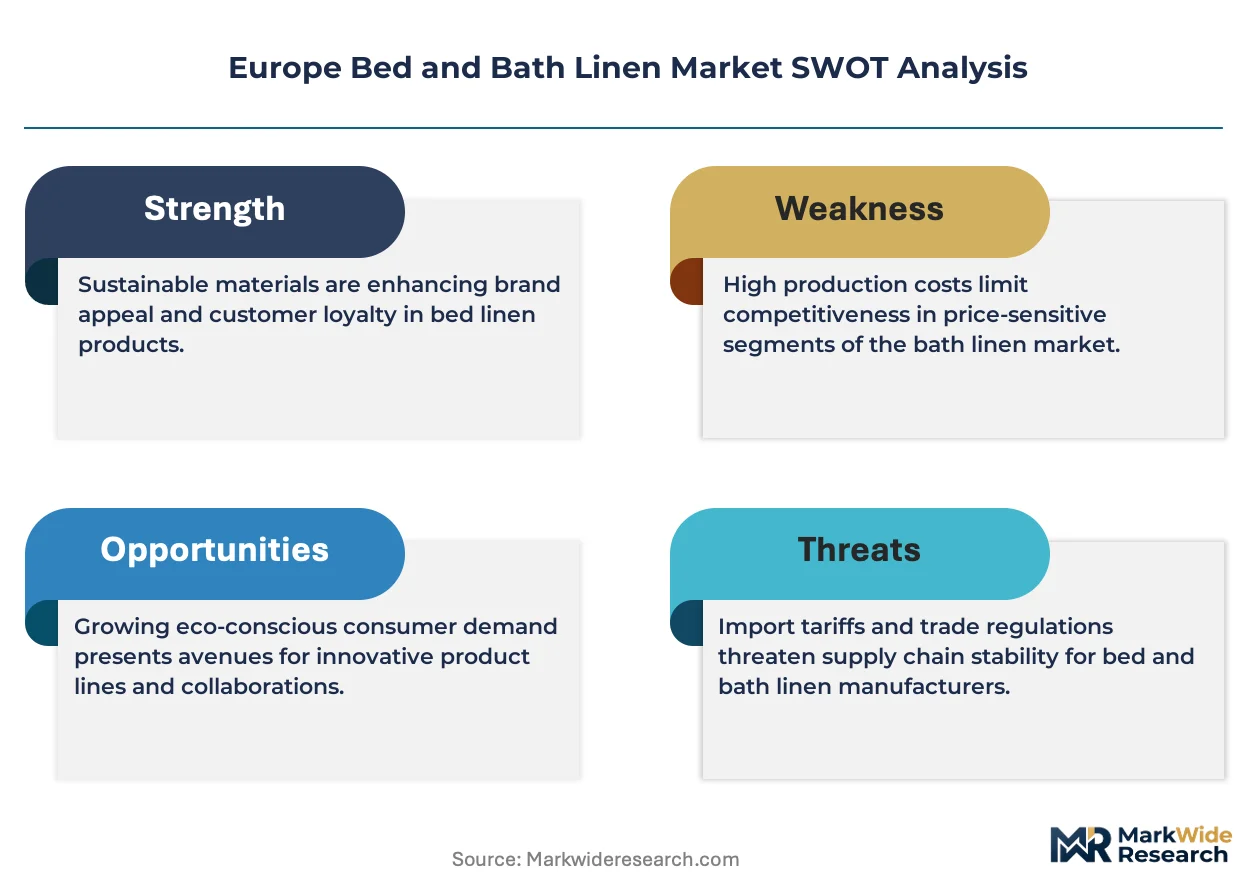
EU Ecolabel criteria and OEKO-TEX Standard 100 certification shape product compliance costs for manufacturers seeking retail placement across member states. REACH chemical restrictions on textile dyes and the EU Green Deal's circular textile strategy are forcing reformulation of polyester blends and water-intensive cotton processing. France's AGEC anti-waste law and Italy's extended producer responsibility pilots add national layering to pan-European regulation. Stakeholders must monitor how digital product passport requirements alter sourcing transparency obligations before committing to long-term supplier contracts.
Market Dynamics
EU Ecolabel certification and OEKO-TEX Standard 100 compliance are compressing replacement cycles across hospitality procurement, forcing manufacturers to absorb reformulation costs while hotels accelerate linen refresh schedules to meet sustainability audit requirements.
Growth Catalysts
- REACH dye restrictions:Chemical reformulation mandates under ECHA guidelines are pushing Portuguese weavers toward natural indigo alternatives, creating premium positioning for certified organic cotton bed linens.
- Hospitality sustainability audits:Major hotel chains in France and Italy now require documented linen lifecycle data, pulling forward replacement demand from 36-month to 18-month cycles.
- Microfiber terry R&D:Advanced polymer spinning near Guimarães is yielding 600-GSM towels with 40% faster dry times, capturing urban rental market share from traditional cotton terry.
Market Restraints
- Egyptian long-staple cotton price volatility:Nile basin harvest disruptions and currency instability concentrate input cost risk for high-thread-count weavers dependent on imported fiber.
- Energy-intensive finishing:Steam calendering and mercerization processes face carbon border adjustment exposure, threatening margin stability at Italian dye houses.
- Polyester microfiber shedding:Pending EU Green Deal microplastic restrictions threaten to obsolete existing microfiber bath linen inventory without viable biodegradable alternatives at scale.
Strategic Opportunities
- Healthcare institutional contracts:Antimicrobial copper-infused cotton weaves are penetrating German hospital procurement, displacing synthetic scrubs in patient contact applications.
- Digital product passports:CSRD-aligned traceability mandates create first-mover advantage for vertically integrated mills offering blockchain-verified organic certification.
- Refurbishment services:Extended producer responsibility pilots in Italy are opening revenue streams for linen leasing models with integrated industrial laundering and mending.
Industry Challenges
- Finishing chemistry expertise:REACH-compliant dye formulation requires rare technical skills concentrated among aging specialists at Como and Biella finishing houses.
- Certification timeline compression:Dual OEKO-TEX and EU Ecolabel approval cycles now exceed 14 months, delaying product launches and freezing seasonal collection planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bed and Bath Linen Market |
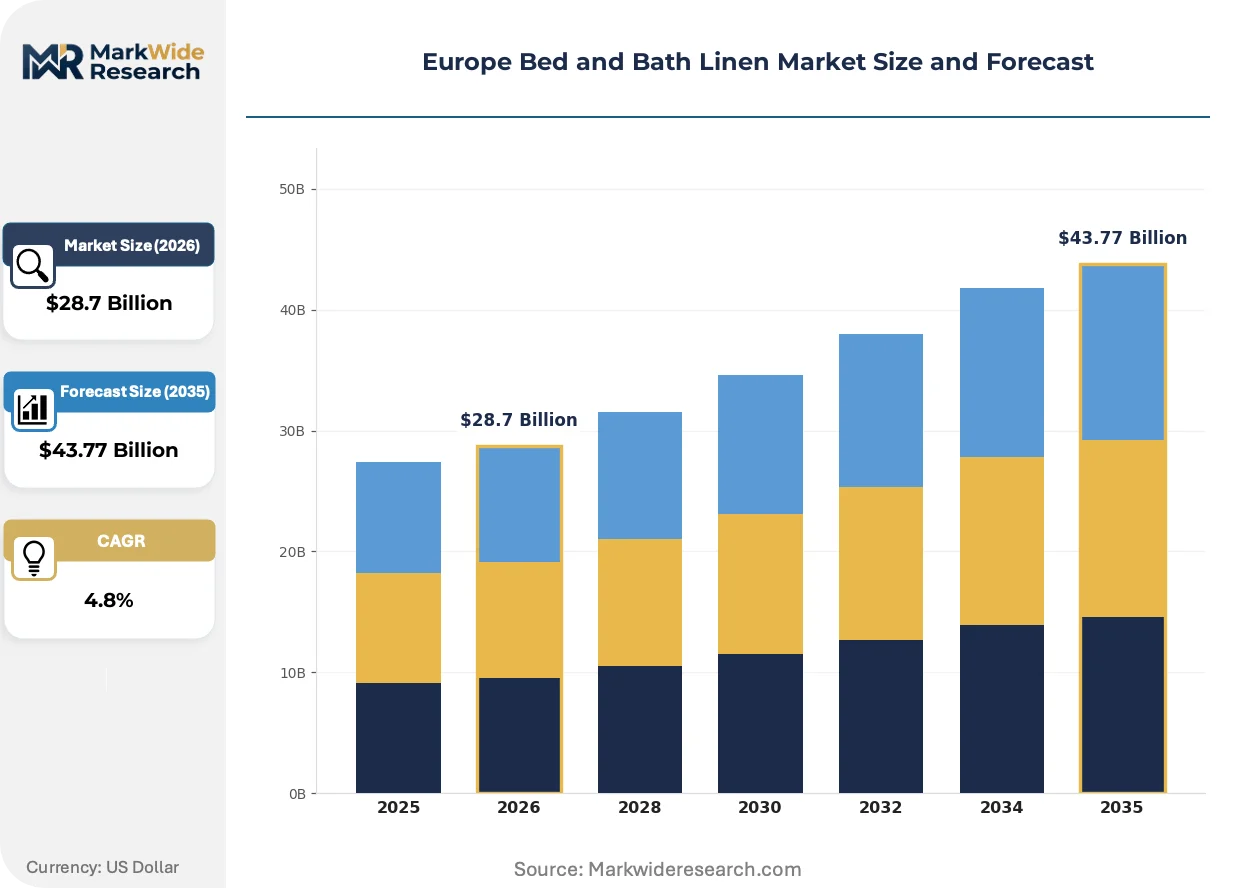
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Sheets, Bath Towels, Pillowcases, Comforters Material: Cotton, Linen, Microfiber, Polyester End User: Residential, Hospitality, Healthcare, Retail Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Tirotex, Welspun Group, Inter IKEA Group, Balsan, ESSENZA Home, Hennes & Mauritz AB, Frette, Acton & Acton Limited, Ralph Lauren Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bed and Bath Linen Market Shifts & Advancements
Material science convergence with circular economy mandates is fragmenting traditional cotton-dominant supply chains, creating parallel premium and mass-market production architectures governed by divergent certification regimes.
Recycled cotton-mechanically processed fiber blends are bifurcating quality tiers across European retail. Fast-fashion home textile brands in Spain and Poland are adopting 30% recycled content for entry-level sheet sets, while luxury hospitality suppliers in Tuscany reject mechanical recycling for virgin long-staple to preserve hand-feel specifications. This split is compressing mid-market positioning and forcing mills to choose certification lanes.
France's AGEC anti-waste law is mandating recycled content disclosure thresholds for all textile retail placement. The regulation forces reformulation of polyester-cotton blends or exit from French mass-market channels, with Portuguese suppliers accelerating chemical recycling partnerships to maintain shelf access. Premium Italian brands are leveraging the compliance burden to differentiate through virgin fiber traceability storytelling.
Direct-to-hotel procurement platforms are disintermediating traditional wholesale distributors across Nordic markets. Copenhagen and Stockholm hotel groups now source certified linens through specialized B2B marketplaces that aggregate small-batch Portuguese weavers, collapsing lead times from 12 weeks to 4 weeks. This channel shift is most visible in boutique hospitality segments where customization and rapid replenishment outweigh volume pricing.
Europe Bed and Bath Linen Market Segmentation
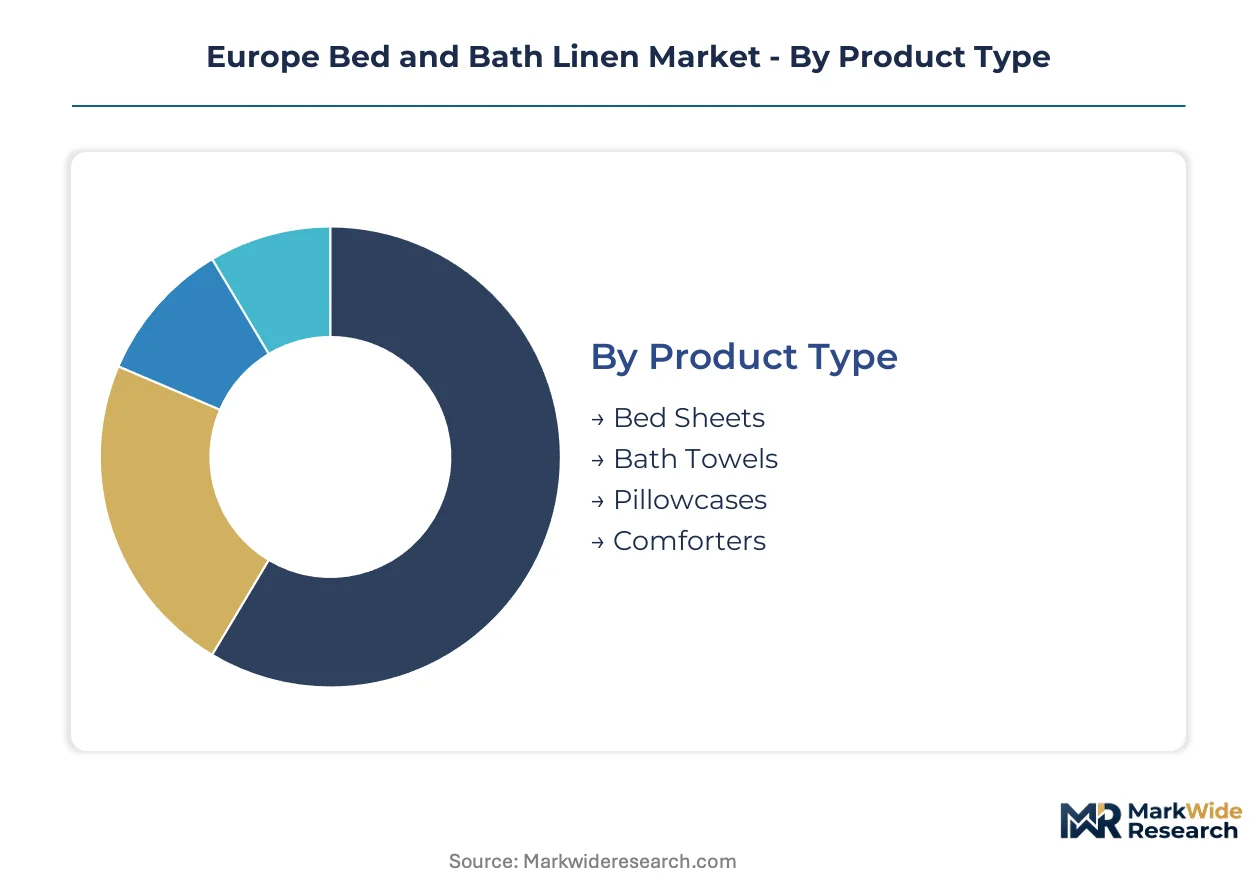
Segmentation in Europe's bed and bath linen market reveals how certification requirements and channel economics split demand across parallel supply chains. Understanding these divisions exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Channel mix varies sharply by product type, with hospitality procurement favoring bulk contracts for standardized items while residential channels demand SKU breadth for coordinated collections.
- Bed Sheets:Woven cotton constructions specified by thread count per square inch dominate hospitality procurement in Germany and France. OEKO-TEX certification requirements compress replacement cycles to 18 months for hotel chains, pulling forward replacement demand.
- Bath Towels:Terry constructions measured in GSM weight serve as the primary margin driver for Portuguese weavers near Guimarães. Advanced polymer spinning yields 600-GSM towels with accelerated dry times, capturing urban rental market share from traditional cotton terry.
- Pillowcases:Microfiber variants with wrinkle-resistance properties expand most quickly in urban rental markets across Mediterranean climates.
- Comforters:Down-alternative fills and natural fiber battings concentrate in Nordic retail channels where thermal performance specifications drive selection.
Bed sheets dominate installed base across hospitality and residential channels. Bath towels are where expansion concentrates as durability certification becomes a procurement gate.
Material:
Cost tier stratification separates premium fiber positioning from mass-market substitution, with regulatory pressure forcing material reformulation at the mid-market level.
- Cotton:Long-staple Egyptian and Pima varieties anchor luxury hospitality specifications for breathability in Mediterranean climates. REACH dye restrictions push Portuguese weavers toward natural indigo alternatives, creating premium positioning for certified organic variants.
- Linen:Belgian and French flax cultivation supports high-end residential positioning with superior moisture-wicking properties for summer-weight bedding.
- Microfiber:Advanced polymer constructions from Guimarães spinning operations yield faster-dry terry with 40% moisture evaporation improvement over cotton.
- Polyester:Blended constructions face pending EU Green Deal microplastic restrictions that threaten existing inventory without biodegradable alternatives at scale.
Cotton commands the dominant material share by volume. Microfiber is climbing the fastest as wrinkle-resistance demand reshapes urban rental procurement.
End User:
Application-specific requirements fragment procurement patterns, with institutional buyers prioritizing lifecycle documentation over unit economics.
- Residential:Individual consumers purchasing through retail and online channels prioritize thread count aesthetics and coordinated collections for master bedroom environments.
- Hospitality:Hotel chains in France and Italy now require documented linen lifecycle data, accelerating replacement demand through sustainability audit compliance.
- Healthcare:German hospital procurement is penetrating antimicrobial copper-infused cotton weaves, displacing synthetic scrubs in patient contact applications.
- Retail:Private-label sourcing for mass-market distribution concentrates in Portuguese textile clusters serving Spanish and Polish fast-fashion home textile brands.
Residential channels dominate transaction volume. Healthcare is where technology differentiation commands pricing power.
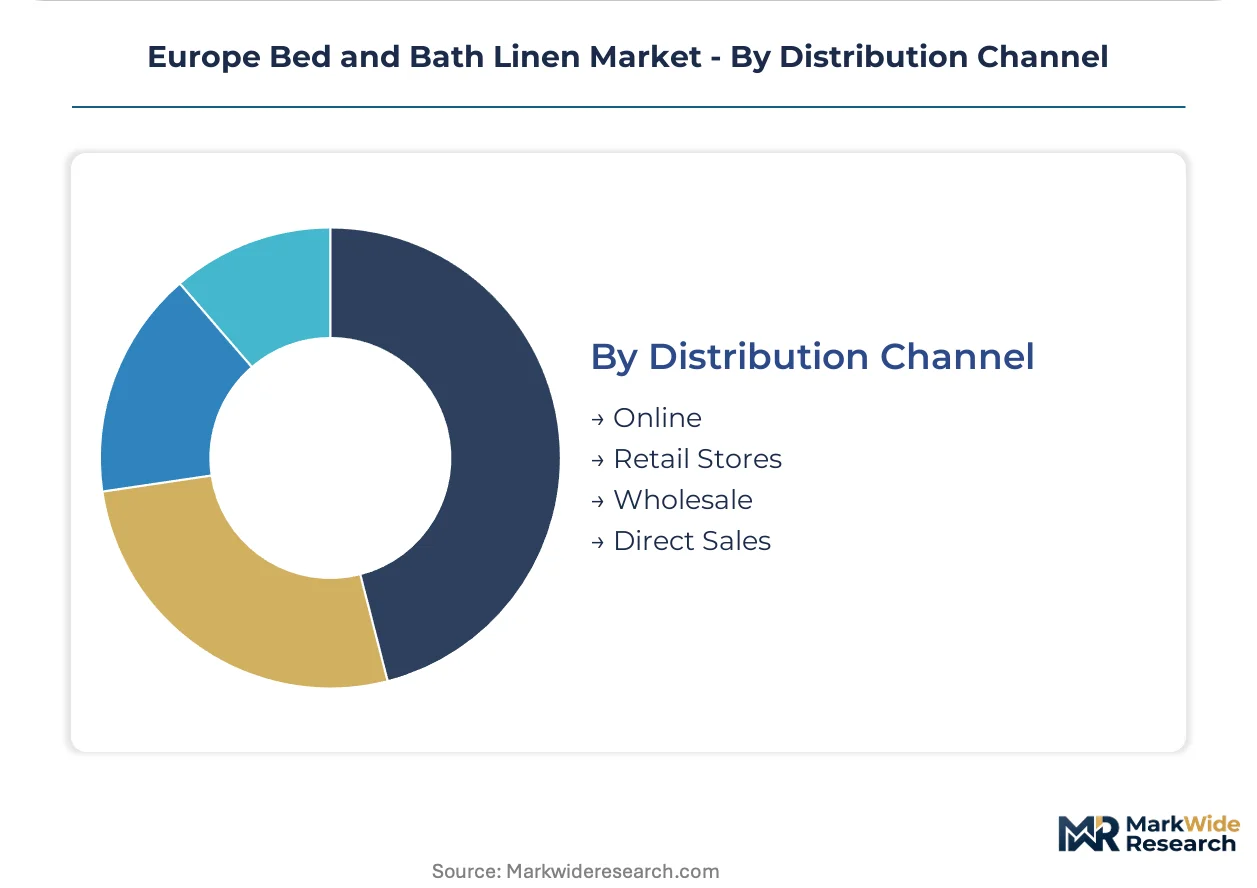
Distribution Channel:
Customer type and geography determine channel selection, with urban concentration favoring platform-based procurement over traditional wholesale relationships.
- Online:Direct-to-consumer platforms aggregate small-batch Portuguese weavers for Copenhagen and Stockholm hotel groups, collapsing lead times from 12 weeks to 4 weeks.
- Retail Stores:France's AGEC anti-waste law mandates recycled content disclosure thresholds, forcing reformulation of polyester-cotton blends or exit from French mass-market channels.
- Wholesale:Traditional distributors face disintermediation across Nordic markets as specialized B2B marketplaces capture boutique hospitality segments.
- Direct Sales:Vertically integrated mills offering blockchain-verified organic certification leverage CSRD-aligned traceability mandates for first-mover advantage in institutional contracting.
Wholesale retains dominant share in hospitality procurement. Online is gaining share fastest as replenishment velocity outweighs volume pricing for boutique operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates with Italian finishers serving luxury hospitality chains, while Portuguese weavers compete on volume-scale efficiency for mid-market European retail. This asymmetry shapes procurement patterns across the continent.
Germany
Hospital procurement drives antimicrobial linen demand as copper-infused cotton weaves displace synthetic alternatives in patient contact applications. REACH compliance costs from ECHA guidelines push reformulation investments. The North Rhine-Westphalia textile belt hosts specialized finishing houses adapting dye chemistry to regulatory timelines.
France
AGEC anti-waste law mandates recycled content disclosure thresholds for all retail textile placement, forcing polyester-cotton blend reformulation or channel exit. Paris-based hotel chains accelerate linen replacement cycles to 18 months under sustainability audit requirements. The Nord-Pas-de-Calais region maintains flax cultivation supporting high-end residential bedding positioning.
Italy
Extended producer responsibility pilots open revenue streams for linen leasing models with integrated industrial laundering. Como and Biella finishing houses concentrate rare REACH-compliant dye formulation expertise among aging specialist workforces. Tuscany-based luxury hospitality suppliers reject mechanical recycling to preserve virgin long-staple hand-feel specifications.
Portugal
The Guimarães textile cluster concentrates high-thread-count cotton weaving capacity for premium European brand supply. Advanced polymer spinning operations yield 600-GSM microfiber terry with accelerated dry times. Chemical recycling partnerships accelerate to maintain French mass-market shelf access under AGEC thresholds.
Sweden
Copenhagen and Stockholm hotel groups source certified linens through specialized B2B marketplaces, collapsing lead times from 12 weeks to 4 weeks. CSRD-aligned traceability mandates create procurement preference for blockchain-verified organic certification. Direct-to-hotel platforms disintermediate traditional wholesale distributors across Nordic boutique hospitality segments.
Europe Bed and Bath Linen Market Competitive Landscape
Concentration sits with integrated spinning-to-retail operators and century-old finishing specialists. The vendor base splits between volume-scale automation players and premium craftsmanship anchors. Two strategic archetypes dominate: vertically integrated mills controlling fiber-to-finished-goods workflows, and heritage finishing houses leveraging proprietary soft-hand chemistry. Competitive moves center on certification timeline compression and circular service model deployment.
Within the heritage craftsmanship tier, Frette anchors luxury hospitality positioning through Italian finishing expertise. Welspun Group represents integrated infrastructure spanning European distribution nodes. Inter IKEA Group exemplifies volume-scale automation compressing lead times for flat-packed home textile bundles. These three occupy distinct competitive lanes without direct overlap.
| Leading Market Players |
|---|
| Tirotex |
| Welspun Group |
| Inter IKEA Group |
| Balsan |
| ESSENZA Home |
| Hennes & Mauritz AB |
| Frette |
| Acton & Acton Limited |
| Ralph Lauren Corporation |
| Others |
Supply & Pricing Matrix
Guimarães weaving cluster capacity utilization above 85 percent anchors European supply concentration and compresses price floors for mid-market terry production. Portuguese scale economies feed directly into hospitality procurement contracts where volume thresholds override unit cost negotiation.
Pricing Analysis
The customization-premium spread separates configured-to-order hospitality linens from standard retail SKUs by 40-60 percent at the invoice level. Three-tier pricing structure across premium, standard, and economy levels dominates, with OEKO-TEX certification tier and thread count specification as primary price differentiation drivers. Pricing pressure stems from Egyptian long-staple cotton input volatility as Nile basin harvest disruptions concentrate cost risk. Boutique hotel chains exhibit lowest price sensitivity, while fast-fashion home textile brands in Poland and Spain face margin compression from AGEC compliance costs.
Supply Chain Analysis
Strait of Gibraltar transit underwrites raw cotton delivery schedules for Portuguese weavers dependent on Egyptian and Brazilian fiber imports. Supply concentrates in Portugal, Italy, and Belgium, with Guimarães terry production, Como finishing expertise, and Belgian flax cultivation anchoring regional capacity. Raw material dependencies center on long-staple cotton, natural indigo dyes, and copper-infused yarn for antimicrobial applications. Single-source vulnerability sits with Egyptian cotton supply as currency instability and climate disruption compound. Distribution runs through specialized B2B marketplaces disintermediating traditional Nordic wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecolabel timeline compression and digital product passport mandates are accelerating competitive disruption across European linen procurement. The regulatory inflection creates first-mover advantage for integrated mills with traceability infrastructure.
For Market Incumbents: Consolidate finishing chemistry expertise at Como and Biella houses before specialist workforce attrition accelerates. Acquire chemical recycling partnerships in Portugal to secure French mass-market shelf access under AGEC thresholds. Dual certification capacity—OEKO-TEX plus EU Ecolabel—defends against 14-month approval cycle delays freezing seasonal collection planning. For New Entrants and Emerging Players: OEKO-TEX fast-track certification programs open boutique hospitality procurement in Copenhagen and Stockholm where lead time compression outweighs volume pricing. Target Nordic direct-to-hotel platforms with blockchain-verified organic cotton positioning. White-space penetration runs through antimicrobial copper-infused weaves for German hospital contracts displacing synthetic alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated mills offering linen leasing models with integrated industrial laundering under Italian extended producer responsibility pilots. Five-to-ten year viability favors Portuguese weavers with chemical recycling partnerships and Guimarães cluster proximity. Watch CSRD-aligned traceability mandate enforcement velocity as inflection indicator for certification-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Portuguese suppliers secure French retail shelf access under AGEC recycled content thresholds. |
| Dual Certification Investment | Simultaneous OEKO-TEX and EU Ecolabel approval compresses product launch timelines for hospitality. |
| Blockchain Traceability Deployment | CSRD-aligned digital product passports create procurement preference among Nordic boutique hotel groups. |
| Antimicrobial Weave Development | Copper-infused cotton penetrates German hospital procurement displacing synthetic patient contact linens. |
| Linen Leasing Model Launch | Italian extended producer responsibility pilots open recurring revenue streams with integrated laundering. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with procurement directors at French and Italian hotel chains, sustainability compliance officers at Portuguese weaving operations, finishing specialists at Como dye houses, and Nordic B2B marketplace operators; and secondary validation against EU ECHA chemical restriction filings, AGEC regulatory texts, OEKO-TEX certification databases, and customs trade data for cotton fiber imports. Bottom-up demand modeling from hospitality replacement cycle data and top-down market sizing from textile production statistics were triangulated for convergence.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, material grade tier, end-user application, and distribution channel complexity. CAGRs were derived from regression analysis against hospitality construction permits, sustainability audit penetration rates, and certification timeline compression effects. Industry-specific inputs included OEKO-TEX approval cycle duration data and REACH dye reformulation cost curves from Portuguese weaver disclosures.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Ecolabel enforcement and stable Egyptian cotton supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as CSRD digital passport requirements and microplastic restriction timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Duvets Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Bed and Bath Linen Market