
 US & Europe Bed Linen and Curtains Market | 2026-2036
US & Europe Bed Linen and Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
US & Europe Bed Linen and Curtains Market Insights
Direct-to-hospitality supply contracts is reconfiguring margin distribution across the value chain, pulling profitability away from wholesale distributors and toward manufacturers with certified production capabilities. Welspun Group leverages its integrated spinning-to-stitching infrastructure to capture this shift in North American hospitality accounts. Indo Count Industries Ltd. anchors its competitive stance through specialized organic cotton bedding lines that command premium positioning in European retail channels. Trident Limited competes on manufacturing scale, operating some of the largest terry towel and bed linen facilities serving mass-market European retailers.
Bed linen and curtains encompass woven textile products designed for sleep environments and window treatments, typically constructed from cotton percale or sateen weaves with thread counts ranging from 200 to 800, and curtain fabrics weighted at 200-400 grams per square meter for light-blocking or decorative performance. These products serve commercial and residential interiors by regulating sleep hygiene, thermal comfort, and aesthetic coherence across hospitality, healthcare, and domestic settings. Cotton bed sheets maintain dominant volume share across both regions due to breathability and laundering durability, while silk and linen materials occupy the fastest-growing premium tier as consumers prioritize natural fiber provenance. The hospitality end-user segment concentrates procurement volume, though residential channels sustain higher per-unit margins through design-style differentiation across modern and minimalist preferences.
EPA textile chemical standards and OEKO-TEX certification frameworks govern product safety and market access across US and European jurisdictions, compelling manufacturers to eliminate restricted substances from dyeing and finishing processes. REACH registration requirements in Europe further constrain synthetic chemical inputs, while state-level California Proposition 65 enforcement in the United States creates additional compliance exposure for formaldehyde-treated fabrics. Stakeholders must monitor evolving Extended Producer Responsibility legislation in France and Germany, which will mandate textile collection and recycling infrastructure investments that reshape cost structures and supplier qualification criteria.
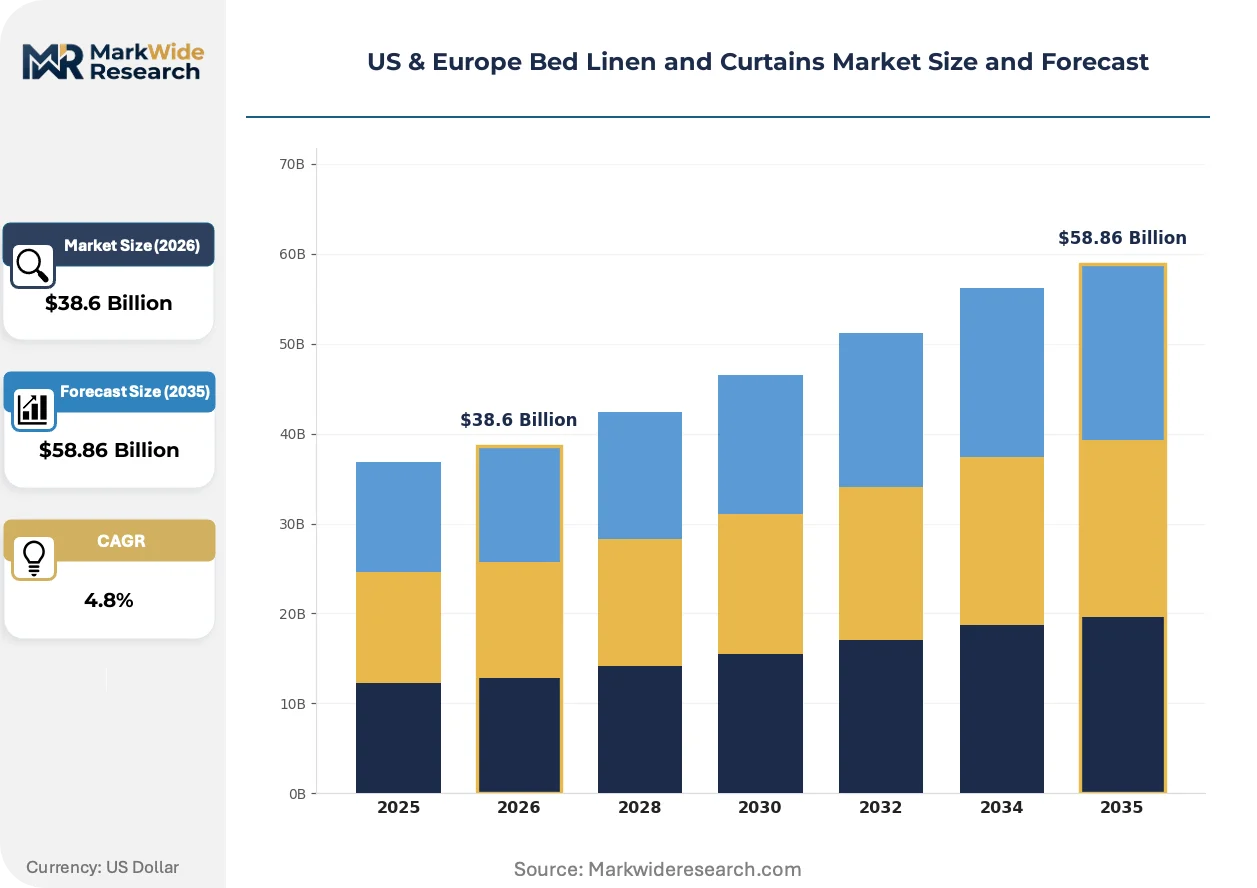
Market Dynamics
REACH registration and OEKO-TEX certification requirements are redirecting capital toward organic cotton processing and closed-loop dyeing infrastructure across European manufacturing bases.
Growth Catalysts
- Post-pandemic hospitality rebound:German and French procurement teams are accelerating linen replacement cycles as occupancy rates recover in premium urban corridors.
- REACH chemical compliance:Manufacturers investing in restricted substance elimination are qualifying for expanded retail shelf placement in EU distribution channels.
- Heritage property renovation wave:London hoteliers are commissioning custom curtain installations for listed building refurbishments, creating specialized demand for high-thread-count woven fabrics.
Market Restraints
- Organic cotton input cost volatility:Weather-dependent harvest yields in Egyptian and Indian growing regions are compressing spinning margins for certified fiber lines.
- Synthetic dye substitution threat:Low-cost polyester-cotton blends from South Asian producers are undercutting natural fiber positioning in mass-market European retail.
- California Proposition 65 enforcement:Formaldehyde-treated fabric shipments face litigation exposure at US ports, creating compliance friction for untreated inventory.
Strategic Opportunities
- Extended Producer Responsibility mandates:France and Germany are legislating textile collection infrastructure that rewards manufacturers with pre-established recycling partnerships.
- Direct-to-hospitality channel expansion:Bypassing wholesale distributors allows certified producers to capture margin previously allocated to intermediaries.
- Healthcare-acquired infection protocols:Antimicrobial finishing technologies are opening institutional procurement channels in UK and US hospital systems.
Industry Challenges
- Closed-loop dyeing capex intensity:Water-recirculation and zero-liquid-discharge systems require eight-figure facility investments that strain mid-tier manufacturer balance sheets.
- Multi-jurisdiction certification timelines:Simultaneous OEKO-TEX, GOTS, and EPA compliance documentation extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US & Europe Bed Linen and Curtains Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Sheets, Pillowcases, Duvets, Curtains Material: Cotton, Polyester, Linen, Silk End User: Residential, Hospitality, Healthcare, Commercial Design Style: Modern, Traditional, Minimalist, Rustic |
| Companies Covered | Keeco, Inc., Town & Country Living, Welspun Group, Indo Count Industries Ltd., Trident Limited, Himatsingka Seide, 1888 Mills, LLC, YTML (Yunus Mills), Natco Home, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US & Europe Bed Linen and Curtains Market Trends and Innovations
Digital textile printing and waterless coloration processes are compressing traditional wet-processing timelines while enabling micro-batch customization for hospitality specification.
Closed-loop dyeing systems are collapsing water consumption benchmarks in European finishing facilities. Italian and Portuguese textile houses are retrofitting existing plants with membrane filtration and salt-recovery modules. This technology is collapsing the cost gap between small-batch custom coloration and mass-production economics.
REACH SVHC candidate list expansion is forcing reformulation of flame-retardant curtain treatments across EU member states. Manufacturers are substituting phosphorus-based chemistry for halogenated compounds in public building specifications. Hospitality procurement in Germany and France now requires full material disclosure documentation extending to auxiliary chemical inputs.
Buyer concentration among consolidated hospitality groups is compressing supplier negotiation leverage. Marriott and Hilton procurement consortiums are mandating unified sustainability scorecards that privilege multi-site contract awards. This concentration is most visible in London and Paris metropolitan corridors where heritage renovation projects require single-source accountability for fabric performance warranties.
US & Europe Bed Linen and Curtains Market Segmentation
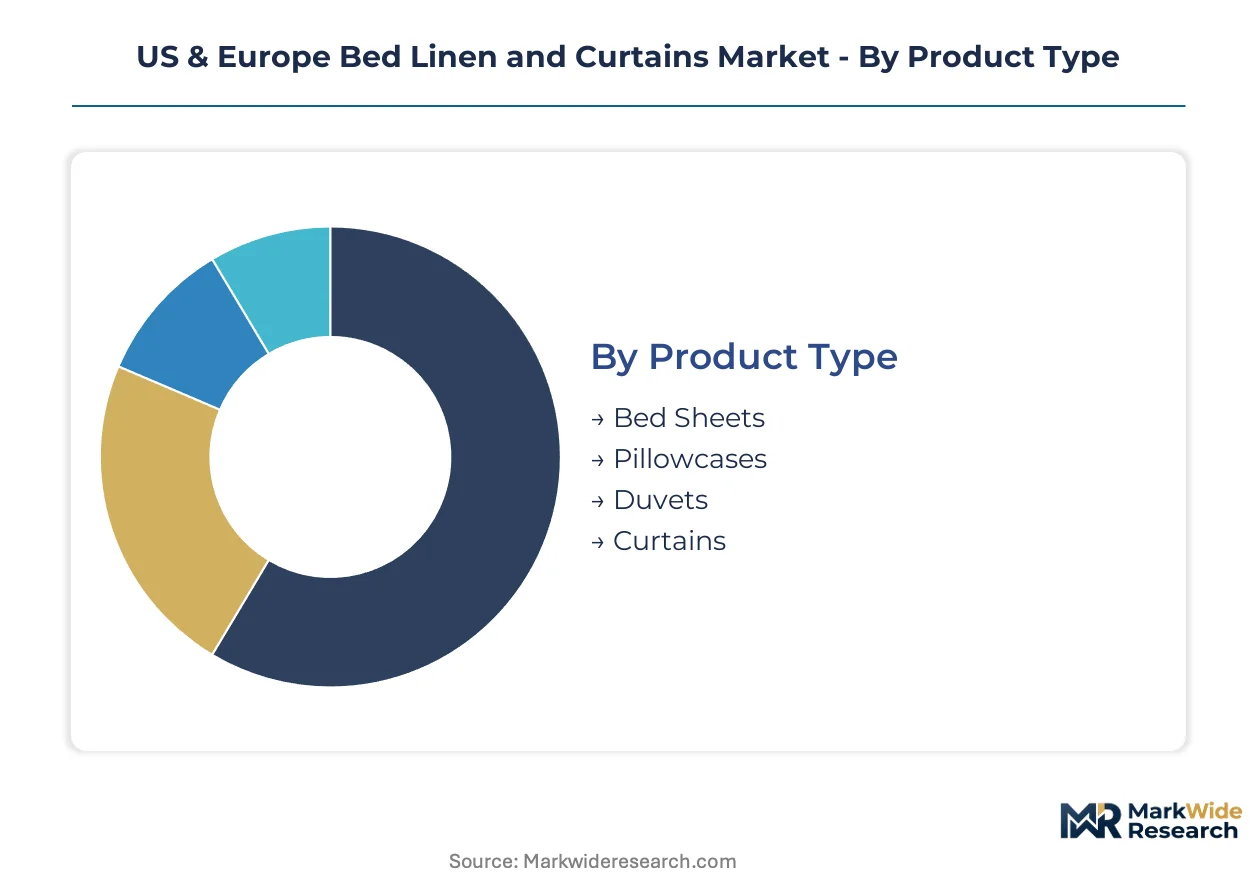
Segmentation in the US & Europe Bed Linen and Curtains Market reveals distinct procurement patterns across hospitality, healthcare, and residential channels. Material certification requirements and design specifications vary sharply by end-use, directing manufacturer investment toward specialized production lines.
Product Type:
Use-case spectrum spans sleep surfaces, protective encasements, thermal layers, and window treatments with divergent performance specifications.
- Bed Sheets:Cotton percale and sateen weaves with thread counts from 200 to 800 serve high-frequency laundering environments. German and French hospitality procurement teams prioritize 300-400 thread count lines for replacement cycle standardization.
- Curtains:Fabrics weighted at 200-400 grams per square meter deliver light-blocking or decorative performance. London heritage property renovations are driving demand for custom woven installations with fire-retardant treatments compliant with REACH SVHC requirements.
- Pillowcases:Envelope and housewife constructions in matching sheet specifications complete bedding ensembles. Healthcare-acquired infection protocols in UK hospital systems are expanding antimicrobial-finished pillowcase procurement.
- Duvets:Insulated covers and inserts regulate thermal comfort across seasonal demand cycles. Down-alternative fills are displacing natural down in EU markets due to animal welfare compliance documentation requirements.
The dominant share belongs to Bed Sheets, while Curtains is closing the gap fastest.
Material:
Cost tier stratification separates certified organic inputs from commodity synthetics, with margin capture concentrated at the premium tier.
- Cotton:Breathable cellulose fibers maintain laundering durability across commercial and residential applications. Egyptian and Indian organic cotton harvest volatility is compressing spinning margins for certified GOTS lines serving European retail channels.
- Polyester:Synthetic polymer fibers deliver cost efficiency and wrinkle resistance for mass-market positioning. South Asian producers are undercutting natural fiber pricing in European discount retail through polyester-cotton blend substitution.
- Linen:Bast fibers from flax stalks provide superior moisture wicking and textural character. French and Belgian linen mills are capturing heritage positioning in US premium residential channels.
- Silk:Protein filament fibers occupy luxury tier with hypoallergenic and temperature-regulating properties. Mulberry silk pillowcases are expanding in UK wellness retail driven by dermatological positioning.
Cotton commands volume leadership, though Linen is expanding most quickly in premium positioning.
End User:
Customer type determines certification burden, contract structure, and margin distribution across the value chain.
- Hospitality:High-volume procurement with standardized specifications and unified sustainability scorecards. Marriott and Hilton consortiums are mandating OEKO-TEX certification for multi-site contract awards in London and Paris corridors.
- Residential:Design-style differentiation supports higher per-unit margins through aesthetic curation. German and French consumers are prioritizing organic cotton provenance in direct-to-consumer online channels.
- Healthcare:Institutional procurement channels require antimicrobial finishing and barrier protection documentation. UK and US hospital systems are adopting EPA-compliant textile protocols for infection control.
- Commercial:Office and public building specifications emphasize flame-retardant performance and durability warranties. REACH-compliant phosphorus-based treatments are displacing halogenated compounds in EU public sector tenders.
Hospitality retains procurement volume concentration, while Healthcare is gaining share fastest through institutional specification expansion.
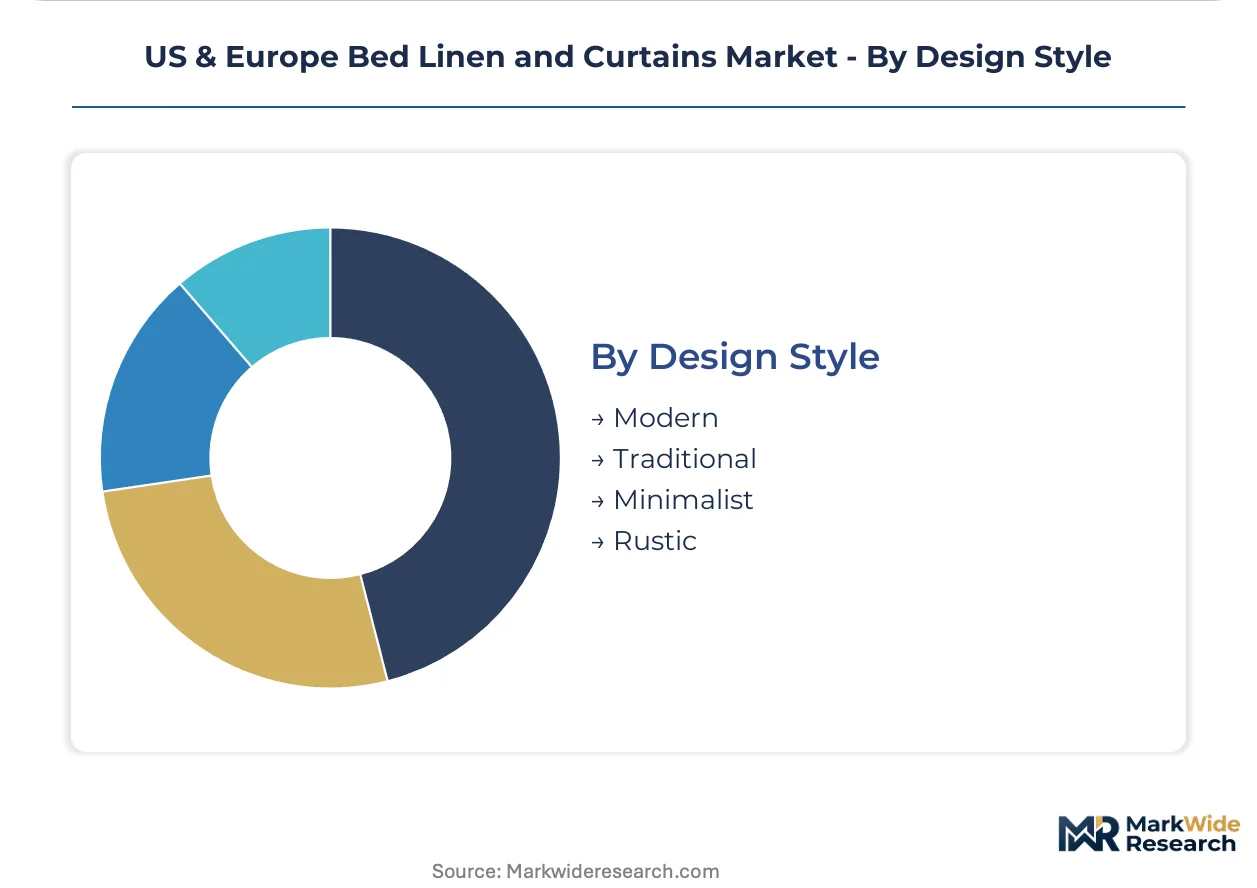
Design Style:
Application context drives aesthetic segmentation, with hospitality and residential channels diverging in trend adoption timelines.
- Modern:Clean lines and neutral palettes align with contemporary hospitality refurbishment cycles. London hoteliers are specifying geometric patterns and solid color blocking for urban property positioning.
- Minimalist:Reduced visual complexity and monochromatic schemes emphasize material quality over ornamentation. Scandinavian-influenced residential demand in Germany and France favors unbleached organic cotton and natural linen textures.
- Traditional:Ornate patterns and rich color saturation serve heritage property authenticity requirements. UK country house hotels are commissioning custom curtain installations with historical pattern reproduction.
- Rustic:Textured weaves and earth-toned palettes reference artisanal production methods. Portuguese and Italian textile houses are marketing small-batch rustic lines to US boutique hospitality accounts.
Modern styling holds the largest installed base, though Minimalist is climbing the fastest in new construction and renovation specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the US and Europe, with American hospitality chains prioritizing high-frequency replacement durability while European procurement emphasizes certified organic provenance and heritage design authenticity.
United States
Marriott and Hilton procurement consortiums drive volume concentration through unified sustainability scorecards mandating OEKO-TEX certification for multi-site awards. EPA textile chemical standards and California Proposition 65 enforcement create compliance friction for formaldehyde-treated inventory at West Coast ports. The Southeast manufacturing corridor, particularly Georgia and North Carolina textile clusters, processes cotton inputs for institutional hospitality contracts.
Germany
Post-pandemic hospitality rebound accelerates linen replacement cycles as occupancy rates recover in premium urban corridors. Extended Producer Responsibility legislation mandates textile collection infrastructure investments that reshape supplier qualification criteria. The North Rhine-Westphalia industrial basin hosts retrofitting operations for closed-loop dyeing systems with membrane filtration modules.
United Kingdom
London hoteliers commission custom curtain installations for heritage property renovations, creating specialized demand for high-thread-count woven fabrics with fire-retardant treatments. NHS procurement protocols expand antimicrobial-finished textile adoption for healthcare-acquired infection control. The Midlands manufacturing region supplies institutional bedding to hospital systems and hospitality groups.
France
REACH SVHC candidate list expansion forces reformulation of flame-retardant curtain treatments in public building specifications. Procurement teams prioritize full material disclosure documentation extending to auxiliary chemical inputs. The Hauts-de-France textile cluster specializes in phosphorus-based chemistry substitution for halogenated compounds in EU tender compliance.
Italy
Portuguese and Italian textile houses market small-batch rustic lines to US boutique hospitality accounts seeking artisanal production differentiation. Digital textile printing adoption compresses traditional wet-processing timelines while enabling micro-batch customization. The Como silk district maintains premium positioning for luxury residential channel supply.
US & Europe Bed Linen and Curtains Market Competitive Landscape
Capability concentration sits with integrated spinning-to-stitching specialists; scale advantage sits with mass-market terry towel and bed linen fabricators. The vendor base organizes around three strategic archetypes: certified organic cotton specialists commanding premium retail positioning, vertically integrated hospitality contractors capturing direct-to-hotel margins, and regional wholesale distributors facing margin compression from channel disintermediation. Dominant competitive moves include backward integration into captive cotton spinning and strategic partnerships with recycling infrastructure operators ahead of Extended Producer Responsibility mandates.
Among India-based integrated textile groups, Welspun Group, Indo Count Industries Ltd., and Trident Limited exemplify divergent competitive positioning. Welspun occupies the hospitality-direct tier through spinning-to-stitching infrastructure. Indo Count anchors the certified organic premium segment for European retail channels. Trident represents scale-driven mass-market supply serving high-volume European retail procurement. These three fabricators illustrate how certification investment, vertical scope, and production scale create non-overlapping competitive territories.
| Leading Market Players |
|---|
| Keeco, Inc. |
| Town & Country Living |
| Welspun Group |
| Indo Count Industries Ltd. |
| Trident Limited |
| Himatsingka Seide |
| 1888 Mills, LLC |
| YTML (Yunus Mills) |
| Natco Home |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in South Asian spinning mills is compressing contract negotiation leverage for European and North American buyers, pushing procurement teams toward long-term offtake agreements that lock in organic cotton premiums while suppliers absorb dye-house retrofit costs to maintain OEKO-TEX qualification.
Pricing Analysis
Long-term offtake contracts dominate hospitality procurement, with Marriott and Hilton consortiums mandating multi-year volume commitments that standardize per-unit costs across replacement cycles. Price differentiation rests on GOTS certification tier and thread-count grade, with 600-plus count lines commanding substantial premiums in heritage renovation specifications. Cost compression in mass-market polyester-cotton blends is intensifying because South Asian producers are flooding European discount retail with untreated inventory. Healthcare systems exhibit lowest price sensitivity due to infection-control protocol mandates, while residential direct-to-consumer channels face acute pressure from private-label substitution.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated spinning-to-stitching operators in India, Pakistan, and Turkey, where Welspun Group and Indo Count Industries Ltd. hold captive dye-house capacity. Raw material dependencies draw from Egyptian long-staple cotton, Indian organic fiber harvests, and Belgian flax inputs for linen specialization. Single-source vulnerability in GOTS-certified organic cotton creates exposure to weather-driven yield volatility across Indian growing regions. Distribution runs through direct-to-hospitality channels that bypass wholesale intermediaries, with certified producers capturing margin previously allocated to distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic fiber substitution threatens natural fiber positioning as polyester-cotton blend pricing undercuts certified organic premiums in mass-market European retail, forcing incumbents to defend provenance-based value propositions.
For Market Incumbents:Insulate margin position through backward integration into captive Egyptian cotton spinning and pre-emptive recycling infrastructure partnerships ahead of French and German Extended Producer Responsibility enforcement. Certification investment in simultaneous OEKO-TEX and GOTS documentation creates switching costs that lock hospitality procurement teams into qualified supplier bases.
For New Entrants and Emerging Players:Mid-market healthcare-acquired infection protocols in UK and US hospital systems represent the most penetrable entry point, with antimicrobial finishing specialization opening institutional procurement channels underserved by legacy hospitality suppliers. Direct contracting with NHS procurement committees bypasses distributor concentration that blocks retail channel access.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across closed-loop dyeing retrofit requirements, favoring acquisition targets with pre-installed membrane filtration and salt-recovery modules. Vertically integrated operators with spinning-to-stitching scope and established recycling partnerships offer superior long-term viability through regulatory compliance moats. Quarterly review of REACH SVHC candidate list expansions is advised to detect inflection in flame-retardant chemistry substitution requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Dyeing Retrofit | Water-recirculation installations in Portuguese and Italian finishing houses collapse environmental compliance costs for EU market access. |
| Direct-to-Hospitality Channel Expansion | Bypassing wholesale distributors allows certified producers to capture margin from Marriott and Hilton consortium procurement. |
| Antimicrobial Finishing Certification | EPA-compliant textile protocols unlock NHS and US hospital system procurement for infection-control applications. |
| Recycling Infrastructure Partnership | Pre-established textile collection networks qualify manufacturers for French and German Extended Producer Responsibility incentives. |
| Heritage Custom Installation Capability | Micro-batch digital printing enables London hoteliers to commission pattern-matched curtain installations for listed building renovations. |
Research Methodology
Operator-level perspectives from hospitality procurement directors, textile plant managers, OEKO-TEX certification auditors, and healthcare materials managers anchored the qualitative base, cross-referenced with customs trade data, REACH registration filings, SEC textile sector disclosures, and hospitality sustainability scorecard publications. Bottom-up volume estimates from individual manufacturing facilities were triangulated against top-down consumption models derived from replacement cycle analysis and heritage renovation pipeline tracking.
Scenario-bracketing around organic cotton harvest volatility and REACH SVHC expansion timelines structured the analytical framework across the analysis window, with segmentation modeling spanning material grade tier, end-user channel, certification status, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and procurement cycle normalization assumptions, incorporating hospitality occupancy recovery trajectories and healthcare protocol adoption curves as industry-specific demand inputs.
Practitioners should monitor Egyptian and Indian cotton yield forecasts, REACH candidate list publication schedules, and California Proposition 65 enforcement actions for early signals requiring forecast revision. Quarterly review of hospitality group sustainability scorecard updates and Extended Producer Responsibility implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Duvets Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Organic Bed Linen Market