
 Organic Bed Linen Market | 2026-2036
Organic Bed Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Bed Linen Market Analytics
Subscription-based textile refresh programs is broadening how organic bed linen reaches consumers. Coyuchi leverages a circular commerce model with take-back and renewal services. Boll & Branch anchors its positioning through direct-to-consumer channel control and transparent farm-to-finish sourcing. Parachute Home differentiates through design-forward aesthetics paired with certified organic material claims.
Organic bed linen comprises bedding textiles manufactured from fibers cultivated without synthetic pesticides, herbicides, or genetically modified organisms, typically processed under Global Organic Textile Standard protocols that restrict chemical inputs and mandate water treatment standards. The primary commercial purpose is to serve consumers and institutions seeking reduced chemical exposure and verifiable environmental accountability in sleep environments. Sheets dominate residential volume while duvet covers command premium positioning in boutique hospitality procurement. Organic cotton sustains the largest material share though linen fiber is gaining traction in climate-adaptive bedding applications.
GOTS, Oeko-Tex Standard 100, and EU Green Deal due diligence frameworks collectively define product legitimacy and market access across European and North American retail channels. The EU AI Act's supply chain documentation requirements are extending traceability obligations from fiber origin through finished goods distribution. Health Canada and EPA chemical restriction precedents influence formulation choices for dyes and finishes in cross-border commerce. Stakeholders must monitor how evolving certification harmonization between GOTS and national organic programs reshapes supplier qualification and inventory segmentation strategies.
Market Dynamics
EU Green Deal sustainability mandates and the EU AI Act's supply chain traceability provisions are forcing manufacturers to restructure fiber sourcing, dye chemistry, and documentation workflows across European distribution channels.
Growth Catalysts
- GOTS Certification Mandates:Boutique hospitality chains in Portugal and Greece now require certified organic linen procurement to meet EU Green Deal compliance, creating guaranteed demand pools for verified suppliers.
- Germany's Premium Residential Segment:Consumers in this market prioritize Oeko-Tex and GOTS-labeled bedding, concentrating purchasing power toward certified producers with transparent farm-to-finish documentation.
- Subscription-Based Textile Refresh Programs:Circular commerce models with take-back and renewal services are expanding addressable market reach beyond traditional retail purchase cycles.
Market Restraints
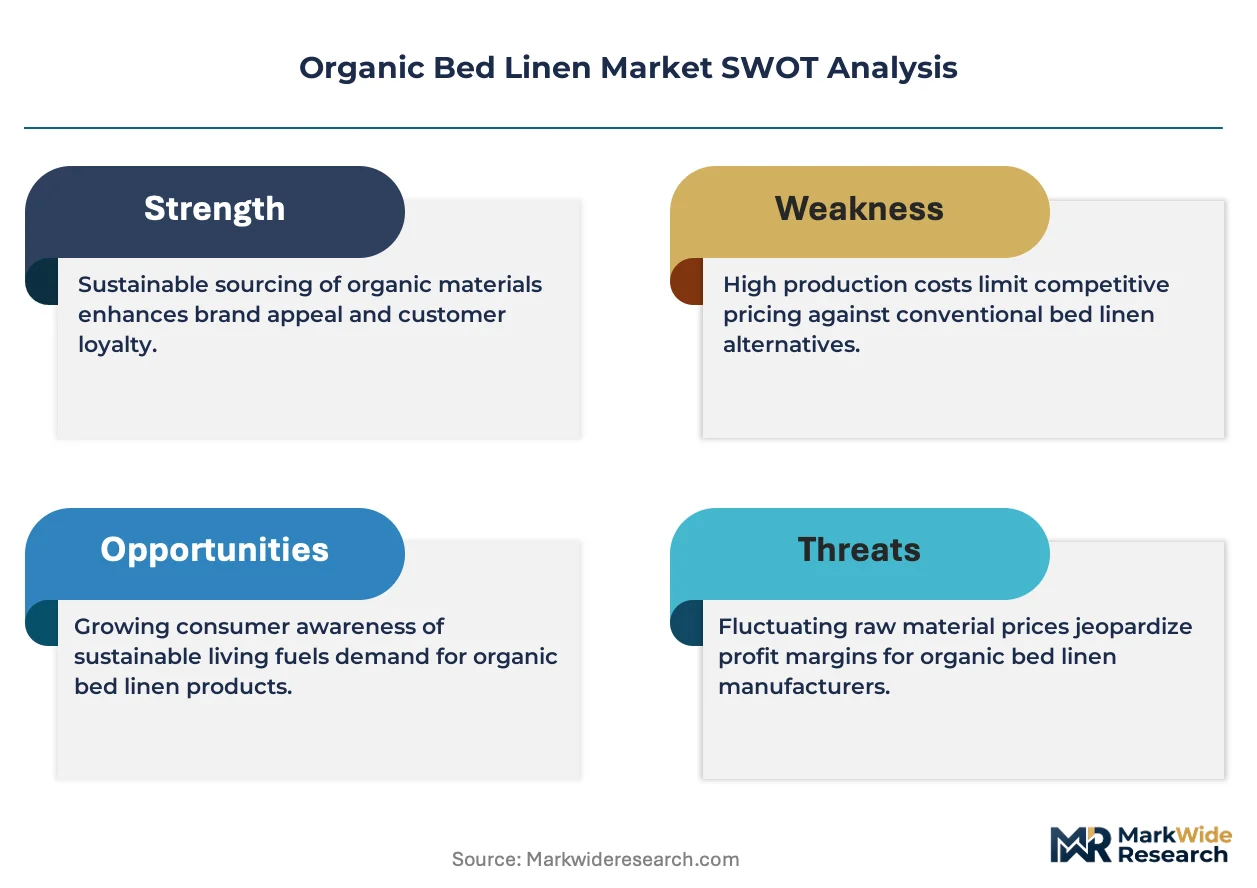
- Organic Cotton Input Cost Volatility:Weather-sensitive fiber yields and limited certified acreage create pricing instability that compresses manufacturer margins during supply contractions.
- GOTS Certification Timeline Friction:Multi-stage audit processes and annual renewal requirements delay market entry for new suppliers, concentrating supply among incumbent certified producers.
- Conventional Linen Substitution Threat:Non-certified flax bedding marketed as "natural" captures price-sensitive consumers unwilling to pay organic premiums without regulatory enforcement.
Strategic Opportunities
- Climate-Adaptive Linen Fiber Applications:Linen's moisture-wicking and thermoregulation properties are gaining traction in Mediterranean and subtropical markets where cooling bedding commands premium positioning.
- EU AI Act Documentation Requirements:Supply chain traceability mandates create competitive moats for manufacturers with pre-existing fiber-origin tracking systems and blockchain-verified provenance.
- Direct-to-Consumer Channel Control:Bypassing wholesale intermediaries enables transparent pricing communication and margin capture for certified organic claims that resist commoditization.
Industry Challenges
- Water Treatment Infrastructure Capex:GOTS-mandated effluent processing requires substantial capital investment in dyehouse facilities, particularly for mid-scale manufacturers serving mixed conventional-organic production.
- Harmonization Between GOTS and National Organic Programs:Divergent certification requirements across export markets force inventory segmentation and dual-label production runs that complicate supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Bed Linen Market |
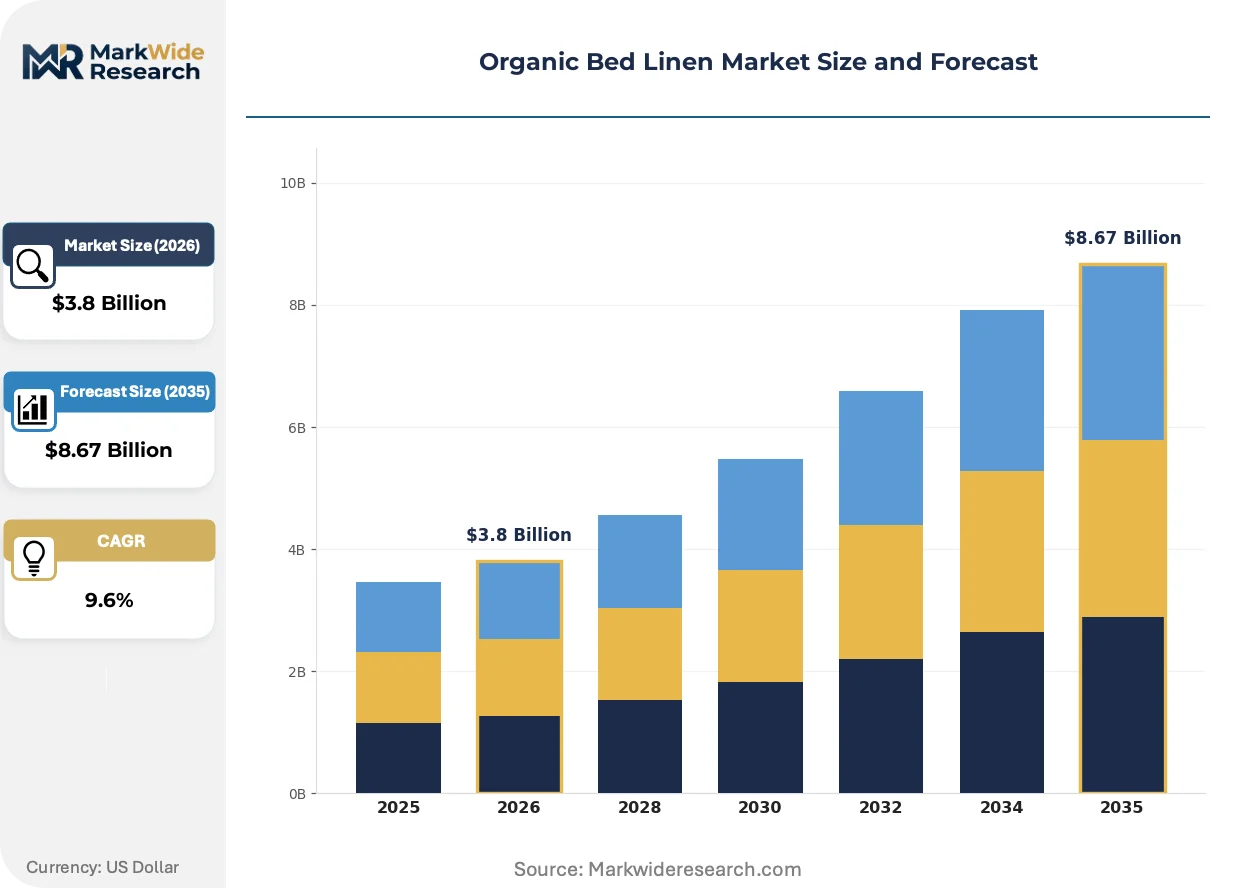
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Pillowcases, Duvet Covers, Bed Spreads Material: Organic Cotton, Linen, Bamboo, Hemp End User: Residential, Hotels, Healthcare Facilities, Eco-Resorts Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale |
| Companies Covered | AKP TEX, Coyuchi, Boll & Branch, Parachute Home, Good Night Naturals, Magnolia Organics, L.L.Bean, Alva Linen, The Company Store, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Bed Linen Market Evolving Landscape
Digital traceability infrastructure and circular service models are displacing traditional linear production-consumption cycles in organic textile commerce. These shifts compress certification verification timelines while expanding asset utilization through product-life extension.
Blockchain-enabled fiber provenance tracking is automating documentation compliance for EU AI Act supply chain disclosure requirements. German retailers and hospitality procurement teams are piloting these systems to compress audit preparation from weeks to hours. The technology is automating supplier qualification workflows that previously required manual certificate verification and third-party laboratory testing.
REACH chemical restriction expansions and the EU Green Deal due diligence framework are mandating dye and finish reformulation across European distribution channels. Manufacturers serving Germany, France, and the Netherlands must eliminate specific azo dyes and formaldehyde-based finishes previously common in conventional textile processing. The regulatory pressure is most acute in children's bedding and healthcare hospitality segments where skin-contact safety standards are strictest.
Certification-driven preference consolidation is reshaping residential purchasing patterns in premium urban markets. Consumers in Berlin, Munich, and Hamburg now treat GOTS and Oeko-Tex labels as minimum hygiene factors rather than differentiators, forcing uncertified competitors toward price-driven positioning or exit. This behavioral shift is most visible in online direct-to-consumer channels where label scanning and third-party verification tools enable instant competitive comparison.
Organic Bed Linen Market Segmentation
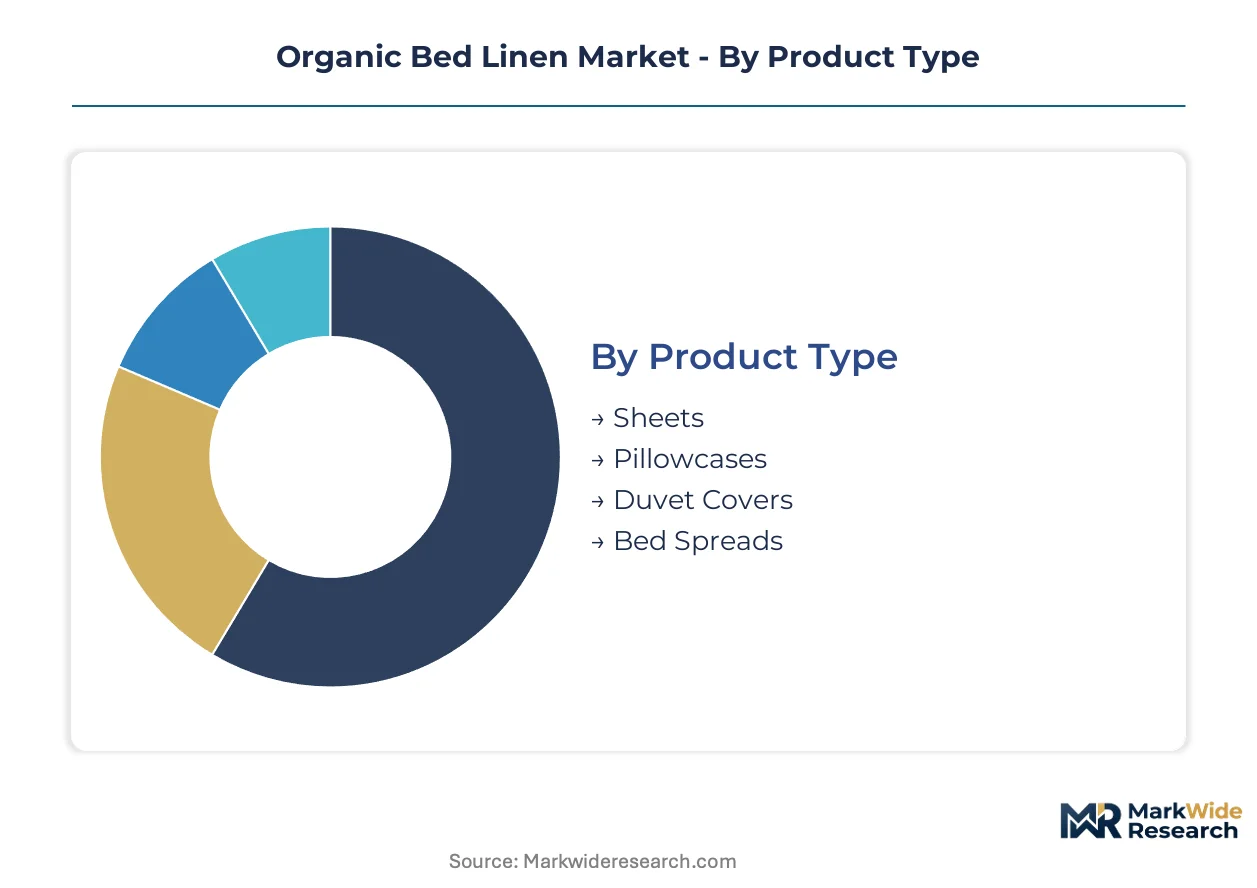
Organic bed linen manufacturers must navigate divergent certification thresholds, fiber performance profiles, and procurement workflows across residential and institutional buyers. Segmentation reveals where GOTS compliance creates pricing power versus where conventional alternatives erode margins.
Product Type:
Fabric construction and dimensional specifications determine replacement frequency and margin capture across sleep environments.
- Sheets:Flat and fitted constructions in percale or sateen weaves constitute the highest-volume residential purchase. German urban consumers treat GOTS and Oeko-Tex labels as baseline hygiene factors, forcing uncertified competitors toward price-driven positioning.
- Duvet Covers:Envelope or button closures in higher thread counts command premium positioning in boutique hospitality procurement across Portugal and Greece. EU Green Deal sustainability mandates now require certified organic linen for contract eligibility.
- Pillowcases:Standard and king-size enclosures follow sheet purchase cycles with lower individual price points but equivalent certification requirements.
- Bed Spreads:Quilted and woven top-layer coverings serve decorative and thermal functions in climate-adaptive bedding applications across Mediterranean markets.
Mature deployment sits with Sheets. Newer deployment is concentrated in Bed Spreads as climate-adaptive applications expand.
Material:
Fiber origin and cultivation protocols create tiered sustainability credentials that reshape supplier qualification.
- Organic Cotton:Cultivated without synthetic pesticides or GMOs under GOTS protocols that restrict chemical inputs and mandate water treatment standards. Weather-sensitive yields and limited certified acreage create pricing instability that compresses manufacturer margins during supply contractions.
- Linen:Flax fiber delivers moisture-wicking and thermoregulation properties gaining traction in Mediterranean and subtropical markets. REACH chemical restriction expansions and EU Green Deal due diligence frameworks mandate dye reformulation for European distribution.
- Bamboo:Cellulosic fiber derived from grass pulp offers rapid renewability but faces certification ambiguity around chemical processing methods in viscose production.
- Hemp:Bast fiber with low water requirements and minimal pesticide needs attracts sustainability-focused positioning though limited softening infrastructure constrains premium applications.
Established volume concentrates in Organic Cotton. Emerging positioning favors Linen as cooling bedding claims gain regulatory scrutiny.
End User:
Procurement authority and compliance obligation intensity vary sharply across buyer categories.
- Residential:Individual consumers in Germany's premium segment prioritize Oeko-Tex and GOTS-labeled bedding with transparent farm-to-finish documentation. Certification-driven preference consolidation is most visible in online direct-to-consumer channels.
- Hotels:Boutique hospitality chains in Portugal and Greece require certified organic linen procurement to meet EU Green Deal compliance. Blockchain-enabled fiber provenance tracking is automating documentation for these procurement teams.
- Healthcare Facilities:Skin-contact safety standards are strictest in children's bedding and healthcare hospitality segments. REACH chemical restrictions eliminate specific azo dyes and formaldehyde-based finishes previously common in conventional processing.
- Eco-Resorts:Sustainability-themed properties use certified organic claims as core brand differentiation, accepting premium pricing for verified supply chains.
Contracted demand anchors in Hotels. Discretionary expansion is concentrated in Eco-Resorts as experiential travel positioning intensifies.
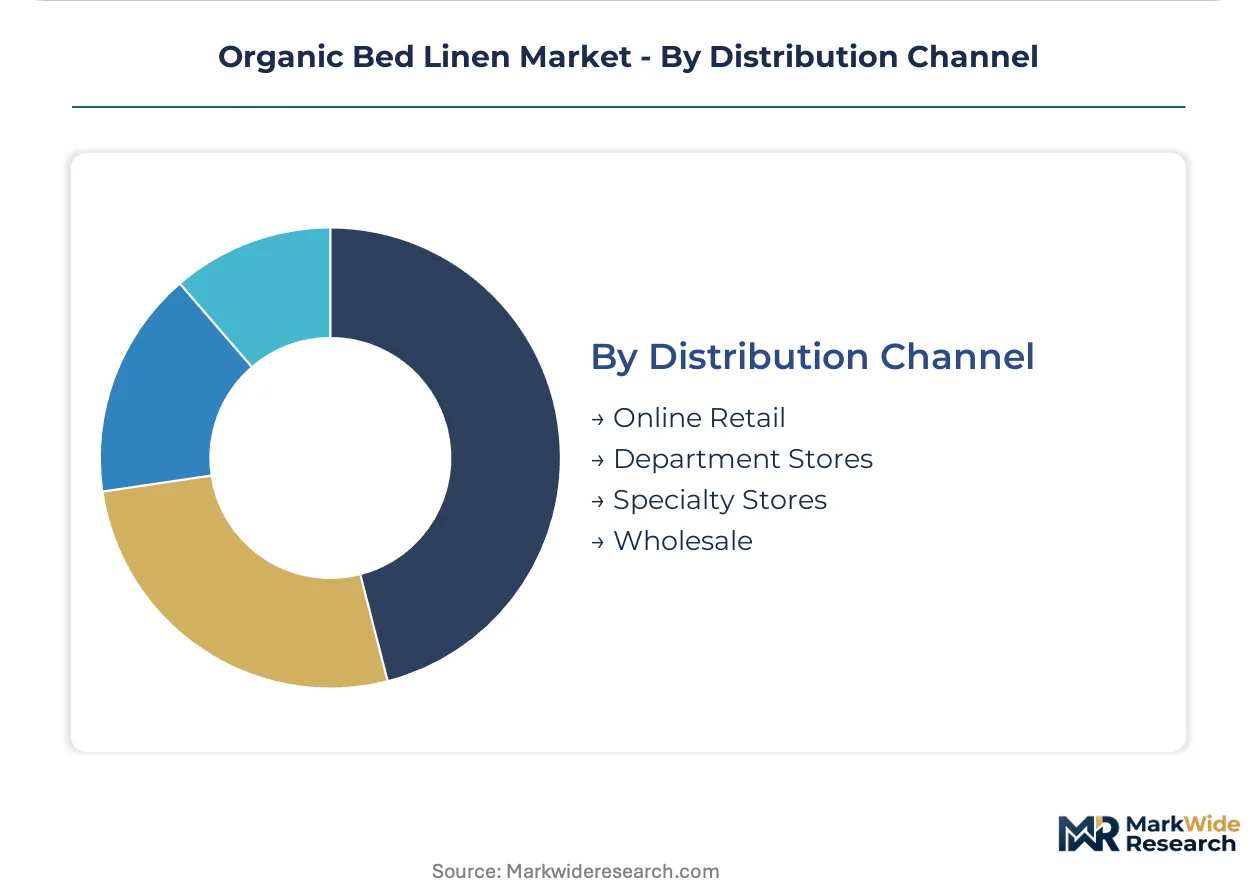
Distribution Channel:
Channel control determines margin retention and certification narrative authority.
- Online Retail:Direct-to-consumer platforms enable transparent pricing communication and margin capture for certified organic claims. Label scanning and third-party verification tools enable instant competitive comparison.
- Specialty Stores:Curated assortments in urban centers like Berlin, Munich, and Hamburg consolidate purchasing power toward certified producers with physical certificate verification.
- Department Stores:Multi-brand environments force inventory segmentation and dual-label production runs that complicate supply chain planning across divergent certification requirements.
- Wholesale:Intermediary-dominated channels erode margin capture and obscure farm-to-finish transparency that resists commoditization.
Margin protection concentrates in Online Retail. Volume scale persists in Wholesale despite transparency constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic cotton cultivation concentrates in India and Turkey while premium consumption clusters in Germany and the United States, creating a geographic disconnect between fiber origin and finished goods demand.
Germany
Berlin, Munich, and Hamburg consumers treat GOTS and Oeko-Tex labels as baseline hygiene factors for residential bedding purchases. ECHA's REACH chemical restrictions eliminate specific azo dyes and formaldehyde-based finishes from children's bedding and healthcare hospitality segments. Bavaria's premium retail clusters consolidate purchasing power toward certified producers with transparent farm-to-finish documentation.
United States
Direct-to-consumer channel control enables transparent pricing communication and margin capture for certified organic claims that resist commoditization. EPA chemical restriction precedents influence formulation choices for dyes and finishes in cross-border commerce. California's design-forward residential markets anchor subscription-based textile refresh program adoption.
Portugal
Boutique hospitality chains in Lisbon and the Algarve require certified organic linen procurement to meet EU Green Deal compliance, creating guaranteed demand pools for verified suppliers. The EU AI Act's supply chain traceability provisions extend documentation obligations from fiber origin through finished goods distribution. Porto-based textile manufacturers pilot blockchain-enabled fiber provenance tracking to automate audit preparation.
Greece
Island eco-resorts and Athens boutique hotels expand certified organic linen procurement to satisfy EU Green Deal sustainability mandates for contract eligibility. Climate-adaptive linen fiber applications gain traction in Mediterranean markets where cooling bedding commands premium positioning. Thessaloniki's hospitality procurement teams leverage digital traceability infrastructure to compress supplier qualification timelines.
India
Weather-sensitive organic cotton yields and limited certified acreage create pricing instability that compresses manufacturer margins during supply contractions. The country's national textile regulator enforces GOTS-mandated effluent processing standards for export-oriented dyehouse facilities. Gujarat and Maharashtra industrial clusters concentrate fiber cultivation and early-stage processing for European and North American distribution channels.
Organic Bed Linen Market Competitive Landscape
Top-tier vendors anchor premium positioning through direct-to-consumer channel control and transparent farm-to-finish sourcing, while mid-scale producers compete on GOTS certification speed and regional hospitality contract capture. The vendor base stratifies across three archetypes: circular commerce specialists with take-back and renewal services, design-forward direct brands pairing aesthetics with certified material claims, and legacy textile houses retooling for organic compliance. Dominant competitive moves include strategic partnerships with blockchain traceability providers and backward integration into certified fiber sourcing to secure supply continuity.
Within the circular commerce archetype, Coyuchi exemplifies subscription-based renewal service models that extend product lifecycle value. Among direct-to-consumer specialists, Boll & Branch and Parachute Home occupy positions where channel control enables margin retention and certification narrative authority. These three entities represent distinct strategic vectors—circular service innovation, transparent sourcing anchoring, and design-led premium positioning—that collectively define competitive differentiation in certified organic bedding.
| Leading Market Players |
|---|
| AKP TEX |
| Coyuchi |
| Boll & Branch |
| Parachute Home |
| Good Night Naturals |
| Magnolia Organics |
| L.L.Bean |
| Alva Linen |
| The Company Store |
| Others |
Value Network & Pricing Analysis
Organic cotton futures volatility cascades through GOTS-certified dyehouse facilities into three-tier pricing structure across premium, standard, and economy levels, with India-origin fiber premiums compressing mid-scale manufacturer margins while German and Portuguese hospitality buyers absorb certified organic markups through EU Green Deal compliance budgets.
Pricing Analysis
Margin tightening in mid-tier residential bedding traces to weather-sensitive organic cotton yields and limited certified acreage in Gujarat and Maharashtra. Price differentiation hinges on GOTS certification tier and transparent farm-to-finish documentation, with direct-to-consumer channels capturing premium positioning while wholesale intermediaries erode margin retention. Cost-down pressure on economy-tier conventional linen substitutes accelerates because non-certified flax bedding marketed as "natural" siphons price-sensitive consumers without regulatory enforcement. Boutique hospitality procurement in Portugal and Greece demonstrates least price sensitivity, while German urban residential buyers treat certification labels as baseline hygiene factors that resist commoditization premiums.
Supply Chain Analysis
Returns and renewal flows from Coyuchi's circular commerce model compress replacement cycles while extending asset utilization through blockchain-verified provenance documentation. Supply concentrates in India, Turkey, and Portugal, with fiber cultivation anchored in Gujarat organic cotton clusters and finishing stages distributed across Porto-based GOTS-certified dyehouses. Raw material dependencies rest on azo dye reformulation under REACH restrictions, GOTS-mandated water treatment chemistry, and linen fiber softening infrastructure. Single-source vulnerability sits with limited certified organic cotton acreage exposed to monsoon variability. Distribution runs through direct-to-consumer platforms and specialty retail in Berlin, Munich, and Hamburg, bypassing wholesale margin erosion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into certified fiber sourcing and captive dyehouse capacity defines competitive positioning in this market, with upstream control over GOTS-verified supply chains separating viable players from margin-compressed alternatives.
For Market Incumbents: Deepen control over India-origin organic cotton procurement through long-term grower contracts and captive ginning capacity. Incumbents must defend against conventional linen substitution by accelerating blockchain traceability deployment for EU AI Act compliance, while expanding climate-adaptive linen fiber processing infrastructure to capture Mediterranean cooling bedding premiums. For New Entrants and Emerging Players: EU AI Act supply chain traceability provisions in Portugal and Greece open a window for digital-native entrants with pre-existing fiber-origin tracking systems. New players should target boutique hospitality procurement in Lisbon and Algarve with subscription-based textile refresh programs, leveraging automated documentation workflows to compress supplier qualification timelines against incumbent audit friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale GOTS-certified manufacturers with underutilized dyehouse capacity in Porto and Thessaloniki industrial clusters. Long-term viability hinges on water treatment infrastructure capex completion and harmonization between GOTS and national organic program alignment. Investors should monitor EU Green Deal due diligence framework enforcement intensity as inflection indicator for certified organic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Sourcing | Captive organic cotton supply from Gujarat and Maharashtra clusters secures margin protection against weather-driven input volatility. |
| Blockchain-Enabled Provenance Tracking Deployment | Automated documentation compresses EU AI Act audit preparation from weeks to hours for Portuguese hospitality procurement teams. |
| Climate-Adaptive Linen Fiber Capacity Expansion | Moisture-wicking processing infrastructure captures premium positioning in Mediterranean and subtropical cooling bedding segments. |
| Direct-to-Consumer Channel Control | Bypassing wholesale intermediaries enables transparent pricing communication and margin retention for GOTS-certified claims. |
| Circular Commerce Service Model Launch | Take-back and renewal programs extend product lifecycle value while expanding addressable market beyond traditional retail cycles. |
Research Methodology
Independent corroboration across GOTS certification databases, EU customs trade records, and ECHA REACH restriction filings underwrites the qualitative findings. Primary interviews with textile procurement directors at Portuguese boutique hotel chains, GOTS audit supervisors in Porto, and category buyers at Berlin specialty retailers combined with secondary validation from organic cotton futures exchanges and EU Green Deal implementation trackers. Bottom-up fiber cultivation estimates and top-down finished goods consumption patterns triangulate market sizing.
Rate-of-change decomposition across material type, end-user segment, and distribution channel dimensions structures the analytical framework. Modeled segments span organic cotton, linen, bamboo, and hemp materials; residential, hotel, healthcare, and eco-resort end users; and online retail, specialty store, department store, and wholesale channels. CAGRs derive from fiber yield projections, certification penetration curves, and hospitality procurement contract visibility throughout the forecast period. Climate-adaptive bedding demand and subscription service adoption velocity constitute textile-specific forecast inputs.
Caveats apply where organic cotton yield shocks, GOTS-national organic program harmonization delays, or EU AI Act enforcement intensity variations could materially shift the outlook. Practitioners should monitor ECHA chemical restriction expansions and monsoon pattern anomalies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Duvets Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Table Linen Market