
 United Kingdom Bed and Bath Linen Market | 2026-2036
United Kingdom Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Bed and Bath Linen Market Analytics
Hospitality buyers are unwinding the historical dominance of residential consumers in UK linen expenditure. Dunelm Group plc leverages its vertically integrated sourcing network to maintain price competitiveness across mid-market bedding. John Lewis Partnership plc anchors its position through premium private-label collections that emphasize British manufacturing heritage. Marks & Spencer Group plc differentiates via rapid replenishment capabilities that reduce lead times for hospitality contract accounts.
Bed and bath linen encompasses woven and knitted textile products manufactured from natural and synthetic fibers, with thread counts typically ranging from 200 to 800 for cotton bedding and GSM ratings of 400–700 for terry towels, serving hygiene, comfort, and interior decoration functions across residential and commercial environments. Cotton bedding occupies the largest revenue pool due to established consumer preference for breathability and durability, while microfiber towels represent the fastest-expanding material segment as budget hospitality operators prioritize rapid-drying properties and lower laundering costs. The eco-friendly feature category is capturing margin concentration as UK retailers impose minimum recycled-content thresholds on suppliers.
Trading Standards enforces the Textile Products (Labelling and Fibre Composition) Regulations 2012, which mandate fiber content disclosure and restrict misleading environmental claims on linen packaging. BSI Kitemark certification shapes procurement criteria for NHS healthcare linen contracts, requiring validated durability and infection-control performance. REACH compliance administered by the Health and Safety Executive restricts chemical finishes in dyes and coatings, elevating compliance costs for imported polyester bedding. Stakeholders must monitor how forthcoming UK carbon-border adjustments on textile imports reshape competitive dynamics between domestic mills and Asian suppliers.
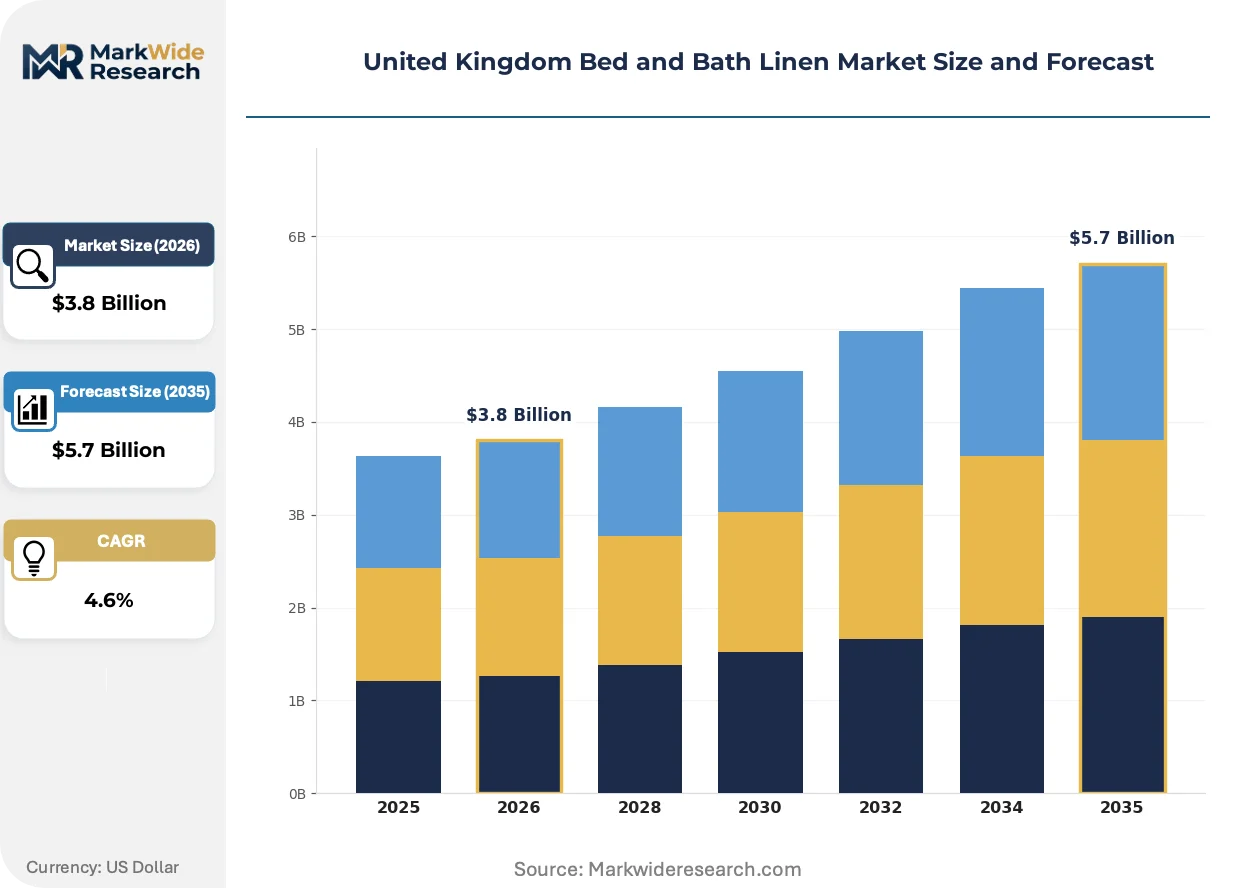
Market Dynamics
The United Kingdom's Extended Producer Responsibility regulations for textiles are forcing wholesale restructuring of sourcing networks, as mills must now account for end-of-life collection costs in their pricing models and contract terms.
Growth Catalysts
- Extended Producer Responsibility:The UK's EPR framework mandates textile waste accountability, creating compliance-driven demand for traceable supply chains and certified recycled-content products among hospitality procurement teams.
- Luxury serviced apartments:Greater London's premium residential hospitality segment is expanding linen replacement frequencies and quality specifications, pulling spend toward higher-thread-count cotton bedding.
- Microfiber terry technology:Rapid-drying synthetic towel formulations are displacing cotton in budget hotel chains, reducing laundering energy costs and inventory requirements.
Market Restraints
- REACH compliance costs:The Health and Safety Executive's chemical finish restrictions on imported polyester bedding elevate testing and certification expenses for Asian suppliers serving UK contracts.
- Cotton price volatility:Raw fiber input costs fluctuate with climate-driven harvest uncertainty in major producing regions, compressing margin predictability for UK retailers.
- Healthcare certification barriers:BSI Kitemark requirements for NHS linen contracts create technical qualification hurdles that exclude smaller mills without validated durability testing infrastructure.
Strategic Opportunities
- Scottish textile heritage revival:Underpenetrated positioning for premium linen woven in Scottish mills offers differentiation against mass-market imports in boutique hospitality channels.
- Carbon border adjustment preparation:Upcoming UK import levies on textile carbon intensity create first-mover advantage for domestic mills investing in renewable energy-powered production.
- Direct-to-hospitality digital platforms:Bypassing traditional wholesale distribution, specialized e-procurement portals enable contract account customization with shorter lead times.
Industry Challenges
- Textile chemist scarcity:Formulation expertise for compliant dye and finish development is concentrating among aging specialist workforces, constraining product innovation pipelines.
- Legacy ERP integration:Hospitality buyers' procurement systems require expensive custom API development to connect with supplier traceability platforms mandated by EPR reporting.
- Recycled fiber certification lag:Third-party verification capacity for post-consumer content claims is insufficient to match retailer-mandated minimum thresholds, delaying contract approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Bed and Bath Linen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Towels, Curtains, Mattresses Material: Cotton, Linen, Polyester, Microfiber Feature: Cooling, Hypoallergenic, Eco-Friendly, Water-Resistant End User: Residential, Hospitality, Healthcare, Commercial |
| Companies Covered | Dunelm Group plc, John Lewis Partnership plc, Marks & Spencer Group plc, IKEA Ltd (UK), The White Company, Peter Reed International Limited, Victoria Linen Ltd., Ralph Lauren Corporation, Serta Simmons Bedding LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Bed and Bath Linen Market Evolving Landscape
Digital traceability infrastructure and material science advances are compressing traditional supply chain hierarchies, while regulatory compliance is becoming a product feature rather than a back-office function.
Blockchain-enabled fiber provenance tracking is miniaturizing the documentation burden for EPR compliance, embedding batch-level origin data directly into QR-coded care labels. Boutique hotel procurement teams are mandating this capability for contract renewals, treating traceability as a brand integrity asset. The technology is miniaturizing audit costs previously absorbed by dedicated compliance departments, shifting verification to automated scanning at point of receipt.
REACH chemical restrictions administered by the Health and Safety Executive are eliminating certain formaldehyde-based crease-resistant finishes from polyester bedding imports. Mills serving UK contracts must reformulate with citric acid cross-linking alternatives that reduce wrinkle resistance durability. Premium hospitality segments are absorbing higher per-unit costs, while budget operators are shortening replacement cycles to compensate for performance degradation.
Hospital procurement consortia are consolidating linen purchasing through framework agreements that unbundle after-sales inventory management from product supply. NHS Supply Chain's national contracts now specify vendor-managed stock levels with penalty clauses for availability failures. This concentration is most visible in England's acute trust networks, where three-year agreements are displacing fragmented local purchasing.
United Kingdom Bed and Bath Linen Market Segmentation
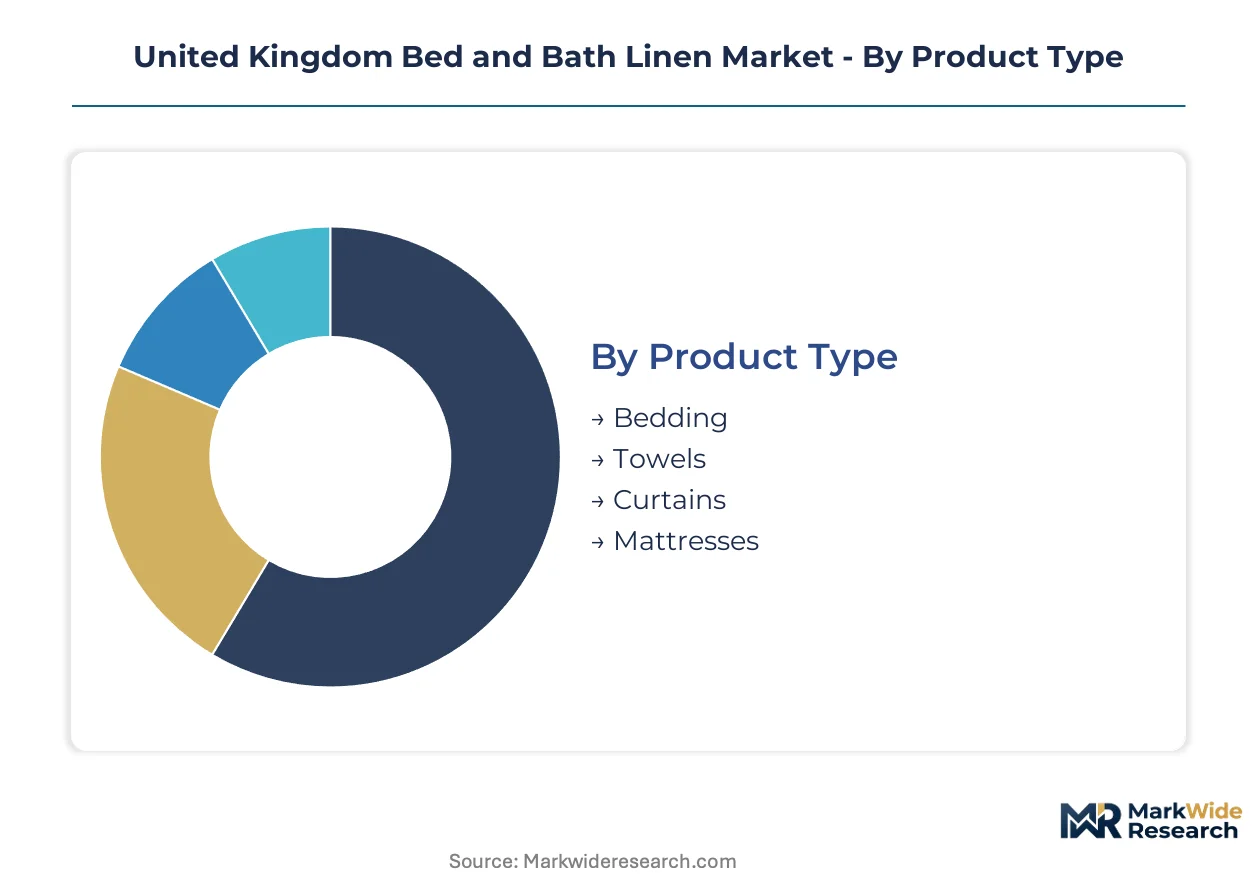
Segmentation in the United Kingdom bed and bath linen market reveals how procurement priorities diverge between domestic hospitality contracts and export-oriented retail channels. Understanding these splits enables suppliers to align manufacturing capacity with the compliance requirements and replacement cycles dominant in each slice.
Product Type:
Domestic production concentrates on bedding and towels serving UK hospitality chains, while curtains and mattresses draw more heavily on imported components from European and Asian suppliers.
- Bedding:Woven and knitted textile products spanning sheets, duvet covers, and pillowcases with thread counts from 200 to 800. Demand concentrates in Greater London's luxury serviced apartment sector, where operators specify higher-thread-count cotton for premium positioning against international competitors.
- Towels:Terry cloth and flat-woven absorbent textiles rated by GSM density for absorbency and durability. Microfiber formulations are displacing cotton in budget hotel chains across Manchester and Birmingham, reducing laundering energy costs and inventory holding requirements.
- Curtains:Decorative and blackout window treatments manufactured from blended fabrics. Residential renovation activity in the Southeast drives replacement demand.
- Mattresses:Support surfaces with textile ticking and integrated bedding systems. Hospitality procurement teams in Scotland are extending replacement cycles to manage capital expenditure.
Bedding holds the largest share; momentum sits with towels as rapid-dry technology penetrates mid-market hospitality.
Material:
Cost tiers separate premium natural fibers from synthetic alternatives, with compliance costs under REACH and Extended Producer Responsibility reshaping margin structures across each tier.
- Cotton:Natural cellulosic fiber prized for breathability and moisture wicking, processed into percale or sateen weaves. Scottish mills anchor premium positioning through heritage branding for boutique hospitality channels in Edinburgh and the Highlands.
- Microfiber:Synthetic filaments below one denier creating rapid-drying, lightweight textiles. Budget operators in England's regional hotel chains prioritize this material for reduced laundry cycle times and lower water consumption.
- Polyester:Petroleum-derived synthetic fiber offering wrinkle resistance and dimensional stability. REACH compliance costs for chemical finishes elevate testing expenses for Asian suppliers.
- Linen:Bast fiber from flax plants delivering superior thermoregulation and texture variation. Artisan production in Northern Ireland serves niche premium residential demand.
Cotton retains the dominant position; microfiber is climbing the fastest as operational efficiency pressures intensify in hospitality procurement.
Feature:
Application requirements drive feature selection, with healthcare and hospitality buyers imposing divergent performance specifications that segment supplier capabilities.
- Eco-Friendly:Products incorporating certified recycled content, organic fiber sourcing, or end-of-life recyclability. UK retailer minimum thresholds for post-consumer content are accelerating supplier qualification bottlenecks.
- Hypoallergenic:Treatments and fiber selections minimizing dust mite penetration and irritant retention. NHS procurement consortia mandate this capability for acute care contracts.
- Cooling:Phase-change materials or moisture-wicking constructions regulating sleep temperature. Residential demand in Southern England's warmer counties supports premium pricing.
- Water-Resistant:Barrier treatments protecting underlying surfaces from fluid penetration. Commercial end-users in food service and elder care specify these for liability reduction.
Eco-Friendly holds the largest share; momentum sits with Hypoallergenic as healthcare certification barriers concentrate contract awards.
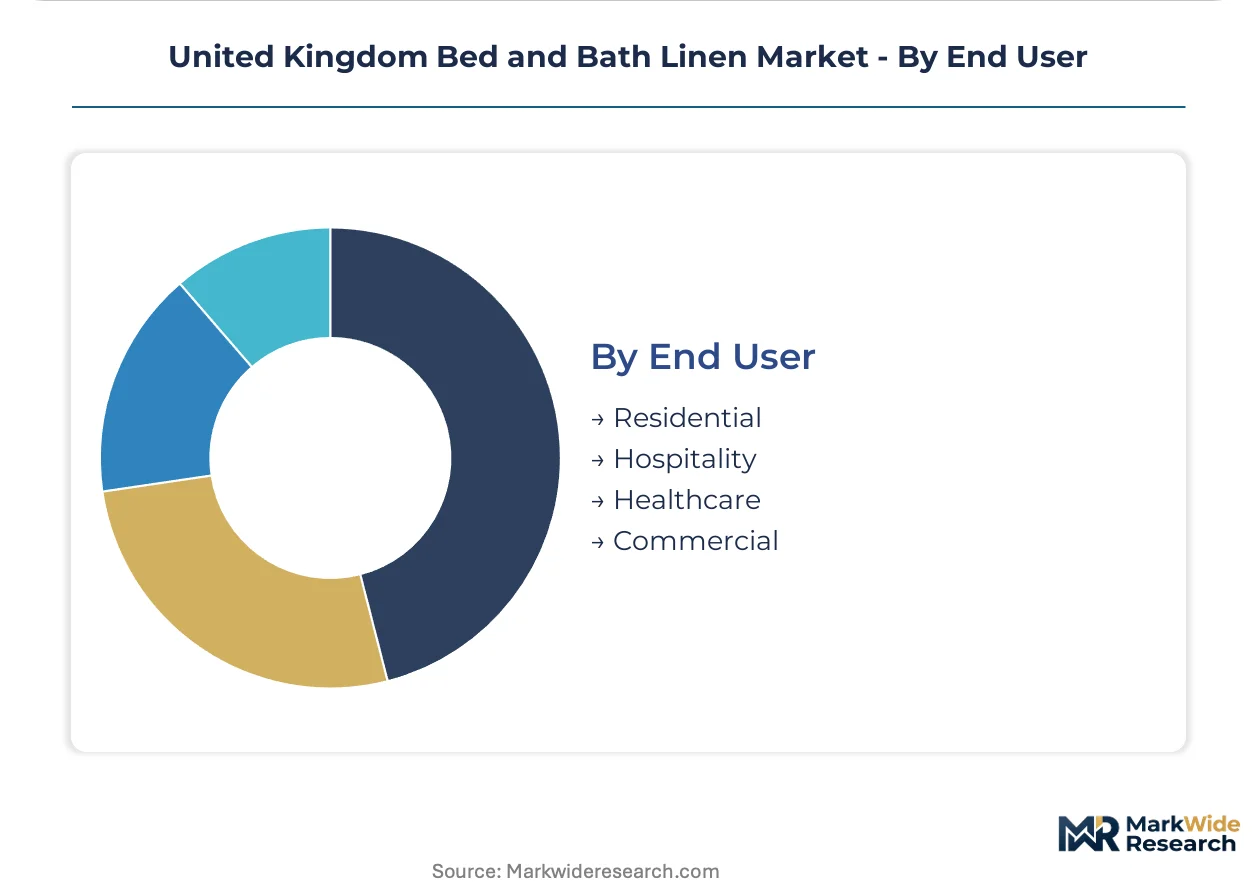
End User:
Customer type determines volume scale and customization intensity, with hospitality buyers consolidating purchasing power while residential channels fragment across distribution formats.
- Hospitality:Hotels, serviced apartments, and short-term rental operators purchasing on contract cycles with specified durability testing. Greater London's premium residential hospitality segment is expanding replacement frequencies and quality specifications.
- Residential:Individual consumers purchasing through retail, direct-to-consumer, or interior design channels. Dunelm Group plc anchors mid-market penetration through vertically controlled sourcing.
- Healthcare:NHS trusts and private hospital operators requiring BSI Kitemark certification for infection control and validated durability. Framework agreements are consolidating purchasing through national contracts.
- Commercial:Corporate offices, educational institutions, and food service establishments with standardized procurement requirements. Budget constraints favor synthetic blends with shorter replacement cycles.
Residential holds the largest share; hospitality is gaining share fastest as procurement teams unwind historical consumer dominance in UK linen expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement teams dominate UK linen expenditure patterns, with replacement cycles and quality specifications varying sharply across England's regional hotel markets, Scotland's heritage textile corridors, and Wales's emerging manufacturing zones.
London and the Southeast
Luxury serviced apartments in Greater London command premium cotton bedding with thread counts exceeding 600, driving margin concentration in high-end supply chains. Trading Standards enforces the Textile Products Regulations 2012 across this dense commercial corridor. Croydon and Slough host distribution hubs where hospitality buyers consolidate procurement through vendor-managed inventory agreements.
Midlands
Budget hotel chains in Birmingham and Manchester prioritize microfiber towels for reduced laundry cycle times and lower water consumption. REACH compliance administered by the Health and Safety Executive elevates testing costs for polyester bedding imports through Midlands ports. Leicester's textile heritage cluster is repurposing mill infrastructure for rapid-dry synthetic production.
Scotland
Boutique hospitality channels in Edinburgh and the Highlands specify heritage-branded linen from Scottish mills for differentiation against mass-market imports. The Scottish Environment Protection Agency coordinates with UK-wide Extended Producer Responsibility frameworks. Hawick and the Scottish Borders anchor premium positioning through artisan weaving traditions.
Wales
Emerging manufacturing investment in South Wales targets carbon-border-adjustment readiness through renewable energy-powered production. Natural Resources Wales implements textile waste accountability protocols aligned with UK EPR mandates. Cardiff's logistics infrastructure supports just-in-time replenishment for hospitality contract accounts.
Northern Ireland
Artisan linen production from flax cultivation serves niche premium residential demand concentrated in Belfast and surrounding counties. Northern Ireland Environment Agency enforces fiber content disclosure requirements. Lisburn's textile mills specialize in thermoregulating bast fiber products for discerning consumer segments.
United Kingdom Bed and Bath Linen Market Competitive Landscape
Player mix skews toward vertically integrated mid-market retailers with captive sourcing networks. Concentration is moderate, with three domestic holding companies controlling significant shelf space and contract hospitality relationships. Strategic archetypes separate heritage-positioned premium specialists from scale-driven rapid-replenishment operators and direct-to-hospitality digital platforms. Competitive moves center on backward integration into textile manufacturing and API development for procurement system connectivity.
Among UK-based retailers, Dunelm Group plc, John Lewis Partnership plc, and Marks & Spencer Group plc occupy positions that exemplify distinct competitive vectors. Dunelm represents vertically controlled sourcing efficiency across mid-market bedding. John Lewis anchors premium private-label positioning through British manufacturing heritage associations. Marks & Spencer exemplifies rapid replenishment capabilities that compress lead times for hospitality contract accounts. These three entities sit within a structure where procurement consolidation favors operators with traceability infrastructure and EPR-compliant supply chains.
| Leading Market Players |
|---|
| Dunelm Group plc |
| John Lewis Partnership plc |
| Marks & Spencer Group plc |
| IKEA Ltd (UK) |
| The White Company |
| Peter Reed International Limited |
| Victoria Linen Ltd. |
| Ralph Lauren Corporation |
| Serta Simmons Bedding LLC |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above eighty percent at Pakistani and Bangladeshi spinning mills are compressing raw cotton pricing power upstream while elevating minimum order quantities for UK hospitality buyers. This scale concentration simultaneously reinforces contract-based procurement and squeezes margin flexibility for mid-market retailers lacking backward integration into yarn production.
Pricing Analysis
Cost-plus contracts with cotton futures indexation dominate hospitality procurement, insulating buyers from spot volatility while locking suppliers into thin conversion margins. Three-tier pricing structure across premium, standard, and economy levels separates BSI Kitemark-certified healthcare linen from rapid-replenishment hospitality stock and unbranded retail basics. Price differentiation hinges on certification grade and volume scale, with NHS framework agreements commanding steeper discounts than boutique hotel orders. Pricing pressure stems from REACH compliance testing costs elevating landed costs for Asian polyester bedding, with budget operators absorbing compression through shortened replacement cycles.
Supply Chain Analysis
Inventory compression to under forty-five days of forward cover is reshaping replenishment economics as hospitality buyers mandate vendor-managed stock agreements with penalty clauses for availability failures. Raw cotton draws from Pakistan, India, and Uzbekistan, while finished textile manufacturing concentrates in Bangladesh, Turkey, and Portugal for UK-bound hospitality contracts. Supply chain risk centers on single-source vulnerability for Egyptian long-staple cotton grades specified in luxury serviced apartment contracts. Distribution runs through Croydon and Slough consolidation hubs serving Greater London's dense hospitality corridor, with direct mill-to-property drops bypassing wholesale tiers for national hotel chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
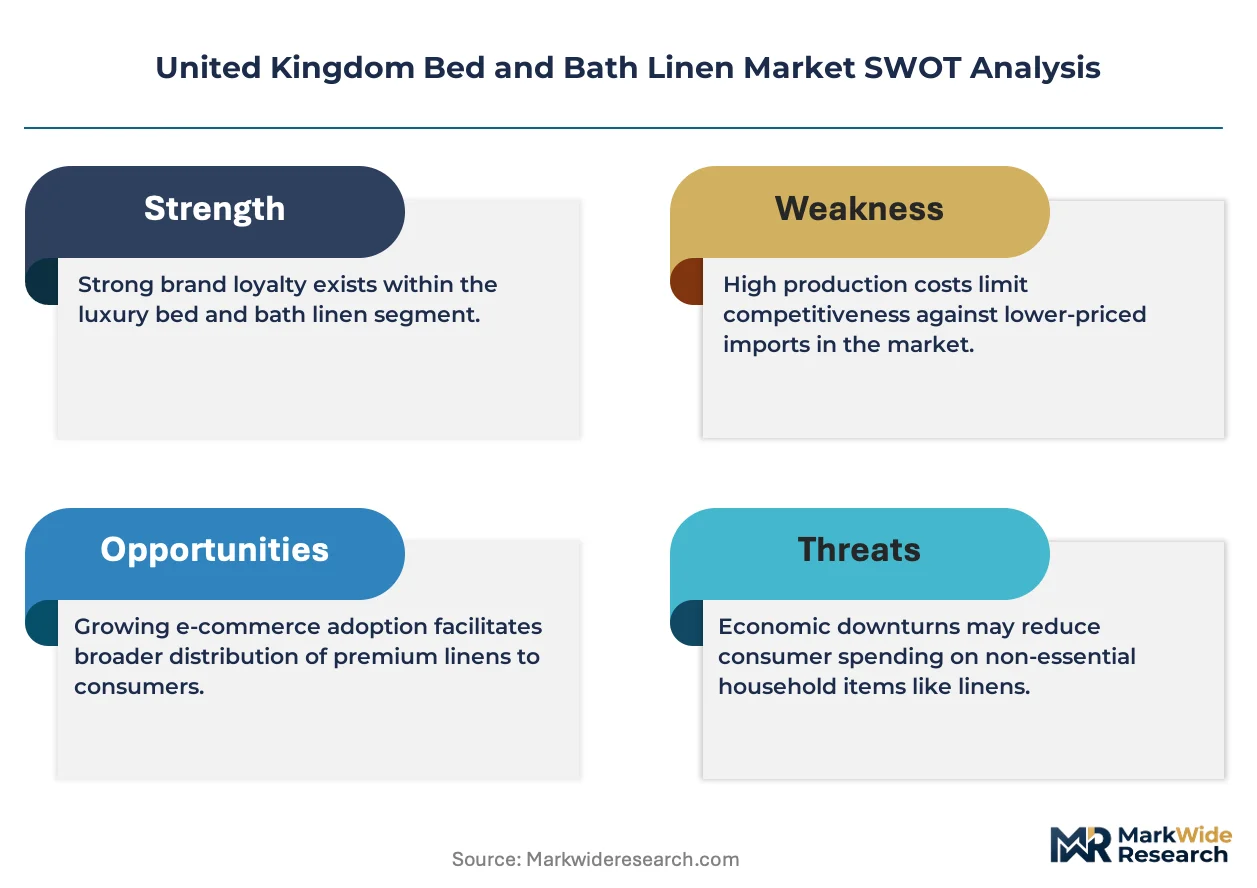
Analyst Recommendations
Extended Producer Responsibility compliance deadlines are accelerating procurement system overhauls, creating early-cycle expansion tailwinds for traceability infrastructure vendors and certified recycled-content suppliers ahead of mandatory reporting thresholds.
For Market Incumbents: Secure EPR-compliant traceability platforms through API integration with hospitality buyers' legacy ERP systems, defending contract renewal rates against digital-native entrants. Prioritize captive supply of Scottish heritage-branded linen to boutique channels where artisan positioning commands sustainable premiums. Carbon-border-adjustment readiness through renewable energy sourcing represents the critical lever for margin defense against Asian import competition. For New Entrants and Emerging Players: Anchor in direct-to-hospitality digital platforms bypassing wholesale distribution, exploiting fragmented local purchasing in England's regional hotel markets outside Greater London. The most penetrable white space sits in vendor-managed inventory services for mid-market chains lacking procurement infrastructure. A specialized e-procurement portal with batch-level QR traceability addresses unmet demand from sustainability-marketed boutique operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors traceability infrastructure specialists over commodity textile manufacturers, as compliance software margins expand while spinning capacity faces overcapacity pressure. Long-term viability hinges on acquiring platforms with embedded hospitality buyer relationships rather than standalone mill assets. The signal to watch is NHS Supply Chain framework consolidation velocity, which will concentrate purchasing power and elevate barriers for non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Spinning | Dunelm's captive sourcing network neutralizes cotton price volatility for mid-market bedding contracts. |
| Blockchain Traceability Platform Deployment | Batch-level fiber provenance tracking satisfies EPR audit requirements for boutique hospitality renewals. |
| Scottish Heritage Brand Acquisition | Peter Reed's artisan positioning commands premium placement in Edinburgh luxury serviced apartments. |
| Vendor-Managed Inventory Service Launch | Marks & Spencer's rapid replenishment capabilities reduce stockout penalties for NHS acute trusts. |
| Recycled Fiber Certification Investment | Third-party verification capacity expansion unlocks retailer-mandated minimum thresholds for contract approval. |
Research Methodology
Operator-level perspectives from hospitality procurement directors, NHS Supply Chain framework managers, Scottish mill operations heads, and Trading Standards enforcement officers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through UK customs textile import records, BSI Kitemark certification databases, and Health and Safety Executive REACH compliance filings. Bottom-up segment sizing across product type, material, feature, and end-user dimensions triangulated against top-down macroeconomic indicators for the UK textiles sector.
Sensitivity analysis around cotton price volatility scenarios and EPR implementation timelines shaped the analytical framework across the projection horizon. Segmentation modeling incorporated bedding versus towel demand splits, natural versus synthetic fiber mix shifts, and hospitality versus residential end-user penetration trajectories. CAGRs derived from historical replacement cycle analysis and procurement consolidation patterns were stress-tested against regulatory compliance cost assumptions and carbon border adjustment readiness curves.
Material uncertainties — climate-driven harvest disruption in major cotton-producing regions, recycled fiber certification bottlenecks, and hospitality capital expenditure cyclicality — sit outside the modeled envelope and could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Duvets Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Global Textiles Home Decor Market