
 Table Linen Market | 2026-2036
Table Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Table Linen Market Analysis
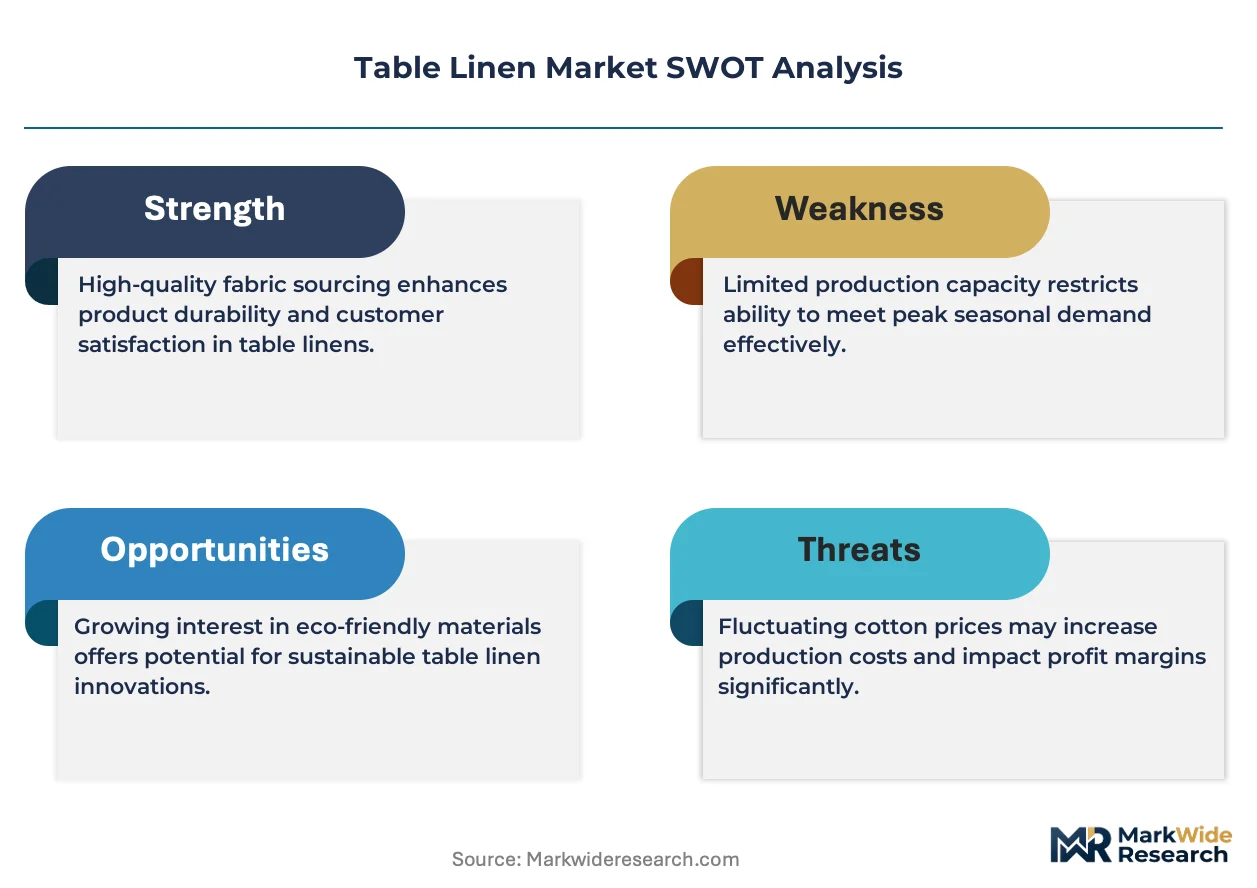
Portuguese textile mills are decoupling from seasonal cotton spot markets by locking multi-year pima contracts. Sferra sustains its position through artisanal finishing techniques anchored in Italian supply chains. Frette competes on hotel-direct distribution, while Garnier-Thiebaut differentiates through jacquard weaving leadership in Eastern France.
Table linen encompasses woven or knitted fabric goods designed to protect, decorate, or define dining surfaces, typically manufactured in weights between 120 and 250 GSM with mercerized cotton or ring-spun linen for dimensional stability and repeated commercial laundering. The commercial purpose spans hospitality presentation standards, brand identity reinforcement through custom embroidery, and food-safety compliance via non-slip silicone-backed placements. Cotton tablecloths occupy the largest volume share due to institutional procurement familiarity, while polyester blends capture the fastest growth in quick-service restaurant chains seeking lower total cost of ownership through extended replacement cycles. Hotel end users concentrate margin pools in white-tablecloth segments where thread count and hand-feel drive per-cover pricing authority.
EPA wastewater discharge standards shape commercial laundry operator equipment decisions, indirectly filtering upstream to fiber and finish specifications. OEKO-TEX Standard 100 certification operates as a de facto market-access requirement for European hospitality procurement, while state-level California Proposition 65 enforcement pressures dye chemistry disclosure across U.S. import channels. Stakeholders must monitor how municipal water tariffs and perchloroethylene bans reshape the economics of linen service versus disposable alternatives.
Market Dynamics
Municipal water-use ordinances in drought-prone U.S. states are compressing commercial laundry economics and forcing hospitality procurement toward soil-release finishes and extended-wear blends that reduce wash cycles.
Growth Catalysts
- Soil-release chemistry:Fluorocarbon-free finishes developed in German textile labs cut detergent volumes by half, aligning with EPA wastewater discharge standards while lowering per-cycle operating costs for Las Vegas hospitality clusters.
- Extended-wear cotton-polyester blends:Ring-spun 70/30 constructions now dominate procurement tenders from Nevada casino operators seeking 300+ wash-cycle durability against rising municipal water tariffs.
- California Proposition 65 enforcement:Dye chemistry disclosure mandates across U.S. import channels are accelerating supplier consolidation toward OEKO-TEX Standard 100 certified mills with pre-validated documentation.
Market Restraints
- Egyptian long-staple cotton price volatility:Nile Delta supply disruptions and currency instability concentrate input cost risk among Portuguese and Italian finishers locked into artisanal quality positioning.
- Perchloroethylene bans:Municipal phaseouts across California, New York, and Illinois are stranding dry-cleaning infrastructure investments and compressing service-network density for specialty linen care.
- Disposable paper-linen substitution:Quick-service restaurant chains in cost-sensitive segments are piloting compostable alternatives that eliminate laundering entirely, threatening volume in institutional cotton.
Strategic Opportunities
- Jacquard weaving for boutique hospitality:Eastern French technical expertise in complex patterning offers margin expansion beyond commodity white-tablecloth procurement through customization and brand co-development.
- EU Green Deal textile circularity requirements:Upcoming extended producer responsibility frameworks will reward mills with established take-back programs and fiber-to-fiber recycling partnerships.
- Direct-to-hotel distribution platforms:Digital procurement portals are disintermediating traditional textile jobbers, allowing Italian finishers to capture margin previously lost to layered distribution.
Industry Challenges
- Commercial laundering skill gaps:EPA compliance documentation and soil-release finish maintenance protocols require technical training that legacy hospitality operations lack, creating service-quality variance.
- OEKO-TEX certification timelines:Six-to-nine-month validation cycles for new dye chemistries delay product launches and tie up working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Linen Market |
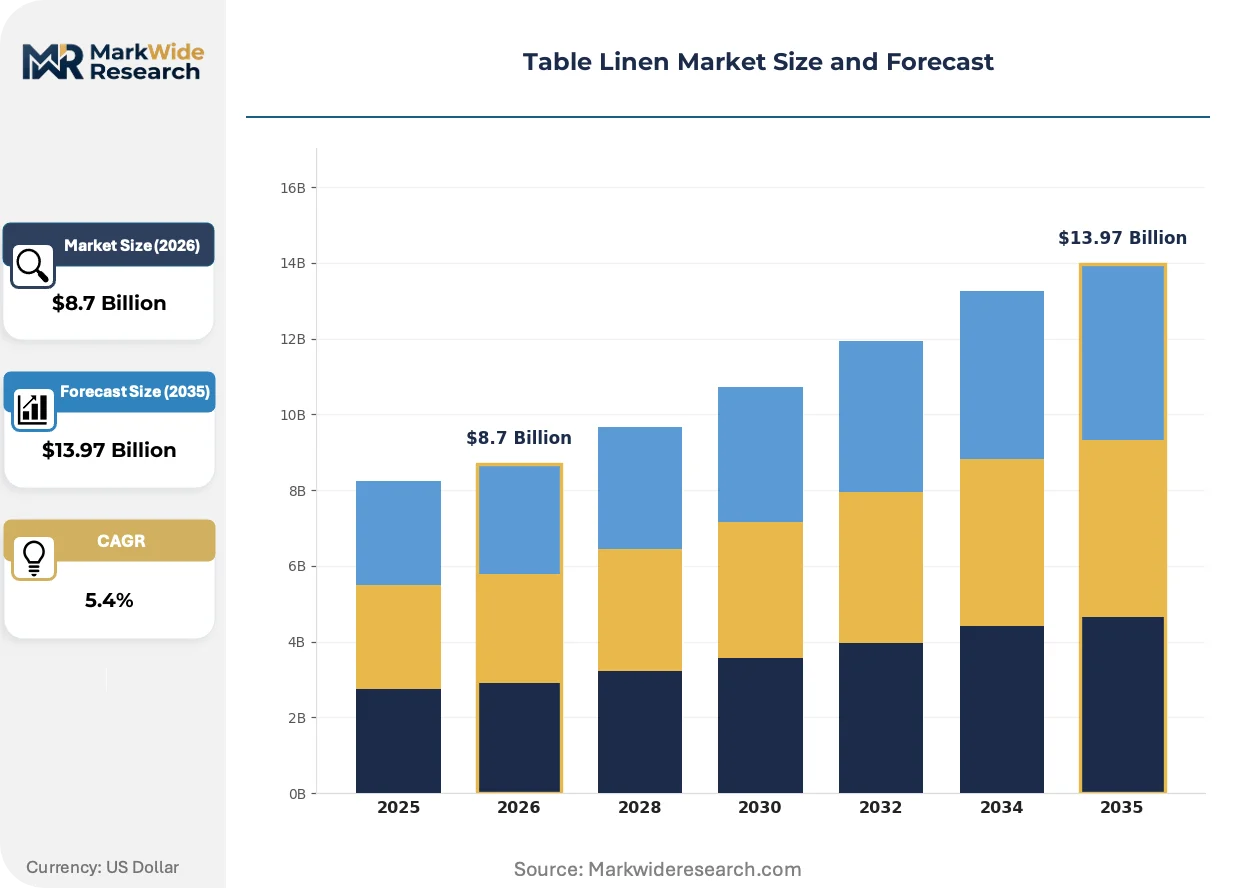
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablecloths, Napkins, Placemats, Runners Material: Cotton, Polyester, Linen, Blends End User: Households, Restaurants, Hotels, Catering Services Pattern Type: Solid, Striped, Floral, Geometric |
| Companies Covered | IKEA Holdings B.V., Sferra, Frette, Jomar Table Linens, Prestige Linens, Milliken & Company, Garnier-Thiebaut, Villeroy & Boch, Williams-Sonoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Linen Market Emerging Trajectories
Active chemistry and digital traceability are converging to reshape how table linen is specified, financed, and recovered at end-of-life across hospitality supply chains.
Plasma-based hydrophilic finishing is electrifying soil-release performance without fluorocarbon chemistry. Nevada casino operators adopted the technology within eighteen months of commercial availability. The shift is compressing demand for traditional silicone-based treatments and reallocating R&D budgets toward atmospheric-pressure plasma systems.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation across European import supply chains. German textile chemical suppliers have accelerated bio-based alternatives to maintain market access. Italian finishers now face six-month requalification cycles for existing hotel contracts previously secured on legacy chemistry.
Boutique hotel chains are consolidating procurement through sustainability scorecards that weight water intensity per wash cycle above unit price. Third-party linen service operators in California and Arizona are responding with fleet-wide blend standardization to simplify compliance reporting. The behavior is most visible in Scottsdale and Palm Springs resort clusters where municipal water tariffs now exceed detergent costs in total operating economics.
Table Linen Market Segmentation
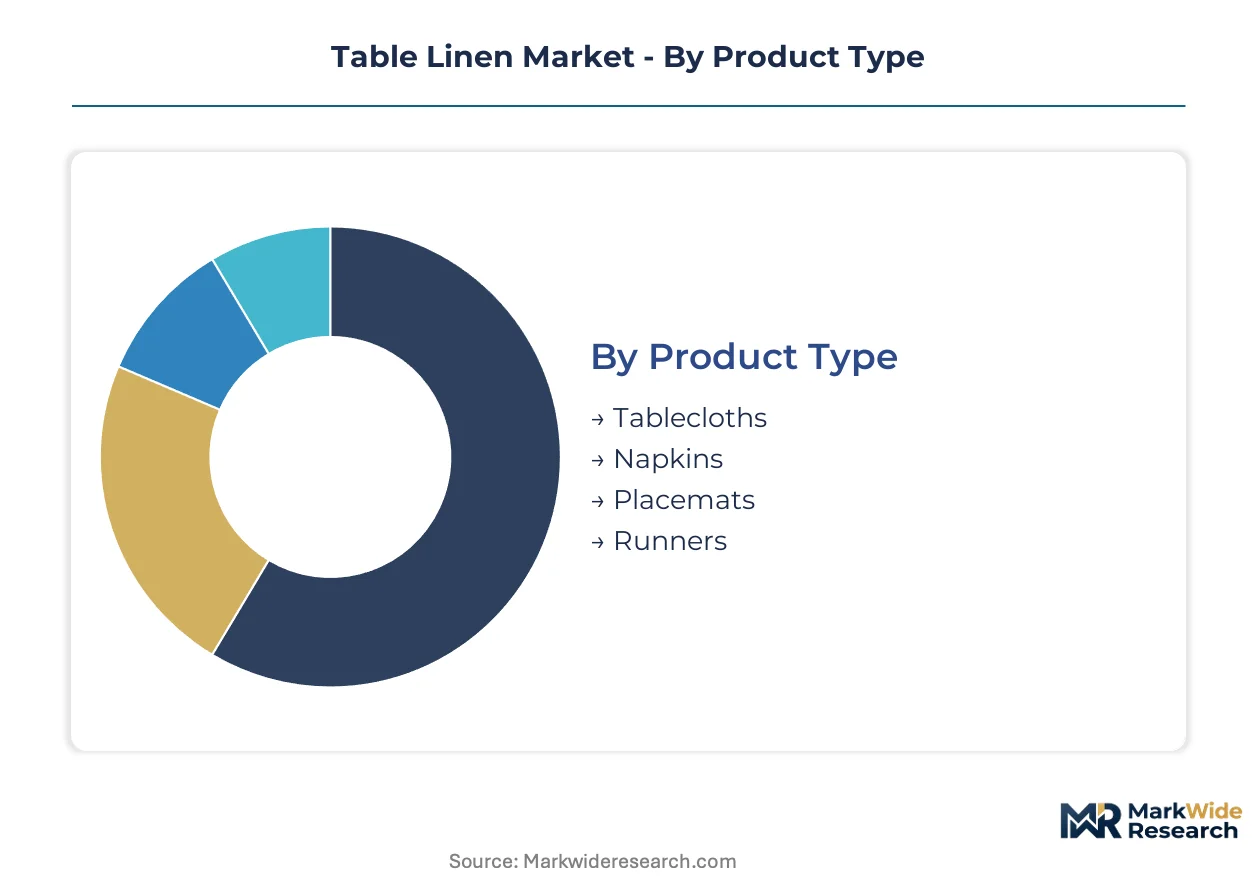
Segmentation in table linen reveals how procurement specifications diverge between institutional laundries and residential care cycles. Material chemistry and weave construction determine replacement economics across hospitality tiers, while pattern complexity shapes margin capture in boutique versus commodity channels.
Product Type:
Standalone tabletop coverings dominate procurement volumes, while coordinated sets embed linen into broader hospitality presentation systems.
- Tablecloths:Woven goods between 180-250 GSM serve as the primary dining surface protector in white-tablecloth restaurants. Las Vegas casino operators specify soil-release finished cotton-poly blends to withstand 300+ commercial wash cycles under rising municipal water tariffs.
- Napkins:Ring-spun constructions in 120-180 GSM range function as both functional wiping surfaces and folded presentation elements. European boutique hotels drive demand for mercerized cotton with custom embroidery anchoring brand identity at per-cover pricing premiums.
- Placemats:Silicone-backed variants deliver non-slip food-safety compliance for quick-service chains.
- Runners:Narrow-width accent pieces concentrate in seasonal hospitality refreshes and residential tablescaping.
Tablecloths lead volumes today; napkins are gaining share fastest through boutique hotel procurement consolidation.
Material:
Cost tier stratification separates artisanal positioning from total-ownership economics in high-frequency laundering environments.
- Cotton:Long-staple and pima varieties deliver dimensional stability through repeated mercerization. Institutional procurement in drought-prone U.S. states favors cotton-poly constructions that reduce water intensity per wash cycle.
- Polyester:Solution-dyed filament constructions eliminate fading and extend replacement cycles. Quick-service restaurant chains specify 100% polyester for lowest total cost of ownership in high-turnover settings.
- Linen:Belgian and French flax supply chains serve premium hospitality through distinctive hand-feel and natural luster.
- Blends:Ring-spun 70/30 cotton-poly constructions balance absorbency with wrinkle resistance for commercial laundry corridors.
Cotton dominates procurement tonnage; polyester blends are expanding most quickly in cost-sensitive institutional channels.
End User:
Customer type determines frequency-of-use specifications and replacement cycle economics across residential and commercial laundries.
- Restaurants:White-tablecloth segments prioritize thread count and hand-feel for per-cover pricing authority. Soil-release finishes and extended-wear blends reduce wash frequency under California and Nevada water-use ordinances.
- Hotels:Procurement teams concentrate margin pools in luxury segments where custom embroidery reinforces brand identity. EPA wastewater discharge standards shape equipment decisions that filter upstream to fiber specifications.
- Households:Occasional-use patterns favor natural fibers and decorative patterning over durability engineering.
- Catering Services:Event-based demand cycles require rapid-turn inventory with stain-hiding darker colorways.
Restaurants anchor current volume; hotels are climbing the fastest through boutique chain expansion.
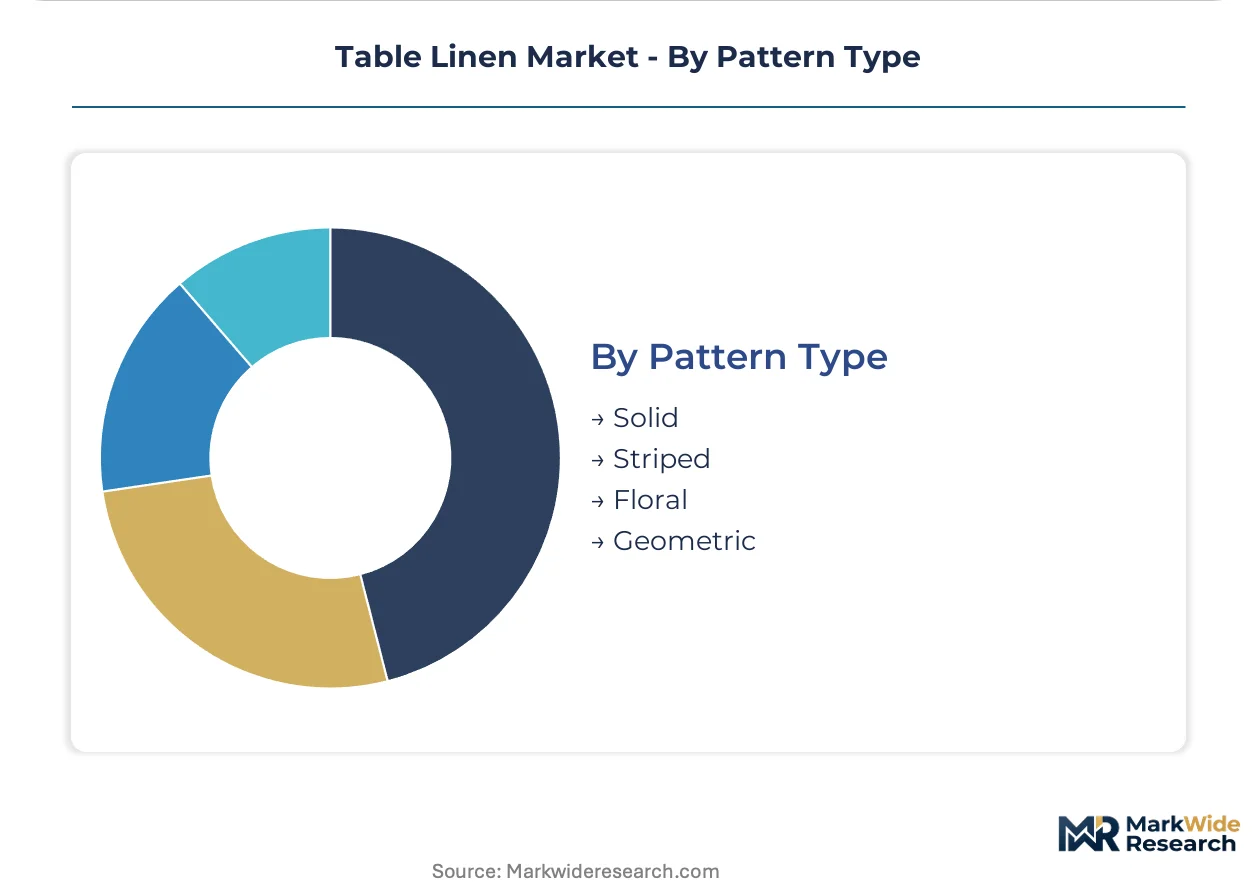
Pattern Type:
Geographic supply concentration for complex weaving determines margin structure across commodity and customization tiers.
- Solid:Undyed or piece-dyed constructions dominate institutional procurement for color consistency across replacement cycles. White-tablecloth hospitality specifies optical brightener-compatible finishes for presentation standards.
- Geometric:Jacquard-woven complex patterns leverage Eastern French technical expertise for boutique hotel brand co-development and margin expansion beyond commodity tiers.
- Striped:Yarn-dyed constructions serve seasonal hospitality refreshes with predictable repeatability.
- Floral:Rotary-screen and digital print applications concentrate in residential and catering segments.
Solid patterns command volume leadership today; geometric patterns show the steepest expansion trajectory through customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian finishers command premium positioning through artisanal supply chains, while Portuguese mills secure raw material stability through multi-year cotton contracts. Water scarcity regulations in the American Southwest are compressing commercial laundry economics and redirecting procurement specifications.
United States
Municipal water tariffs in Nevada and California now exceed detergent costs in total operating economics for commercial laundries. EPA wastewater discharge standards filter upstream to fiber specifications, forcing Las Vegas casino operators toward soil-release finished cotton-poly blends rated for 300+ wash cycles. Scottsdale and Palm Springs resort clusters standardize blend specifications to simplify compliance reporting.
Italy
Artisanal finishing techniques anchor supply chains for luxury hospitality procurement. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force six-month requalification cycles for hotel contracts previously secured on legacy chemistry. Prato and Como industrial districts concentrate plasma-based hydrophilic finishing adoption within eighteen months of commercial availability.
Portugal
Textile mills decouple from seasonal cotton spot markets through multi-year pima contracts. EU Green Deal textile circularity requirements reward established take-back programs and fiber-to-fiber recycling partnerships. Northern Portuguese manufacturing corridors develop digital procurement portals that disintermediate traditional textile jobbers.
France
Eastern French technical expertise in jacquard weaving supports boutique hotel brand co-development beyond commodity tiers. OEKO-TEX Standard 100 certification operates as de facto market-access requirement for hospitality procurement. Alsace and Vosges weaving clusters concentrate complex patterning capabilities that command margin expansion through customization.
Germany
German textile chemical suppliers accelerate bio-based alternatives to maintain European market access under evolving substance restrictions. Fluorocarbon-free finishes developed in German labs cut detergent volumes by half while aligning with discharge standards. Technical textile research corridors near Stuttgart and Munich drive atmospheric-pressure plasma system development.
Table Linen Market Vendor Landscape
Italian producers anchor the premium tier through artisanal finishing heritage; Portuguese specialists hold supply security advantages through cotton contract structures. The vendor base stratifies across three functional layers: integrated mills controlling fiber-to-finish workflows, design houses monetizing brand equity through hospitality-direct distribution, and regional converters serving institutional procurement with standardized specifications. Strategic moves concentrate on digital platform development for direct hotel relationships and circularity infrastructure for upcoming extended producer responsibility frameworks.
Among heritage-positioned European houses, Sferra exemplifies artisanal finishing anchored in Italian supply chains, while Frette occupies a position built on hotel-direct distribution models. Garnier-Thiebaut represents jacquard weaving specialization concentrated in Eastern France. These three entities illustrate how geographic craft traditions translate into procurement tier segmentation across white-tablecloth hospitality and boutique hotel channels.
| Leading Market Players |
|---|
| IKEA Holdings B.V. |
| Sferra |
| Frette |
| Jomar Table Linens |
| Prestige Linens |
| Milliken & Company |
| Garnier-Thiebaut |
| Villeroy & Boch |
| Williams-Sonoma |
| Others |
Supply Flow & Price Mechanics
Captive finishing operations in Italian industrial districts anchor premium-tier positioning while insulating margin pools from raw material volatility. Portuguese mills leverage backward integration into cotton sourcing to secure supply predictability that translates into contract pricing power against spot-market competitors.
Pricing Analysis
Capacity additions in Portuguese spinning corridors are reshaping price floors for pima cotton constructions. Three-tier pricing structure across premium, standard, and economy levels separates artisanal Italian finishers from Portuguese contract spinners and Asian commodity converters. Price differentiation hinges on OEKO-TEX certification tier and soil-release finish performance. Cost compression in quick-service polyester blends is intensifying because disposable paper-linen substitution threatens volume. Quick-service chains exhibit highest price sensitivity; boutique hotel procurement teams prioritize water-intensity metrics over unit cost.
Supply Chain Analysis
Long-staple cotton supply rests on Egyptian, American, and Peruvian agricultural corridors. Belgian and French flax cultivation, German textile chemical formulation, and Italian mercerization equipment constitute critical upstream dependencies. Single-source vulnerability concentrates in Egyptian Giza cotton harvests exposed to Nile Delta water access disputes. Distribution runs through hospitality-direct platforms, traditional textile jobbers, and institutional laundry service operators in layered arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Table linen procurement functions as a regulatory compounder where EPA wastewater discharge standards and California Proposition 65 enforcement accelerate supplier consolidation toward certified mills.
For Market Incumbents: Deploy plasma-based hydrophilic finishing to defend market position against fluorocarbon chemistry obsolescence driven by REACH Annex XVII restrictions. Extend multi-year cotton contracts to lock input cost predictability against Egyptian supply disruption. Consolidate OEKO-TEX certification documentation to preempt procurement disqualification under tightening dye chemistry disclosure mandates. For New Entrants and Emerging Players: Digital traceability platforms offer technology-first entry into boutique hotel sustainability scorecard procurement. Target Scottsdale and Palm Springs resort clusters where municipal water tariffs exceed detergent costs and compliance reporting complexity creates service gaps. Lead with water-intensity analytics as differentiated go-to-market positioning against legacy textile jobbers. For Investors and Strategic Acquirers: Roll-up economics work for regional linen service operators because commercial laundering skill gaps fragment quality delivery and create acquisition currency for consolidation platforms. Five-to-ten year viability hinges on circularity infrastructure positioning ahead of EU Green Deal extended producer responsibility activation. Monitor plasma finishing adoption velocity in Nevada casino procurement as inflection signal for chemistry transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Soil-Release Finish Certification | REACH-compliant fluorocarbon alternatives secure European hospitality procurement access under Annex XVII restrictions. |
| Multi-Year Cotton Contracting | Pima supply locks insulate Portuguese mills from Egyptian currency instability and harvest volatility. |
| Direct-to-Hotel Platform Launch | Digital portals disintermediate jobber margins and capture hospitality procurement consolidation value. |
| Fiber-to-Fiber Recycling Partnership | EU Green Deal circularity requirements reward established take-back infrastructure with compliance advantage. |
| Atmospheric-Pressure Plasma Investment | German-developed hydrophilic systems cut detergent volumes and align with Las Vegas water tariff economics. |
Methodological Framework
Coverage spans the United States, Italy, Portugal, France, and Germany, with primary inputs from each regional textile manufacturing corridor. Primary interviews with hospitality procurement directors, commercial laundry operators, textile mill production managers, and chemical supplier technical leads combined with secondary validation from customs trade records, EPA enforcement databases, OEKO-TEX certification registries, and EU regulatory filings. Bottom-up fiber consumption estimates and top-down hospitality expenditure analysis underwent triangulation to converge on market sizing.
Rate-of-change decomposition separated volume from value trajectories across the projection horizon. Segmentation dimensions modeled include material chemistry, product construction, end-user category, and geographic regulatory cluster. CAGRs derived from weighted average of historical replacement cycle analysis and forward procurement intention surveys. Industry-specific forecast inputs incorporated municipal water tariff escalation schedules and REACH substance restriction implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Egyptian cotton supply disruption, perchloroethylene ban acceleration, and disposable paper-linen substitution penetration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hospitality capital expenditure cycles. Material deviation in water scarcity ordinance adoption velocity or plasma finishing cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Duvets Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Global High Temperature Curtains Market