
 India Bed and Bath Linen Market | 2026-2036
India Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
India Bed and Bath Linen Market Foresight
Hotel and hospital procurement in India is consolidating around large-format institutional buyers with standardized quality requirements. Welspun India Ltd anchors its position through integrated towel and bedding manufacturing at scale. Trident Group leverages captive cotton sourcing from Punjab to sustain margin stability across volatile fiber cycles. Indo Count Industries Ltd specializes in high-thread-count bedding exports, competing primarily on design-to-delivery speed for European hospitality chains.
Bed and bath linen encompasses woven and knitted textile products for sleeping environments and personal hygiene, typically constructed from cotton fibers exceeding 200 threads per square inch for premium grades, with terry-loop construction for absorbent toweling. These products serve dual commercial purposes: delivering thermal comfort and moisture management in residential settings, while meeting institutional laundering durability standards in hospitality and healthcare. Cotton bedding commands the dominant value share within product type segmentation, though microfiber towels are gaining traction in budget hotel chains for faster drying cycles and reduced replacement frequency. The household end-user segment remains structurally mature, whereas hospital procurement is emerging as a faster-growing channel driven by infection-control protocols and disposable-to-reusable conversion programs.
BIS textile standards and the CDSCO's evolving guidelines for hospital linen sterility are reshaping product specifications and testing burdens across domestic supply chains. The PLI scheme for textiles is channeling capital toward large-scale manufacturing investments, favoring mills with existing compliance infrastructure over smaller regional competitors. Stakeholders must monitor how BIS enforcement intensity and state-level textile park incentives interact to reshape competitive access in India's southern and western manufacturing belts.
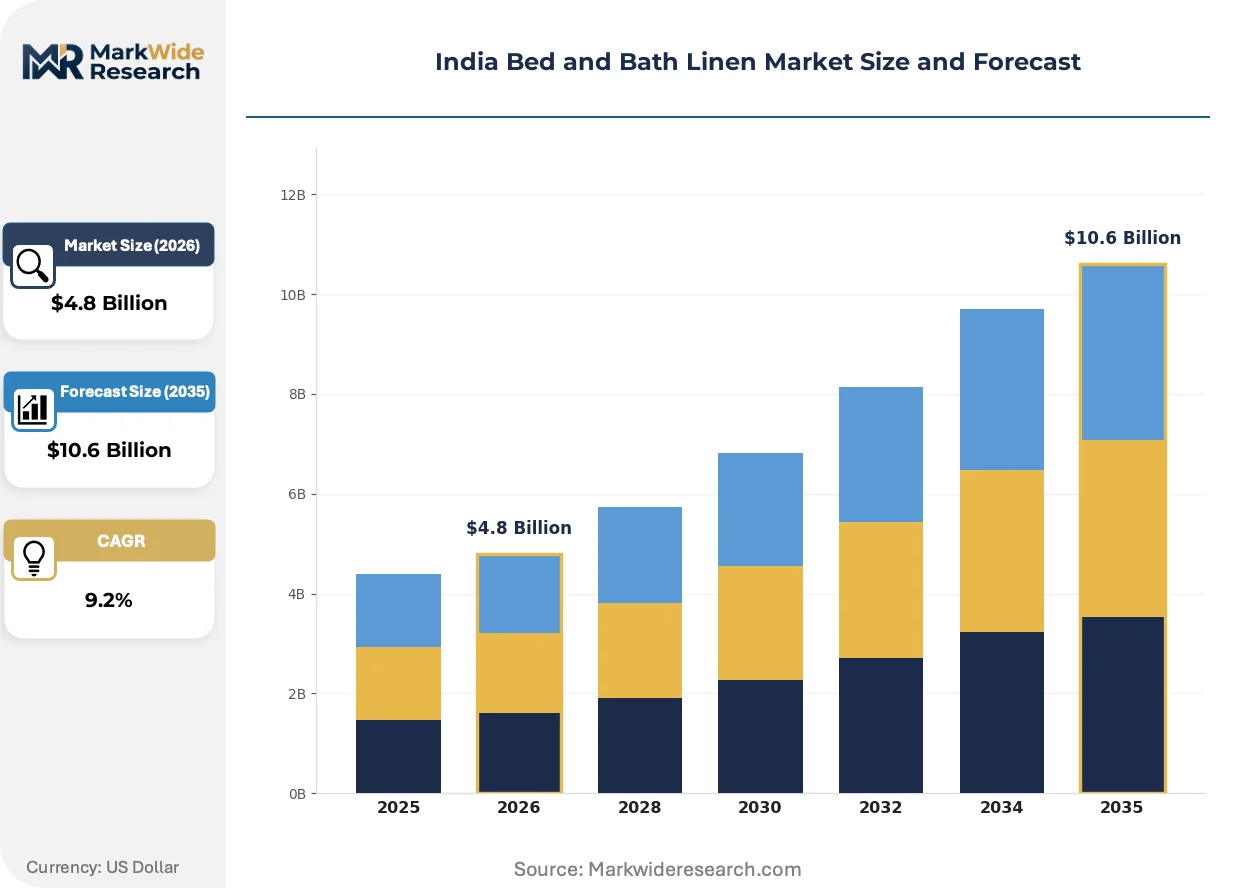
Market Dynamics
India's bed and bath linen sector is restructuring around the PLI scheme for textiles, which channels capital toward large-scale manufacturing investments and favors mills with existing compliance infrastructure over smaller regional competitors.
Growth Catalysts
- BIS Certification Mandates:Tightening textile quality and labeling standards are forcing domestic mills to upgrade testing capabilities, creating tiered market access that rewards compliant producers with institutional hospitality contracts.
- Hotel Sector Expansion:India's hospitality procurement is consolidating around premium cotton bedding suites as branded hotel chains standardize supplier bases across new properties in Maharashtra and Gujarat.
- Captive Cotton Sourcing:Mills with backward integration into Punjab's cotton belt are sustaining margin stability through volatile fiber price cycles, insulating production costs from spot market fluctuations.
Market Restraints
- Input Cost Volatility:Raw cotton prices swing with monsoon variability and international commodity markets, compressing margins for non-integrated spinners who lack captive ginning operations.
- Supply Concentration Risk:Manufacturing investment disproportionately clusters in Maharashtra and Gujarat due to port access, creating regional vulnerability to logistics disruptions or state-level policy shifts.
- Technical Limitation:Domestic terry-loop weaving capacity for premium hotel towels remains concentrated among a handful of integrated players, constraining rapid scaling for mid-tier entrants.
Strategic Opportunities
- Southern Manufacturing Belt:Tamil Nadu and Karnataka textile parks offer underutilized spinning capacity and state incentives that could absorb PLI-linked investments away from western concentration.
- Hospital Linen Conversion:CDSCO sterility guidelines are accelerating disposable-to-reusable conversion programs in healthcare, opening certified laundering contracts for mills with autoclave-compatible fabric finishes.
- Microfiber Budget Positioning:Budget hotel chains are adopting quick-dry synthetic toweling for reduced replacement cycles, creating a parallel product line opportunity distinct from cotton premium positioning.
Industry Challenges
- Compliance Timeline Compression:BIS enforcement intensity is accelerating certification renewal cycles, requiring mills to maintain dedicated testing staff and third-party audit relationships.
- Capex Intensity for Scale:PLI threshold requirements for minimum investment and revenue are excluding sub-scale regional competitors from incentive access, forcing consolidation or exit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bed and Bath Linen Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Towels, Curtains, Table Linen Material: Cotton, Polyester, Linen, Microfiber End User: Households, Hotels, Hospitals, Resorts Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | GHCL Home Textiles, Himatsingka Seide, Welspun India Ltd, Vardhman Textiles, Raymond Home, Trident Group, Bombay Dyeing, MyTrident, Indo Count Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bed and Bath Linen Market Shifts & Advancements
Digital weaving controls and antimicrobial fabric finishes are reshaping how Indian mills compete on specification compliance and laundering durability for institutional buyers.
Air-jet weaving technology with electronic jacquard patterning is expanding into high-thread-count bedding production for European hospitality chains. Mills in Gujarat are retrofitting looms with automated warp tension systems to reduce defects below the threshold required by luxury hotel procurement teams. This precision capability is expanding into design-to-delivery contracts where sample approval cycles compress from weeks to days.
BIS textile standards and CDSCO hospital linen sterility guidelines are mandating documented traceability from fiber source to finished goods. Domestic mills must now maintain batch-level testing records for tensile strength and colorfastness, with third-party laboratory verification for institutional contracts. Maharashtra-based manufacturers are responding by integrating in-house quality assurance departments that interface directly with hospitality procurement auditors.
Large-format institutional buyers are consolidating supplier relationships around integrated manufacturers who control spinning, weaving, and finishing under single ownership. Mid-sized hotel chains are bypassing traditional trading houses to contract directly with mills for standardized bedding suites, compressing margin layers in the distribution stack. This direct contracting pattern is most visible in Gujarat's Surat cluster, where hospitality-focused mills maintain dedicated B2B sales teams for chain account management.
India Bed and Bath Linen Market Segmentation
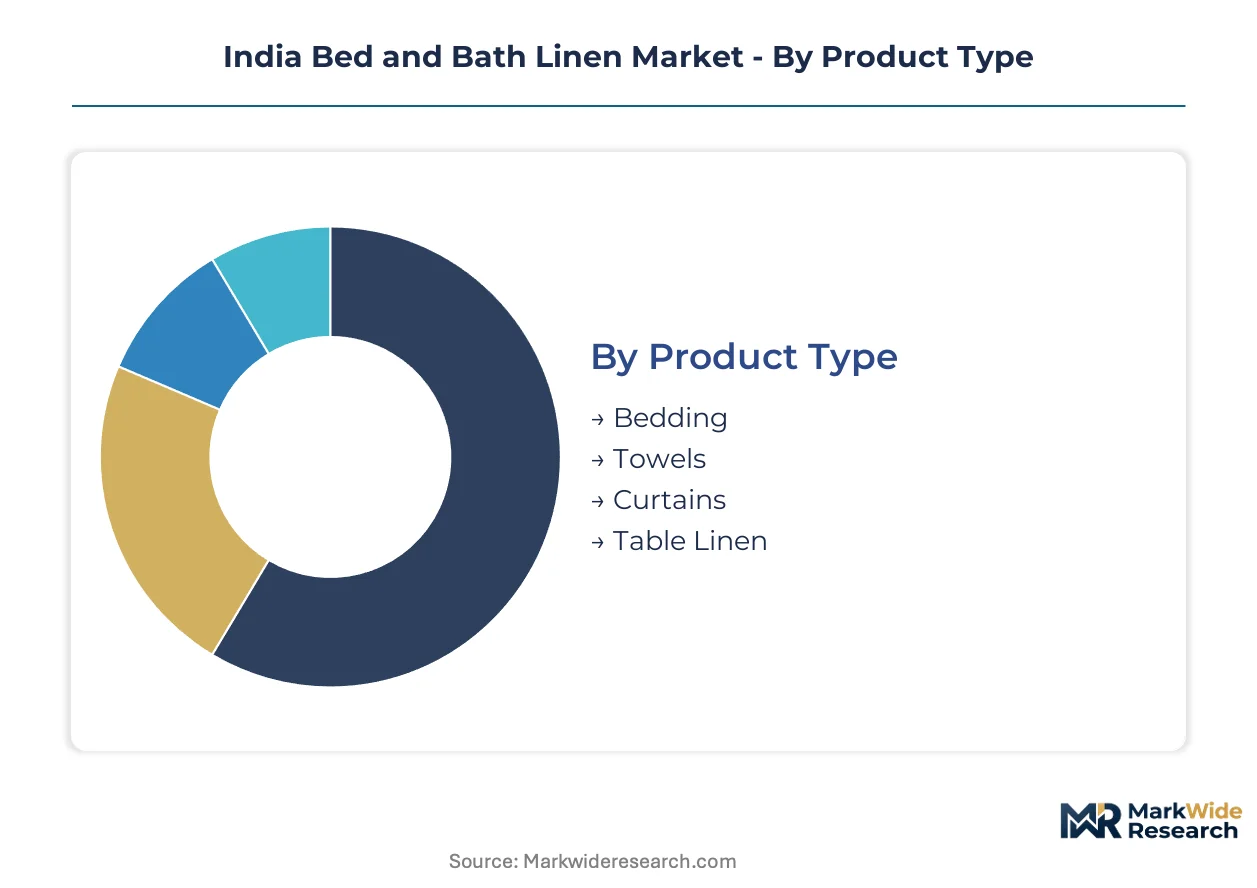
Segmentation in India's bed and bath linen market reveals how capital deployment, regulatory compliance, and procurement consolidation reshape competitive access across distinct product tiers and institutional channels.
Product Type:
Capital intensity varies sharply across weaving technologies, with high-thread-count bedding requiring air-jet loom investments that terry-loop towel production cannot easily replicate.
- Bedding:Woven sheeting and duvet covers exceeding 200 threads per square inch dominate premium hospitality procurement. Maharashtra and Gujarat mills absorb the bulk of branded hotel chain contracts as properties standardize supplier bases.
- Towels:Terry-loop construction for absorbent toweling demands specialized weaving capacity concentrated among integrated players. CDSCO sterility guidelines are accelerating certified laundering programs for hospital-grade towel supply.
- Curtains:Decorative window treatments serve residential and resort segments with lower technical barriers to entry.
- Table Linen:Institutional dining procurement represents a smaller addressable market with standardized durability specifications.
Bedding absorbs the bulk of installed capacity; towels are expanding most quickly through hospital linen conversion programs.
Material:
Backward integration into fiber sourcing determines margin resilience when commodity cotton prices swing with monsoon variability.
- Cotton:Punjab's cotton belt supplies captive ginning operations that insulate integrated mills from spot market volatility. BIS certification mandates for fiber traceability favor producers with documented batch-level testing infrastructure.
- Microfiber:Quick-dry synthetic toweling gains traction in budget hotel chains seeking reduced replacement cycles and faster drying times between laundering.
- Polyester:Blended sheeting offers cost positioning for mid-tier residential markets with lower thread-count requirements.
- Linen:Premium natural fiber positioning serves boutique hospitality and high-end residential segments with distinct texture preferences.
Cotton commands the dominant value position; microfiber is climbing the fastest as budget chains standardize synthetic specifications.
End User:
Procurement consolidation patterns diverge between fragmented household demand and concentrated institutional contracting.
- Hotels:Large-format branded chains in Maharashtra and Gujarat are consolidating supplier relationships around integrated manufacturers with single-ownership control of spinning through finishing.
- Hospitals:CDSCO evolving sterility guidelines are accelerating disposable-to-reusable conversion programs, opening certified laundering contracts for mills with autoclave-compatible fabric finishes.
- Households:Structurally mature residential demand channels through retail and online distribution with price-sensitive purchasing patterns.
- Resorts:Boutique and leisure properties maintain fragmented procurement with design-driven specifications distinct from standardized hotel suites.
Hotels absorb the bulk of institutional contract value; hospitals are gaining share fastest through infection-control procurement mandates.
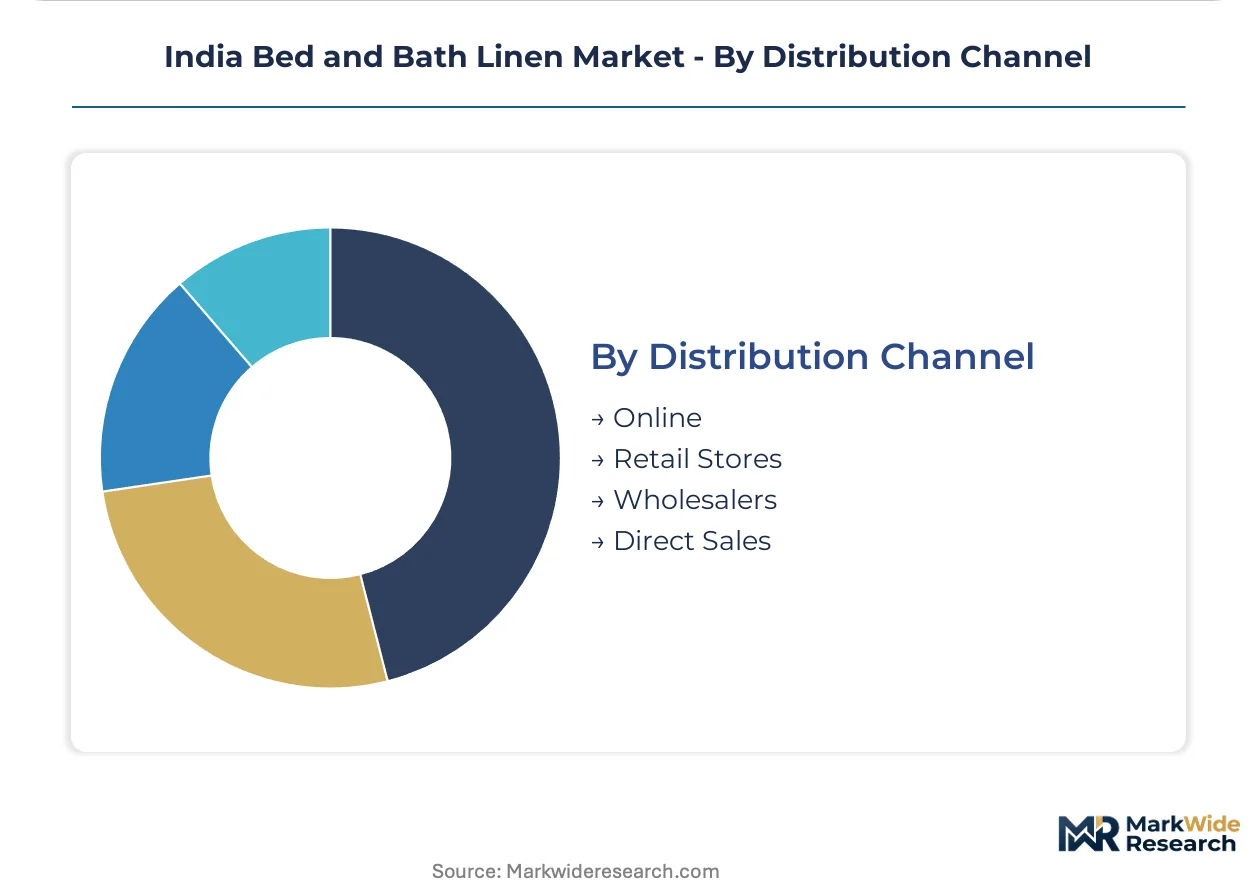
Distribution Channel:
Channel economics reshape margin capture as mid-tier buyers bypass traditional trading layers.
- Direct Sales:Mills in Surat maintain dedicated B2B sales teams for chain account management, compressing margin layers in the distribution stack.
- Wholesalers:Traditional trading houses face displacement as institutional buyers seek documented traceability from fiber source to finished goods.
- Retail Stores:Household segment purchases flow through brick-and-mortar channels with regional brand concentration.
- Online:E-commerce platforms aggregate fragmented residential demand with limited penetration in institutional procurement.
Direct sales absorb the bulk of institutional volume; online channels are expanding most quickly in residential replacement purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional procurement concentrates in western and southern manufacturing belts where port access and cotton belt proximity intersect with state-level textile park incentives.
Maharashtra
Branded hotel chains in Mumbai and Pune drive premium cotton bedding demand as properties standardize supplier bases across new developments. BIS certification mandates for textile quality and labeling force mills to upgrade testing capabilities and maintain dedicated quality assurance departments. The Mumbai-Thane industrial corridor hosts integrated manufacturers with single-ownership control of spinning through finishing operations.
Gujarat
Surat cluster mills maintain dedicated B2B sales teams for direct chain account management, compressing traditional trading house margins. PLI scheme thresholds for minimum investment and revenue channel capital toward large-scale manufacturing investments that favor compliant producers. Ahmedabad and Vadodara absorb disproportionate terry-loop weaving capacity for premium hotel towel production.
Punjab
Captive cotton sourcing from the state's agricultural belt insulates integrated mills from spot market volatility and monsoon-driven price swings. DGFT export promotion schemes support value-added textile shipments to European hospitality chains. Ludhiana and Amritsar host spinning operations that supply backward-integrated producers across northern and western manufacturing zones.
Tamil Nadu
Underutilized spinning capacity in Coimbatore and Tiruppur textile parks offers state incentives that could absorb PLI-linked investments away from western concentration. CDSCO evolving sterility guidelines for hospital linen accelerate certified laundering contract opportunities for mills with autoclave-compatible fabric finishes. Southern manufacturing infrastructure remains less saturated than Maharashtra-Gujarat corridors.
Karnataka
Bangalore's hospitality sector expansion creates demand for standardized bedding suites as business hotel chains penetrate secondary cities. State-level textile park incentives compete with western region offerings for new manufacturing investment. Mysore and Hassan districts host emerging weaving clusters seeking to capture institutional procurement flows from saturated western markets.
India Bed and Bath Linen Market Competitive Landscape
Western producers anchor the integrated manufacturing tier; northern specialists hold captive cotton advantages through Punjab belt proximity. The vendor base splits between large-format institutional suppliers with full vertical control and mid-tier regional competitors facing PLI threshold exclusion. Three archetypes dominate: scale-driven integrated mills, design-to-delivery exporters, and captive-sourcing cotton belt operators. Consolidation pressures intensify through M&A activity among sub-scale regional players and capacity expansion by incentive-qualified producers.
Among western India-based integrated manufacturers, Welspun India Ltd and Trident Group exemplify the scale-driven archetype with full-process control, while Indo Count Industries Ltd occupies a position within the design-to-delivery export tier specializing in high-thread-count bedding for European hospitality chains. These three entities represent distinct competitive vectors: manufacturing scale, fiber cost insulation, and specification speed respectively.
| Leading Market Players |
|---|
| GHCL Home Textiles |
| Himatsingka Seide |
| Welspun India Ltd |
| Vardhman Textiles |
| Raymond Home |
| Trident Group |
| Bombay Dyeing |
| MyTrident |
| Indo Count Industries Ltd |
| Others |
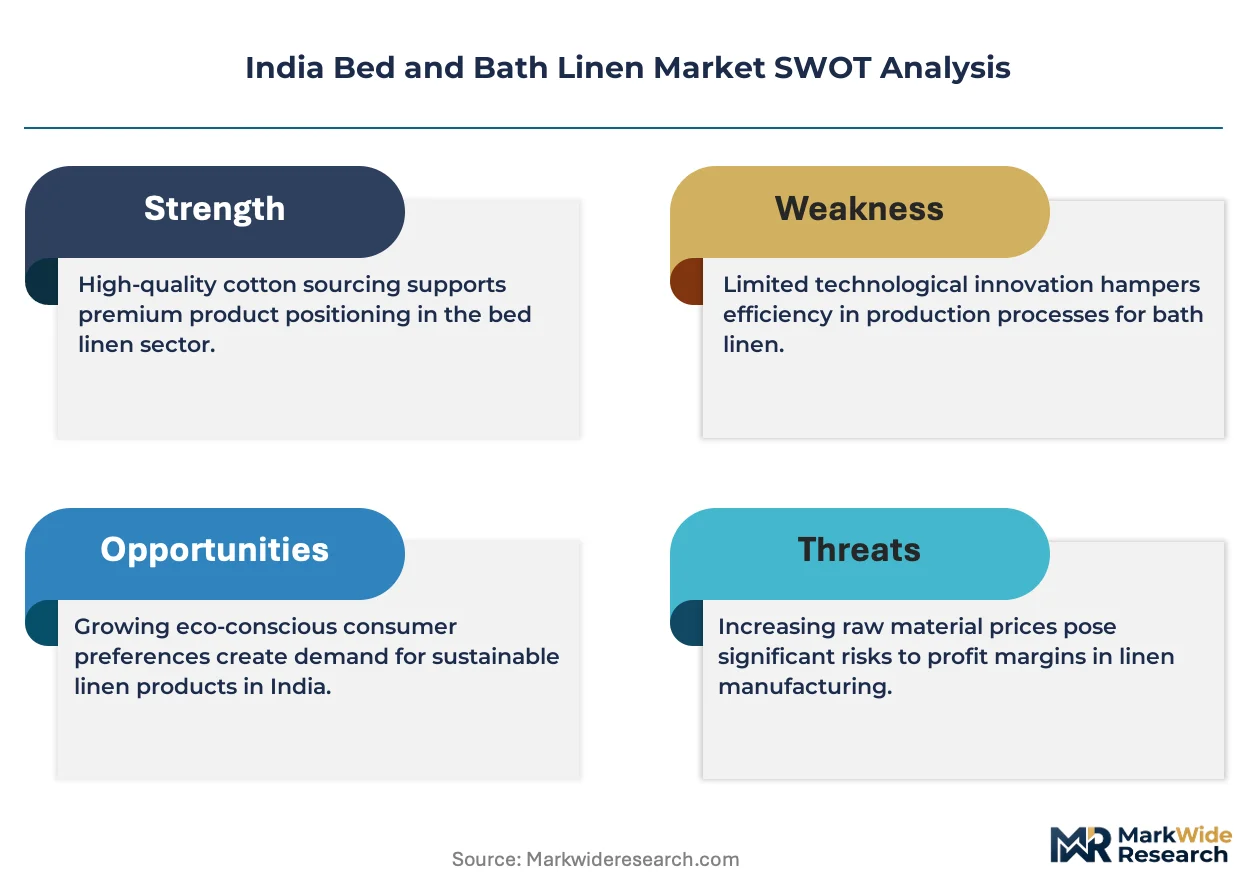
Supply & Pricing Matrix
Captive cotton sourcing from Punjab's agricultural belt anchors both supply security and margin stability for integrated mills, insulating production costs from spot market volatility while compressing pricing power for non-integrated competitors. This backward integration pattern concentrates pricing leverage among producers with in-house ginning operations, forcing mid-tier spinners to absorb fiber cost swings or exit contract bidding.
Pricing Analysis
Volume contracts absorb institutional procurement at thin margins, while design-to-delivery premiums attach to rapid sample turnaround for European hospitality chains. Price differentiation hinges on BIS certification tier and captive fiber sourcing, with certified mills commanding 15-20% premiums over non-compliant regional competitors. Pricing pressure stems from raw cotton volatility driven by monsoon variability, compressing margins for non-integrated spinners lacking captive ginning. Budget hotel chains exhibit highest price sensitivity, prioritizing microfiber quick-dry specifications over cotton premiums; luxury hospitality demonstrates lowest sensitivity, paying for documented traceability and air-jet weaving precision.
Supply Chain Analysis
Raw cotton supply rests on Punjab's agricultural belt, with supplementary sourcing from Maharashtra and Gujarat ginning clusters. Critical inputs include long-staple cotton fiber, air-jet loom components from European and Japanese manufacturers, and antimicrobial finishing chemicals. Supply chain risk centers on regional concentration in Maharashtra-Gujarat manufacturing corridors, exposing procurement flows to logistics disruptions or state-level policy shifts. Distribution runs through direct mill-to-hotel contracting in Surat and Mumbai-Thane corridors, with traditional wholesalers losing share to integrated manufacturers with dedicated B2B sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's bed and bath linen sector is transitioning from conventional shuttle looms to air-jet weaving with electronic jacquard patterning, as digital controls replace mechanical systems for specification compliance and rapid design iteration.
For Market Incumbents: Deploy certification infrastructure as a moat by accelerating BIS testing capability investments ahead of enforcement intensity increases. Consolidate around captive cotton sourcing from Punjab to defend margin stability against fiber price volatility, while acquiring sub-scale regional competitors facing PLI threshold exclusion to capture stranded capacity. For New Entrants and Emerging Players: Microfiber quick-dry technology offers a wedge into budget hotel chain procurement, where synthetic specifications are displacing cotton for reduced replacement cycles. Target Tamil Nadu and Karnataka textile parks with underutilized spinning capacity and state incentives distinct from saturated western corridors. Lead with autoclave-compatible fabric finishes for hospital linen conversion contracts under evolving CDSCO sterility guidelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by scale-driven integrated mills seeking regional capacity and compliance infrastructure. Five-to-ten year viability favors producers with documented fiber traceability systems and direct B2B hospitality relationships. Watch BIS enforcement intensity and PLI scheme threshold adjustments as inflection signals for competitive access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Jet Loom Retrofit | Enables high-thread-count bedding production for European hospitality design-to-delivery contracts. |
| Backward Cotton Integration | Captive ginning from Punjab insulates margins against monsoon-driven spot price volatility. |
| BIS Certification Investment | Unlocks institutional hospitality contracts requiring documented batch-level testing infrastructure. |
| Hospital Linen Conversion | CDSCO sterility guidelines open certified laundering contracts for autoclave-compatible finishes. |
| Southern Manufacturing Expansion | Tamil Nadu and Karnataka incentives absorb PLI-linked investment away from western concentration. |
Research Methodology
Document review covered BIS textile standards filings, CDSCO hospital linen guidelines, PLI scheme administrative records, and DGFT export promotion data, complemented by interviews with spinning mill operations directors, hospitality procurement managers at branded hotel chains, textile park development officers, and antimicrobial finishing chemical suppliers. Secondary validation drew from customs trade databases, state industrial department investment reports, and hospitality sector expansion announcements. Bottom-up capacity assessments and top-down procurement flow estimates were triangulated against disclosed manufacturing investments.
Output modeling generated volume and value trajectories across the projection horizon by weaving technology type, fiber composition tier, end-user procurement channel, and regional manufacturing cluster. Segmentation dimensions included product construction (bedding versus terry-loop toweling), material specification (cotton grade versus microfiber), buyer archetype (branded hotel chain versus hospital system versus household), and distribution structure (direct mill contracting versus wholesale trading). CAGRs were derived from installed capacity expansion rates, hospitality room stock growth, and hospital bed conversion program adoption curves.
Several conditions sit outside the modeled scope, including extreme monsoon disruption to cotton yields, abrupt BIS enforcement timeline acceleration, and trade policy shifts affecting fiber import duties. Forecasts embed assumptions regarding PLI scheme continuity and state textile park incentive stability. A small set of named triggers warrants ongoing watch: CDSCO sterility guideline finalization, Maharashtra-Gujarat logistics corridor reliability, and air-jet loom component import cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Duvets Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market