
 Bed and Bath Linen Market | 2026-2036
Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Bed and Bath Linen Market Analysis
Digital textile printing combined with AI-driven color matching is narrowing the gap between small-batch customization and mass-production economics in linen manufacturing. Welspun India anchors its competitive position through backward integration into cotton spinning across its Gujarat facilities. American Textile Company leverages domestic cut-and-sew operations to sustain rapid replenishment contracts with North American hospitality chains. Trident Group specializes in terry towel engineering, occupying a technical niche in high-gram-weight institutional bath products.
Bed and bath linen comprises woven and knitted textile goods designed for sleeping environments and hygiene routines, typically constructed from cotton fibers with thread counts ranging from 200 to 800 per square inch, finished with mercerization or singeing processes to enhance absorbency and dimensional stability. The residential end-user segment dominates volume throughput, though hospitality procurement commands premium positioning through contract-grade durability specifications and custom sizing requirements. Cotton maintains structural leadership in the material dimension due to established consumer preference for breathability, while microfiber competes aggressively in economy-tier institutional sourcing where rapid-dry performance outweighs tactile considerations. Online distribution channels are reshaping margin architecture, with direct-to-consumer platforms capturing higher per-unit realization than wholesale bulk contracts.
The OEKO-TEX Standard 100 framework governs chemical residue limits across European import channels, compelling Asian suppliers to reformulate dyeing and finishing chemistries. India's BIS certification requirements for textile flammability and dimensional stability create compliance thresholds for domestic market access that parallel EU technical specifications. The US Consumer Product Safety Commission maintains oversight of children's sleepwear flammability standards, a niche but consequential category for branded linen retailers. Stakeholders must monitor how converging sustainability disclosure mandates across the EU Green Deal and emerging Indian textile sector ESG protocols reshape supplier qualification timelines and capital allocation priorities.
Market Dynamics
Post-pandemic hospitality procurement teams are compressing linen refresh cycles from 36-month intervals to 18-month rotations, creating sustained volume pull through North American and European contract channels while straining South Asian spinning capacity.
Growth Catalysts
- EU Green Deal textile disclosure mandates:OEKO-TEX Standard 100 and GOTS certification requirements are redirecting supplier qualification criteria toward traceable organic cotton sourcing, favoring integrated mills with captive ginning operations.
- Hospitality contract-grade durability specifications:Premium positioning through custom sizing and institutional laundering tolerance is expanding average contract values for Tamil Nadu and Gujarat textile clusters.
- Digital textile printing convergence:AI-driven color matching is narrowing the gap between small-batch customization and mass-production economics, enabling rapid replenishment contracts with North American hospitality chains.
Market Restraints
- Cotton price volatility:Input cost swings in raw lint markets compress spinning margins and destabilize long-term contract pricing for bulk hospitality procurement.
- Tamil Nadu-Gujarat supply concentration:Integrated spinning-weaving-finishing operations cluster in two Indian states, creating geographic vulnerability to monsoon disruption and regional labor actions.
- Microfiber substitution in economy-tier institutional sourcing:Rapid-dry synthetic performance outweighs tactile considerations in budget hospitality and healthcare segments, displacing cotton volume at the low end.
Strategic Opportunities
- Direct-to-consumer platform expansion:Online distribution channels are capturing higher per-unit realization than wholesale bulk contracts, reshaping margin architecture for branded linen retailers.
- CSRD-aligned sustainability reporting:Converging ESG disclosure mandates across European import channels create first-mover advantage for suppliers with verified Scope 3 cotton traceability systems.
- Terry towel technical niche engineering:High-gram-weight institutional bath products occupy an underserved segment between commodity bath linens and luxury retail positioning.
Industry Challenges
- Dyeing chemistry reformulation timelines:OEKO-TEX Standard 100 residue limit compliance requires 12-18 month supplier requalification cycles, delaying contract awards for reformulating Asian mills.
- Integrated spinning-weaving-finishing capex intensity:Backward integration into cotton ginning and captive yarn production demands sustained capital allocation that mid-scale weavers cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed and Bath Linen Market |
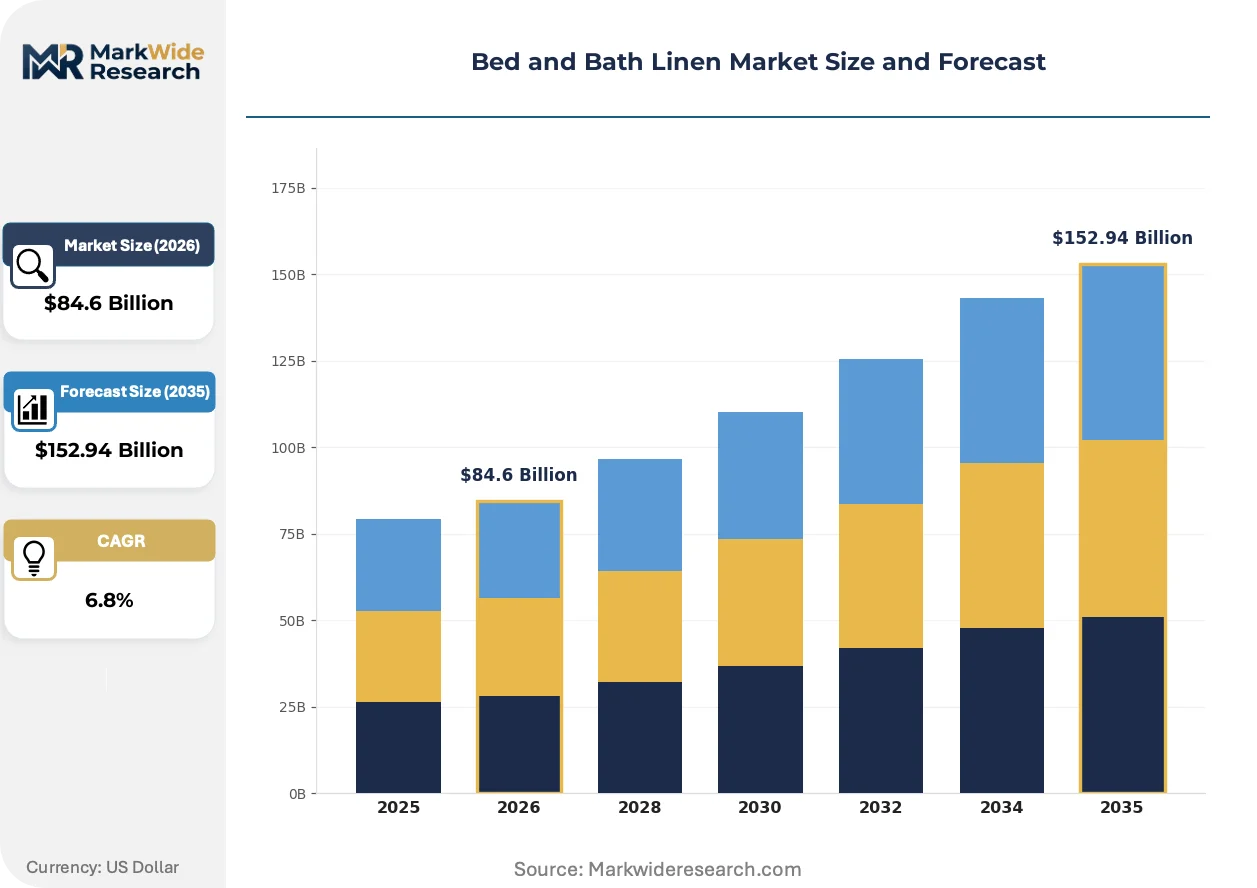
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Towels, Bath Rugs, Table Linens Material: Cotton, Polyester, Linen, Microfiber End User: Residential, Hospitality, Healthcare, Retail Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Alok Industries, American Textile Company, Welspun India, Williams-Sonoma, Avanti Linens, Trident Group, Springs Global, Parachute Home, WestPoint Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed and Bath Linen Market Emerging Trajectories
Digital production technologies and regulatory disclosure mandates are compressing traditional batch-size economics while fragmenting distribution channels away from wholesale concentration.
Digital textile printing is hybridizing conventional rotary screen methods with inkjet deposition systems capable of 2,000-meter production runs. Hospitality procurement teams in Germany and France are adopting these platforms for property-specific color matching without minimum order penalties. The technology is hybridizing mass-production cost structures with customization flexibility previously restricted to artisan workshops.
EU Green Deal textile sector protocols are mandating fiber composition disclosure and recycling content verification across import channels. REACH chemical restriction lists are expanding to cover formaldehyde-based finishing agents common in mercerization processes. European hospitality chains are responding by pre-qualifying Indian suppliers with BIS-certified dimensional stability testing and third-party organic cotton traceability.
Buyer concentration among North American hospitality chains is consolidating procurement decisions into centralized sourcing functions with data-driven replenishment algorithms. Traditional distributor networks are losing share to direct mill relationships with embedded inventory management systems. This pattern is most visible in the United States, where Marriott and Hilton have established dedicated supplier development programs with Tamil Nadu integrated mills.
Bed and Bath Linen Market Segmentation
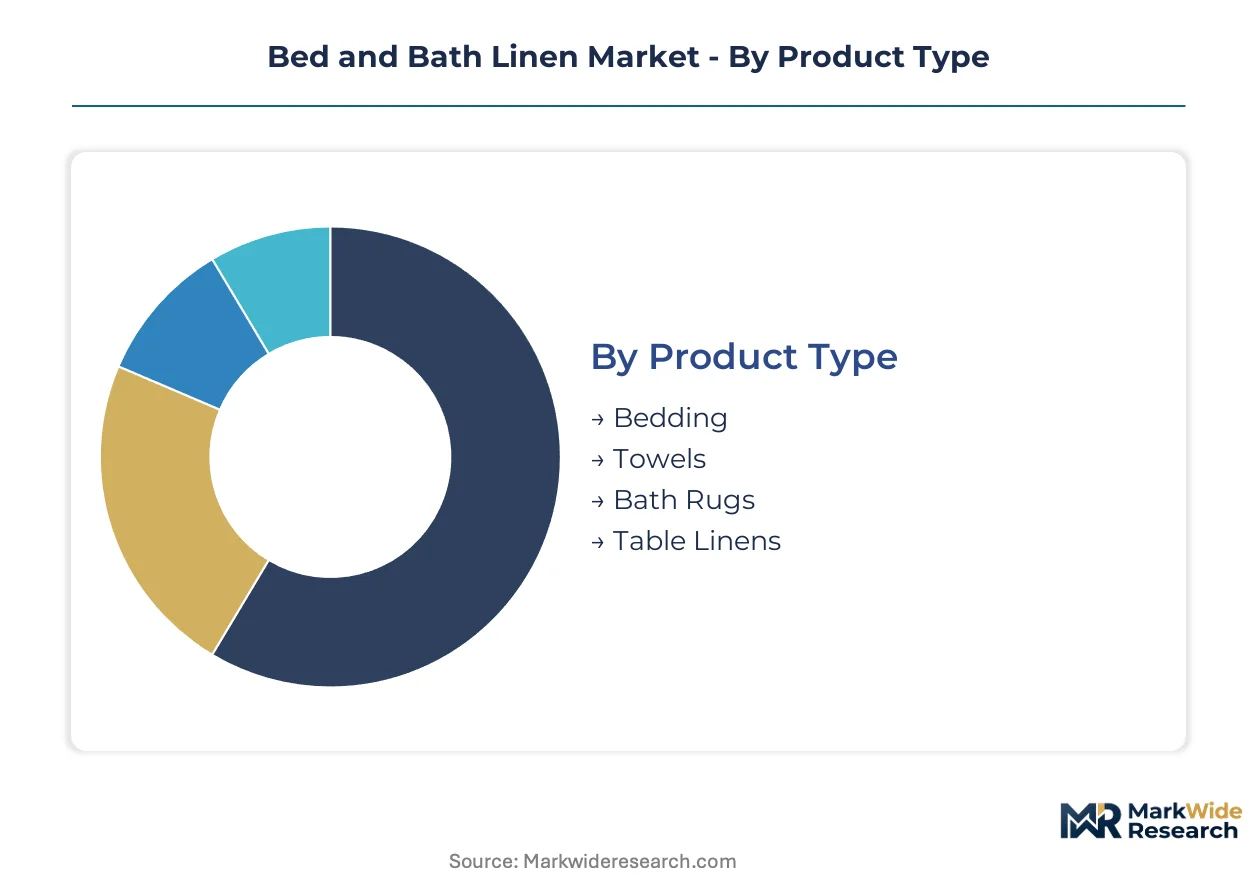
Bed and bath linen procurement cycles vary dramatically across end-use contexts, from 18-month hospitality refresh rotations to decade-long residential replacement patterns. Understanding these velocity differentials shapes inventory positioning and margin capture strategies for suppliers and distributors alike.
Product Type:
Towels turn over fastest in commercial laundering environments, while bedding commands the longest replacement intervals in residential settings.
- Bedding:Comprises sheets, pillowcases, duvet covers, and bedspreads typically constructed from 200-800 thread count cotton weaves. Demand concentrates in North American hospitality chains where Marriott and Hilton have established dedicated supplier development programs with Tamil Nadu integrated mills for contract-grade durability specifications.
- Towels:Terry cloth and velour constructions ranging from 400-800 GSM for institutional applications. Expansion concentrates in high-gram-weight institutional bath products where Trident Group occupies a technical niche between commodity linens and luxury retail positioning.
- Bath Rugs:Tufted cotton and microfiber constructions with non-slip backing systems for moisture absorption at shower egress points.
- Table Linens:Woven damask and jacquard napery for hospitality food service applications with stain-resistant finishing chemistries.
Bedding dominates installed base across residential and hospitality channels. Towels are where expansion concentrates amid compressed hospitality refresh cycles.
Material:
Cost tier positioning separates premium natural fibers from economy synthetic alternatives, with certification grade increasingly determining supplier qualification.
- Cotton:Maintains structural leadership due to established consumer preference for breathability, with OEKO-TEX Standard 100 and GOTS certification requirements redirecting European procurement toward traceable organic cotton sourcing. Welspun India anchors competitive position through backward integration into cotton spinning across Gujarat facilities.
- Microfiber:Rapid-dry synthetic performance outweighs tactile considerations in budget hospitality and healthcare segments, displacing cotton volume at the low end of institutional procurement.
- Polyester:Blended with cotton for wrinkle resistance in economy-tier hospitality sourcing where laundering tolerance exceeds softness priorities.
- Linen:Bast fiber construction prized for thermoregulation in premium residential and boutique hospitality applications with extended product lifecycles.
Cotton dominates installed base across all price tiers. Microfiber is gaining share fastest in economy institutional channels.
End User:
Volume throughput concentrates in residential applications, while premium positioning and contract values favor commercial procurement functions.
- Residential:Individual household consumption patterns with replacement driven by lifecycle events and aesthetic refresh rather than wear failure. Direct-to-consumer platforms are capturing higher per-unit realization than wholesale bulk contracts in this channel.
- Hospitality:Contract-grade durability specifications with custom sizing requirements and institutional laundering tolerance. Post-pandemic procurement teams are compressing refresh cycles from 36-month intervals to 18-month rotations, creating sustained volume pull through North American and European contract channels.
- Healthcare:Antimicrobial finishing requirements and industrial sterilization compatibility for hospital and long-term care facility procurement.
- Retail:Branded merchandise and private label sourcing for department store and specialty channel distribution with seasonal collection turnover.
Residential dominates installed base by unit volume. Hospitality is where margin expansion concentrates through premium contract positioning.
Distribution Channel:
Channel selection determines margin architecture, with direct relationships compressing traditional distributor economics.
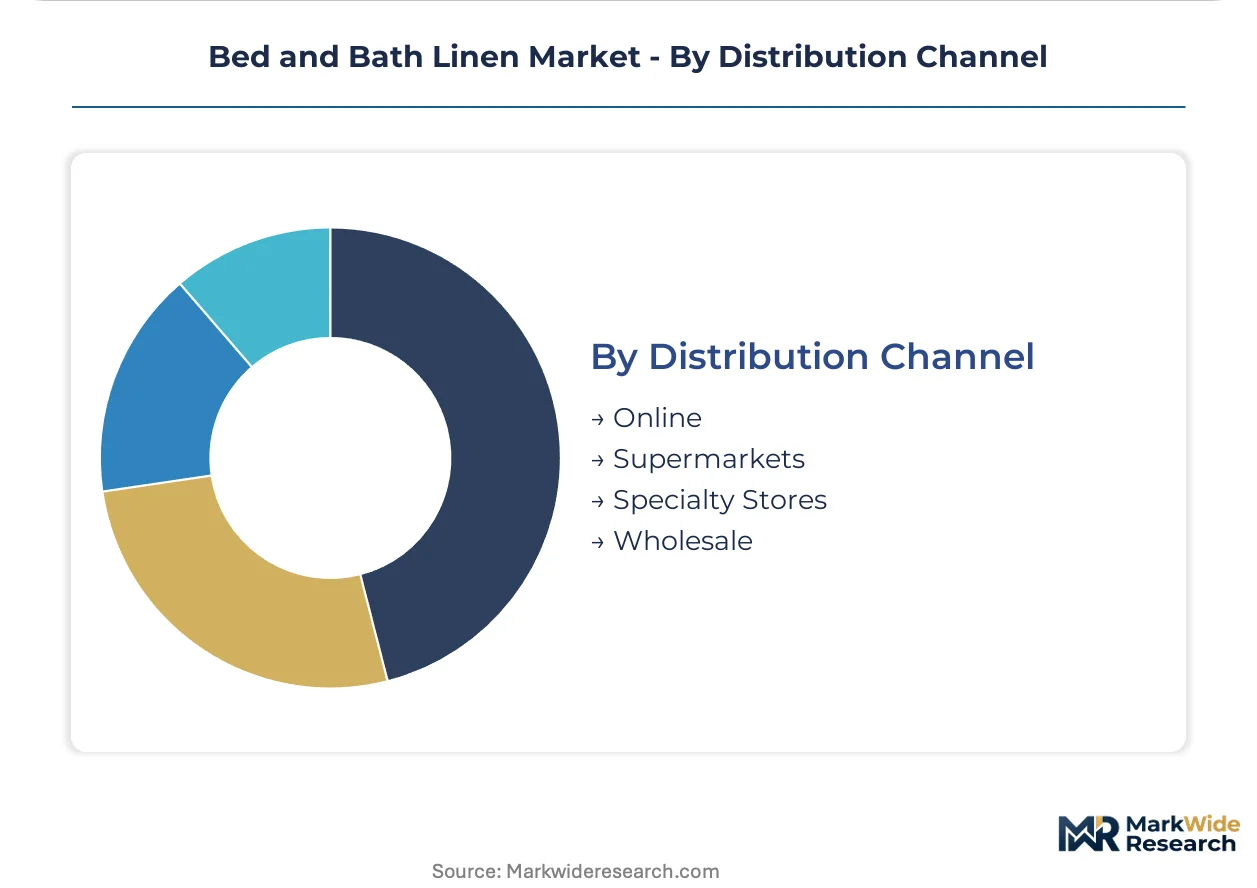
- Online:Direct-to-consumer platforms and brand-owned e-commerce with data-driven replenishment algorithms replacing traditional distributor networks. American Textile Company leverages domestic cut-and-sew operations to sustain rapid replenishment contracts through this channel.
- Wholesale:Bulk contract channels for hospitality and healthcare institutional procurement with embedded inventory management systems and centralized sourcing functions.
- Supermarkets:Mass-market retail distribution for economy-tier residential replacement purchases with high inventory velocity and compressed margins.
- Specialty Stores:Curated assortments for premium residential and gift market positioning with consultative selling environments.
Wholesale dominates installed base in commercial segments. Online is climbing the fastest in residential market share capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports finished bed and bath linens to hospitality procurement teams across Germany, France, and the United States, with Tamil Nadu and Gujarat textile clusters anchoring contract-grade production capacity.
United States
Post-pandemic hospitality chains including Marriott and Hilton compress linen refresh cycles to 18-month rotations, creating sustained volume pull through contract channels. The US Consumer Product Safety Commission maintains flammability oversight for children's sleepwear categories. American Textile Company leverages domestic cut-and-sew operations in southeastern states to sustain rapid replenishment contracts.
Germany
Hotel procurement teams in Frankfurt and Munich adopt digital textile printing platforms for property-specific color matching without minimum order penalties. EU Green Deal textile disclosure mandates and REACH chemical restrictions govern import qualification. Hospitality sourcing concentrates in Baden-Württemberg and Bavaria, where centralized procurement functions deploy data-driven replenishment algorithms.
France
Paris-based hospitality groups and boutique hotel chains drive premium positioning through custom sizing and institutional laundering tolerance specifications. OEKO-TEX Standard 100 certification requirements redirect supplier qualification toward traceable organic cotton sourcing. Lyon and northern textile regions maintain finishing expertise for high-thread-count luxury positioning.
India
Tamil Nadu and Gujarat integrated spinning-weaving-finishing operations achieve cost advantages in bulk hospitality contracts. BIS certification requirements for textile flammability and dimensional stability create compliance thresholds for domestic market access. Welspun India anchors competitive position through backward integration into cotton spinning across Gujarat facilities.
United Kingdom
London hospitality procurement teams consolidate sourcing decisions into centralized functions with embedded inventory management systems. CSRD-aligned sustainability reporting requirements create first-mover advantage for suppliers with verified Scope 3 cotton traceability. Manchester and northwestern textile regions retain technical expertise for institutional terry towel engineering.
Bed and Bath Linen Market Vendor Landscape
On the supply side, the industry is fragmented across integrated textile mills, domestic cut-and-sew operators, and specialty terry towel engineers. Three strategic archetypes dominate: backward-integrated Indian spinning-weaving conglomerates, North American rapid-replenishment specialists with domestic manufacturing, and technical niche players in high-gram-weight institutional bath products. Competitive moves concentrate on direct mill relationships replacing distributor networks, and CSRD-aligned sustainability certification pre-qualification.
Among India-based integrated mills, Welspun India and Trident Group exemplify contrasting archetypes. Welspun India represents the backward-integrated model with captive cotton spinning capacity. Trident Group occupies a position in terry towel technical niche engineering. American Textile Company anchors the North American rapid-replenishment specialist archetype with domestic operations. These three entities illustrate how geographic and capability positioning stratifies competitive access to hospitality contract channels.
| Leading Market Players |
|---|
| Alok Industries |
| American Textile Company |
| Welspun India |
| Williams-Sonoma |
| Avanti Linens |
| Trident Group |
| Springs Global |
| Parachute Home |
| WestPoint Home |
| Others |
Supply Flow & Price Mechanics
The Nhava Sheva-Mundra freight corridor connecting Gujarat textile clusters to European ports shapes cost dynamics across the Bed and Bath Linen Market, compressing margins for non-integrated weavers while amplifying price differentiation between OEKO-TEX-certified and uncertified supply tiers.
Pricing Analysis
Rotary screen printing versus emerging inkjet deposition systems versus hybrid digital platforms creates a three-tier technology-generation pricing structure across contract manufacturing. Certification grade and volume scale drive price differentiation, with GOTS-organic cotton commanding premiums over conventional sourcing. Pricing pressure stems from microfiber substitution in budget hospitality procurement, where rapid-dry performance outweighs tactile quality. Economy-tier institutional buyers exhibit highest price sensitivity; boutique hospitality chains with custom color-matching requirements show lowest.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk calculus for contract-grade linen procurement. Manufacturing concentrates in India, Turkey, and Portugal, with raw cotton drawing from domestic ginning operations in Gujarat and imported lint from African origins. Single-source vulnerability persists in Tamil Nadu-Gujarat spinning concentration. Distribution runs through direct mill relationships with embedded inventory management systems, bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive cotton spinning represents the scarce capability separating contract winners from commodity suppliers in this market, with OEKO-TEX requalification timelines creating additional barriers to mid-scale entrants.
For Market Incumbents: Insulate contract positions by accelerating BIS certification for dimensional stability testing and embedding inventory management systems with Marriott and Hilton procurement functions. Microfiber substitution in economy-tier healthcare sourcing threatens volume; defend through terry towel technical niche engineering in high-gram-weight institutional bath products. For New Entrants and Emerging Players: Healthcare antimicrobial finishing requirements in Germany and France represent underpenetrated white-space where established hospitality suppliers lack regulatory familiarity. Target hospital procurement committees with industrial sterilization compatibility specifications. Enter through direct-to-consumer platforms capturing higher per-unit realization than wholesale bulk contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate textile divisions lacking CSRD-aligned Scope 3 cotton traceability systems. Long-term viability favors integrated spinning-weaving-finishing operations with captive ginning capacity over asset-light trading houses. Watch for EU Green Deal disclosure mandate enforcement as inflection signal for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Spinning | Welspun India anchors competitive positioning through captive yarn production in Gujarat facilities. |
| Digital Textile Printing Platform Deployment | AI-driven color matching enables property-specific hospitality contracts without minimum order penalties. |
| OEKO-TEX Standard 100 Certification Investment | REACH chemical restrictions in EU channels compel 12-18 month supplier requalification cycles. |
| Direct-to-Consumer Channel Expansion | American Textile Company leverages domestic cut-and-sew operations for rapid replenishment contracts. |
| Terry Towel Technical Niche Engineering | Trident Group occupies high-gram-weight institutional bath segment between commodity and luxury positioning. |
Methodological Framework
Desk research of EU Green Deal textile protocols, BIS certification requirements, and REACH chemical restriction lists preceded structured interviews with hospitality procurement directors, integrated mill operations heads, and textile finishing chemists. Primary fieldwork with Tamil Nadu and Gujarat spinning-weaving conglomerates combined with secondary validation through customs export data and hospitality chain annual sourcing disclosures. Bottom-up contract value estimates triangulated against top-down market sizing across product type, material, and end-user dimensions.
Fixed assumptions held cotton price volatility within historical bands and OEKO-TEX requalification timelines at 12-18 months across the projection horizon. Segmentation modeling incorporated product type, material certification grade, end-user procurement velocity, and distribution channel margin architecture. CAGRs derived from weighted average of historical contract value expansion and projected hospitality refresh cycle compression. Industry-specific inputs included institutional laundering tolerance specifications and digital printing adoption curves in German and French hospitality markets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish integrated mills or sudden REACH chemical restriction expansion would shift outcomes. Macroeconomic deviation in cotton lint markets, regulatory acceleration in EU textile disclosure mandates, or breakthrough rapid-dry natural fiber technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Table Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Duvets Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Bedroom Linen Market