
 Kitchen Linens Market | 2026-2036
Kitchen Linens Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Linens Market Insights
Direct-to-consumer e-commerce is fragmenting as legacy department store partnerships lose share to specialty kitchen portals and brand-owned storefronts. Williams-Sonoma Inc. leverages its catalog heritage and digital infrastructure to control premium discovery. Coyuchi anchors its position through organic cotton certification and transparent supply chains. Rough Linen specializes in small-batch European flax sourcing to differentiate against mass-market competitors.
Kitchen linens encompass woven and knitted textile goods—dish towels, aprons, oven mitts, and tablecloths—typically constructed from cotton, linen, polyester, or blended fibers with thread counts ranging from 120 to 400 GSM for absorbency and heat resistance. These products serve protective, hygienic, and decorative functions across residential food preparation and commercial foodservice environments. Cotton dish towels lead volume due to universal household penetration and replacement frequency, while linen tablecloths command the strongest margin pools in the premium tier where heritage weaving commands price premiums. Polyester blends compete aggressively in commercial kitchens and catering services where industrial laundering demands synthetic durability and rapid drying.
The EU's Ecodesign for Sustainable Products Regulation and REACH chemical restrictions shape fiber sourcing and dye formulations for exporters targeting European buyers. The US EPA and state-level California Proposition 65 compliance requirements influence flame-retardant treatments and formaldehyde limits in imported kitchen textiles. Stakeholders must monitor evolving digital product passport mandates and decide whether to front-run traceability investments or absorb compliance costs as market-access barriers tighten.
Market Dynamics
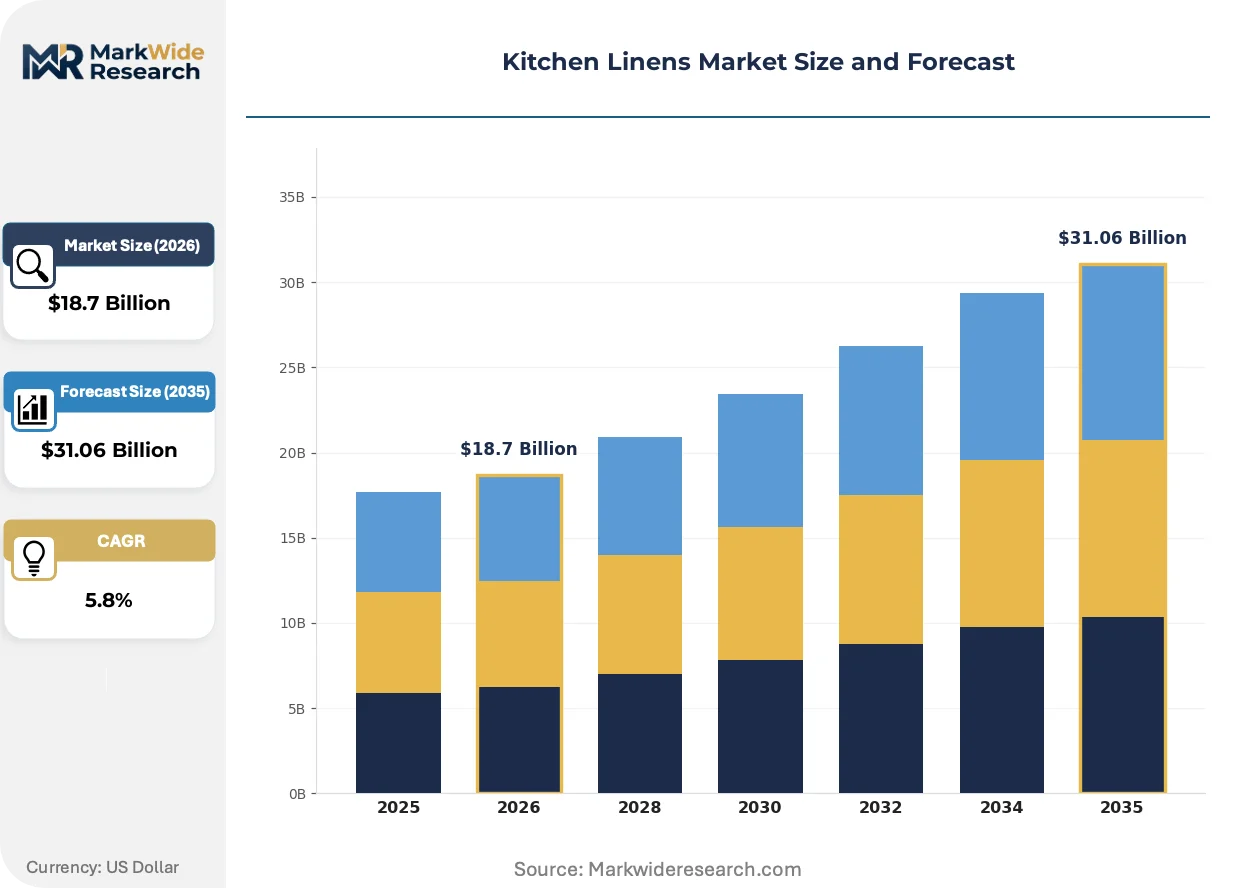
The EU's Ecodesign for Sustainable Products Regulation is forcing fiber disclosure and durability testing upgrades across export supply chains, compressing margins for undifferentiated suppliers while rewarding certified organic and traceable sourcing investments.
Growth Catalysts
- REACH chemical compliance:European import standards for formaldehyde limits and azo dye bans are accelerating R&D into plant-based colorants and low-impact finishing processes among Turkish and Indian exporters.
- Independent restaurant procurement:Boutique cafés and chef-owned establishments in France, Italy, and Spain are expanding commercial-grade linen orders for open-kitchen aesthetics and brand differentiation.
- Handloom cluster concentration:Kerala and Tamil Nadu weaving cooperatives anchor premium export capacity for heritage linen tablecloths, creating geographic moats against mass-market polyester competitors.
Market Restraints
- Cotton price volatility:Input cost swings from climate-impacted harvests in Gujarat and Texas squeeze margin predictability for mid-tier towel manufacturers.
- Polyester substitution threat:Commercial catering services prioritize synthetic blends for industrial laundering durability, capping natural fiber penetration in high-volume foodservice accounts.
- EU digital product passport friction:Traceability infrastructure requirements create compliance cost barriers for small-batch artisan suppliers without ERP integration.
Strategic Opportunities
- US EPA Safer Choice certification:Federal procurement preferences for verified low-toxicity textiles open institutional channels for certified organic cotton towel suppliers.
- Specialty kitchen portal growth:Direct-to-consumer storefronts and curated culinary platforms are displacing legacy department store shelf space for premium discovery.
- Flax-linen convergence with technical finishing:European flax sourcing combined with antimicrobial treatments targets healthcare-adjacent foodservice hygiene requirements.
Industry Challenges
- Artisan skill attrition:Master weaver retirement rates in Tamil Nadu exceed apprenticeship pipeline replenishment, threatening small-batch heritage production continuity.
- Multi-certification timeline compression:Simultaneous GOTS organic, OEKO-TEX, and EU Ecodesign compliance audits strain quality assurance bandwidth for export-focused mills.
- Legacy dyehouse retrofit capex:Waterless dyeing and closed-loop finishing equipment upgrades demand capital allocations that conflict with short-term margin defense priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Linens Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dish Towels, Aprons, Oven Mitts, Tablecloths Material: Cotton, Linen, Polyester, Blends Application: Home Use, Commercial Kitchens, Catering Services, Restaurants Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | Williams-Sonoma Inc., All-Clad, Coyuchi, Yves Delorme, Inc., Maison d’Hermine, McGee & Co., Stoffer Home, Kitchen Linen Company, Rough Linen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Linens Market Trends and Innovations
Digital traceability infrastructure and fiber-to-finish transparency tools are compressing information asymmetry between suppliers and buyers, while regulatory chemical restrictions and procurement channel fragmentation reshape competitive positioning.
Blockchain-enabled supply chain verification is virtualizing provenance documentation for organic cotton and European flax batches. Williams-Sonoma and specialty kitchen portals are piloting QR-linked farm-to-shelf tracking for premium tier differentiation. This transparency layer is compressing price premiums for uncertified competitors while enabling margin capture for verified heritage suppliers.
REACH chemical restrictions and the EU's Ecodesign for Sustainable Products Regulation are tightening azo dye bans and formaldehyde limits for textile imports. Turkish finishing houses and Indian dyehouses face reformulation costs or market exclusion. Premium linen tablecloth exporters targeting Northern European hospitality are accelerating plant-based colorant R&D to maintain shelf access.
Buyer concentration among specialty kitchen portals and brand-owned direct storefronts is fragmenting legacy wholesale distribution. Independent restaurants and boutique cafés in France and Italy now source through curated B2B platforms rather than textile jobbers. This channel shift is most visible in Mediterranean markets where open-kitchen aesthetics drive visible linen investment.
Kitchen Linens Market Segmentation
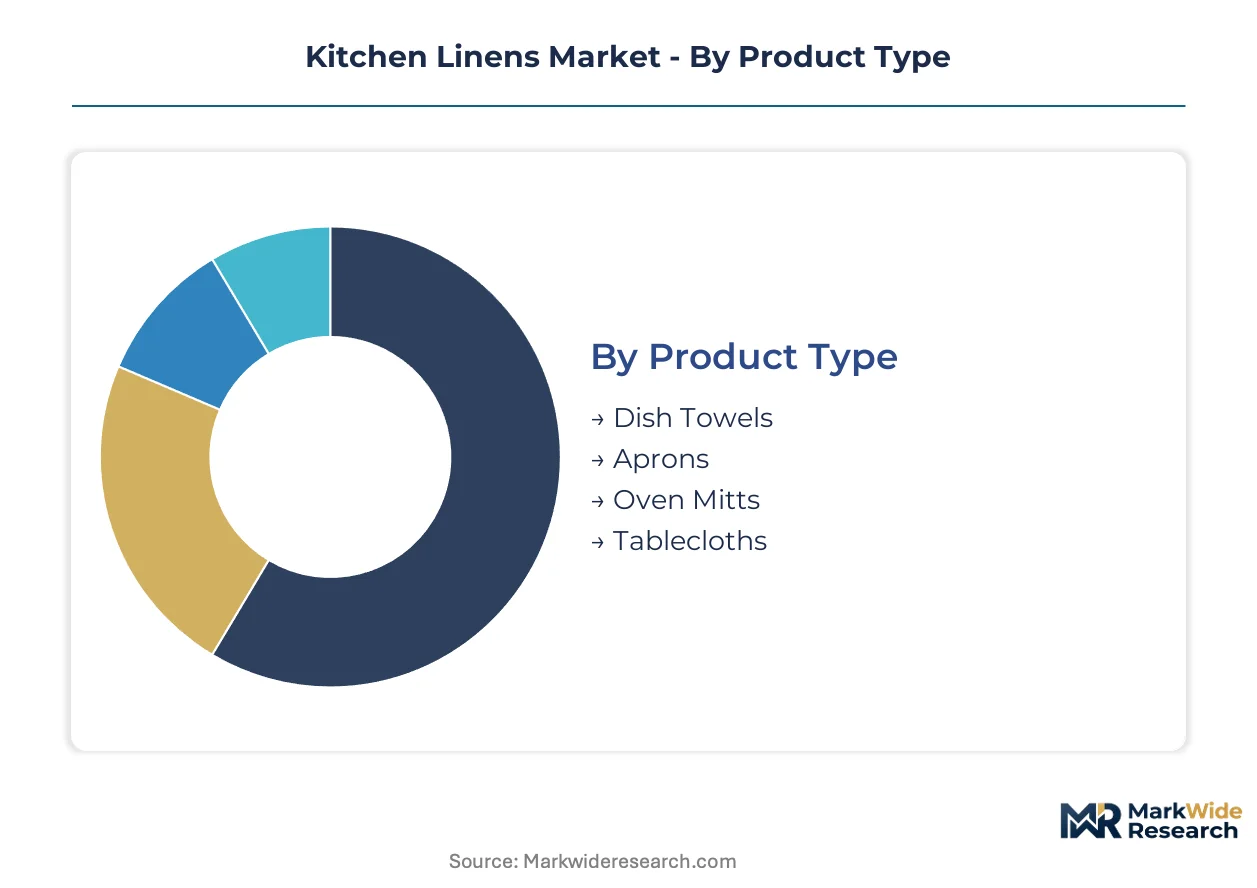
Kitchen linens fragment across four structural dimensions that determine margin capture and channel access. Product type and material composition anchor manufacturing configuration, while application and price tier dictate distribution strategy and certification requirements.
Product Type:
Volume concentration across the four product categories tracks replacement frequency and visibility in end-use settings.
- Dish Towels:Woven cotton constructions dominate with thread counts from 120 to 400 GSM for absorbency. Residential replacement cycles drive volume concentration in India and Turkey, where Gujarat cotton clusters and Denizli terry mills supply mass-market retail channels.
- Tablecloths:Heritage linen weaving commands the strongest margin pools in premium tiers. Kerala and Tamil Nadu handloom cooperatives anchor export capacity for Northern European hospitality procurement, where open-kitchen aesthetics drive visible linen investment.
- Aprons:Cross-functional protective garments span domestic cooking and professional foodservice with reinforced stitching and adjustable fastenings.
- Oven Mitts:Heat-resistant padding requirements favor quilted cotton and silicone-composite constructions for residential safety compliance.
Dish towels hold installed capacity. Tablecloths is rotating up the share rankings.
Material:
Raw material selection determines regulatory pathway, laundering durability, and price positioning against synthetic substitutes.
- Cotton:Universal household penetration stems from natural absorbency and biodegradability. Climate-impacted harvest volatility in Gujarat and Texas squeezes margin predictability for mid-tier towel manufacturers dependent on spot cotton markets.
- Linen:European flax sourcing from France and Belgium combined with antimicrobial finishing targets healthcare-adjacent foodservice hygiene requirements. Small-batch heritage production in Kerala faces artisan skill attrition as master weaver retirements exceed apprenticeship pipelines.
- Polyester:Synthetic durability and rapid drying characteristics dominate commercial catering procurement where industrial laundering demands cap natural fiber penetration.
- Blends:Cotton-polyester combinations balance cost efficiency with functional performance for high-volume foodservice accounts.
Cotton holds installed capacity. Linen is climbing the fastest.
Application:
End-use environment shapes certification requirements, laundering protocols, and procurement channel selection.
- Home Use:Residential replacement frequency concentrates volume in mass-market retail and direct-to-consumer specialty portals. California Proposition 65 compliance requirements influence flame-retardant treatments and formaldehyde limits in imported textiles for US households.
- Restaurants:Boutique cafés and chef-owned establishments in France, Italy, and Spain expand commercial-grade linen orders for open-kitchen aesthetics. Curated B2B platforms displace traditional textile jobbers in Mediterranean procurement channels.
- Commercial Kitchens:Industrial laundering durability demands drive polyester blend preference over natural fibers in high-volume institutional accounts.
- Catering Services:Event-based rental and rapid turnaround requirements favor synthetic constructions with commercial laundry compatibility.
Home Use holds installed capacity. Restaurants is gaining share fastest.
Price Tier:
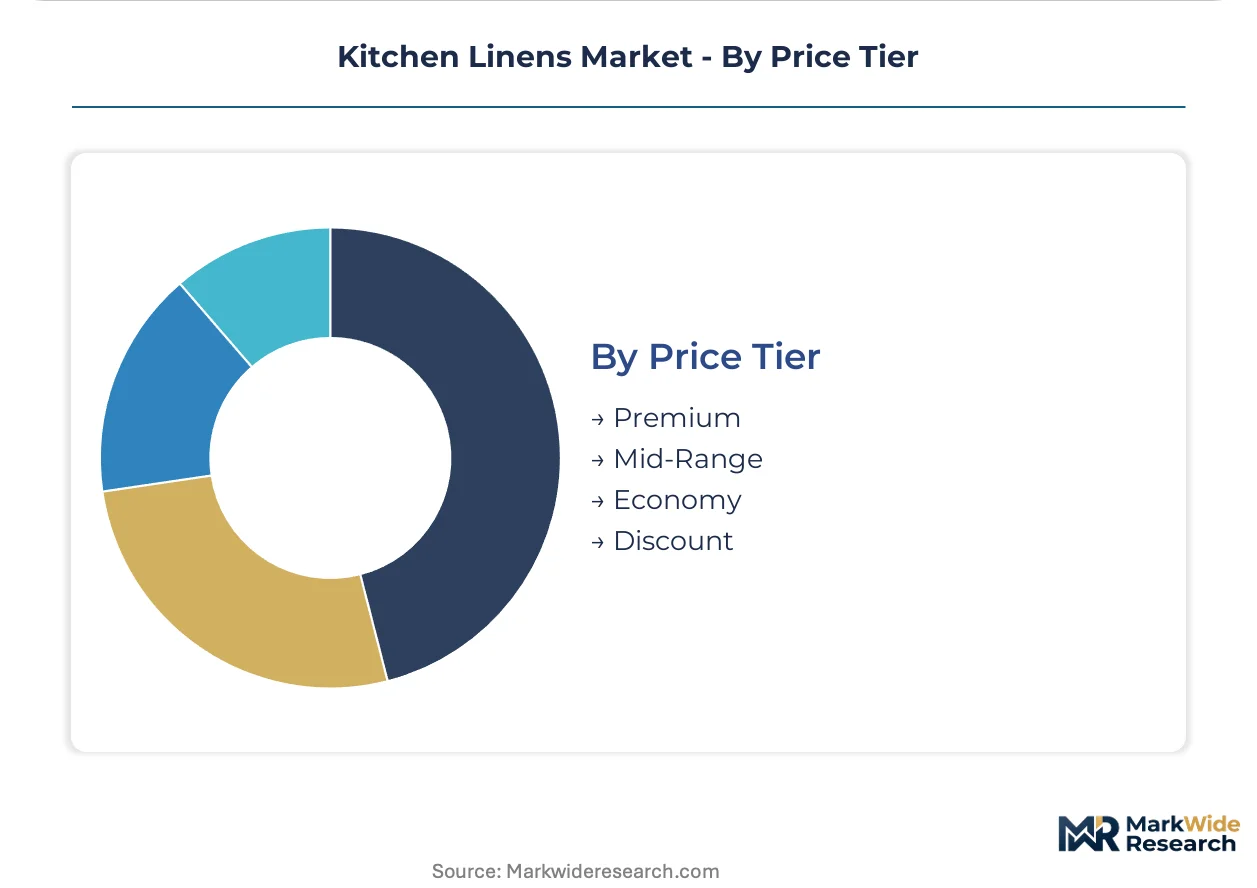
Cost stratification aligns with certification grade, supply chain transparency, and channel positioning against mass-market competition.
- Premium:GOTS organic and OEKO-TEX certifications combined with blockchain-enabled farm-to-shelf tracking capture margin from transparency-demanding buyers. Williams-Sonoma and specialty kitchen portals pilot QR-linked provenance documentation for heritage linen differentiation.
- Mid-Range:Quality cotton constructions without full organic certification serve price-conscious households seeking durability over traceability.
- Economy:Basic polyester and cotton-polyester blends target high-frequency replacement cycles in commercial foodservice and budget retail.
- Discount:Undifferentiated imports face compressed margins from EU Ecodesign fiber disclosure and durability testing upgrades that reward certified sourcing investments.
Premium holds installed capacity. Economy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Northern Europe's textile import infrastructure, connecting Indian handloom clusters to hospitality procurement networks in France and Germany. This maritime corridor channels certified organic cotton and heritage linen through Dutch distribution hubs before final-mile delivery to boutique restaurants and specialty retail channels.
United States
Williams-Sonoma's San Francisco headquarters anchors premium direct-to-consumer distribution, while California Proposition 65 compliance requirements reshape flame-retardant treatment standards for imported kitchen textiles. The Port of Long Beach handles bulk cotton towel shipments from Gujarat and Denizli before inland rail distribution to Chicago and New York retail corridors.
France
Boutique cafés in Lyon and Marseille expand commercial-grade linen procurement for open-kitchen aesthetics, driving visible textile investment. REACH chemical restrictions enforced by ECHA accelerate plant-based colorant R&D among exporters targeting French hospitality buyers. Normandy's flax cultivation belt supplies raw fiber to premium weaving cooperatives in Kerala and Tamil Nadu.
India
Gujarat's cotton clusters and Tamil Nadu handloom cooperatives anchor global supply for mid-tier towels and heritage tablecloths respectively. BIS fiber grading standards and DGFT export certification requirements shape quality assurance protocols for EU-bound shipments. Master weaver retirements in Kerala threaten small-batch production continuity despite apprenticeship program expansion.
Germany
EU Ecodesign for Sustainable Products Regulation implementation through national market surveillance authorities tightens fiber disclosure mandates for textile imports. Hamburg's port infrastructure channels Turkish finishing house output toward Central European foodservice distributors. Berlin's boutique restaurant density drives commercial linen rental demand through curated B2B procurement platforms.
Italy
Chef-owned establishments in Rome and Florence prioritize visible kitchen linens for brand differentiation in competitive dining markets. ANSM chemical safety guidelines align with broader EU azo dye restrictions affecting import compliance costs. Prato's textile finishing district processes Indian cotton shipments before redistribution to Mediterranean hospitality accounts.
Kitchen Linens Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply chains. The vendor base organizes around three structural tiers: catalog-era retailers with digital infrastructure, certified organic specialists with transparent sourcing, and small-batch heritage weavers with geographic moats. Consolidation pressure concentrates among mid-tier towel manufacturers facing cotton price volatility and compliance cost compression. Dominant competitive moves include backward integration into captive cotton sourcing and specialty portal partnerships displacing legacy wholesale distribution.
Within the certified organic tier, Coyuchi exemplifies transparent supply chain positioning through GOTS and OEKO-TEX certification investments. Rough Linen occupies the small-batch heritage vector with European flax sourcing specialization. Williams-Sonoma Inc. anchors the platform-integrator archetype, leveraging catalog heritage and digital infrastructure to control premium discovery channels. These three represent divergent strategic responses to regulatory tightening and procurement channel fragmentation.
| Leading Market Players |
|---|
| Williams-Sonoma Inc. |
| All-Clad |
| Coyuchi |
| Yves Delorme, Inc. |
| Maison d'Hermine |
| McGee & Co. |
| Stoffer Home |
| Kitchen Linen Company |
| Rough Linen |
| Others |
Pricing and Supply Chain Analysis
Gujarat's cotton clusters and Tamil Nadu handloom cooperatives anchor upstream capacity, concentrating margin capture downstream among certified organic specialists and heritage weavers who command transparency premiums. Price differentiation between mass-market polyester blends and traceable European linen reflects this geographic supply asymmetry.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers capture margin through GOTS organic and blockchain-enabled provenance documentation, while economy tiers face compression from undifferentiated polyester substitution. Pricing pressure stems from EU Ecodesign compliance costs that reward certified sourcing investments. Commercial foodservice buyers exhibit highest price sensitivity due to industrial laundering volume requirements.
Supply Chain Analysis
Turkish finishing houses in Denizli and Indian weaving cooperatives in Kerala hold contract-manufacturing concentration for terry production and heritage tablecloths respectively. Raw material flows draw from Normandy flax cultivation, Gujarat cotton harvests, and Belgian linen fiber processing. Single-source vulnerability concentrates in master weaver retirement pipelines that exceed apprenticeship replenishment. Distribution runs through Dutch port infrastructure at Rotterdam before final-mile delivery to specialty kitchen portals and boutique restaurant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kitchen linens market is recovering from cyclical input cost volatility as climate-impacted cotton harvests normalize and EU regulatory compliance investments mature.
For Market Incumbents: Build traceability infrastructure moats through blockchain-enabled farm-to-shelf verification and captive organic cotton sourcing in Gujarat. Defend against polyester substitution in commercial foodservice by accelerating antimicrobial linen finishing R&D. Deepen backward integration into Kerala handloom cooperatives to secure heritage production continuity against artisan skill attrition. For New Entrants and Emerging Players: Pursue white-space opportunities in curated B2B procurement platforms serving Mediterranean boutique restaurants with open-kitchen aesthetics. Target US institutional channels through EPA Safer Choice certification for federal procurement preference. Enter via specialty kitchen portal partnerships that displace legacy department store shelf access. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with certified organic positioning and transparent European flax supply chains. Long-term viability favors assets with multi-certification bandwidth spanning GOTS, OEKO-TEX, and evolving EU digital product passport requirements. Watch apprenticeship pipeline ratios in Tamil Nadu as inflection indicator for heritage production capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cotton Sourcing | Captive Gujarat supply secures margin predictability against spot market volatility. |
| Blockchain-Enabled Provenance Documentation | QR-linked tracking compresses price premiums for uncertified competitors. |
| Antimicrobial Linen Finishing Development | Technical treatments target healthcare-adjacent foodservice hygiene requirements. |
| Specialty Kitchen Portal Partnership | Direct-to-consumer storefronts displace legacy wholesale distribution channels. |
| EU Digital Product Passport Compliance | Traceability infrastructure investments preempt market-access barrier tightening. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with brand managers at specialty kitchen portals, category buyers at curated B2B platforms, procurement leads at boutique restaurant groups, and master weavers at Tamil Nadu cooperatives; and secondary validation against customs trade records, DGFT export certification databases, and EU Ecodesign implementation guidance. Bottom-up volume modeling triangulated with top-down market sizing across product type, material composition, application environment, and price tier segments.
Forecast inputs considered fiber price trajectories, regulatory compliance cost curves, and channel migration patterns across the projection horizon. Segmentation dimensions modeled included product category, raw material grade, end-use setting, and certification tier. CAGRs derived from historical replacement cycle analysis and procurement channel shift elasticity. Industry-specific inputs incorporated climate-impacted cotton yield variability and artisan skill pipeline demographics.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mass-market polyester suppliers would shift outcomes through accelerated price competition. Quarterly review of EU digital product passport implementation timelines and Kerala apprenticeship enrollment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Duvets Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Europe Bed and Bath Linen Market