
 Tele-Care Market | 2026-2036
Tele-Care Market Size, Share, and Industry Trends Forecast 2026-2036
Tele-Care Market Analytics
The tele-care sector is consolidating around two distinct performance tiers. Enterprise-grade platforms with FDA-cleared diagnostic integrations and dedicated network infrastructure command premium positioning, while lightweight consumer-facing apps compete on accessibility and cost. Teladoc Health anchors the high-acuity segment through its comprehensive specialist access model. Koninklijke Philips sustains hardware-software convergence advantages in remote patient monitoring. Amwell differentiates through payer-centric deployment and embedded insurance workflows.
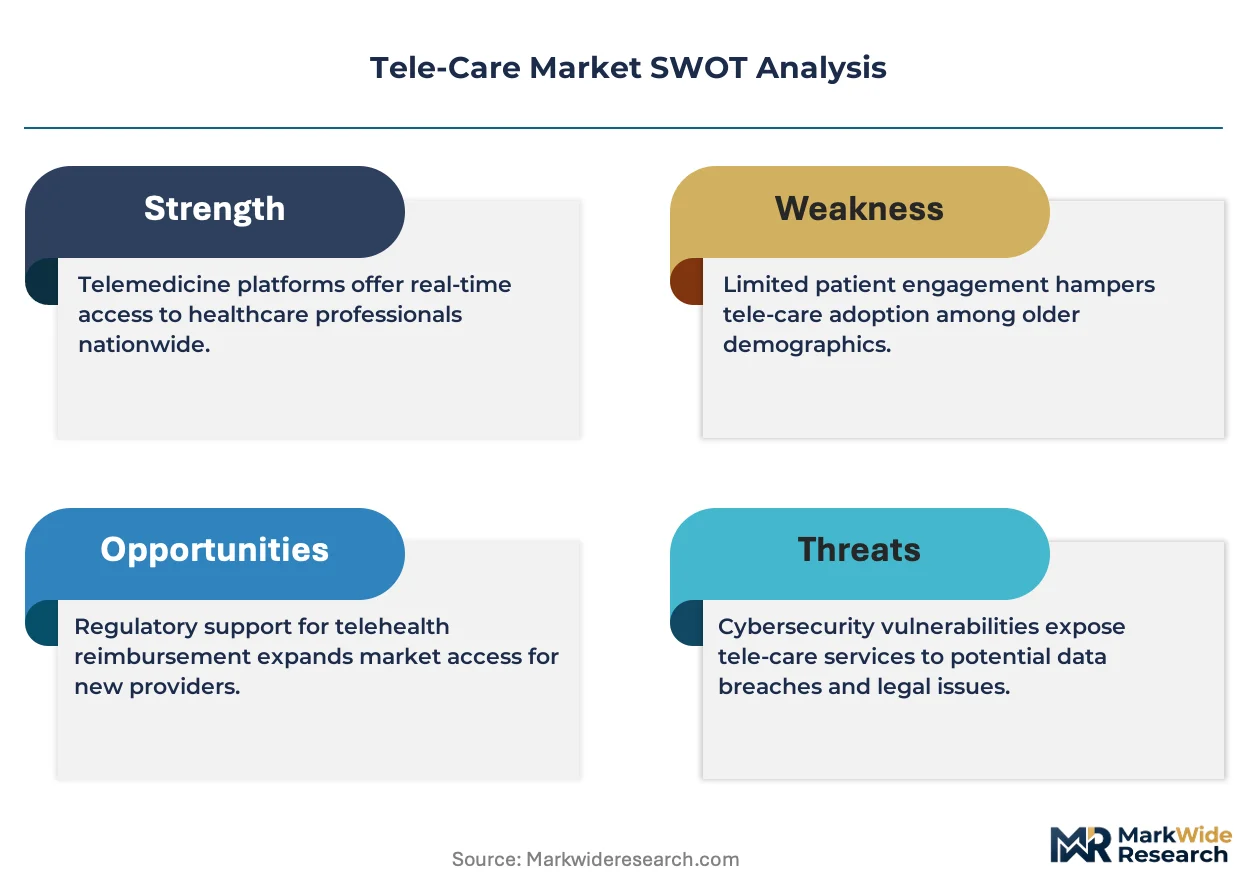
Tele-care encompasses the delivery of clinical and non-clinical health services through synchronous and asynchronous digital channels, typically requiring HIPAA-compliant encryption, sub-150-millisecond latency for real-time video, and interoperability with electronic health record systems. Its primary purpose is to extend diagnostic reach, reduce facility-dependent costs, and enable continuous care outside traditional settings. Remote monitoring and teletherapy represent the fastest-expanding service categories as chronic disease prevalence rises and mental health parity gains enforcement. Wearable devices and mobile apps capture disproportionate investment flow among technology segments, though video conferencing retains the largest transaction volume. Cloud-based delivery dominates new implementations, while hybrid architectures persist in security-sensitive provider environments.
FDA digital health guidance, HIPAA security rule enforcement, and CMS reimbursement policies collectively determine product viability and provider economics in the United States. The EU Medical Device Regulation and GDPR data-processing requirements shape market access conditions across European member states. Japan's Ministry of Health, Labour and Welfare reimbursement codes and South Korea's MFDS software-as-medical-device framework are accelerating East Asian platform deployment. Stakeholders must track evolving cross-border data-localization mandates and interoperability certification standards as determinants of scalable market participation.
Market Dynamics
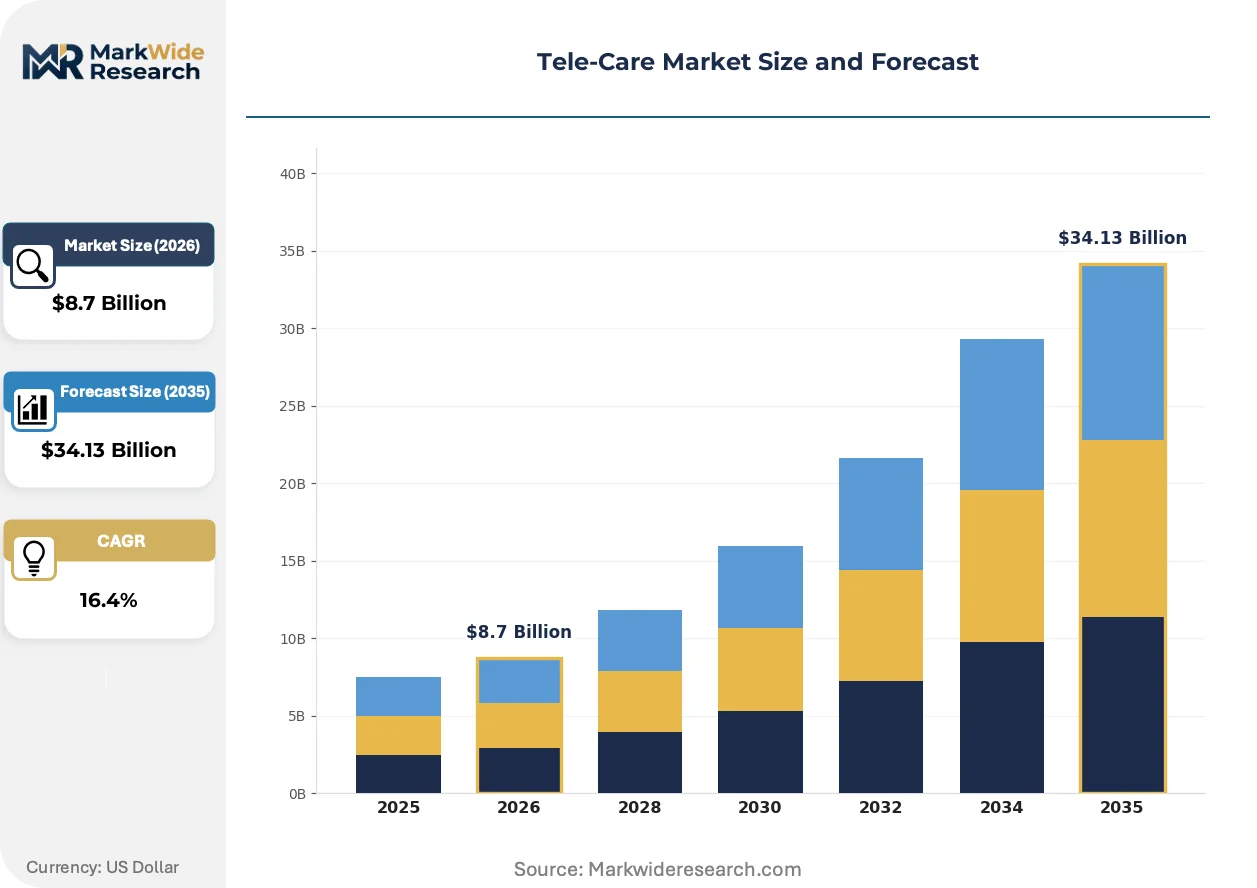
Reimbursement parity mandates are restructuring provider economics and accelerating platform consolidation across the tele-care sector. CMS reimbursement codes in the United States, combined with equivalent frameworks in Germany and Japan, are forcing health systems to integrate digital channels into standard care workflows.
Growth Catalysts
- CMS Reimbursement Parity:Medicare reimbursement equivalence for telehealth services in the United States eliminates financial disincentives for provider adoption.
- Japan's MHLW Reimbursement Codes:Ministry of Health, Labour and Welfare coverage expansion for remote monitoring enables platform deployment in aging municipalities.
- Cloud-Native Architectures:Scalable infrastructure deployment reduces capital barriers for mid-sized health system implementations.
Market Restraints
- GDPR Data Localization:EU cross-border patient data transfer restrictions fragment platform architecture requirements.
- Legacy EHR Integration Costs:Proprietary electronic health record systems impose interoperability penalties on new entrants.
- Specialist Shortage Concentration:Rural United States physician density gaps limit high-acuity service delivery regardless of platform capability.
Strategic Opportunities
- Brazil's ANVISA Digital Health Pathway:Streamlined software-as-medical-device registration creates first-mover advantages in Latin America's largest health market.
- AI-Augmented Diagnostic Triage:Machine learning integration with FDA-cleared algorithms expands scope of reimbursable asynchronous consultations.
- Retail Pharmacy Channel Expansion:CVS Health and Walgreens clinic networks embed tele-care into high-frequency consumer touchpoints.
Industry Challenges
- HIPAA Security Rule Compliance:Sub-150-millisecond latency requirements for real-time video conflict with end-to-end encryption overhead.
- Interoperability Certification Delays:ONC certification timelines stretch 18-24 months, freezing platform updates during review periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tele-Care Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Consultation, Teletherapy, Telesurgery, Remote Monitoring Technology: Video Conferencing, Mobile Apps, Wearable Devices, Chatbots End User: Patients, Healthcare Providers, Insurance Companies, Employers Delivery Mode: Cloud-based, On-premise, Mobile-based, Hybrid |
| Companies Covered | Teladoc Health, Koninklijke Philips, Medtronic, Amwell, GE Healthcare, Doctor On Demand, Abbott Laboratories, Johnson & Johnson, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tele-Care Market Evolving Landscape
Edge computing architectures and ambient monitoring sensors are collapsing the distance between clinical-grade measurement and patient environments. These shifts are redistributing diagnostic authority from centralized facilities toward continuous, algorithm-mediated surveillance.
Continuous glucose monitors and blood pressure wearables are decentralizing chronic disease management from quarterly clinic visits toward daily algorithm-adjusted interventions. Medicare Advantage plans in the United States are deploying these devices to high-risk enrollees within 48 hours of hospital discharge. The structural consequence is compressing emergency department utilization for heart failure and diabetes complications.
The EU Medical Device Regulation's software classification rules are forcing platform developers to segregate diagnostic modules from wellness features to avoid full MDR certification burdens. Germany's national health system is requiring MDR-compliant modules for any remote monitoring reimbursed under statutory insurance. This is bifurcating the European market between certified clinical platforms and consumer-grade wellness applications.
Employer-sponsored health plans are unbundling tele-mental health from comprehensive benefits and purchasing direct contracts with specialized platforms. Large self-insured employers in the United States are negotiating per-employee-per-month rates that bypass traditional insurance intermediaries. This channel shift is most advanced in technology and financial services sectors with concentrated white-collar workforces.
Tele-Care Market Segmentation
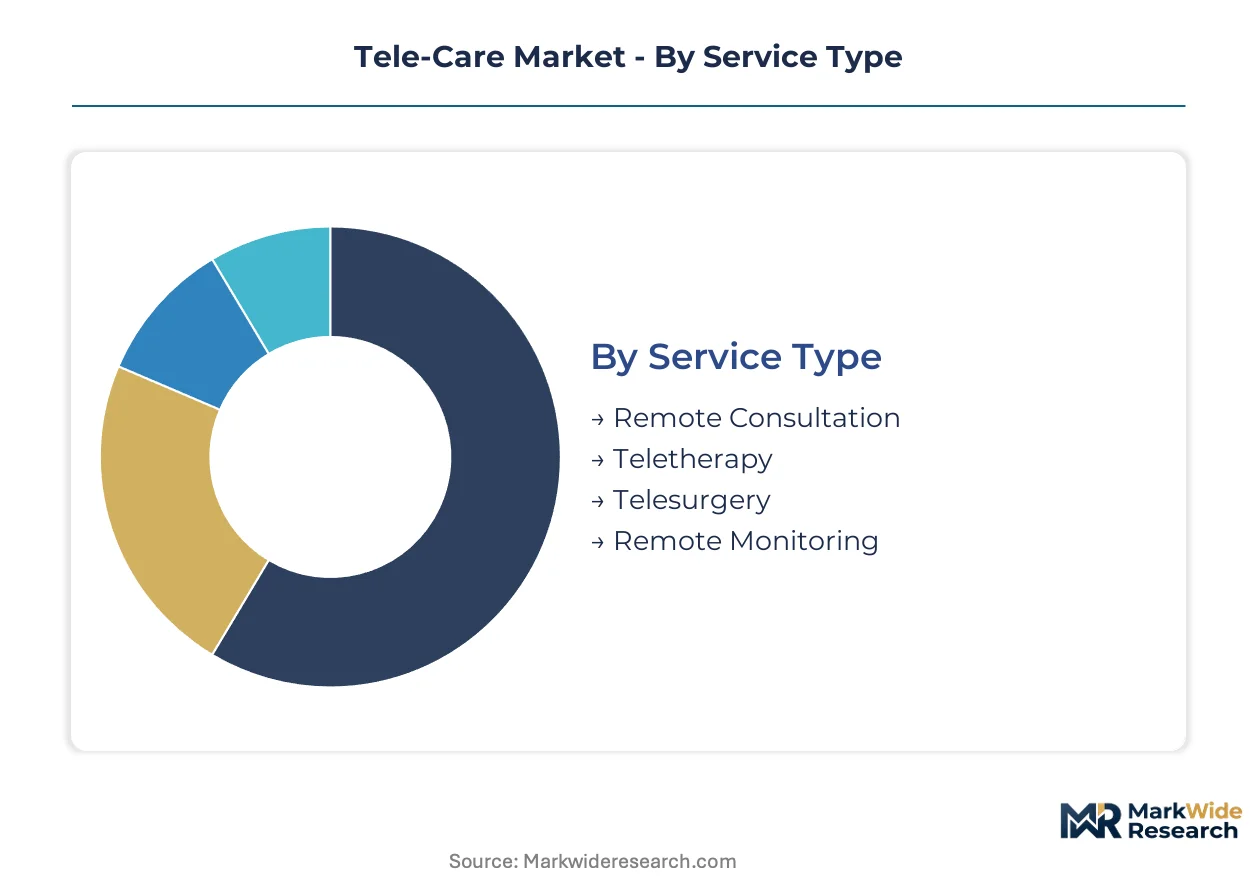
Segmentation in tele-care reveals how reimbursement codes, latency requirements, and data sovereignty rules fragment addressable markets. Each dimension carries distinct regulatory burdens and infrastructure investments that reshape competitive positioning across service tiers.
Service Type:
Replacement cycles in tele-care services accelerate where CMS reimbursement parity and equivalent European frameworks eliminate financial friction for digital adoption.
- Remote Consultation:Synchronous video encounters between patients and licensed clinicians require sub-150-millisecond latency and HIPAA-compliant encryption. Demand concentrates in United States Medicare Advantage plans and German statutory insurance networks as primary care access gaps widen in rural counties.
- Remote Monitoring:Continuous physiological data transmission from patient environments to clinical dashboards enables algorithm-adjusted interventions for heart failure and diabetes. Deployment accelerates in Japan's aging municipalities where MHLW reimbursement codes now cover device provisioning within 48 hours of hospital discharge.
- Teletherapy:Mental health service delivery through digital channels benefits from parity law enforcement in the United States and employer direct-contracting trends in technology and financial services sectors.
- Telesurgery:Robotic-assisted procedures performed across geographic distances remain limited to research protocols and specialized academic medical centers with dedicated network infrastructure.
Remote Consultation sits at the top of the volume ranking, with Remote Monitoring climbing the fastest.
Technology:
Cost tier stratification in tele-care technology separates enterprise-grade diagnostic integrations from lightweight consumer-facing implementations.
- Video Conferencing:Real-time audiovisual platforms retain the largest transaction volume across tele-care delivery, though encryption overhead conflicts with latency requirements for high-acuity consultations.
- Wearable Devices:Continuous glucose monitors and blood pressure sensors decentralize chronic disease management from quarterly clinic visits toward daily surveillance. Investment flow concentrates here as Medicare Advantage plans deploy devices to high-risk enrollees.
- Mobile Apps:Asynchronous consultation platforms and patient-facing interfaces compete on accessibility and cost, often segregating wellness features from diagnostic modules to avoid EU MDR certification burdens.
- Chatbots:AI-augmented triage tools with FDA-cleared algorithms expand reimbursable asynchronous consultation scope, though deployment remains concentrated in pilot programs.
Video Conferencing maintains volume leadership, while Wearable Devices gain share fastest among technology segments.
End User:
Customer type determines procurement authority and contract structure, from individual patient subscriptions to enterprise-wide health system implementations.
- Healthcare Providers:Integrated delivery networks and hospital systems drive platform consolidation around FDA-cleared diagnostic integrations and dedicated network infrastructure.
- Insurance Companies:Payer-centric deployment models embed tele-care into prior authorization workflows and claims processing systems, with Amwell-style embedded insurance workflows gaining traction.
- Employers:Large self-insured employers in the United States unbundle tele-mental health from comprehensive benefits, negotiating per-employee-per-month rates that bypass traditional insurance intermediaries.
- Patients:Direct-to-consumer channels compete on accessibility and cost, though reimbursement parity laws increasingly shift financial responsibility toward payers.
Healthcare Providers anchor procurement volume, with Employers expanding most quickly through direct-contracting channels.
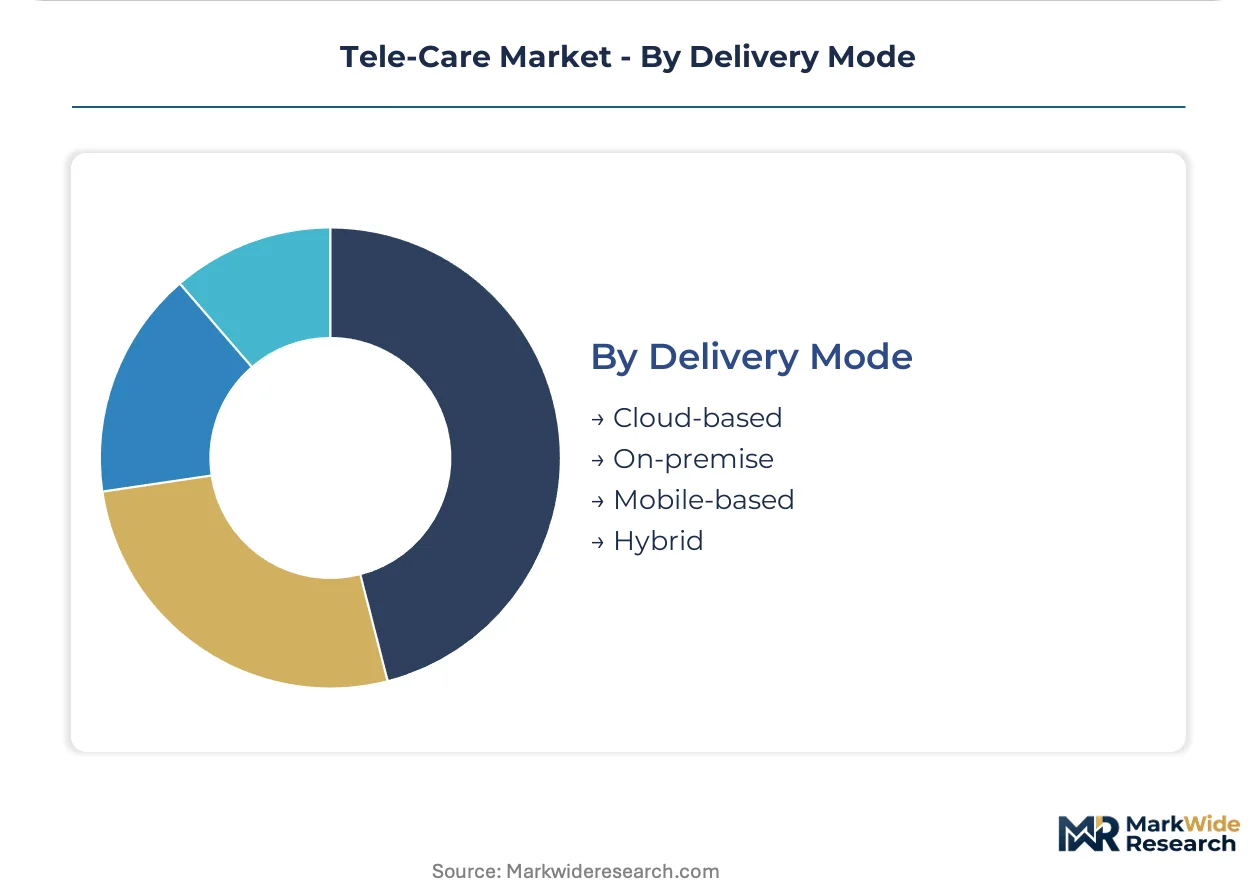
Delivery Mode:
Infrastructure maturity separates cloud-native implementations from hybrid architectures persisting in security-sensitive provider environments.
- Cloud-based:Scalable infrastructure deployment dominates new implementations, reducing capital barriers for mid-sized health system adoption across North American and European markets.
- Hybrid:Mixed cloud-on-premise architectures persist where GDPR data localization requirements or HIPAA security rule enforcement mandate on-site data retention for specific patient populations.
- Mobile-based:Smartphone-native delivery targets consumer-facing applications and asynchronous consultation platforms with lower regulatory certification requirements.
- On-premise:Fully localized infrastructure remains concentrated in national health systems with strict data sovereignty mandates and legacy EHR integration constraints.
Cloud-based delivery holds volume leadership, with Hybrid architectures climbing fastest as data localization rules proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory insurance networks deploy remote monitoring at scale while Japan's aging municipalities accelerate platform adoption through targeted reimbursement codes, revealing how national health system architectures shape deployment velocity.
United States
Medicare Advantage plans and integrated delivery networks drive demand for FDA-cleared diagnostic integrations. CMS reimbursement parity eliminates financial disincentives for telehealth adoption across rural counties. The Greater Boston cluster concentrates academic medical centers pioneering telesurgery protocols with dedicated network infrastructure.
Germany
Statutory insurance networks require MDR-compliant modules for reimbursed remote monitoring, bifurcating the market between clinical platforms and wellness applications. The EU Medical Device Regulation's software classification rules force architectural segregation of diagnostic features. North Rhine-Westphalia anchors health system consolidation around cloud-native implementations.
Japan
Aging municipalities in rural prefectures deploy connected monitoring platforms within 48 hours of hospital discharge. MHLW reimbursement codes now cover device provisioning for heart failure and diabetes management. The Kanto region around Tokyo concentrates payer-provider integration pilots with sub-150-millisecond latency requirements.
United Kingdom
NHS integrated care systems embed tele-care into primary care access workflows as GP density gaps widen in rural counties. GDPR data localization requirements fragment platform architecture for cross-border patient transfers. The London-Southeast corridor concentrates specialist teleconsultation hubs serving national referral networks.
Brazil
ANVISA's streamlined software-as-medical-device registration creates first-mover advantages for platform developers entering Latin America's largest health market. Private insurance expansion in São Paulo and Rio de Janeiro drives demand for payer-centric deployment models. The Southeast region anchors tele-mental health pilots targeting employer-sponsored plans.
Tele-Care Market Competitive Landscape
Top-tier vendors anchor the premium segment with FDA-cleared diagnostic integrations and dedicated network infrastructure, while mid-tier specialists compete on payer-centric deployment and embedded insurance workflows. The market structure consolidates around enterprise-grade platforms with hardware-software convergence capabilities versus lightweight consumer-facing applications. Two strategic archetypes dominate: comprehensive specialist access models and remote patient monitoring hardware-software bundles. Competitive moves concentrate on M&A for diagnostic algorithm portfolios and strategic partnerships with Medicare Advantage plans.
Within the comprehensive access tier, Teladoc Health exemplifies the high-acuity specialist model, while Koninklijke Philips occupies a position representing hardware-software convergence advantages in continuous monitoring. Amwell anchors the payer-centric archetype through embedded insurance workflow integration.
| Leading Market Players |
|---|
| Teladoc Health |
| Koninklijke Philips |
| Medtronic |
| Amwell |
| GE Healthcare |
| Doctor On Demand |
| Abbott Laboratories |
| Johnson & Johnson |
| AT&T |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in remote patient monitoring hardware command asymmetric pricing power through captive device provisioning networks, while cloud-native software vendors face margin compression from multi-tenant infrastructure commoditization. This ownership pattern concentrates supply-side discipline among FDA-cleared diagnostic integrators while fragmenting pricing authority across asynchronous consultation platforms.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise-grade platforms with dedicated network infrastructure from lightweight consumer-facing applications. Pricing stratifies across premium, standard, and economy tiers based on FDA certification grade and after-sales service bundling. Cost compression in the mid-market tier is intensifying because Medicare Advantage plans demand per-employee-per-month rates that bypass traditional insurance intermediaries. Self-insured employers exhibit highest price sensitivity, while integrated delivery networks with statutory reimbursement mandates show lowest elasticity.
Supply Chain Analysis
Semiconductor supply for wearable devices rests on Taiwanese foundry capacity and South Korean memory producers, with sensor modules drawing from Japanese precision component specialists. Cloud infrastructure feeds from hyperscaler data centers concentrated in the United States, Germany, and Japan. Single-source vulnerability in FDA-cleared diagnostic algorithm licensing creates bottleneck risk for platform developers seeking reimbursable asynchronous consultation modules. Distribution runs through hospital system procurement committees and payer embedded insurance workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tele-care market functions as a geographic-arbitrage play where CMS reimbursement parity in the United States enables platform economics that remain inaccessible under Germany's MDR compliance cost structure.
For Market Incumbents: Hedge against algorithm commoditization by acquiring FDA-cleared diagnostic portfolios and embedding them into Medicare Advantage contracting workflows. Defensive consolidation through backward integration into wearable device manufacturing protects margin position from component supply shocks. Priority lever: captive supply of continuous glucose monitoring hardware. For New Entrants and Emerging Players: Rural United States counties with physician density gaps represent the most penetrable buyer archetype for high-acuity specialist access models. Brazil's ANVISA streamlined registration pathway offers white-space entry for software-as-medical-device platforms targeting private insurance expansion in São Paulo. Go-to-market angle: direct employer contracting for tele-mental health bypassing traditional benefits intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-architecture specialists with GDPR-compliant data localization capabilities and legacy EHR integration moats. Long-term viability over the next decade hinges on reimbursement code expansion velocity rather than technology differentiation alone. Signal to watch: MHLW coverage expansion for ambient monitoring sensors in Japan's aging municipalities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Clears pathway for Medicare reimbursement equivalence under CMS parity mandates. |
| CE Marking Pathway | Enables MDR-compliant module deployment across German statutory insurance networks. |
| Hospital System Partnership | Secures embedded placement within integrated delivery network procurement workflows. |
| Software Companion Development | Extends reimbursable scope for asynchronous consultations through AI-augmented triage. |
| Reimbursement Strategy | Captures MHLW code expansion for remote monitoring in Japan's aging municipalities. |
Research Methodology
Coverage spans North America, Europe, and East Asia, with primary inputs from each region combined with secondary validation. Interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers were triangulated against FDA 510(k) filings, CMS Medicare reimbursement databases, EMA MDR submission records, and hospital procurement contract registries. Bottom-up platform deployment counts and top-down health system expenditure estimates were reconciled through iterative cross-checking.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation dimensions modeled include service type, technology tier, end-user archetype, and delivery mode complexity. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate MHLW reimbursement code expansion schedules and Medicare Advantage enrollment trajectories without year-specific anchoring.
Inputs from CMS and MHLW regulatory filings were available through the study window; gaps in real-time platform deployment counts from private health systems introduce uncertainty bands around mid-market penetration estimates. Forecasts reflect documented assumptions regarding reimbursement parity enforcement velocity and cross-border data localization rule proliferation. A small set of named triggers—CMS code revision timelines, EU MDR software classification rulings, and ANVISA registration backlog clearance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
India Telehealth Services Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Telepathology Service Market
Telemedicine
Remote Healthcare Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Telestroke Services Market
Telemedicine
Telemedicine EMR Software Market