
 Global Telecom Outsourcing Market | 2026-2036
Global Telecom Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Outsourcing Market Outlook
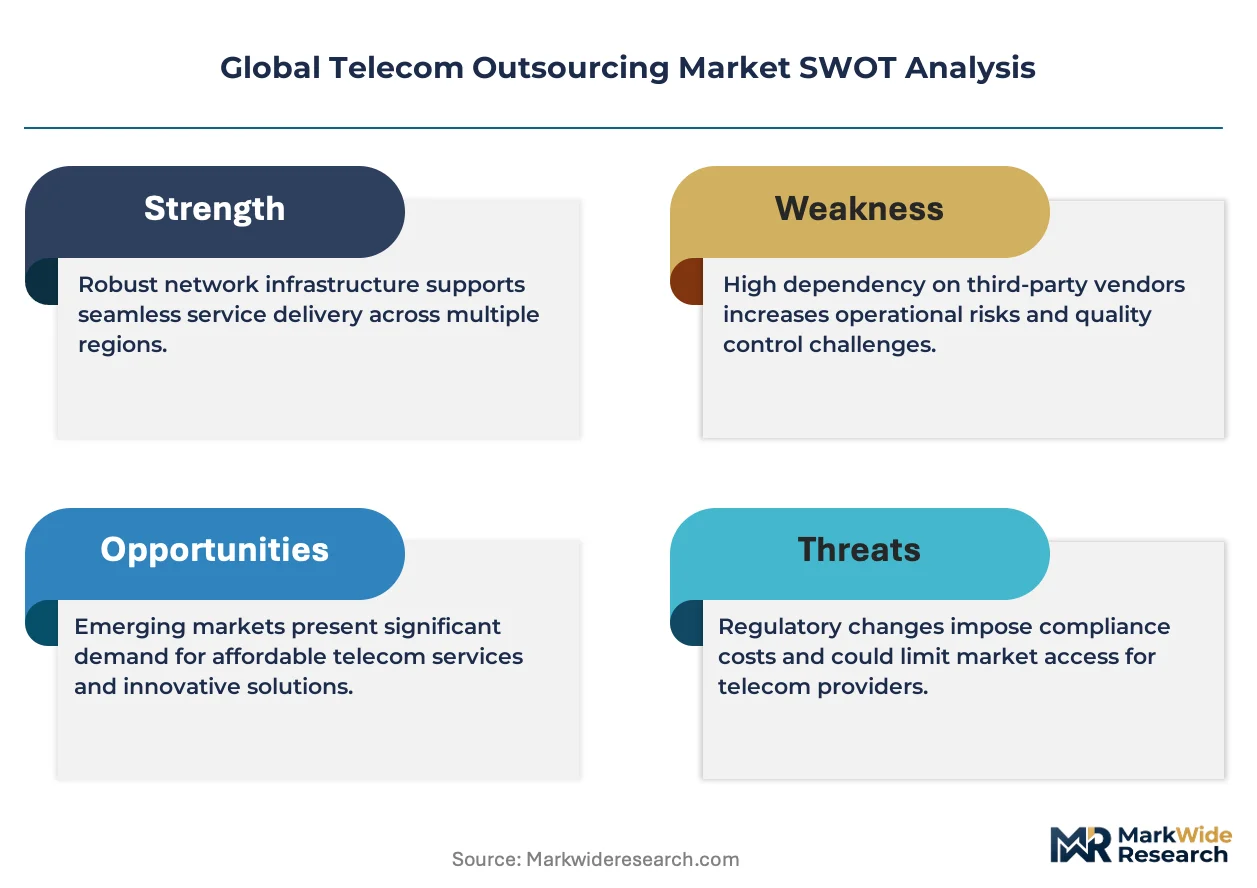
The EU Green Deal is decoupling infrastructure refresh timelines from traditional replacement cycles across European telecom operators. Ericsson leverages its integrated 5G portfolio to sustain long-term managed services contracts with tier-one carriers. Huawei Technologies anchors significant network outsourcing volume across emerging markets through cost-competitive deployment models. Nokia differentiates with cloud-native network management platforms that appeal to operators pursuing virtualized infrastructure strategies.
Telecom outsourcing encompasses the delegation of network operations, customer care, IT systems, and engineering functions to third-party specialists, typically governed by multi-year service level agreements specifying uptime thresholds, mean time to repair, and penalty structures. The practice allows operators to convert fixed capital expenditures into variable operational costs while accessing specialized technical competencies. Network management services dominate current contract value given the complexity of multi-vendor radio access networks and core infrastructure. Cloud-based deployment models represent the fastest-expanding segment as operators migrate network functions from physical appliances to software-defined environments. AI-enabled service delivery is capturing disproportionate margin pools through predictive maintenance and automated incident resolution.
The Federal Communications Commission shapes US market access through spectrum allocation rules and network reliability mandates, while the European Telecommunications Standards Institute establishes interoperability benchmarks that outsourcing providers must satisfy. China's Ministry of Industry and Information Technology governs domestic telecom infrastructure standards and cross-border data handling requirements for foreign outsourcing vendors. India's Telecom Regulatory Authority oversees service quality benchmarks that directly influence outsourcing contract terms for customer support delivery. Stakeholders must monitor evolving data localization requirements and carbon disclosure obligations as these criteria increasingly determine vendor selection and contract renewals.
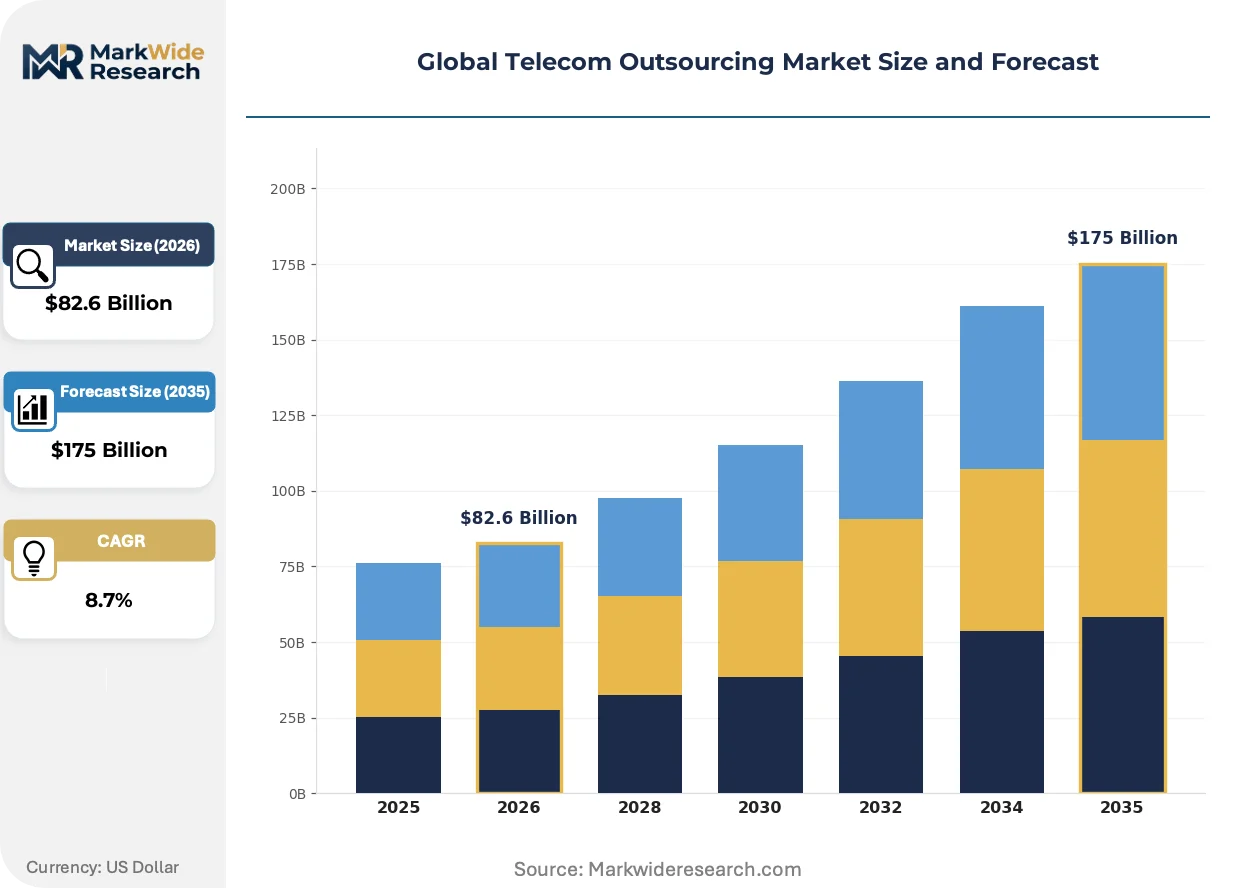
Market Dynamics
Mobile network operators are accelerating the migration of network management functions to third-party specialists as 5G deployment complexity and capital intensity strain in-house engineering capacity. This structural shift converts fixed infrastructure costs into variable operational expenditures while accessing specialized multi-vendor integration expertise.
Growth Catalysts
- EU Green Deal mandates:European operators face accelerated infrastructure refresh timelines driven by e-waste directives and carbon disclosure requirements, expanding managed services demand for energy-efficient network modernization.
- Cloud-native architecture migration:Virtualized network functions require specialized orchestration capabilities that most operators lack internally, pushing radio access network management toward outsourcing specialists with software-defined expertise.
- India and Philippines delivery clusters:Mature customer support outsourcing ecosystems in these markets provide scalable, cost-competitive voice and digital care operations for global carriers seeking operational leverage.
Market Restraints
- Semiconductor supply concentration:Network equipment manufacturing depends on concentrated Asian foundry capacity, creating procurement bottlenecks that delay outsourced deployment schedules and inflate hardware costs.
- Data localization requirements:China's MIIT cross-border data handling restrictions and India's TRAI service quality mandates impose operational friction on global outsourcing providers seeking unified delivery models.
- Skilled engineering scarcity:Multi-vendor 5G integration expertise remains concentrated among limited specialist workforces, constraining the scalability of high-value managed services contracts.
Strategic Opportunities
- AI-enabled predictive maintenance:Machine learning algorithms analyzing network telemetry data create premium service tiers through automated incident resolution and proactive capacity planning.
- Edge computing infrastructure management:Distributed cloud deployments at cell tower sites require new operational competencies that operators will delegate to infrastructure specialists.
- EU AI Act compliance services:Risk management and algorithmic transparency requirements for automated network optimization create advisory revenue streams for outsourcing providers with regulatory expertise.
Industry Challenges
- Multi-generational network integration:Outsourced teams must simultaneously manage legacy 2G/3G voice infrastructure, 4G LTE cores, and 5G standalone deployments without service degradation.
- Cybersecurity certification timelines:FedRAMP and ISO 27001 compliance requirements for cloud-based network management platforms extend sales cycles and delay contract activations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Outsourcing Market |
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $175 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Customer Support, IT Services, Engineering Services End User: Telecom Operators, Enterprises, Government, Managed Service Providers Deployment Model: On-Premise, Cloud-Based, Hybrid, Virtualized Technology: AI, IoT, 5G Solutions, Big Data Analytics |
| Companies Covered | Ericsson, Huawei Technologies, Nokia, Accenture, IBM, Tata Consultancy Services, Cisco Systems, Tech Mahindra, Amdocs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Outsourcing Market Strategic Shifts
Artificial intelligence and software-defined architectures are fundamentally restructuring how network operations are delivered, shifting value capture from hardware deployment toward predictive analytics and automated orchestration capabilities.
Open RAN architectures are expanding into mainstream carrier infrastructure strategies. These disaggregated hardware-software interfaces enable multi-vendor interoperability in radio access networks. Tier-one operators in Germany, Japan, and the United States are mandating Open RAN compliance in new procurement frameworks. This technology shift is compressing incumbent equipment vendor margins while creating integration service opportunities for outsourcing specialists with systems integration expertise.
The EU AI Act establishes mandatory risk classification and human oversight requirements for automated network optimization systems deployed across European Union member states. Telecom operators utilizing machine learning for predictive maintenance or dynamic spectrum allocation must document algorithmic decision pathways and maintain audit trails. Network outsourcing contracts in France, Italy, and Spain now explicitly assign compliance liability to managed services providers, reshaping vendor selection criteria toward regulatory expertise.
Consumption-based pricing models are displacing traditional fixed-fee managed services arrangements. Enterprise and wholesale carrier customers increasingly demand network performance guarantees tied to actual usage patterns rather than provisioned capacity. This behavioral shift is most visible in North American and Nordic markets where cloud-native infrastructure enables granular metering. Outsourcing providers are restructuring contracts around latency thresholds, packet loss rates, and energy consumption metrics rather than headcount or equipment maintenance fees.
Global Telecom Outsourcing Market Segmentation
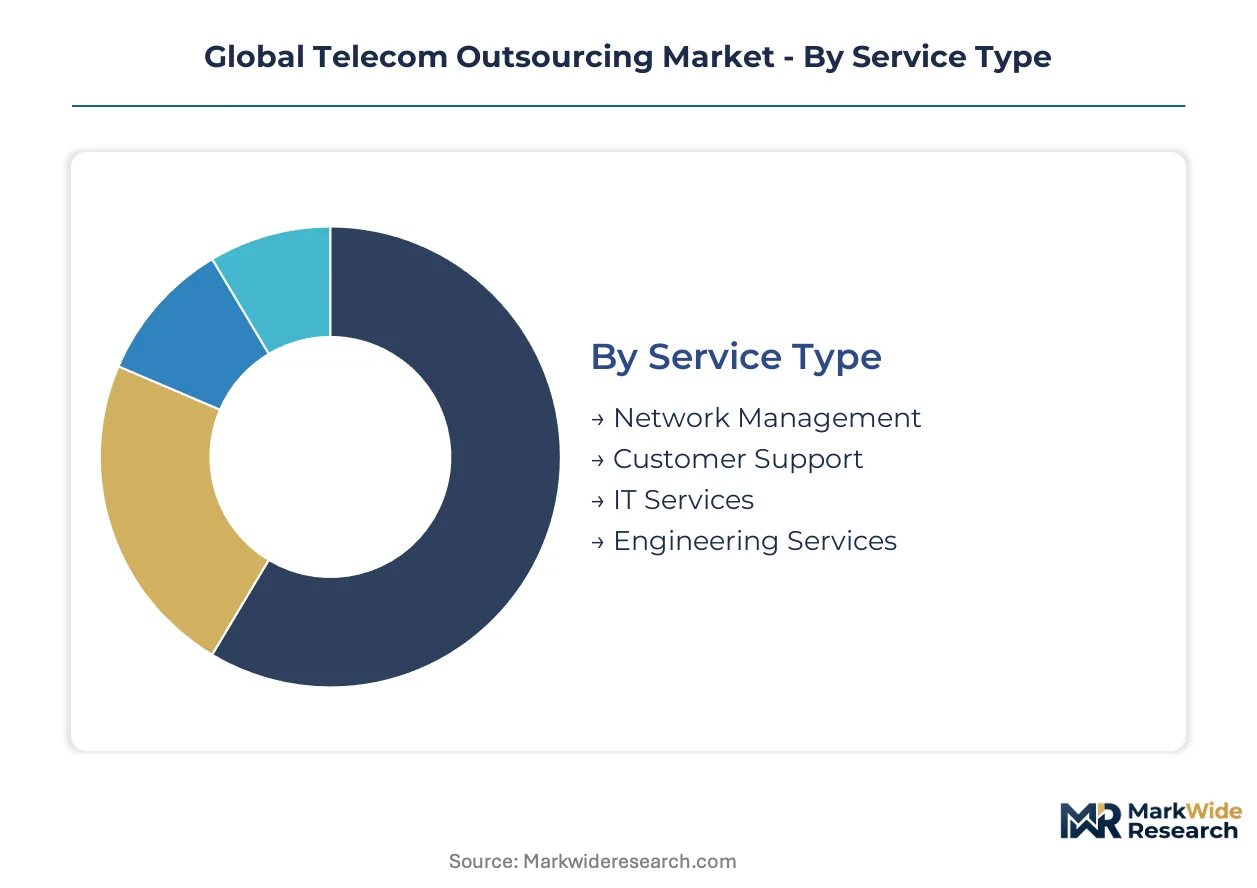
Telecom outsourcing contracts diverge sharply by technical complexity and commercial risk allocation. Understanding how service types, deployment models, and technology layers intersect determines vendor selection and pricing architecture.
Service Type:
Technical sophistication and capital intensity separate high-margin network functions from commoditized support services.
- Network Management:Multi-vendor radio access network orchestration and core infrastructure monitoring command premium pricing due to specialized 5G integration expertise. European operators under EU Green Deal mandates are accelerating contracts for energy-efficient network modernization.
- Customer Support:Voice and digital care operations scale through delivery clusters in India and the Philippines, where TRAI service quality benchmarks shape contract terms and operational metrics.
- IT Services:Back-office systems and billing platform management.
- Engineering Services:Field deployment and infrastructure construction.
Network Management leads on scale; Customer Support leads on momentum.
End User:
Procurement authority and compliance burden vary dramatically across buyer categories.
- Telecom Operators:Mobile network carriers convert fixed infrastructure costs into variable operational expenditures through multi-year managed services agreements. FCC spectrum allocation rules and network reliability mandates in the United States shape vendor qualification requirements.
- Enterprises:Private 5G deployments and SD-WAN management.
- Government:FedRAMP certification requirements extend sales cycles for cloud-based network management platforms.
- Managed Service Providers:Intermediary resale and white-label arrangements.
Telecom Operators dominate contract value; Enterprises are expanding most quickly.
Deployment Model:
Virtualization maturity determines operational flexibility and cost structure.
- Cloud-Based:Software-defined network functions enable granular metering and consumption-based pricing. Nordic and North American markets show strongest adoption where cloud-native infrastructure supports latency threshold guarantees.
- Virtualized:Network function virtualization without full cloud abstraction.
- Hybrid:Mixed on-premise and cloud orchestration.
- On-Premise:Traditional appliance-based infrastructure.
Cloud-Based deployment captures the steepest expansion trajectory; Hybrid models retain largest installed base.
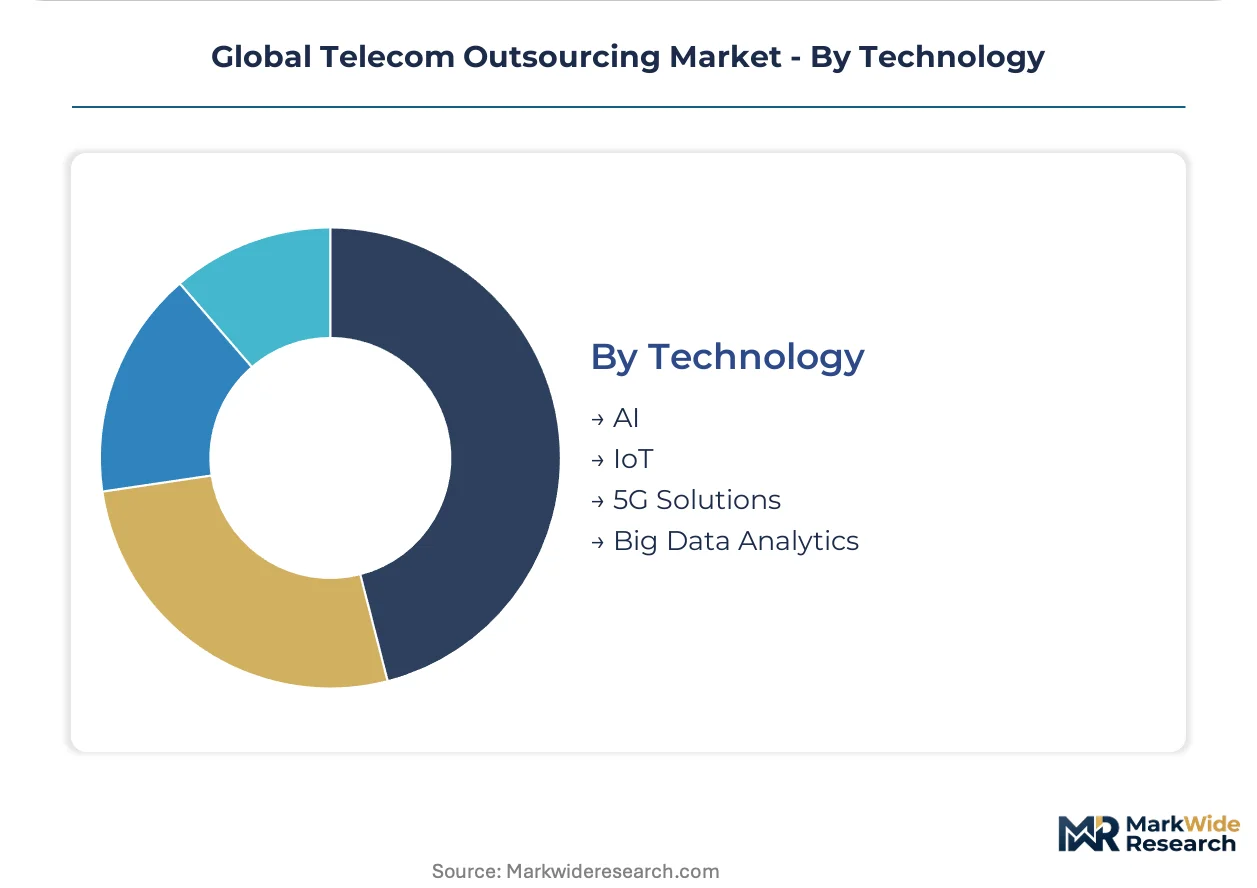
Technology:
Intelligence layer integration separates commodity outsourcing from premium service tiers.
- AI:Machine learning algorithms analyzing network telemetry enable predictive maintenance and automated incident resolution. EU AI Act compliance requirements in France, Italy, and Spain now assign algorithmic liability to managed services providers.
- 5G Solutions:Standalone core and radio access network specialization.
- Big Data Analytics:Traffic pattern optimization and capacity planning.
- IoT:Connected device platform management and security.
AI-enabled delivery commands premium margins; 5G Solutions anchor infrastructure replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom outsourcing originated in the United States during the 1990s deregulation era, when AT&T and Verizon first externalized network maintenance to reduce operational overhead. The practice diffused to Europe through British Telecom's landmark contracts, then scaled across Asia-Pacific as mobile penetration surged in the 2000s.
United States
FCC spectrum allocation rules and network reliability mandates drive carrier procurement of managed services. FedRAMP certification requirements extend sales cycles for cloud-based network management platforms. Dallas-Fort Worth anchors significant delivery operations where AT&T and Verizon maintain outsourced engineering centers.
Germany
Deutsche Telekom and Vodafone accelerate Open RAN procurement frameworks requiring multi-vendor interoperability. EU Green Deal e-waste directives compress infrastructure refresh timelines. Munich and Düsseldorf host concentrated systems integration specialists serving Central European operators.
India
TRAI service quality benchmarks directly shape customer support outsourcing contract terms for global carriers. The country's mature delivery clusters provide scalable voice and digital care operations. Bangalore and Hyderabad concentrate engineering talent for network management service delivery.
China
MIIT cross-border data handling restrictions govern domestic telecom infrastructure standards and foreign vendor participation. Dual carbon goals pressure state-owned operators toward energy-efficient modernization. Shenzhen and Beijing anchor indigenous equipment manufacturing and managed services development.
United Kingdom
BT and Virgin Media O2 outsource network operations to manage 5G standalone deployment complexity. GDPR and emerging AI governance frameworks reshape liability allocation in managed services contracts. London and Manchester host primary delivery centers for European customer care operations.
Global Telecom Outsourcing Market Competitive Environment
Capital-heavy equipment manufacturers compete with asset-light systems integrators for contract value in telecom outsourcing. The market structures around three tiers: integrated infrastructure vendors, pure-play managed services specialists, and IT consultancies with telecom practices. Consolidation pressures concentrate high-value network management contracts among specialists with multi-vendor 5G expertise. Dominant competitive moves include strategic partnerships for Open RAN interoperability and geographic expansion into emerging market operator procurement cycles.
Within the integrated infrastructure tier, Ericsson and Nokia represent archetypes of vendors sustaining long-term managed services relationships through captive equipment deployment. Huawei Technologies occupies a distinct position anchoring significant volume across emerging markets through cost-competitive delivery models. Among IT-centric service providers, Accenture exemplifies consultancies capturing cloud-native transformation contracts as operators virtualize network functions.
| Leading Market Players |
|---|
| Ericsson |
| Huawei Technologies |
| Nokia |
| Accenture |
| IBM |
| Tata Consultancy Services |
| Cisco Systems |
| Tech Mahindra |
| Amdocs |
| Others |
Value Chain & Pricing Dynamics
Cloud-native network function virtualization compresses both deployment timelines and hardware procurement cycles, concentrating cost leverage among systems integrators with software-defined orchestration capabilities while fragmenting traditional equipment vendor pricing power. This dual compression reshapes contract economics as operators migrate from capital-intensive appliance purchases to consumption-based operational expenditures.
Pricing Analysis
Consumption-based pricing with performance guarantees tied to latency thresholds and energy metrics is displacing fixed-fee managed services arrangements across North American and Nordic markets. Price differentiation rests on certification tier—FedRAMP and ISO 27001 compliance commands substantial premiums—while customization depth for multi-vendor Open RAN integration separates premium from standard tiers. Cost compression in commoditized customer support segments is intensifying due to delivery cluster competition between India and the Philippines. Enterprise buyers exhibit highest price sensitivity given procurement authority constraints, whereas government contracts show lowest sensitivity due to compliance-driven vendor qualification requirements.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Munich, and Bangalore anchor hub-and-spoke delivery patterns for network management services and customer care operations. Semiconductor foundry capacity concentrates in Taiwan, South Korea, and China, creating procurement bottlenecks that delay outsourced deployment schedules. Raw material dependencies span advanced node chips, radio frequency components, and specialized optical equipment. Single-source vulnerability around 5G baseband processors represents the dominant structural risk. Distribution runs through direct carrier relationships and intermediary managed service providers with white-label arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where operator procurement is shifting toward premium specifications around AI-enabled predictive maintenance and EU AI Act compliance capabilities.
For Market Incumbents: Lock in long-term managed services contracts through captive equipment deployment and exclusive Open RAN interoperability partnerships. Ericsson and Nokia archetypes must defend against pure-play systems integrators by deepening certification investment in FedRAMP and ISO 27001 tiers. Vertical integration into cloud-native orchestration platforms represents the critical capacity lever for margin defense. For New Entrants and Emerging Players: Capture edge computing infrastructure management contracts as distributed cloud deployments at cell tower sites create new operational competency gaps. EU AI Act compliance advisory services in France, Italy, and Spain offer the most penetrable white-space given liability assignment to managed services providers. Channel partnership with Tier 1 carriers pursuing private 5G enterprise deployments provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light systems integrators with multi-vendor 5G expertise and regulatory compliance capabilities. Long-term viability across the analysis window favors specialists with AI-enabled service delivery platforms and cloud-native transformation credentials. Watch for inflection signals around Open RAN procurement mandate acceleration in Germany, Japan, and the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Partnership | Deutsche Telekom and Vodafone procurement frameworks mandate multi-vendor compliance, creating integration service demand. |
| AI-Enabled Predictive Maintenance Platform | Machine learning algorithms analyzing network telemetry create premium service tiers through automated incident resolution. |
| Eu AI Act Compliance Service Development | Risk management and algorithmic transparency requirements in France, Italy, and Spain assign liability to managed services providers. |
| Edge Computing Infrastructure Management Capability | Distributed cloud deployments at cell tower sites require new operational competencies operators will delegate to specialists. |
| Delivery Cluster Expansion in India and Philippines | TRAI service quality benchmarks shape contract terms while mature ecosystems provide scalable voice and digital care operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network operations executives, procurement officers at Tier 1 carriers, systems integration specialists, and regulatory affairs leads with secondary validation against FCC spectrum allocation records, ETSI interoperability benchmarks, TRAI service quality reports, and MIIT infrastructure standards. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Historical reference periods spanning infrastructure refresh cycles and 5G deployment waves anchored the projection horizon across the modeling period. Segmentation dimensions modeled include service type, deployment model, end user category, and technology layer integration depth. CAGRs derived from weighted average growth assumptions across these dimensions, with specific inputs around Open RAN adoption curves and cloud-native migration timelines.
Regulatory enforcement variance, semiconductor supply disruption, and operator capital expenditure contraction are the dominant revision risks that could materially alter trajectory. Forecasts reflect documented assumptions around EU Green Deal implementation pace and data localization requirement evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market