
 United States Healthcare BPO Market | 2026-2036
United States Healthcare BPO Market Size, Share, and Industry Trends Forecast 2026-2036
United States Healthcare BPO Market Intelligence
HIPAA compliance certification is rotating as the primary gating standard for vendor qualification in federal and state-contracted healthcare services. Optum leverages its vertically integrated payer-provider data infrastructure to dominate large health system engagements. Cognizant sustains competitive positioning through specialized clinical coding and claims adjudication operations. Genpact anchors significant revenue cycle management volume through long-term pharmaceutical firm partnerships.
Healthcare business process outsourcing encompasses the delegation of administrative, financial, and operational functions—such as medical coding, claims processing, and patient scheduling—to third-party specialists operating under strict data security protocols and SLA-governed turnaround times. The primary purpose is to reduce operational expenditure while maintaining compliance with federal privacy mandates and improving cash flow velocity for providers. Revenue cycle management applications command the deepest margin pools as denial management complexity escalates under ICD-10-CM and CPT code expansion. Cloud computing and AI solutions within the technology segment are capturing accelerated procurement interest as health systems modernize legacy EHR-integrated workflows.
FDA oversight of clinical data integrity, CMS reimbursement rulemaking, and HIPAA enforcement by the Office for Civil Rights collectively elevate compliance costs and barrier thresholds for market entry. The No Surprises Act and state-level balance billing prohibitions are forcing payers and providers to restructure patient financial communications and out-of-network claims protocols. Stakeholders must monitor evolving state Medicaid managed care procurement standards and federal interoperability mandates to anticipate contract renewal cycles and technology upgrade requirements.
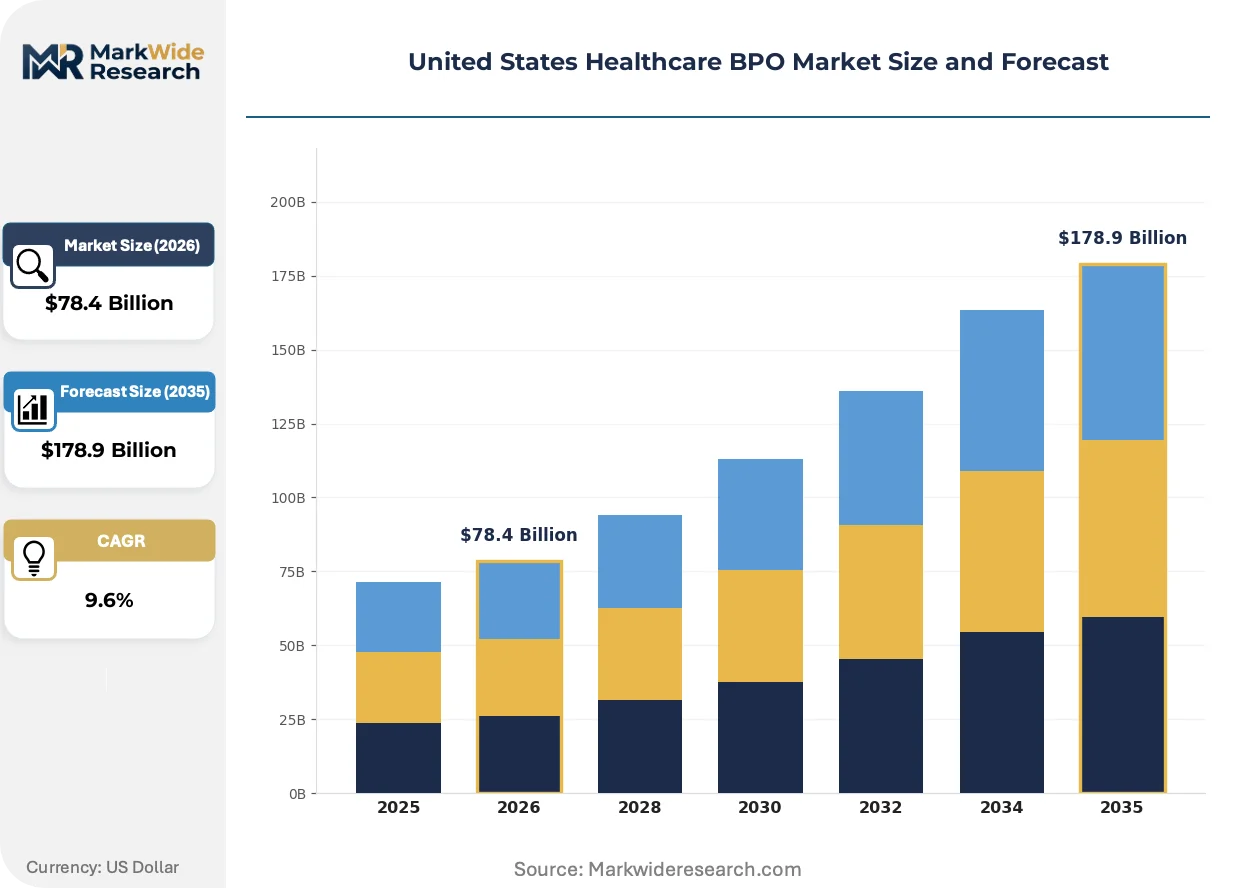
Market Dynamics
CMS value-based care mandates are intensifying administrative complexity across US health systems, forcing payers and integrated delivery networks to restructure revenue cycle operations and expand outsourcing partnerships with specialized vendors.
Growth Catalysts
- Interoperability mandates:Federal interoperability rules under the 21st Century Cures Act are compelling health systems to modernize legacy EHR-integrated workflows, creating procurement urgency for cloud-native BPO platforms.
- ICD-10-CM expansion:The continuous proliferation of diagnosis and procedure codes is elevating denial management complexity, driving demand for specialized clinical coding expertise.
- Texas and Florida concentration:Multi-hospital networks in these states are consolidating revenue cycle management procurement, generating scale economies for vendors with regional delivery centers.
Market Restraints
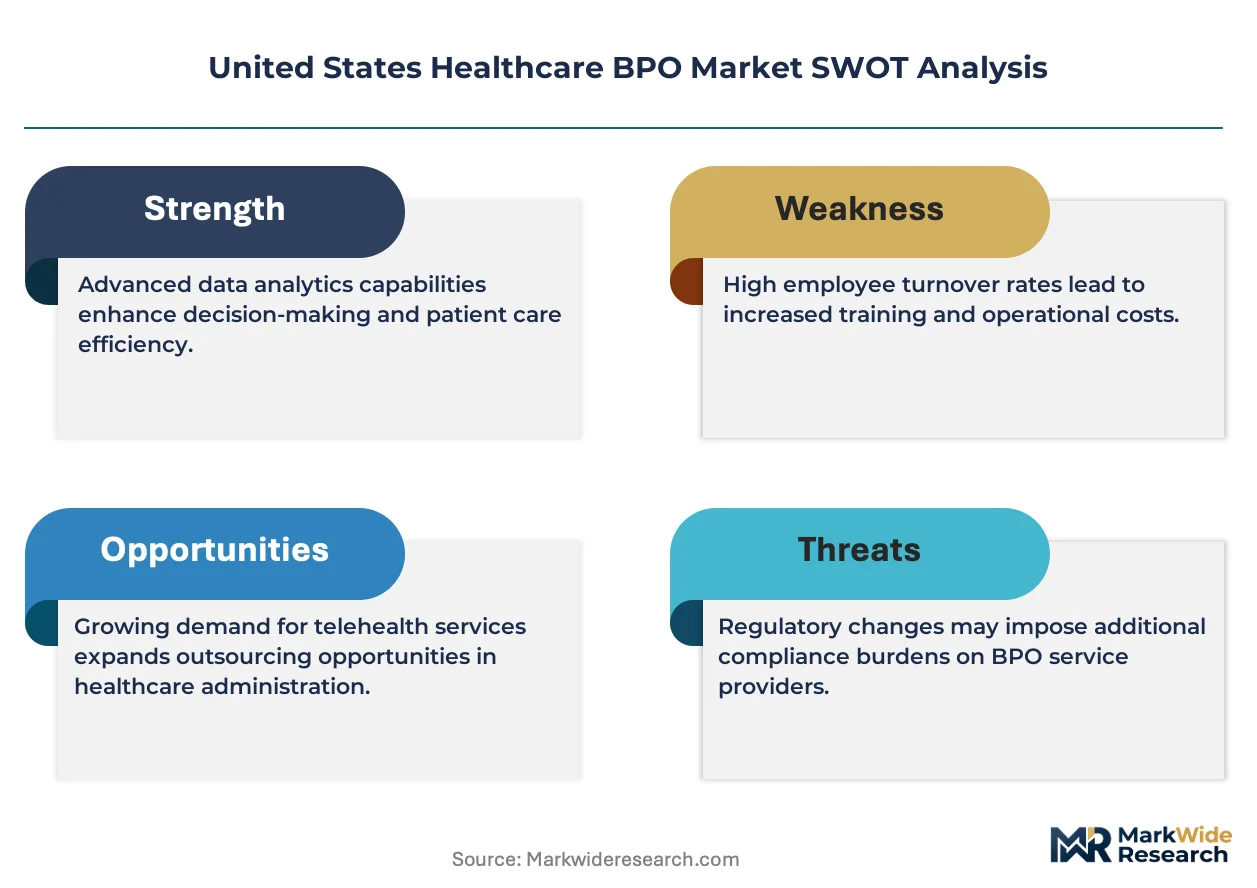
- HIPAA compliance cost escalation:Certification requirements from the Office for Civil Rights are elevating barrier thresholds, squeezing margin capacity for mid-tier vendors.
- Clinical data integrity oversight:FDA scrutiny of outsourced clinical trial documentation is extending validation timelines and inflating quality assurance expenditures.
- Cloud infrastructure concentration:Reliance on hyperscale providers for PHI hosting creates single-point-of-failure exposure and limits vendor negotiation leverage.
Strategic Opportunities
- No Surprises Act implementation:Federal balance billing prohibitions are forcing restructuring of patient financial communications, opening white space for vendors with price transparency tooling.
- AI-enabled claims adjudication:Machine learning convergence with robotic process automation is compressing turnaround times for high-volume payers seeking competitive differentiation.
- Medicaid managed care procurement:State-level contract renewal cycles are creating predictable entry points for vendors with specialized beneficiary eligibility expertise.
Industry Challenges
- Certified medical coder scarcity:AHIMA-credentialed professionals command premium compensation, constraining talent acquisition velocity for scaling operations.
- Legacy EHR integration friction:Epic and Cerner system architectures require custom API development, extending implementation timelines and inflating upfront project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Healthcare BPO Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing, Coding, Claims Processing, Customer Support End User: Hospitals, Clinics, Insurance Companies, Pharmaceutical Firms Application: Telemedicine, Health Information Management, Medical Transcription, Revenue Cycle Management Technology: Cloud Computing, AI Solutions, Data Analytics, Robotic Process Automation |
| Companies Covered | Optum, Cognizant, Conduent, R1 RCM, Genpact, IQVIA, EXL, Accenture, Firstsource, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Healthcare BPO Market Strategic Shifts & Innovations
Automation and regulatory compression are actively reshaping competitive positioning in US healthcare BPO, with vendors racing to deploy intelligent platforms that satisfy simultaneous demands for cost reduction and compliance assurance.
Generative AI is fragmenting traditional clinical documentation workflows. Large language models trained on medical ontologies are automating prior authorization letters and clinical narrative generation. Health plans with substantial Medicare Advantage enrollment are deploying these tools aggressively. The technology is fragmenting task distribution between human coders and algorithmic systems, compressing headcount requirements for routine documentation.
The No Surprises Act independent dispute resolution process is restructuring out-of-network claims protocols. Federal arbitration requirements are forcing payers and providers to maintain specialized dispute infrastructure. Revenue cycle management vendors with IDR workflow expertise are capturing disproportionate contract value from systems with high emergency department utilization.
Hospital procurement departments are consolidating vendor relationships to reduce contract management overhead. Multi-year master service agreements with integrated technology stacks are displacing point-solution contracts. This concentration is most visible among nonprofit systems in the Midwest and Southeast seeking procurement efficiency gains.
United States Healthcare BPO Market Segmentation
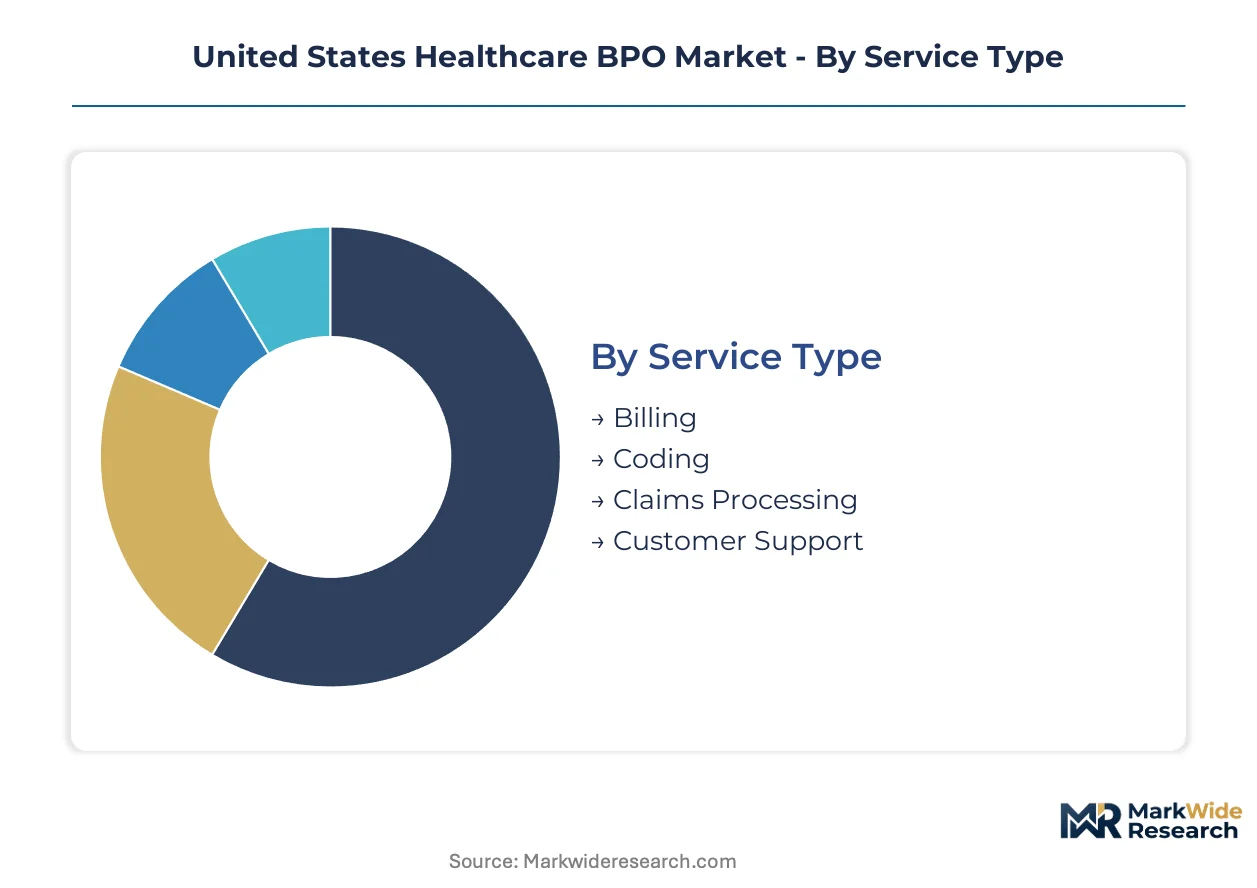
Healthcare BPO segmentation reveals distinct procurement patterns across service modalities and technology maturity levels. Vendor positioning depends on matching capability depth to specific operational pain points within payer and provider organizations.
Service Type:
Domestic delivery centers handle billing and coding functions under HIPAA jurisdiction, while claims processing exhibits limited nearshore migration to Canada and Mexico for cost arbitrage.
- Billing:Patient financial services encompassing charge capture, payment posting, and statement generation require state-specific regulatory knowledge for Medicaid variations. Texas and Florida health systems concentrate procurement among vendors with regional delivery infrastructure.
- Coding:ICD-10-CM and CPT code assignment demands AHIMA-credentialed professionals with specialty-specific expertise in cardiology, orthopedics, and emergency medicine. Scarcity of certified coders elevates labor costs and constrains scaling velocity.
- Claims Processing:Adjudication workflows integrate payer-specific rule engines.
- Customer Support:Member and patient interaction centers leverage speech analytics.
Revenue cycle management commands the established base. The steepest expansion runs through clinical coding specialization.
End User:
Hospital networks generate the deepest contract values through multi-year master service agreements, while pharmaceutical outsourcing concentrates among top-tier firms with FDA-validated quality systems.
- Hospitals:Multi-hospital IDNs consolidate vendor relationships to reduce contract management overhead, favoring integrated technology stacks over point solutions. Midwest and Southeast nonprofit systems lead procurement rationalization efforts.
- Clinics:Ambulatory settings prioritize modular, EHR-integrated platforms with lower implementation thresholds.
- Insurance Companies:Payers demand AI-enabled adjudication for Medicare Advantage enrollment growth.
- Pharmaceutical Firms:Clinical trial documentation and pharmacovigilance outsourcing require FDA-compliant data integrity protocols.
Hospital procurement anchors vendor revenue stability. Pharmaceutical partnerships deliver the highest margin expansion trajectory.
Application:
Telemedicine integration accelerated post-pandemic, while revenue cycle management retains the longest implementation timelines due to legacy EHR architecture complexity.
- Telemedicine:Virtual care platforms require real-time eligibility verification and cross-state licensing compliance for provider networks. CMS reimbursement parity rules are restructuring platform procurement specifications.
- Health Information Management:Enterprise data governance spans master patient index maintenance, release of information workflows, and interoperability mandate compliance under the 21st Century Cures Act.
- Medical Transcription:Voice recognition and NLP tools are compressing human editor requirements.
- Revenue Cycle Management:End-to-end denial management and patient financial communications dominate outsourcing value.
Revenue cycle management absorbs the largest outsourcing expenditure. Telemedicine infrastructure is gaining share fastest among new procurement categories.
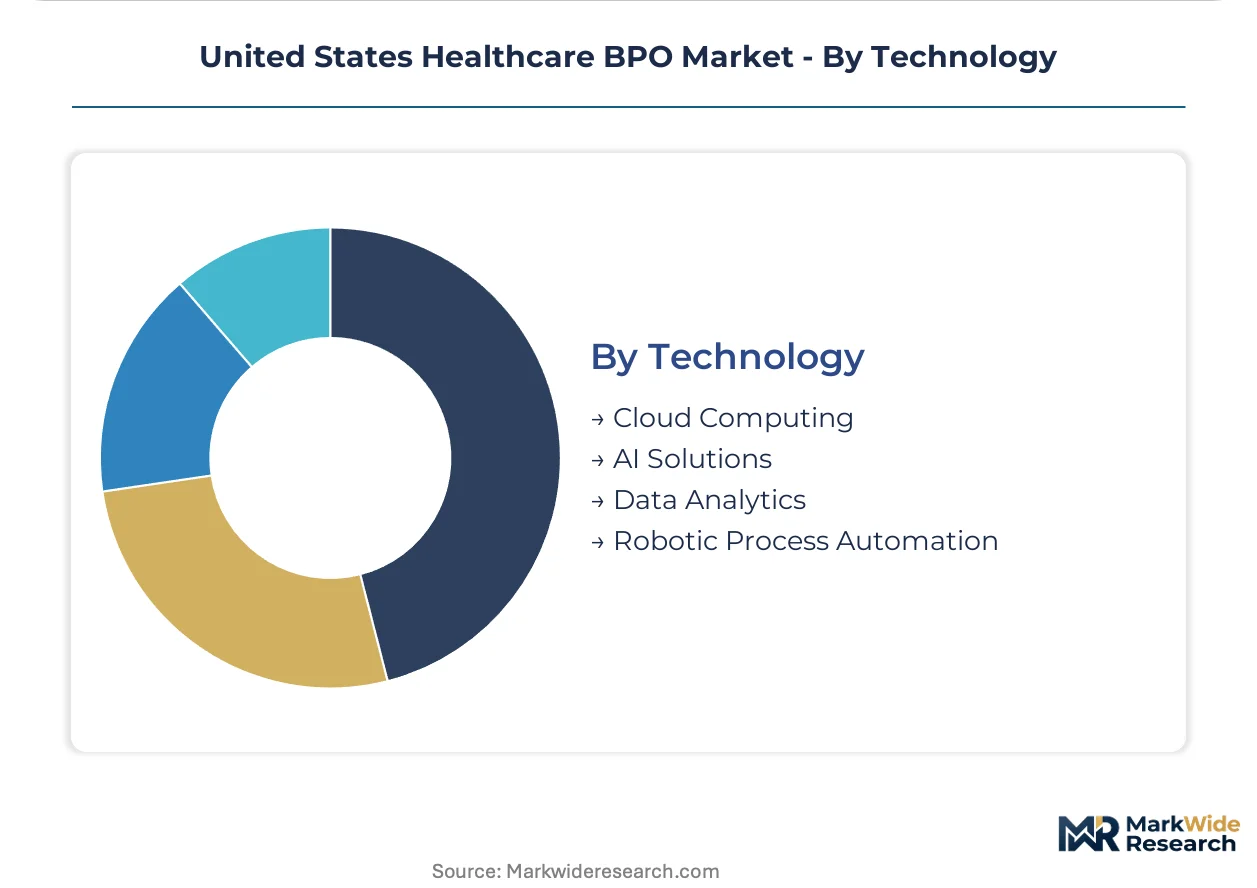
Technology:
Cloud deployment models stratify across public hyperscale infrastructure and private hosted environments for PHI-sensitive workloads, with AI solutions capturing disproportionate R&D investment.
- Cloud Computing:HIPAA-compliant infrastructure-as-a-service enables elastic scaling for seasonal claims volume fluctuations. Concentration risk among hyperscale providers creates single-point-of-failure exposure for vendor negotiation leverage.
- AI Solutions:Machine learning models trained on medical ontologies automate prior authorization letters and clinical narrative generation for Medicare Advantage plans.
- Data Analytics:Population health dashboards and risk stratification tools support value-based care reporting.
- Robotic Process Automation:Rules-based bots handle eligibility verification and claims status inquiries.
Cloud infrastructure underpins operational scalability. AI-enabled platforms are climbing the fastest among technology investment priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Texas and Florida concentrate vendor relationships among multi-hospital networks, while CMS value-based care mandates reshape administrative outsourcing demand across state Medicaid programs.
Texas
Multi-hospital IDNs in Dallas-Fort Worth and Houston consolidate revenue cycle management procurement under long-term master service agreements. The Texas Health and Human Services Commission's Medicaid managed care expansion elevates beneficiary eligibility complexity. San Antonio and Austin health systems concentrate vendor selection among firms with regional delivery infrastructure.
Florida
Nonprofit hospital networks in Miami-Dade and Tampa Bay prioritize integrated technology stacks over point-solution contracts. Florida's Agency for Health Care Administration enforces strict balance billing prohibitions that restructure patient financial communications. Orlando health systems generate scale economies for vendors with specialized denial management capabilities.
California
Medicare Advantage plans in Los Angeles and San Francisco deploy AI-enabled claims adjudication for enrollment growth. The California Department of Managed Health Care enforces price transparency mandates that reshape out-of-network claims protocols. San Diego health systems concentrate procurement among vendors with cloud-native platforms.
New York
Integrated delivery networks in New York City and Long Island expand outsourcing partnerships under state Medicaid redesign initiatives. The New York State Department of Health enforces interoperability mandates that accelerate legacy EHR modernization. Buffalo and Rochester health systems favor vendors with clinical coding specialization.
Illinois
Chicago-area health systems consolidate vendor relationships to reduce contract management overhead under value-based care contracts. The Illinois Department of Healthcare and Family Services manages Medicaid managed care procurement cycles that create entry points for specialized vendors. Peoria and Springfield hospitals concentrate RCM procurement among regional delivery centers.
United States Healthcare BPO Market Key Industry Players
Player mix skews toward vertically integrated payer-affiliated entities and specialized revenue cycle management firms. Market structure concentrates around three tiers: payer-owned platforms with captive data infrastructure, pure-play RCM specialists with deep clinical coding expertise, and diversified IT services firms with healthcare verticals. Dominant competitive moves include multi-year master service agreement consolidation and AI-enabled platform modernization.
Within the payer-affiliated tier, Optum leverages vertically integrated payer-provider data infrastructure. Cognizant sustains positioning through specialized clinical coding operations. Genpact anchors significant volume through long-term pharmaceutical firm partnerships. These three represent distinct archetypes: captive data platforms, coding specialization shops, and pharmaceutical outsourcing anchors.
| Leading Market Players |
|---|
| Optum |
| Cognizant |
| Conduent |
| R1 RCM |
| Genpact |
| IQVIA |
| EXL |
| Accenture |
| Firstsource |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation timelines for Epic and Cerner EHR integrations concentrate vendor pricing power among firms with pre-built API libraries, while HIPAA certification costs compress margin capacity for mid-tier competitors lacking scale economies in compliance infrastructure.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate multi-year master service agreements between hospital IDNs and revenue cycle management vendors. Price differentiation hinges on AHIMA certification density and regional delivery center proximity, with Texas and Florida health systems commanding volume discounts unavailable to standalone community hospitals. Pricing pressure intensifies as cloud infrastructure concentration among hyperscale providers limits vendor negotiation leverage. Standalone clinics exhibit the highest price sensitivity due to constrained IT procurement budgets, while integrated delivery networks prioritize total cost of ownership over per-transaction rates.
Supply Chain Analysis
Inventory-light operating models with 30-45 day talent onboarding cycles characterize clinical coding workforce supply chains concentrated in India, the Philippines, and domestic US metro corridors. Labor inputs draw from AHIMA-accredited training programs, cloud infrastructure subscriptions, and proprietary payer rule engine licenses. Single-source vulnerability in hyperscale PHI hosting creates operational continuity exposure. Distribution runs through direct enterprise sales teams targeting hospital procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward multi-hospital networks consolidating vendor relationships under integrated technology stacks, fragmenting procurement access for point-solution specialists unable to meet enterprise-scale SLA requirements.
For Market Incumbents: Secure AHIMA-credentialed coding talent pipelines through accredited training partnerships before certified professional scarcity worsens. Expand regional delivery infrastructure in Texas and Florida to capture IDN procurement rationalization. Vertical integration into AI-enabled prior authorization tooling defends against generative AI disruptors automating clinical documentation workflows.
For New Entrants and Emerging Players: Specialized denial management expertise for emergency department-intensive health systems represents an under-served service layer where incumbent platforms lack workflow depth. Target Medicaid managed care eligibility verification in states with active procurement cycles. Pursue channel partnerships with Epic and Cerner implementation consultants as primary go-to-market pathway.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because HIPAA enforcement escalation and CMS value-based care mandates continuously elevate compliance barrier thresholds. Acquisition targets should display FDA-validated quality systems for pharmaceutical outsourcing or captive payer data infrastructure. Monitor state Medicaid managed care contract award announcements as inflection indicators for vendor revenue visibility.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Claims Adjudication Platform | Medicare Advantage plans deploy machine learning to compress prior authorization turnaround times under CMS interoperability mandates. |
| Regional Delivery Center Expansion | Multi-hospital IDNs in Texas and Florida consolidate procurement among vendors with localized HIPAA-compliant infrastructure. |
| No Surprises Act Compliance Infrastructure | Federal balance billing prohibitions force restructuring of patient financial communications and IDR workflow capabilities. |
| AHIMA Certification Pipeline Investment | Scarcity of credentialed clinical coders elevates labor costs and constrains scaling velocity for revenue cycle operations. |
| Cloud-Native EHR Integration | Legacy Epic and Cerner architectures require custom API development, extending implementation timelines for modernization projects. |
Research Approach
Operator-level perspectives from revenue cycle directors, hospital procurement officers, HIPAA compliance officers, and payer contract managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare cost reports, GPO contract databases, state Medicaid managed care procurement filings, and hospital 990 financial disclosures. Bottom-up service-line modeling triangulated against top-down payer and provider expenditure estimates.
Sensitivity analysis across ICD-10-CM code expansion scenarios, HIPAA enforcement intensity variations, and cloud infrastructure cost trajectories informed the analytical framework. Segmentation dimensions modeled encompass service type, end-user organization scale, application workflow complexity, and technology deployment architecture. CAGRs derived from regression analysis of historical outsourcing expenditure patterns against regulatory mandate implementation timelines, with Medicare Advantage enrollment growth and state Medicaid expansion status as key forecast inputs.
Forecasts assume regulatory continuity in CMS value-based care programs and HIPAA enforcement protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market