
 Global Cloud Bpo Market | 2026-2036
Global Cloud Bpo Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Bpo Market Foresight
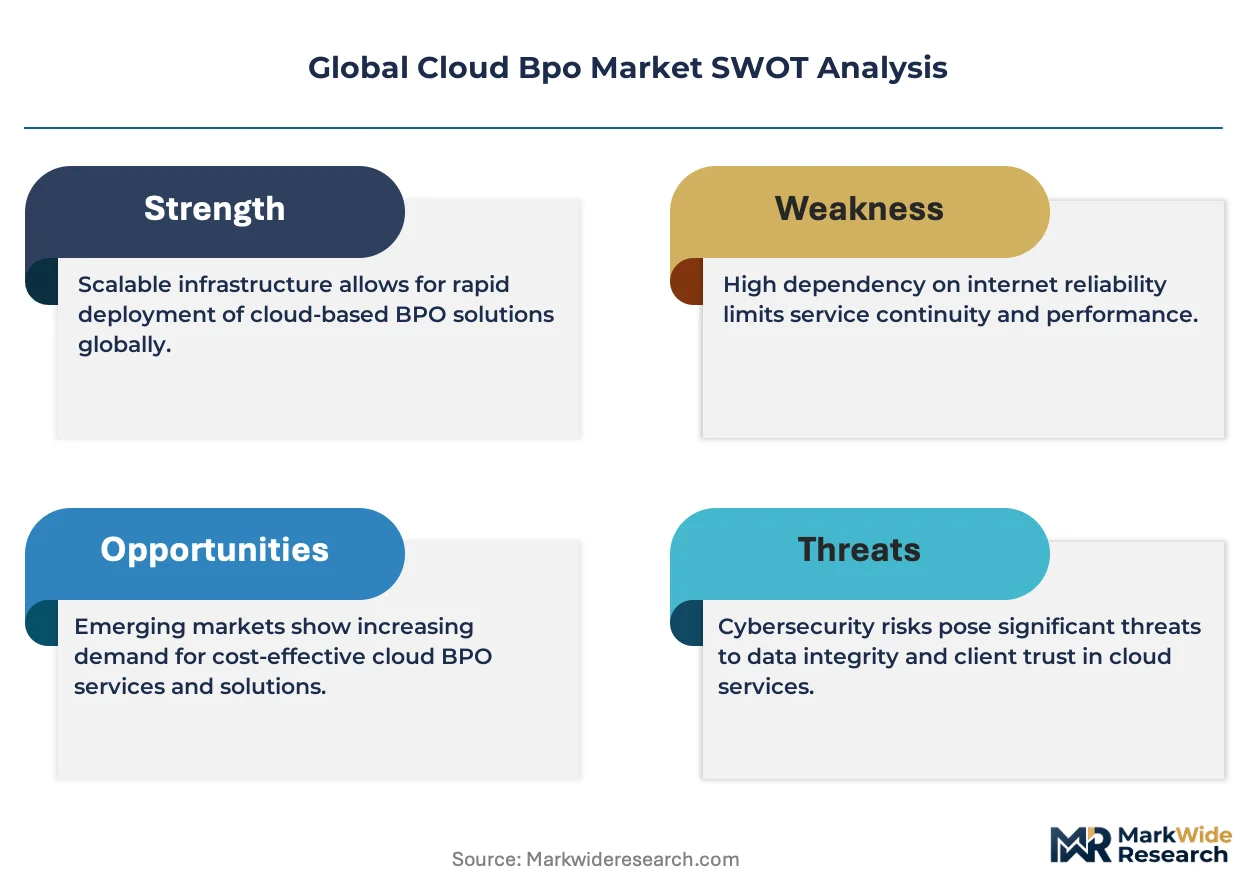
Platform licensing revenue is reconfiguring margin pools away from traditional labor arbitrage toward proprietary automation stacks. Accenture leverages its SynOps platform to embed AI into finance and accounting workflows across banking clients. Tata Consultancy Services anchors its competitive position through the TCS Cognix suite, which controls end-to-end cloud migration for insurance carriers. Genpact specializes in outcome-based contracts that tie fees to measurable cost reduction in healthcare administration.
Cloud BPO denotes the delivery of business process outsourcing services through cloud computing infrastructure, where workloads run on virtualized resources accessible via internet protocols with service-level agreements guaranteeing uptime above 99.9%. The architecture eliminates on-premise capital expenditure while enabling elastic scaling of customer support agents during seasonal demand spikes. Customer Support and Finance & Accounting represent the most mature service type segments with established pricing benchmarks, while IT Helpdesk is accelerating fastest as enterprises consolidate fragmented service desks under single cloud platforms. Hybrid Cloud deployments capture the dominant share of new contracts as regulated industries such as banking and insurance partition sensitive data onto private nodes while routing routine queries through public infrastructure.
The EU AI Act imposes risk-classification requirements on automated decision systems used in credit scoring and insurance underwriting, compelling providers to document algorithmic transparency and human oversight protocols. India's Digital Personal Data Protection Act establishes consent frameworks for cross-border data flows processed by BPO operators in Bangalore and Hyderabad. The US SEC's cybersecurity disclosure rules mandate incident reporting timelines that reshape how cloud BPO contracts allocate liability between vendor and client. Stakeholders must monitor how sovereign data localization mandates fragment previously unified delivery architectures into jurisdiction-specific instances.
Market Dynamics
Platform licensing revenue is reconfiguring margin pools away from labor arbitrage toward proprietary automation stacks, compressing traditional pricing models while elevating vendors with integrated AI layers. Healthcare payers and banking clients now demand outcome-linked contracts that tie fees to measurable operational metrics rather than headcount-based billing.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated decision systems in credit scoring and insurance underwriting compel providers to document algorithmic transparency, accelerating sovereign cloud deployments across European financial services.
- Healthcare claims processing digitization:Payers in the United States are migrating legacy adjudication systems to cloud-native architectures to achieve elastic scaling during enrollment periods and reduce per-claim processing costs.
- India's delivery center concentration:Bangalore and Hyderabad host the largest talent pools for cloud-enabled BPO operations, attracting multinational contracts seeking specialized finance and accounting capabilities at scale.
Market Restraints
- Cross-border data localization costs:India's Digital Personal Data Protection Act and comparable mandates in other jurisdictions fragment unified delivery architectures into jurisdiction-specific instances, raising infrastructure duplication expenses.
- Algorithmic audit requirements:The EU AI Act imposes documentation burdens on high-risk automated systems that extend contract negotiation timelines and inflate legal compliance overhead before revenue recognition.
- Hybrid cloud complexity:Regulated industries partitioning sensitive data onto private nodes while routing routine queries through public infrastructure face integration friction that delays time-to-value for new deployments.
Strategic Opportunities
- Sovereign cloud expansion in Germany:GDPR-aligned data residency requirements create demand for domestically hosted instances serving banking and insurance clients seeking regulatory certainty.
- IT Helpdesk consolidation:Enterprises are unifying fragmented service desks under single cloud platforms, opening whitespace for vendors with multi-channel orchestration capabilities and pre-built connectors to SaaS ecosystems.
- Convergence of generative AI and process mining:Vendors combining large language models with operational telemetry can offer predictive intervention in finance workflows, differentiating beyond cost-based competition.
Industry Challenges
- Human-in-the-loop staffing gaps:The EU AI Act mandates human oversight for high-risk automated decisions, yet qualified compliance officers with both domain and technical expertise remain scarce in delivery centers.
- Legacy system API limitations:Core banking and claims platforms built on COBOL architectures lack modern interfaces, forcing expensive middleware development that erodes cloud migration margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Bpo Market |
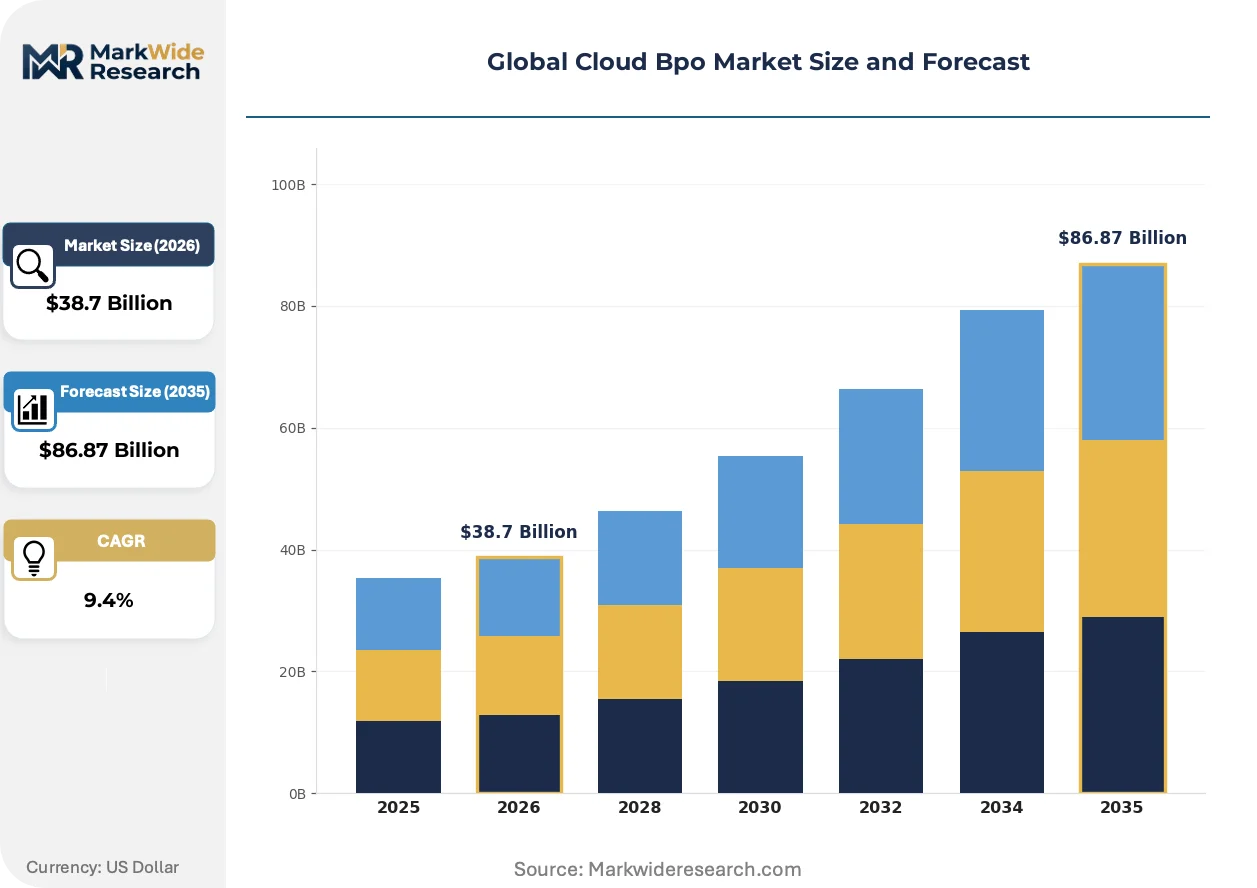
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customer Support, IT Helpdesk, Finance & Accounting, Human Resources, Sales & Marketing Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User Industry: Telecommunications, Banking, Insurance, Manufacturing, Education Contract Model: Fixed Price, Time & Material, Dedicated Team, Outcome-Based |
| Companies Covered | Accenture, IBM, Tata Consultancy Services, Infosys, Cognizant, Genpact, Wipro, Capgemini, EXL Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Bpo Market Shifts & Advancements
Cloud BPO delivery models are hybridizing across infrastructure layers, with automation engines embedding directly into client workflows rather than operating as external service layers. This architectural shift compresses the traditional separation between technology and labor inputs.
Generative AI is hybridizing customer support and finance workflows by embedding inference capabilities directly into agent desktops and reconciliation engines. Banking clients in the United Kingdom and Singapore are piloting these stacks for real-time query resolution and exception handling. The structural consequence is a compression of tier-one support headcounts while elevating vendor margins through software licensing components.
The EU AI Act's risk-tier framework is forcing documentation protocols for automated credit decisions and insurance underwriting across European deployments. Providers must maintain algorithmic transparency logs and human override mechanisms that extend implementation cycles. Healthcare administration and retail banking segments face the steepest compliance curves, with vendors responding through pre-certified workflow templates.
Outcome-based commercial structures are displacing full-time-equivalent pricing in healthcare payer contracts, with fees tied to claims accuracy rates and processing cost reduction. This model shift concentrates buyer power among large insurers while marginalizing smaller BPO operators lacking performance data histories. The United States exhibits the most advanced contract structures, with similar patterns emerging in Australian and Canadian health administration markets.
Global Cloud Bpo Market Segmentation
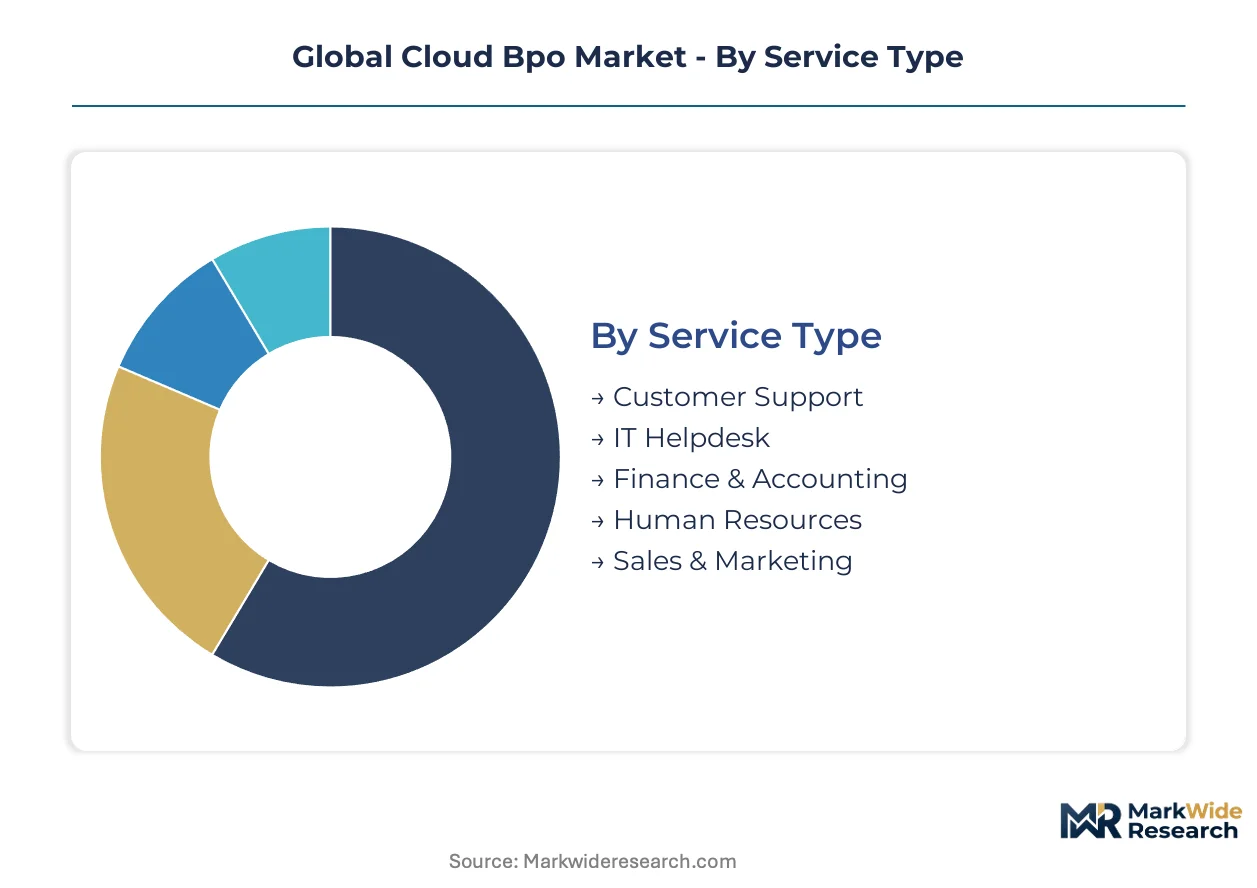
Cloud BPO segmentation reveals how infrastructure choices, service specialization, and commercial structures reshape competitive positioning across delivery models. Understanding these dimensions exposes where automation investments concentrate and which contract architectures capture margin expansion.
Service Type:
Use-case spectrum spans transactional processing through advisory workflows, with maturity curves diverging sharply across functional domains.
- Customer Support:Voice, chat, and email resolution workflows delivered through cloud-native contact center platforms. Demand concentrates in telecommunications carriers across India and the Philippines, driven by seasonal elasticity requirements during product launch windows.
- Finance & Accounting:Accounts payable, receivable, and reconciliation processes augmented by AI-powered exception handling. Banking clients in the United States and United Kingdom anchor volume, compelled by regulatory pressure for audit trail transparency and cost-per-transaction reduction.
- IT Helpdesk:Multi-channel technical support integrating with SaaS ecosystems and endpoint management tools.
- Human Resources:Payroll administration, benefits enrollment, and talent acquisition process outsourcing.
- Sales & Marketing:Lead qualification, campaign management, and customer analytics services.
Established volume favors Customer Support; emerging adoption favors IT Helpdesk.
Deployment Model:
Cost-to-control tradeoffs fragment procurement patterns across risk tolerance profiles and data sensitivity classifications.
- Hybrid Cloud:Partitioned architectures routing sensitive workloads through private nodes while leveraging public infrastructure for routine operations. Banking and insurance carriers in Germany and France mandate this configuration to satisfy GDPR and EU AI Act requirements without sacrificing scalability.
- Public Cloud:Shared infrastructure delivering elastic capacity at utility pricing. Retail and education sectors in the United States and Australia gravitate here, prioritizing speed-to-deployment over data sovereignty.
- Private Cloud:Single-tenant environments with dedicated hardware and network isolation.
- Community Cloud:Collaborative infrastructure shared among organizations with common compliance obligations.
Procurement concentration tilts toward Hybrid Cloud in regulated sectors; Public Cloud dominates where compliance overhead is lighter.
End User Industry:
Application intensity varies by sector digital maturity and regulatory surface area, with financial services commanding premium automation layers.
- Banking:Core processing, compliance documentation, and customer onboarding workflows. Institutions in Singapore and Switzerland deploy sovereign cloud instances to satisfy national data localization while integrating AI-driven fraud detection.
- Insurance:Claims adjudication, policy administration, and actuarial support services. Payers in the United States and Germany are climbing the fastest as legacy system migrations accelerate and outcome-based contracts take hold.
- Telecommunications:Subscriber management, billing inquiry resolution, and network operations support.
- Manufacturing:Supply chain finance, vendor onboarding, and after-sales service operations.
- Education:Enrollment processing, financial aid administration, and alumni engagement services.
Margin capture concentrates in Banking; steepest expansion trajectory appears in Insurance.
Contract Model:
Commercial architecture determines how risk transfers between vendor and client, with performance linkage reshaping buyer-vendor power dynamics.
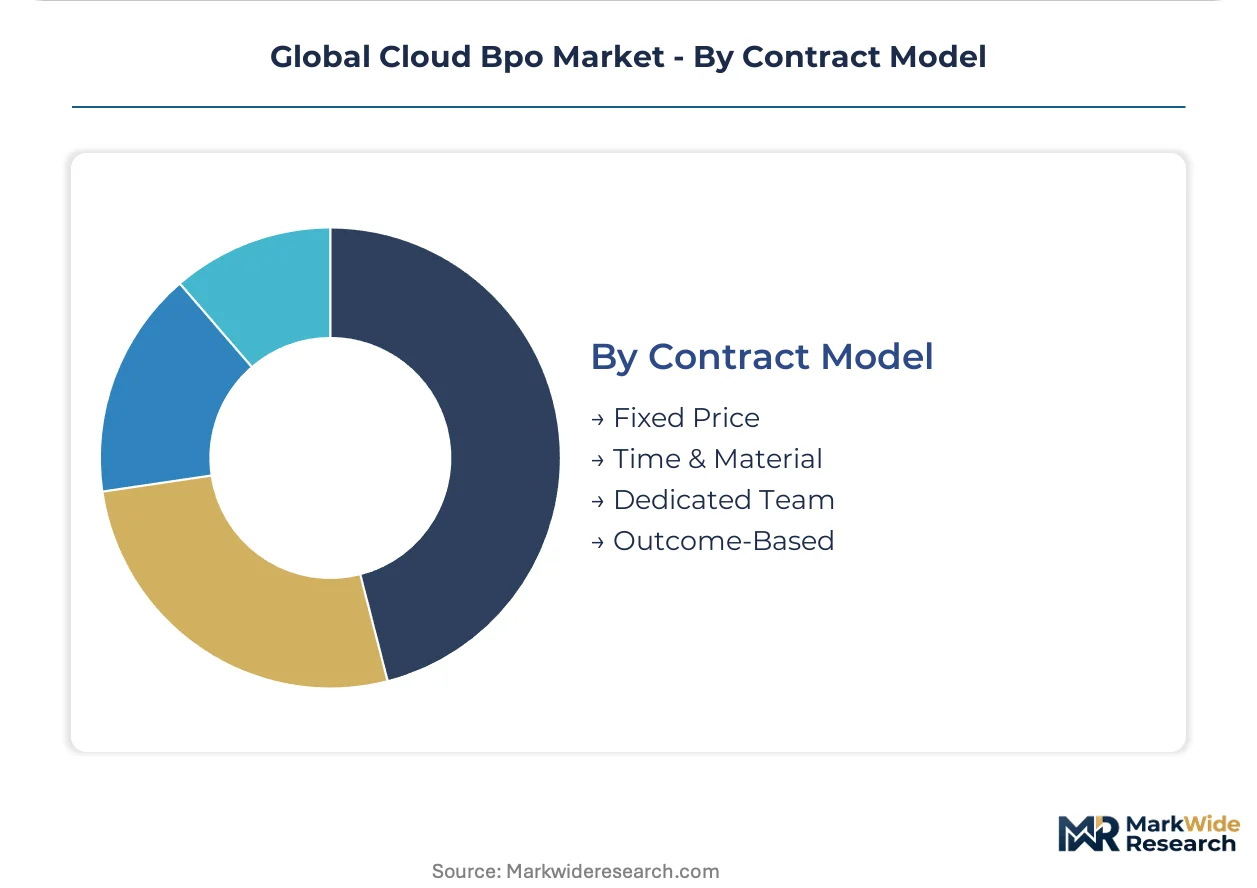
- Outcome-Based:Fee structures tied to measurable operational metrics such as cost reduction percentages or accuracy rates. Healthcare payers in the United States and Australia prefer this model, aligning vendor incentives with claims processing efficiency targets.
- Dedicated Team:Exclusive staffing arrangements with committed personnel and knowledge retention guarantees. Technology firms in Israel and Ireland leverage these contracts for complex product support requiring deep domain immersion.
- Fixed Price:Predetermined fees for defined scope deliverables with change-order mechanisms for expansion.
- Time & Material:Hourly or daily rates billing actual resource consumption against approved estimates.
Contract evolution favors Outcome-Based in mature verticals; Dedicated Team persists where knowledge specificity creates switching costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud BPO consumption patterns diverge sharply by jurisdiction: United States buyers prioritize outcome-based pricing for healthcare claims processing, while European procurement mandates sovereign data residency, and Indian delivery centers anchor global labor arbitrage despite rising localization costs.
United States
Healthcare payers and banking institutions drive demand for elastic claims processing and AI-augmented finance workflows. SEC cybersecurity disclosure rules mandate incident reporting timelines that reshape vendor liability allocation in cloud contracts. Delivery concentration centers on Texas and Arizona, where specialized finance and accounting talent pools support seasonal scaling for insurance enrollment periods.
Germany
GDPR-aligned data residency requirements and EU AI Act risk-classification mandates compel banking and insurance carriers toward sovereign cloud deployments. The national financial regulator BaFin enforces algorithmic transparency documentation for automated credit decisions. Frankfurt and Munich host the dominant domestic delivery infrastructure, with vendors partitioning sensitive workloads onto private nodes while routing routine operations through compliant public infrastructure.
India
The Digital Personal Data Protection Act establishes consent frameworks for cross-border data flows processed by BPO operators, fragmenting previously unified architectures. Bangalore and Hyderabad concentrate the largest talent pools for cloud-enabled finance and accounting operations, attracting multinational contracts seeking specialized capabilities at scale. Rising infrastructure duplication costs from localization mandates compress margins for operators serving European and North American clients simultaneously.
United Kingdom
Banking clients pilot generative AI integration into customer support and exception handling workflows, compressing tier-one support headcounts while elevating vendor margins through software licensing. The Financial Conduct Authority maintains oversight of algorithmic decision systems in credit and insurance applications. London anchors demand for high-complexity advisory services, while regional delivery centers in Manchester and Birmingham handle transactional processing volumes.
Singapore
Financial services institutions deploy sovereign cloud instances to satisfy national data localization while integrating AI-driven fraud detection into core processing workflows. The Monetary Authority of Singapore enforces technology risk management guidelines that extend to outsourced cloud operations. The city-state functions as a regional hub for banking and insurance BPO serving Southeast Asian markets, with vendors maintaining dedicated private cloud infrastructure for sensitive client data.
Global Cloud Bpo Market Competitive Landscape
Capability concentration sits with platform-integrated specialists; scale advantage sits with global IT services conglomerates. The vendor base stratifies across three tiers: proprietary automation stack owners capturing margin expansion through licensing revenue, labor-arbitrage operators defending position through delivery center scale, and outcome-based contract specialists aligning fees with measurable operational metrics. Dominant competitive moves include strategic partnerships embedding automation engines into client workflows and geographic expansion establishing jurisdiction-specific sovereign cloud instances.
Among India-based IT services conglomerates, Tata Consultancy Services and Infosys exemplify the scale-tier archetype, anchoring competitive position through delivery center concentration in Bangalore and Hyderabad. Accenture occupies a position within the platform-integrated specialist tier, leveraging proprietary automation stacks to capture margin expansion beyond traditional labor arbitrage. These three entities represent contrasting strategic postures: captive delivery scale, hybrid cloud orchestration capability, and outcome-based commercial architecture.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| Tata Consultancy Services |
| Infosys |
| Cognizant |
| Genpact |
| Wipro |
| Capgemini |
| EXL Service |
| Others |
Supply & Pricing Matrix
Submarine cable corridors linking India to Europe and the United States carry the bulk of cross-border data traffic for cloud BPO operations, with bandwidth cost volatility feeding directly into delivery center economics and downstream contract pricing tiers. This infrastructure geography concentrates pricing power among operators with redundant fiber paths while fragmenting margin capture for single-route dependent competitors.
Pricing Analysis
Long-term outcome-based contracts dominate healthcare payer relationships in the United States and Australia, with fees indexed to claims accuracy rates and per-transaction cost reduction rather than headcount. Price differentiation hinges on AI automation depth and GDPR/EU AI Act certification tier, with sovereign cloud instances commanding premiums over standard public deployments. Cost compression in transactional processing tiers is intensifying as generative AI displaces tier-one support headcounts. Large insurers exhibit lowest price sensitivity due to performance data requirements, while mid-market retail clients drive hardest bargain negotiations.
Supply Chain Analysis
Upstream talent feedstock draws from specialized university pipelines in Bangalore, Hyderabad, and Manila, with secondary recruitment corridors emerging in Vietnam and Poland for multilingual capabilities. Cloud infrastructure provisioning rests on hyperscaler data center networks concentrated in India, Germany, and Singapore, with API middleware development increasingly sourced from Eastern European engineering clusters. Single-source vulnerability sits with Bangalore-Hyderabad delivery concentration exposed to India's Digital Personal Data Protection Act localization mandates. Distribution runs through direct enterprise sales teams for banking clients and channel partners for mid-market manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large healthcare payers and multinational banks capable of dictating outcome-based contract terms, marginalizing smaller BPO operators lacking performance data histories. This consolidation fragments competitive positioning for labor-arbitrage dependent vendors.
For Market Incumbents: Build proprietary automation stack moats through embedded AI licensing revenue that displaces headcount-dependent margins. Deepen sovereign cloud orchestration capabilities across Germany and Singapore to capture GDPR and MAS compliance premiums. Defend against emerging platform-native entrants by accelerating TCS Cognix and SynOps feature parity with generative AI inference layers.
For New Entrants and Emerging Players: Establish a beachhead in IT Helpdesk consolidation whitespace where fragmented service desk unification demands multi-channel orchestration capabilities. Target mid-market insurance carriers in Australia and Canada seeking outcome-based contract structures without incumbent data history requirements. Lead with pre-certified EU AI Act workflow templates to compress implementation cycles against established competitors.
For Investors and Strategic Acquirers: Niche automation specialists with pre-built healthcare claims adjudication modules represent the highest-conviction acquisition archetype for platform integration strategies. Sovereign cloud infrastructure plays in Frankfurt and Singapore offer defensive positioning as data localization mandates proliferate. Watch for inflection signals in BaFin algorithmic transparency enforcement timelines that will accelerate vendor consolidation among compliance-lagged operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding SynOps and Cognix automation engines directly into client ERP systems captures recurring licensing revenue. |
| Sovereign Cloud Expansion | Germany and Singapore data residency deployments satisfy BaFin and MAS requirements for banking core processing. |
| Outcome-Based Contracting | Healthcare payer relationships tied to claims accuracy rates align vendor incentives with measurable cost reduction. |
| Generative AI Deployment | Agent desktop inference capabilities in UK and Singapore banking pilots compress tier-one support headcounts. |
| Geographic Delivery Diversification | Vietnam and Poland recruitment corridors reduce Bangalore-Hyderabad concentration risk from Indian data localization. |
Research Methodology
Cross-validation between primary interviews with cloud BPO delivery heads and secondary validation through SEC cybersecurity disclosure filings anchors the qualitative findings. Stakeholder roles engaged include CTOs at multinational banks, healthcare payer operations executives, hyperscaler platform engineers, and EU regulatory compliance officers. Secondary sources comprise BaFin algorithmic transparency guidance, MAS technology risk management circulars, Indian Digital Personal Data Protection Act implementation rules, and customs data on submarine cable bandwidth provisioning. Bottom-up contract value aggregation triangulates against top-down market sizing from delivery center capacity and headcount estimates.
Calibration against historical contract win announcements and disclosed automation stack deployment timelines validates the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model architecture, service type maturity curve, end-user industry regulatory intensity, and contract model risk-transfer structure. CAGRs derive from elasticity-adjusted volume projections and price-per-transaction compression curves. Industry-specific inputs incorporate EU AI Act implementation phase transitions and healthcare claims migration velocity from legacy COBOL systems.
Sensitivities concentrate around sovereign data localization mandate expansion and generative AI capability commoditization timelines. Forecasts reflect assumptions on regulatory enforcement intensity and hyperscaler infrastructure capacity expansion without guaranteed alignment to actual policy implementation. Cross-checking against disclosed automation stack customer counts and outcome-based contract renewal rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market