
 Legal Process Outsourcing (LPO) Market | 2026-2036
Legal Process Outsourcing (LPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Process Outsourcing (LPO) Market Analysis
Subscription-based contract analytics is restructuring how legal departments procure external support, shifting from hourly billing to outcome-based retainers. UnitedLex leverages its technology platform to anchor large-scale document review engagements for Fortune 500 legal departments. Elevate Services competes through vertical specialization in compliance workflows for financial services clients. QuisLex differentiates by controlling quality benchmarks across multi-jurisdictional litigation support operations.
Legal process outsourcing encompasses the delegation of legal tasks—ranging from document review and legal research to contract lifecycle management—to external providers operating under defined service-level agreements with turnaround parameters measured in hours or business days. Its primary commercial purpose is to reduce legal expenditure while maintaining privilege protection and regulatory adherence through standardized workflows. Document review occupies the largest revenue pool within service type segmentation due to e-discovery volume growth, while contract management represents the fastest-expanding category as enterprises seek automated clause extraction and obligation tracking. The offshore delivery model dominates absolute volume, though hybrid structures capturing onshore oversight with offshore execution capture expanding margin pools as data residency requirements tighten.
The UK's Solicitors Regulation Authority and the EU's GDPR framework shape cross-border data handling protocols, compelling providers to maintain segregated infrastructure for client matter processing. India's Information Technology Act and the US HIPAA provisions for healthcare-related legal work further fragment compliance requirements across delivery corridors. Stakeholders must monitor evolving data localization mandates and privilege preservation standards as jurisdictions tighten oversight of cross-border legal service delivery.
Market Dynamics
Data localization mandates are fragmenting delivery architectures across the Legal Process Outsourcing sector, compelling providers to replicate infrastructure across multiple jurisdictions rather than consolidating in single offshore hubs. This structural pressure is elevating compliance costs while simultaneously creating protected market positions for regionally anchored operators.
Growth Catalysts
- GDPR Article 44-49 transfer restrictions:European corporate legal departments must verify adequate protection for cross-border matter processing, creating specialized demand for EU-based review centers with segregated data environments.
- Healthcare litigation volume:HIPAA-covered entities generate sustained document review demand requiring Business Associate Agreements with technical safeguards for protected health information.
- Contract lifecycle automation:Enterprise procurement functions deploy AI-powered clause extraction to flag indemnification and limitation-of-liability terms across vendor agreements.
Market Restraints
- Privilege waiver exposure:US Federal Rules of Evidence 502 and inconsistent state-level protections create structural uncertainty when non-attorney personnel handle attorney-client communications.
- India IT Act compliance infrastructure:Mandatory local server deployment and resident nodal officers impose fixed cost burdens that scale poorly with transaction volume.
- Technical limitation in machine translation:Nuanced contractual interpretation across civil and common law traditions remains resistant to automated accuracy thresholds required for binding obligation extraction.
Strategic Opportunities
- Australian corporate legal departments:Relatively immature managed legal services adoption compared to UK and US counterparts offers first-mover positioning for platform-based contract analytics providers.
- Convergence of e-discovery and cybersecurity forensics:Incident response retainers increasingly bundle data breach notification obligations with litigation hold protocols, expanding addressable service scope.
- UK Solicitors Regulation Authority transparency rules:Mandatory disclosure of external spend creates procurement urgency for spend analytics dashboards that benchmark LPO rates against peer institutions.
Industry Challenges
- Attorney admission barriers:Multi-jurisdictional litigation support requires supervising counsel licensed in relevant forums, constraining staffing flexibility and inflating supervisory ratios.
- Legacy practice management integration:Law firm time-and-billing systems resist API connectivity with external matter management platforms, forcing manual reconciliation workflows.
- ISO 27001 certification timelines:Information security management system audits extend 12-18 months, delaying client onboarding for security-sensitive engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Process Outsourcing (LPO) Market |
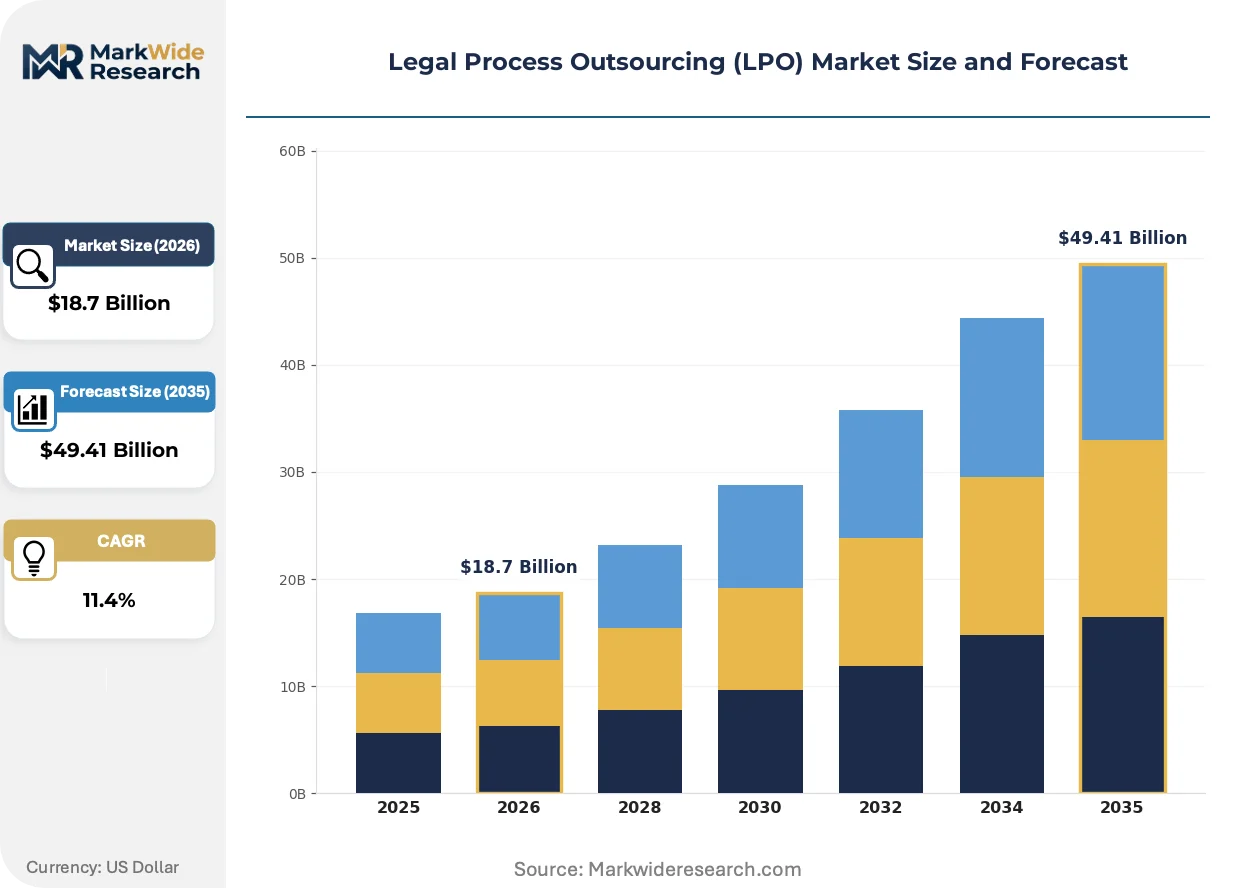
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Document Review, Legal Research, Contract Management, Compliance Services Client Type: Law Firms, Corporations, Government Agencies, Startups Delivery Model: Onshore, Offshore, Hybrid, Remote Industry Vertical: Healthcare, Finance, Technology, Real Estate |
| Companies Covered | Consilio, Insignia Resources, UnitedLex, Infosys Limited, Elevate Services, EY Legal Managed Services, QuisLex, Clarivate Plc, Integreon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Process Outsourcing (LPO) Market Emerging Trajectories
Technology platforms are restructuring competitive boundaries in legal services, compressing the distinction between software vendors and service providers while elevating outcome-based contracting over hourly rate structures.
Natural language processing engines trained on judicial opinions and transactional precedents are converging with contract repository systems to auto-generate redline comparisons against market-standard clauses. Mid-market corporate legal departments in the United States are piloting these tools for NDAs and vendor agreements. The technology is converging with traditional document review workflows, enabling continuous contract monitoring rather than episodic manual audits.
EU AI Act risk classification frameworks now categorize certain legal AI applications as high-risk when they influence judicial or administrative decisions. Providers deploying automated contract analysis across European jurisdictions must implement conformity assessment procedures and maintain human oversight protocols. Financial services legal teams in Frankfurt and Paris are restructuring vendor diligence questionnaires to capture algorithmic transparency documentation.
General counsel functions are consolidating external spend under enterprise procurement umbrellas, displacing relationship-driven panel appointments with competitive tender processes. Law firm clients now require detailed service-level metrics including first-pass quality rates and cycle time distributions. This pattern is most pronounced among Fortune 500 manufacturing and technology enterprises with centralized legal operations functions.
Legal Process Outsourcing (LPO) Market Segmentation
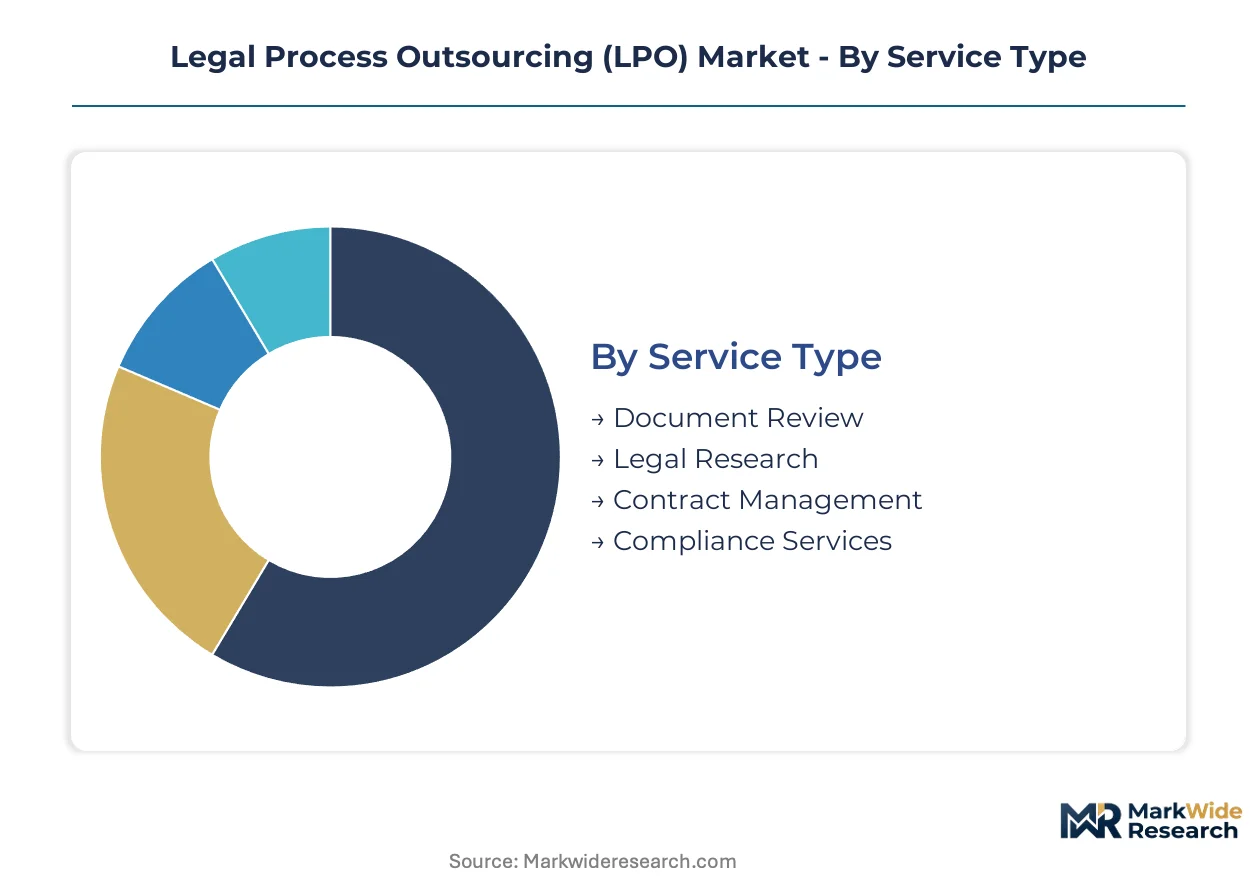
Segmentation in the Legal Process Outsourcing market reveals how compliance burdens, delivery architectures, and client sophistication stratify procurement patterns. Each dimension carries distinct certification requirements that reshape provider economics and competitive positioning.
Service Type:
ISO 27001 certification anchors information security protocols across all service categories, though HIPAA Business Associate Agreements govern healthcare-related document review while GDPR adequacy decisions shape EU-facing contract management engagements.
- Document Review:E-discovery processing of electronically stored information demands forensic chain-of-custody protocols and technology-assisted review platforms. US litigation departments generate concentrated volume through privilege logs and responsive document identification, constrained by Federal Rules of Evidence 502 waiver exposure.
- Contract Management:AI-powered clause extraction and obligation tracking systems require algorithmic transparency documentation under EU AI Act high-risk classifications. Enterprise procurement functions in the United Kingdom and Australia prioritize automated indemnification flagging and limitation-of-liability term monitoring.
- Legal Research:Multi-jurisdictional precedent analysis and regulatory monitoring services.
- Compliance Services:Regulatory filing preparation and policy gap assessments for financial services clients.
Document review sits at the top of the volume ranking, with contract management climbing the fastest.
Client Type:
Procurement sophistication tiers separate retained-counsel relationships from competitive tender processes, with Fortune 500 legal operations demanding outcome-based SLAs while smaller entities retain hourly billing conventions.
- Law Firms:Managed services partnerships contain litigation cost overruns through defined turnaround parameters. US-based Am Law 200 firms drive adoption of hybrid delivery models combining onshore partner oversight with offshore attorney staffing.
- Corporations:Centralized legal operations functions consolidate external spend under enterprise procurement umbrellas. Manufacturing and technology enterprises mandate first-pass quality rate metrics and cycle time distribution reporting.
- Government Agencies:Public sector procurement regulations impose vendor qualification thresholds and domestic preference requirements.
- Startups:Cost-constrained entities prioritize fixed-fee contract templates and automated NDA generation over comprehensive managed services.
Law firms command the largest current spend pool, though corporate legal departments are expanding their share most rapidly.
Delivery Model:
Data residency mandates fragment infrastructure deployment, with localized server requirements elevating fixed costs for offshore operators while creating protected positions for regionally anchored competitors.
- Offshore:India-based delivery centers leverage attorney wage arbitrage for high-volume document review. The country's Information Technology Act mandates resident nodal officers and local server deployment, imposing compliance infrastructure that scales poorly with transaction volume.
- Hybrid:Onshore supervising counsel with offshore execution teams balance privilege protection against cost containment. This architecture captures expanding margin pools as GDPR Article 44-49 transfer restrictions tighten.
- Onshore:Domestic delivery satisfies data localization requirements for healthcare and financial services matters.
- Remote:Distributed attorney networks enable surge capacity without facility overhead.
Offshore delivery maintains absolute volume leadership, with hybrid structures gaining share fastest.
Industry Vertical:
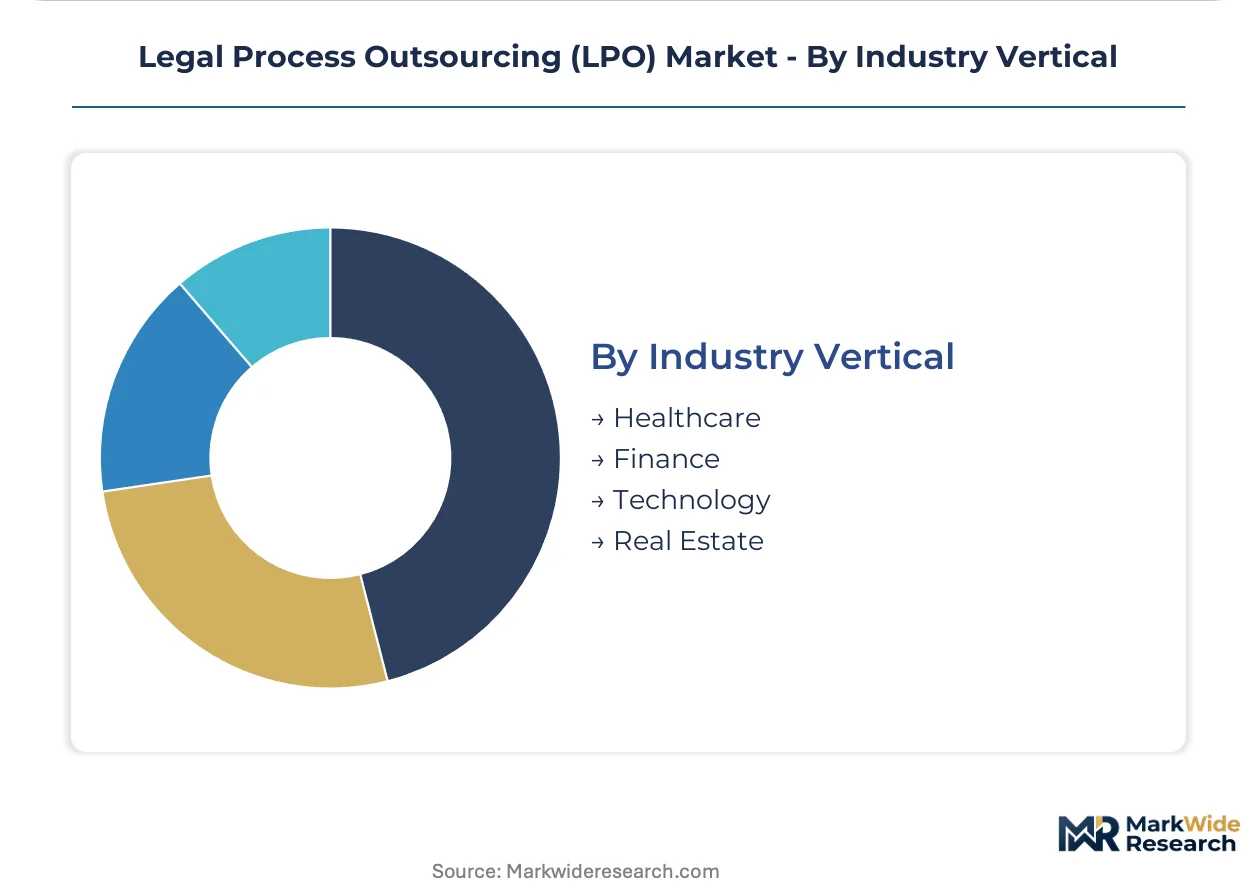
Sector-specific regulatory frameworks determine privilege preservation standards and technical safeguard requirements, with healthcare and finance imposing the most stringent compliance overlays.
- Healthcare:HIPAA-covered entities generate sustained document review demand through medical malpractice and pharmaceutical litigation. Technical safeguards for protected health information require encrypted transmission protocols and access audit trails.
- Finance:Basel III operational risk frameworks and SEC disclosure obligations drive contract lifecycle management adoption. Frankfurt and Paris-based legal teams restructure vendor diligence to capture algorithmic transparency documentation.
- Technology:Intellectual property litigation and open-source license compliance support.
- Real Estate:Title examination and lease abstraction services for portfolio management.
Healthcare anchors current vertical spending, with finance showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing delivery geography as cost-of-compliance gaps widen between jurisdictions. Providers now replicate infrastructure across multiple countries rather than consolidating in single offshore hubs. Data localization mandates in India and GDPR transfer restrictions in Europe fragment traditional concentration patterns.
United States
Am Law 200 firms drive managed services partnerships for litigation cost containment. HIPAA technical safeguards govern healthcare-related document review requiring encrypted transmission protocols. New York and Washington DC legal departments anchor demand for hybrid delivery combining onshore partner oversight with offshore execution.
India
Attorney wage arbitrage sustains high-volume document review operations for foreign clients. The Information Technology Act mandates resident nodal officers and local server deployment. Bangalore and Hyderabad delivery centers absorb compliance infrastructure costs that scale poorly with transaction volume.
United Kingdom
Corporate legal departments prioritize contract management spend visibility through automated clause extraction. The Solicitors Regulation Authority transparency rules mandate external spend disclosure. London-based procurement functions benchmark LPO rates against peer institutions using analytics dashboards.
Germany
Financial services legal teams restructure vendor diligence for algorithmic transparency documentation. EU AI Act high-risk classifications require conformity assessment for automated contract analysis. Frankfurt legal operations anchor compliance-focused managed services demand.
Australia
Relatively immature managed legal services adoption offers first-mover positioning for platform-based providers. Corporate legal departments prioritize automated indemnification flagging across vendor agreements. Sydney and Melbourne procurement functions pilot outcome-based retainers over hourly billing.
Legal Process Outsourcing (LPO) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-anchored platforms capturing premium positioning over pure staffing models. The vendor base stratifies across three tiers: global consultancies with legal managed services divisions, pure-play LPO specialists with proprietary platforms, and offshore IT services firms with legal verticals. Dominant competitive moves include vertical specialization in compliance workflows and geographic expansion through localized infrastructure deployment.
Among platform-based specialists, UnitedLex and Elevate Services occupy positions at the technology-enabled tier, while QuisLex exemplifies quality-controlled multi-jurisdictional operations. UnitedLex leverages its technology platform for large-scale document review engagements. Elevate Services competes through vertical specialization in financial services compliance workflows. QuisLex differentiates by controlling quality benchmarks across litigation support operations spanning multiple jurisdictions.
| Leading Market Players |
|---|
| Consilio |
| Insignia Resources |
| UnitedLex |
| Infosys Limited |
| Elevate Services |
| EY Legal Managed Services |
| QuisLex |
| Clarivate Plc |
| Integreon |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between ISO 27001-audited providers and uncertified operators splits both pricing power and supply chain architecture, with compliance infrastructure investments creating protected margin positions for audited firms while non-certified competitors absorb price erosion in commoditized document review segments.
Pricing Analysis
Distributor margins for technology-assisted review platforms compress as direct enterprise procurement expands, particularly among Fortune 500 legal operations functions. Pricing stratifies across premium, standard, and economy tiers based on attorney credential depth and algorithmic transparency documentation under EU AI Act requirements. Cost compression in offshore delivery stems from India's Information Technology Act compliance infrastructure scaling poorly with transaction volume. Corporate legal departments exhibit highest price sensitivity, while Am Law 200 firms prioritize outcome-based SLAs over unit cost.
Supply Chain Analysis
Returns and remediation flows for privilege waiver exposure create reverse-logistics complexity, with supervising counsel in the United States, United Kingdom, and Germany requiring document re-review when Federal Rules of Evidence 502 compliance gaps surface. Raw material inputs center on attorney labor pools, technology-assisted review licenses, and segregated data center infrastructure. Single-source vulnerability concentrates in India-based delivery centers dependent on resident nodal officer availability. Distribution runs through direct managed services contracts with hybrid onshore-offshore execution teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where wage differentials between Indian attorneys and US supervising counsel sustain margin pools, while GDPR Article 44-49 transfer restrictions fragment delivery architectures and elevate EU-based provider premiums.
For Market Incumbents: Cement hybrid delivery dominance by acquiring ISO 27001-certified facilities in Germany and Australia before data localization mandates tighten. Vertical integration into proprietary contract analytics platforms defends against pure-software vendors displacing service revenue. Capacity addition in EU review centers captures GDPR-constrained demand from pharmaceutical litigation departments. For New Entrants and Emerging Players: Begin with Australian corporate legal departments where managed services penetration lags UK and US benchmarks by several adoption cycles. White-space exists in outcome-based retainers for mid-market technology enterprises lacking centralized legal operations functions. Platform-based contract analytics with automated indemnification flagging offers the clearest go-to-market angle against incumbent staffing models. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification timelines extend 12-18 months and delay client onboarding for security-sensitive engagements. Long-term viability favors technology-anchored platforms with proprietary AI engines over pure attorney-staffing models. Target acquisition archetype: mid-cap specialists with Frankfurt or Paris financial services client relationships and existing EU AI Act conformity assessment documentation. Signal to watch: healthcare litigation volume acceleration triggering HIPAA technical safeguard capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Infrastructure Deployment | EU-based review centers capture GDPR Article 44-49 constrained demand from corporate legal departments. |
| Proprietary Platform Development | Technology-anchored providers differentiate from staffing competitors through AI-powered clause extraction. |
| Vertical Specialization | Financial services compliance workflows in Frankfurt and Paris command premium outcome-based retainers. |
| Hybrid Delivery Expansion | Onshore supervising counsel with offshore execution balances privilege protection against cost containment. |
| Certification Acceleration | ISO 27001 and EU AI Act conformity assessment documentation shortens enterprise sales cycles. |
Methodological Framework
Coverage spans the United States, India, the United Kingdom, Germany, and Australia, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with general counsel at Fortune 500 manufacturing and technology enterprises, managing partners at Am Law 200 firms, procurement officers at healthcare systems, compliance directors at financial services institutions, and delivery center heads at offshore providers informed demand-side and supply-side perspectives. Secondary sources include SEC filings for publicly traded LPO providers, Solicitors Regulation Authority transparency disclosures, EU AI Act implementation guidance, HIPAA Business Associate Agreement templates, and customs data on legal services trade flows. Bottom-up service-line revenue estimates and top-down addressable market calculations were reconciled to establish baseline figures.
Granularity-level modeling captured service type, client type, delivery model, and industry vertical dimensions at the country level, with attorney wage differentials and compliance cost structures incorporated as region-specific inputs. CAGRs were derived from trend-line analysis of historical outsourcing penetration rates and projected regulatory constraint intensification across the analysis window. Healthcare litigation volume trajectories and contract lifecycle automation adoption curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen privilege waiver precedent shifts, abrupt data localization mandate expansions beyond current jurisdictions, and machine translation breakthroughs eliminating attorney review requirements. Forecasts reflect assumptions about sustained wage arbitrage and regulatory fragmentation. Practitioners should monitor EU AI Act enforcement patterns and India IT Act amendment trajectories for early signals of delivery architecture disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market