
 Dammar Gum Market | 2026-2036
Dammar Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Dammar Gum Market Outlook
Asset-light toll manufacturing and third-party resin processing is narrowing the capital barrier for mid-sized entrants in dammar gum supply. PT Samiraschem Indonesia leverages integrated tapping-to-export operations across Sumatran forests. Nexira Inc. sustains its position through specialized purification protocols for food-grade grades. Willy Benecke anchors European distribution with deep inventory positions in Hamburg.
Dammar gum is a triterpenoid resin exuded by Dipterocarpaceae trees, soluble in turpentine and mineral spirits, with acid values between 20–35 mg KOH/g and softening points near 65–75°C; it functions primarily as a film-forming agent, gloss enhancer, and natural binder across coatings and food systems. Natural dammar dominates volume but carries supply volatility tied to monsoon tapping cycles, while powdered dammar captures expanding ink and adhesive demand due to faster dissolution kinetics. Food additive applications represent the fastest-growing margin pool as manufacturers reformulate away from synthetic glazing agents.
Indonesia's Ministry of Environment and Forestry regulates resin tapping permits and export quotas, while the EU's REACH framework governs chemical registration for coating-grade imports into Europe. FDA food additive regulations and FSSAI standards in India further segment compliance requirements between industrial and ingestible grades. Stakeholders must monitor how biodiversity certification schemes and deforestation due diligence rules reshape raw material eligibility across origin markets.
Market Dynamics
Clean-label confectionery reformulation is compressing synthetic glazing agent volumes while pulling natural dammar into accelerated qualification cycles across Southeast Asian and Indian processing facilities.
Growth Catalysts
- REACH food-contact compliance:European coating-grade importers now prioritize dammar over shellac derivatives, tightening purity specifications and rewarding Indonesian exporters with certified tapping operations.
- India's FSSAI natural additive pathway:Domestic confectioners accelerate dammar trials as the regulator streamlines approval timelines for plant-based glazing agents in hard-boiled candy and chocolate coatings.
- Powdered dammar dissolution kinetics:Ink formulators in Vietnam and Thailand adopt micronized grades for UV-curable overprint varnishes, displacing slower-dissolving lump resin in high-speed flexographic lines.
Market Restraints
- Monsoon-tapping volatility:Sumatran resin yields drop 30-40% during extended wet seasons, forcing processors to carry six-month inventory buffers that compress working capital cycles.
- Shellac price competition:Lac beetle resin from Bihar and Jharkhand undercuts dammar in cost-sensitive Asian coating applications, particularly where gloss requirements fall below 90 GU at 60°.
- ECHA SVHC screening expansion:Impending classification of certain triterpenoid oxidation byproducts as substances of very high concern threatens coating-grade export eligibility to Rotterdam and Hamburg ports.
Strategic Opportunities
- Brazilian confectionery penetration:ANVISA's pending natural glazing agent framework creates first-mover positioning for Indonesian dammar suppliers with pre-submitted technical dossiers.
- Pharmaceutical tablet coating:Enteric film-forming applications represent an untapped margin tier as European generics manufacturers seek alternatives to hypromellose-phthalate systems.
- Direct-to-formulator digital platforms:Specialty chemical marketplaces in Mumbai and Jakarta bypass traditional gum brokers, capturing 8-12 point margin spreads on certified food-grade lots.
Industry Challenges
- Forestry certification integration:FSC chain-of-custody documentation gaps across Sumatran smallholder cooperatives delay EU deforestation regulation compliance timelines by 14-18 months.
- Purification capex escalation:Food-grade resin processing requires stainless-steel solvent recovery systems exceeding $2.4 million per line, excluding mid-tier Indonesian processors from premium segment participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dammar Gum Market |
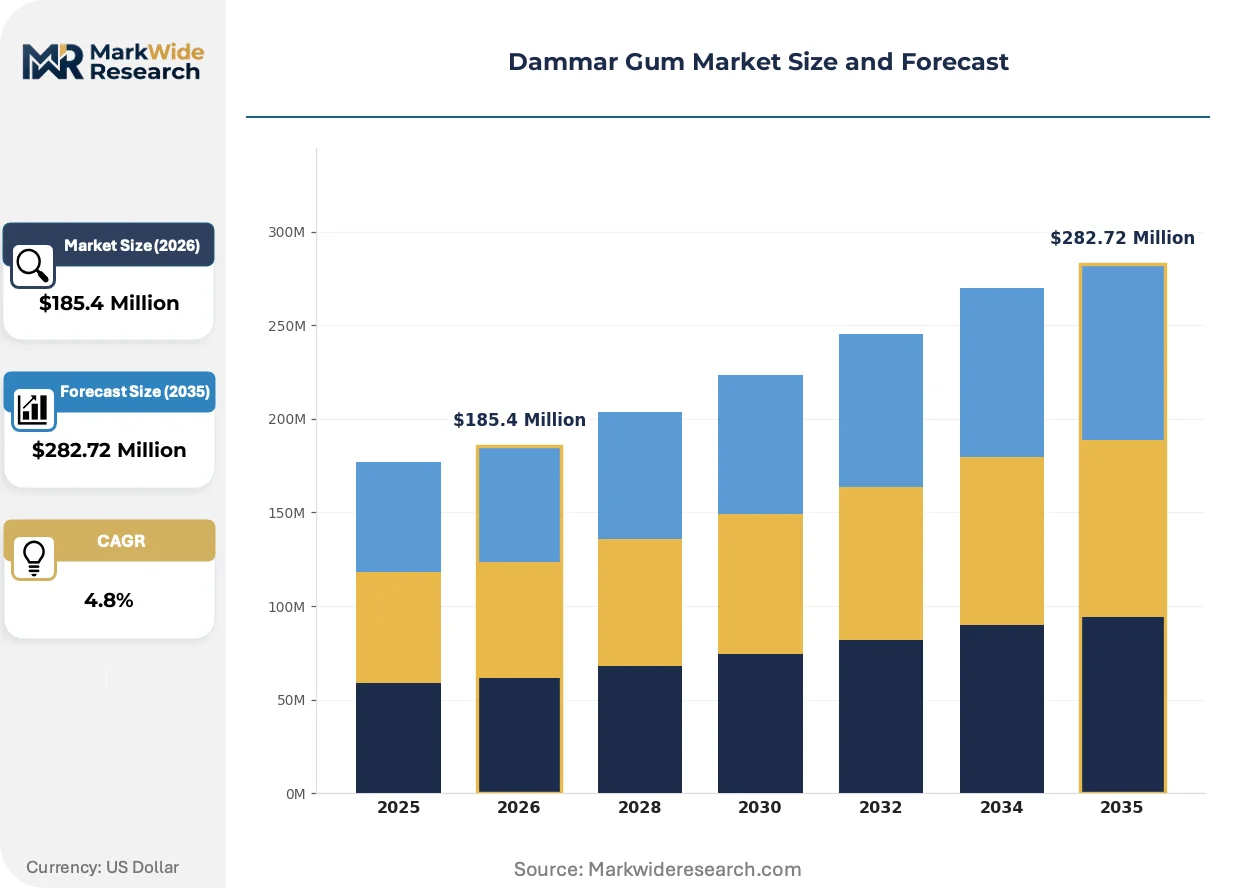
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $282.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dammar, Synthetic Dammar, Powdered Dammar, Solid Dammar Application: Coatings, Adhesives, Ink, Food Additives End User: Chemical Industry, Food Industry, Art Supply Stores, Pharmaceuticals Packaging Type: Bulk Bags, Small Packs, Drums, Canisters |
| Companies Covered | PT Samiraschem Indonesia, Cornelissen & Son, Nexira Inc., Spectrum Chemical Manufacturing, William Bernstein Company, Willy Benecke, Bandish Enterprises, Starlight, Sennelier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dammar Gum Market Strategic Shifts
Reformulation chemistry and regulatory disclosure requirements are forcing simultaneous upgrades across raw material qualification, processing transparency, and end-use certification protocols.
Solvent-based dammar purification is migrating from traditional naphtha extraction to supercritical CO2 systems that eliminate residual aromatic hydrocarbons. European ink manufacturers in Milan and Barcelona now specify CO2-extracted grades for food-contact packaging applications. This migration is compressing conventional processor margins while creating tiered supply structures around extraction technology ownership.
Indonesia's Ministry of Environment and Forestry is tightening export quota allocation to FSC-certified tapping collectives only. Industrial coating-grade shipments to EU ports now require geolocation-verified harvest documentation. Smallholder-dependent processors in Palembang and Jambi face 12-24 month compliance transitions or exclusion from premium European buyer lists.
Confectionery procurement teams in Mumbai and Chennai are consolidating supplier panels from twelve to four qualified dammar sources, demanding batch-level acid value and softening point certificates. This concentration rewards Indonesian exporters with integrated laboratory capabilities while marginalizing traders without in-house testing infrastructure. The shift is most visible in Diwali and Eid seasonal purchasing cycles where qualification lead times now exceed production scheduling windows.
Dammar Gum Market Segmentation
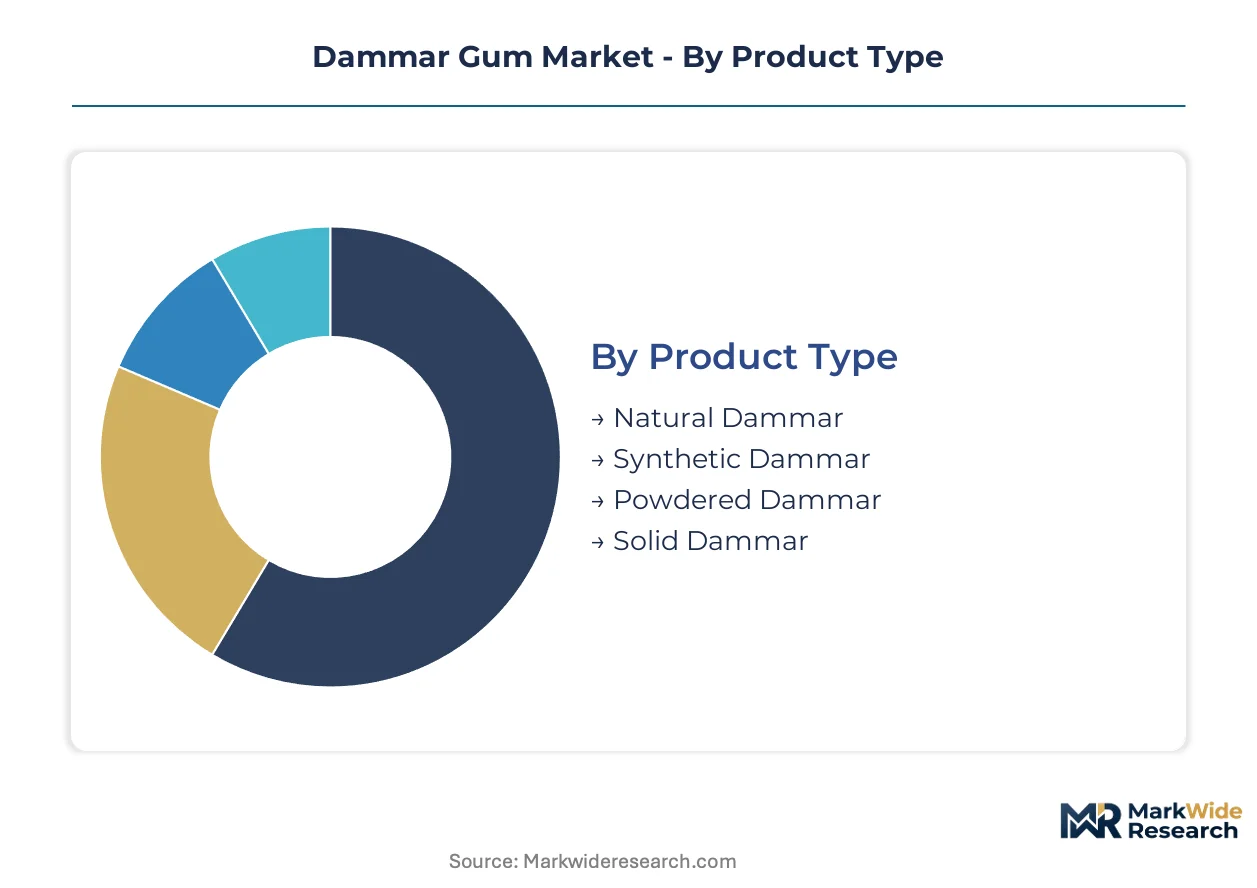
Dammar gum's functional diversity across film-forming, binding, and glazing applications creates distinct specification requirements by product grade. Segmentation reveals how supply chain configuration and regulatory compliance stratify across end-use verticals, with food-grade and coating-grade specifications diverging on purity thresholds and documentation protocols.
Product Type:
Cost tier differentiation separates commodity resin from value-added processed grades, with extraction technology and purification depth determining price positioning.
- Natural Dammar:Raw resin exuded from Dipterocarpaceae trees with acid values of 20–35 mg KOH/g and softening points near 65–75°C. Demand concentrates in European coating manufacturers seeking REACH-compliant imports from FSC-certified Sumatran tapping collectives, though monsoon yield volatility forces inventory-heavy working capital models.
- Powdered Dammar:Micronized grades engineered for rapid dissolution kinetics in solvent systems. Ink formulators in Vietnam and Thailand adopt this grade for UV-curable overprint varnishes on high-speed flexographic lines, displacing lump resin where throughput speed governs equipment economics.
- Solid Dammar:Traditional lump form retains dominance in artisanal applications and small-batch coating operations where manual processing remains economically viable.
- Synthetic Dammar:Petroleum-derived alternatives offering batch-to-batch consistency for industrial buyers prioritizing specification uniformity over natural provenance claims.
Natural dammar commands the established base. The steepest expansion runs through powdered dammar.
Application:
End-use functional requirements dictate divergent purity, certification, and documentation standards across industrial and ingestible categories.
- Food Additives:Glazing and coating applications for confectionery, particularly hard-boiled candy and chocolate coatings. FSSAI in India accelerates approval timelines for plant-based alternatives, while clean-label reformulation compresses synthetic shellac volumes across Mumbai and Chennai processing facilities.
- Coatings:Varnish, lacquer, and protective film applications spanning wood finishing and industrial substrates. REACH compliance requirements in Europe now prioritize dammar over shellac derivatives, tightening acid value and softening point specifications for Rotterdam and Hamburg port entries.
- Ink:Overprint varnishes and flexographic formulations where gloss enhancement and adhesion promotion are critical. Vietnamese and Thai packaging converters drive specification evolution toward faster-curing, lower-VOC systems.
- Adhesives:Natural binder applications in specialty glue formulations where thermoplastic behavior and solvent solubility enable specific bonding architectures.
Coatings anchor volume demand. Food additives are climbing the fastest on margin expansion.
End User:
Customer type determines procurement scale, certification burden, and technical service intensity across the value chain.
- Chemical Industry:Industrial coating and adhesive manufacturers purchasing multi-ton quantities with standardized specifications. These buyers consolidate supplier panels and demand batch-level certificates of analysis, marginalizing traders without in-house testing infrastructure.
- Food Industry:Confectionery manufacturers and contract processors requiring food-grade certification, FSSAI or FDA compliance documentation, and deforestation-free supply chain verification. Procurement teams in Mumbai and Chennai now qualify suppliers 12-18 months ahead of seasonal Diwali and Eid production cycles.
- Art Supply Stores:Small-volume, high-SKU retail channels serving conservators and fine artists with specialized varnish and medium formulations.
- Pharmaceuticals:Enteric coating and tablet film-forming applications where alternatives to hypromellose-phthalate systems are under evaluation by European generics manufacturers.
Chemical industry buyers dominate procurement tonnage. Food industry qualification standards are tightening fastest.
Packaging Type:
Volume scale and handling economics segment packaging configurations from bulk industrial to precision retail formats.
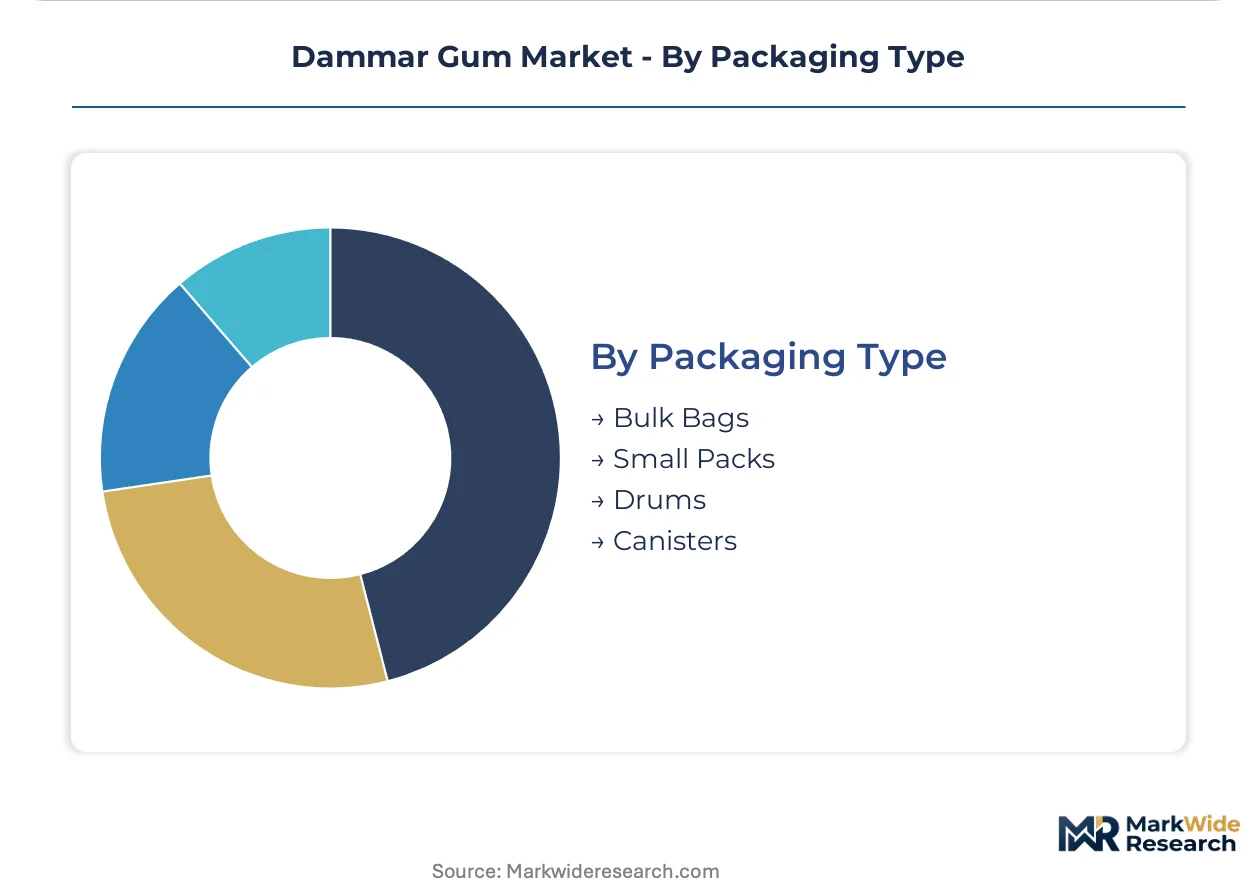
- Bulk Bags:Multi-hundred-kilogram flexible intermediate bulk containers serving coating manufacturers and adhesive compounders with integrated material handling systems. These configurations minimize per-kilogram packaging cost and align with just-in-time delivery contracts.
- Drums:Standard 200-liter steel or fiber containers for mid-scale chemical processors requiring manageable batch quantities and stackable warehouse storage. Drums dominate inter-island shipping from Sumatra to Java-based conversion facilities.
- Small Packs:Retail-scale quantities for art supply distribution and specialty chemical marketplaces in Mumbai and Jakarta, where direct-to-formulator digital platforms capture margin spreads on certified food-grade lots.
- Canisters:Airtight containers for moisture-sensitive powdered grades requiring extended shelf stability, particularly for pharmaceutical and high-specification coating applications.
Bulk bags and drums command industrial procurement. Small packs are expanding most quickly through digital marketplace channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's export quota allocation to FSC-certified tapping collectives is redrawing raw material eligibility across origin markets. European coating-grade importers now demand geolocation-verified harvest documentation. Indian and Southeast Asian formulators are consolidating supplier panels as clean-label confectionery reformulation accelerates.
Indonesia
Sumatran forest tapping operations supply the dominant share of natural resin volume. The Ministry of Environment and Forestry restricts export quotas to certified collectives, forcing Palembang and Jambi processors into 12-24 month compliance transitions. Integrated tapping-to-export operators in Sumatra capture premium positioning through captive laboratory capabilities.
India
FSSAI streamlines approval timelines for plant-based glazing agents in hard-boiled candy and chocolate coatings. Mumbai and Chennai confectioners now qualify dammar suppliers 12-18 months ahead of Diwali and Eid production cycles. Domestic procurement teams consolidate supplier panels from twelve to four qualified sources, demanding batch-level acid value certificates.
Germany
Hamburg anchors European distribution through deep inventory positions serving REACH-compliant coating-grade imports. ECHA SVHC screening expansion threatens coating-grade export eligibility for certain triterpenoid oxidation byproducts. German ink manufacturers specify CO2-extracted grades for food-contact packaging applications, compressing conventional processor margins.
Vietnam
Packaging converters in Ho Chi Minh City drive specification evolution toward faster-curing, lower-VOC overprint varnish systems. Vietnamese ink formulators adopt micronized powdered dammar for UV-curable flexographic lines, displacing slower-dissolving lump resin where throughput speed governs equipment economics.
Brazil
ANVISA's pending natural glazing agent framework creates first-mover positioning for Indonesian suppliers with pre-submitted technical dossiers. São Paulo-based confectionery manufacturers evaluate dammar trials as regulatory pathways for plant-based alternatives clarify. Brazilian procurement teams anticipate qualification cycles to align with 2026-2027 reformulation timelines.
Dammar Gum Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers: integrated forest-to-export operators with captive tapping networks, specialized purification houses with food-grade certification infrastructure, and regional trading houses with broker-dependent sourcing models. Strategic archetypes include vertically integrated Indonesian resin processors, European distribution specialists with inventory-heavy positioning, and toll-manufacturing intermediaries narrowing capital barriers for mid-sized entrants. Dominant competitive moves center on FSC chain-of-custody certification acquisition and supercritical CO2 extraction technology deployment to meet European food-contact specifications.
Among Indonesian integrated operators, PT Samiraschem Indonesia exemplifies the forest-to-export archetype with Sumatran tapping network control. Nexira Inc. occupies a position within the specialized purification tier, representing North American food-grade processing capabilities. Willy Benecke anchors European distribution positioning from its Hamburg base, exemplifying inventory-heavy regional specialization. These three players collectively illustrate how certification depth, extraction technology ownership, and geographic proximity to end-use markets stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| PT Samiraschem Indonesia |
| Cornelissen & Son |
| Nexira Inc. |
| Spectrum Chemical Manufacturing |
| William Bernstein Company |
| Willy Benecke |
| Bandish Enterprises |
| Starlight |
| Sennelier |
| Others |
Value Chain & Pricing Dynamics
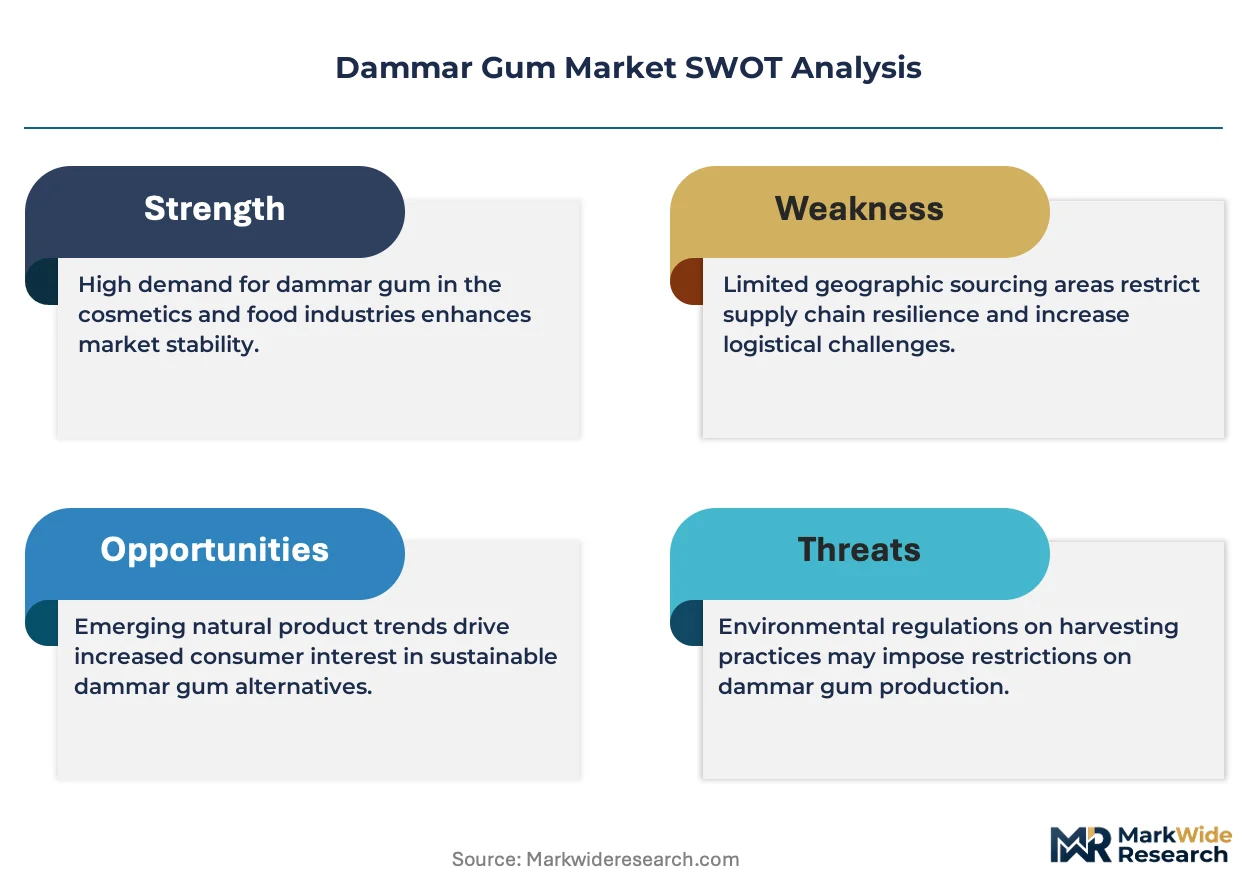
Undercapacity in Sumatran FSC-certified tapping collectives during extended wet seasons tightens raw material availability, forcing processors to absorb inventory carrying costs that transmit directly into food-grade premium structures while compressing margins on standard coating grades.
Pricing Analysis
Certification level creates the primary spread between food-grade and industrial coating grades, with FSSAI-compliant and REACH-registered lots commanding substantial premia over uncertified resin. Pricing stratifies across premium, standard, and economy tiers based on extraction technology ownership, with supercritical CO2-processed dammar positioned above conventional naphtha-extracted material. Cost compression in standard coating grades is intensifying because shellac from Bihar and Jharkhand undercuts dammar in gloss-sensitive applications below 90 GU at 60°. Chemical industry buyers purchasing multi-ton quantities exhibit lowest price sensitivity, while art supply retailers and small-batch confectioners face acute cost pressure.
Supply Chain Analysis
Tariff exposure between Indonesia and EU ports dominates supply chain risk calculus as ECHA SVHC screening expansion threatens coating-grade export eligibility. Raw material concentration rests on Sumatran forest tapping in Indonesia, with secondary processing clusters in Java and distribution hubs in Hamburg anchoring European supply. The chain draws from Dipterocarpaceae resin, stainless-steel solvent recovery equipment, and batch-level laboratory certification infrastructure. Single-source vulnerability runs through FSC-certified smallholder cooperatives facing 14-18 month compliance transitions. Distribution runs through integrated forest-to-export operators, specialized purification houses, and regional trading houses with broker-dependent sourcing models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dammar gum market presents a defensive-moat story anchored in regulatory entrenchment: REACH and FSSAI compliance timelines create 12-18 month qualification windows that lock out unqualified suppliers and reward incumbents with pre-certified operations.
For Market Incumbents: Insulate market position by deepening backward integration into FSC-certified Sumatran tapping networks and deploying supercritical CO2 extraction capacity to capture food-grade premia. Accelerate laboratory infrastructure investment to meet batch-level acid value and softening point documentation demands from consolidating Mumbai and Chennai confectionery procurement panels. Counter shellac price competition through technical service differentiation in high-gloss coating applications.
For New Entrants and Emerging Players: Pursue toll-manufacturing arrangements with underutilized Indonesian processors to bypass $2.4 million solvent recovery system capex requirements. Target Brazilian confectionery penetration ahead of ANVISA's natural glazing agent framework finalization, submitting technical dossiers to secure first-mover positioning. Leverage direct-to-formulator digital platforms in Mumbai and Jakarta to capture margin spreads on certified food-grade lots without traditional broker intermediation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated forest-to-export operators with captive tapping networks and in-house laboratory capabilities. Long-term viability across the analysis window favors acquisition targets with FSC chain-of-custody documentation and supercritical CO2 extraction assets positioned for European food-contact compliance. Monitor ECHA SVHC classification decisions on triterpenoid oxidation byproducts as the critical inflection signal for coating-grade export eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Tapping Networks | Captive Sumatran FSC-certified supply secures quota allocation under Ministry of Environment and Forestry regulations. |
| Supercritical CO2 Extraction Deployment | Eliminates residual aromatic hydrocarbons to meet REACH food-contact specifications for Milan and Barcelona ink manufacturers. |
| Laboratory Certification Infrastructure Investment | Batch-level acid value and softening point testing capability qualifies suppliers for consolidated four-source panels in India. |
| Direct-to-Formulator Digital Platform Launch | Bypasses traditional gum brokers in Mumbai and Jakarta to capture 8-12 point margin spreads on certified lots. |
| ANVISA Technical Dossier Pre-Submission | First-mover positioning in Brazilian confectionery ahead of natural glazing agent framework finalization. |
Study Parameters
Cross-validation between primary fieldwork with resin tappers, plant managers at Indonesian processing facilities, and procurement leads at Mumbai confectionery manufacturers anchors the qualitative findings, supplemented by secondary validation against Indonesian Ministry of Environment and Forestry export quota records, FSC chain-of-custody documentation databases, and ECHA REACH registration filings. Bottom-up triangulation across product grade, application vertical, and end-user segment integrates with top-down calibration against customs trade data and regional production estimates.
Calibration against historical volume trajectories and regulatory milestone timing refines the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, packaging format, and regional production hub. CAGRs were derived through growth driver decomposition and elasticity analysis against substitute material pricing. Industry-specific forecast inputs incorporate monsoon yield volatility patterns and FSSAI approval timeline acceleration effects.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by shellac processors or accelerated ECHA SVHC reclassification would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Superacids Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Dysprosium Acetate Market