
 Fabric Cutting Machines Market | 2026-2036
Fabric Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Cutting Machines Market Foresight
Skilled cutter-operator availability is rotating toward scarcity across major textile-producing regions, compelling factories to automate lay-up and cutting operations. Lectra leverages its software-hardware integration to sustain premium positioning in pattern-to-cut workflows. Gerber Technology anchors North American supply through extensive service networks and training infrastructure. Zünd Systemtechnik AG specializes in modular digital cutting platforms that extend from textiles into composite and technical material applications.
Fabric cutting machines are electromechanical systems that sever rolled or laid textiles using reciprocating blades, rotary tools, focused laser beams, or high-pressure waterjets, typically operating at feed rates between 0.5 and 2.5 meters per second depending on material stack height and blade configuration. Their primary purpose is converting bulk textile inputs into dimensionally precise pattern pieces for downstream sewing, welding, or bonding operations. CNC cutters dominate capital deployment in high-volume apparel factories where multi-ply cutting and nested pattern optimization compress unit labor content. Laser technology captures expanding share in technical textiles and industrial fabrics where sealed edges prevent fraying in synthetic fiber assemblies. Waterjet cutting occupies niche premium positioning for thick, layered, or heat-sensitive material stacks where thermal distortion would compromise dimensional tolerance.
CE marking under the EU Machinery Directive and ISO 11540 blade-guarding standards shape product design obligations for equipment sold into European textile operations. The US OSHA lockout-tagout provisions and NFPA 79 electrical safety standards add compliance layers for machines deployed in American cut-and-sew facilities. Stakeholders must monitor how evolving Ecodesign requirements and carbon-border adjustment mechanisms reshape total cost of ownership calculations for imported cutting equipment versus localized assembly alternatives.
Market Dynamics
Apparel factories in Vietnam and Bangladesh face acute skilled cutter-operator shortages that automation investments must offset, while CE marking and ISO blade-guarding mandates in Europe reshape equipment design obligations for OEMs serving export-oriented garment hubs.
Growth Catalysts
- ISO 11540 blade-guarding compliance:European textile operations upgrade legacy equipment to meet machinery safety standards, triggering replacement cycles in Germany, Italy, and Portugal.
- Reciprocating knife automation:High-volume apparel manufacturers deploy CNC multi-ply cutters to compress unit labor content in nested pattern workflows.
- Dhaka-Chittagong industrial corridor expansion:Bangladesh's export garment concentration drives capital deployment toward automated lay-up systems to offset workforce attrition.
Market Restraints
- Steel alloy price volatility:Blade and cutting tool input costs fluctuate with commodity markets, pressuring margins for mid-tier equipment suppliers.
- Technical limitation in natural fiber stacks:Laser cutting generates thermal degradation in cotton and wool assemblies above three-ply thickness, restricting application scope.
- OSHA lockout-tagout compliance:US cut-and-sew facilities face extended commissioning timelines and documentation burdens for imported electromechanical systems.
Strategic Opportunities
- Technical textile convergence:Composite manufacturers and automotive suppliers adopt modular digital cutting platforms for carbon fiber and aramid assemblies beyond traditional apparel.
- EU Ecodesign requirements:Energy efficiency mandates and carbon-border adjustment mechanisms favor localized equipment assembly over fully imported alternatives.
- Vietnam's export-oriented garment hubs:Underpenetrated mid-tier factories present retrofit potential as foreign direct investment flows into automated cutting floor expansions.
Industry Challenges
- CNC programming skill scarcity:Factories struggle to recruit operators capable of nested pattern optimization and machine calibration across multi-ply configurations.
- Legacy mechanical system integration:Electromechanical cutters must interface with existing spreading tables and material handling infrastructure without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Cutting Machines Market |
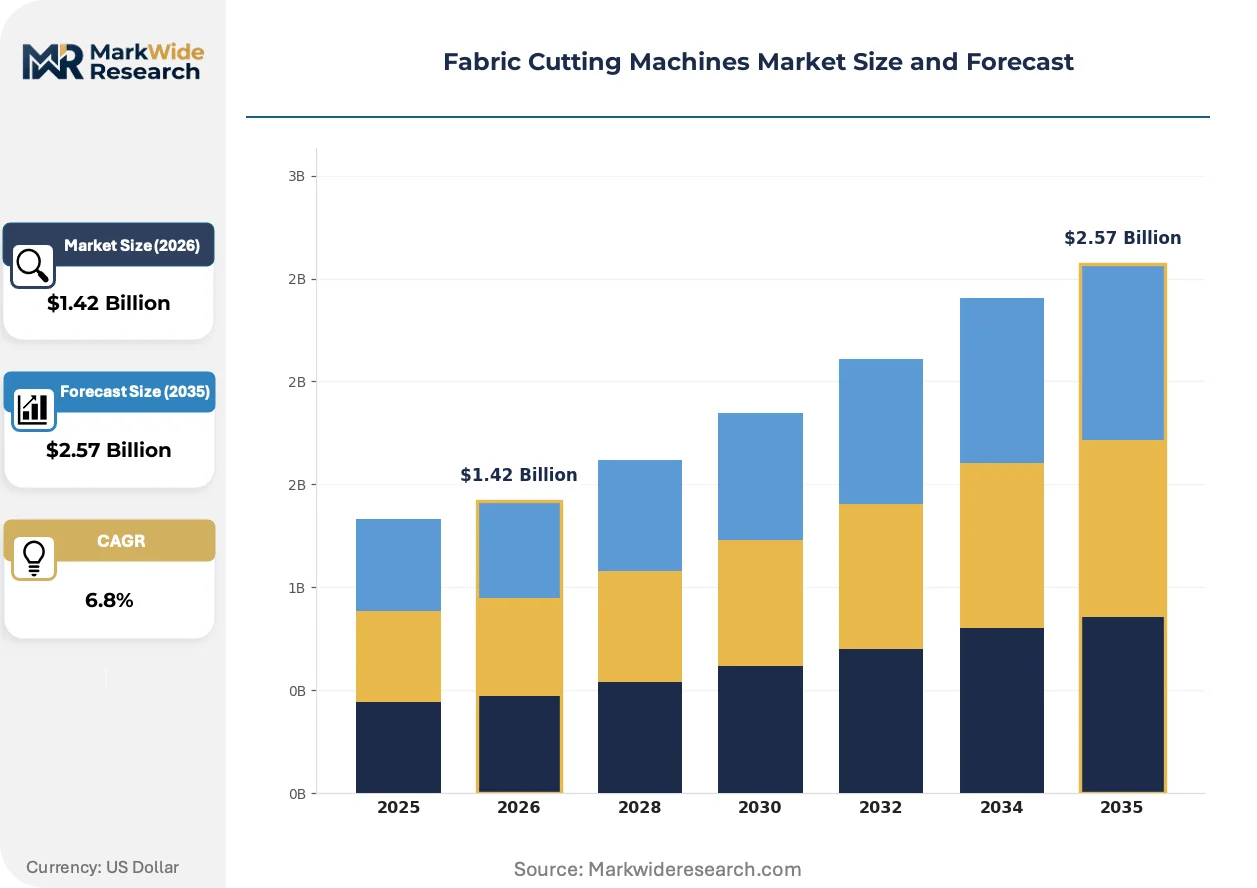
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutters, Electric Cutters, CNC Cutters, Laser Cutters Technology: Die Cutting, Laser Technology, Waterjet Cutting, Ultrasonic Cutting End User: Textile Manufacturers, Apparel Industry, Automotive Sector, Upholstery Services Application: Garments, Home Textiles, Industrial Fabrics, Decorative Fabrics |
| Companies Covered | Gerber Technology, Lectra, Eastman Machine Company, Zünd Systemtechnik AG, KURIS Spezialmaschinen GmbH, Mimaki Engineering Co., Ltd., SHIMA SEIKI, Bullmer GmbH, Investronica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Cutting Machines Market Shifts & Advancements
Laser cutting technology is displacing mechanical blade systems in synthetic fiber applications where sealed edges prevent fraying, while regulatory pressure on machinery safety and energy efficiency accelerates equipment refresh cycles across European and North American installed bases.
High-power CO2 and fiber laser systems are displacing reciprocating knife configurations in technical textile operations processing polyester, nylon, and aramid assemblies. Medical textile manufacturers and industrial fabric converters in Germany and Switzerland adopt these platforms at accelerated pace to achieve sealed-edge finishes without secondary overlocking. This displacement is compressing maintenance-intensive mechanical blade revenue streams while expanding service contract attach rates for optics and resonator replacement cycles.
CE marking under the EU Machinery Directive now requires documented risk assessments for blade exposure, emergency stop response times, and control system reliability. OEMs serving Italy, France, and Spain must certify control architectures through notified bodies, adding six to twelve months to product launch timelines. Premium equipment suppliers absorb these compliance costs into higher ASPs, while economy-tier competitors withdraw from European distribution to focus on Southeast Asian and Middle Eastern markets with less stringent conformity pathways.
Buyer procurement patterns favor outcome-based service agreements over discrete equipment purchases in North American automotive and aerospace textile operations. Tier-1 suppliers now contract for guaranteed cutting throughput and pattern accuracy rather than owning depreciating capital assets, transferring operational risk to OEM service organizations. This shift concentrates most visibly in Michigan, Ohio, and Ontario manufacturing corridors where just-in-time composite cutting supports vehicle assembly schedules.
Fabric Cutting Machines Market Segmentation
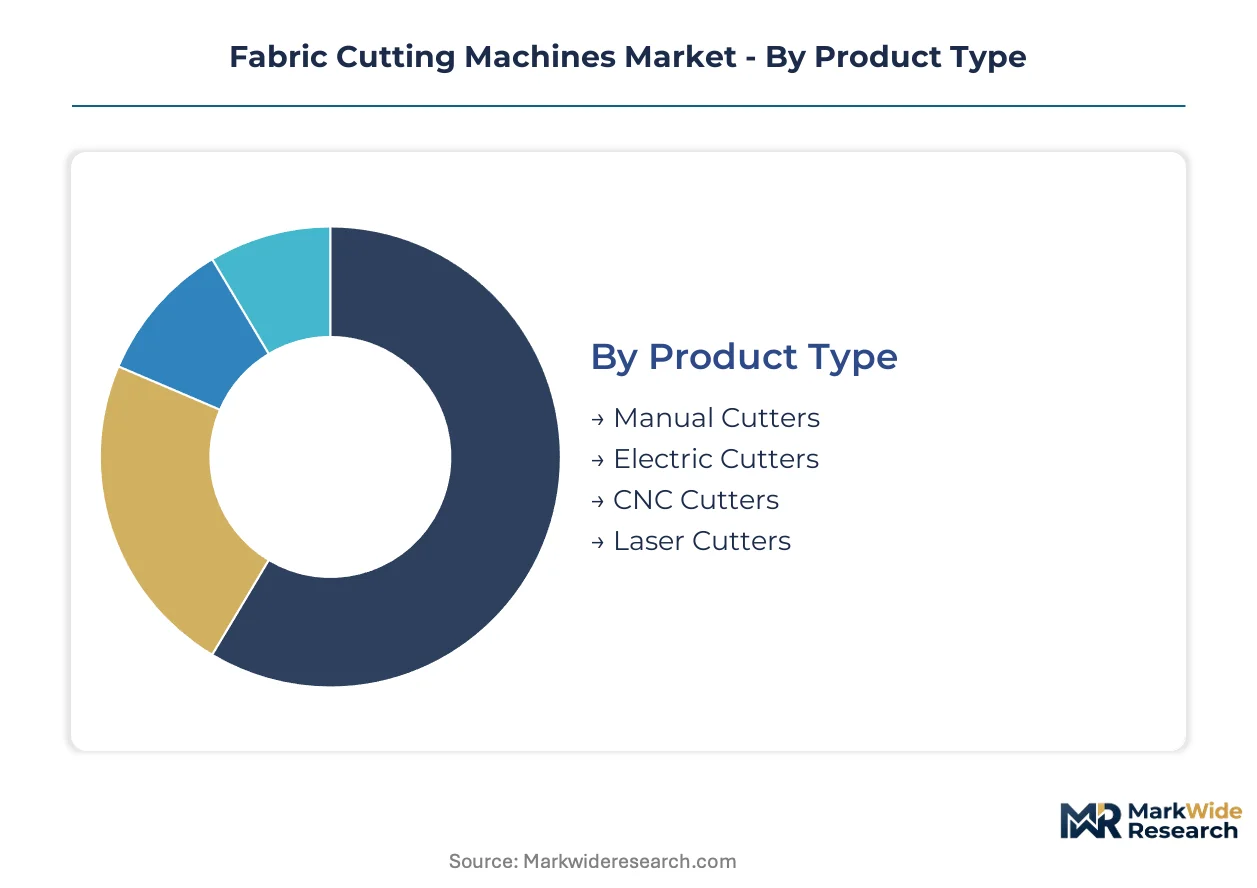
Fabric cutting machines serve divergent operational requirements across manual workshops and automated production floors. Segmentation reveals how technology tiers align with capital intensity, material complexity, and end-use precision demands in textile converting operations.
Product Type:
Equipment flows through distinct procurement channels—manual and electric units via industrial distributors and regional trading houses, CNC and laser platforms through direct OEM sales with bundled service contracts.
- CNC Cutters:Computer-numerical control systems execute multi-ply cutting with nested pattern optimization, reducing unit labor content in high-volume apparel factories across Vietnam's export-oriented garment hubs. Bangladesh's Dhaka-Chittagong corridor drives replacement demand as facilities automate to offset skilled operator attrition.
- Laser Cutters:Focused beam systems sever synthetic fiber assemblies with sealed edges that prevent fraying, displacing mechanical blades in technical textile operations. German and Swiss medical textile manufacturers adopt these platforms for polyester and aramid processing where thermal precision outweighs speed.
- Manual Cutters:Hand-operated shearing tools serve small-batch upholstery workshops and bespoke tailoring operations with minimal capital outlay.
- Electric Cutters:Motorized reciprocating blades bridge manual and automated workflows in mid-tier cut-and-sew facilities with moderate throughput requirements.
CNC cutters dominate installed base. Laser cutters are where expansion concentrates.
Technology:
Process selection hinges on material stack characteristics—thermal tolerance, thickness, and edge finish requirements—shaping capital deployment across natural and synthetic fiber applications.
- Laser Technology:CO2 and fiber laser systems achieve non-contact cutting with micron-level precision, capturing share in automotive airbag fabric and industrial filtration media where sealed edges eliminate secondary finishing. CE marking under the EU Machinery Directive mandates blade-guarding documentation and emergency stop certification for European deployments.
- Waterjet Cutting:High-pressure abrasive streams process thick, layered, or heat-sensitive stacks without thermal distortion, occupying premium positioning in carbon fiber composite and aramid assemblies for aerospace textile suppliers.
- Die Cutting:Steel-rule and rotary die configurations deliver high-speed blanking of uniform shapes in home textile and nonwoven applications with consistent material thickness.
- Ultrasonic Cutting:High-frequency vibration blades fuse synthetic fiber edges during severing, serving narrow fabric and ribbon manufacturers with fray-resistant finishes.
Laser technology leads synthetic fiber penetration. Waterjet cutting claims the steepest expansion trajectory in technical material stacks.
End User:
Customer type determines specification intensity—automotive and technical textile buyers prioritize precision certification, while apparel producers optimize for throughput and nested yield.
- Apparel Industry:Export garment manufacturers in Bangladesh and Vietnam deploy automated lay-up and cutting floors to compress labor costs in nested pattern workflows, with ISO 11540 compliance shaping European-bound production equipment selection.
- Automotive Sector:Tier-1 suppliers contract for guaranteed cutting throughput in composite and technical fabric assemblies, favoring outcome-based service agreements over capital ownership in Michigan, Ohio, and Ontario manufacturing corridors.
- Textile Manufacturers:Integrated mills processing bulk woven and knitted goods require versatile cutting platforms spanning sampling through bulk production.
- Upholstery Services:Custom furniture and marine interior specialists demand flexible short-run capability with rapid pattern changeover.
Apparel industry holds largest equipment population. Automotive sector is where service contract innovation concentrates.
Application:
End-use differentiation drives blade configuration, stack height tolerance, and edge finish specifications across consumer and industrial textile segments.
- Industrial Fabrics:Technical textiles for filtration, geotextiles, and protective equipment demand precision cutting of synthetic fiber assemblies with sealed or reinforced edges, with OSHA lockout-tagout provisions extending commissioning timelines for US-based converters.
- Garments:High-volume apparel production prioritizes multi-ply throughput and pattern nesting efficiency, with Bangladesh and Vietnam factories automating to offset skilled cutter-operator scarcity.
- Home Textiles:Bedding, curtain, and towel manufacturers balance batch size flexibility with cutting accuracy across natural fiber stacks.
- Decorative Fabrics:Narrow fabric, embroidery, and specialty textile converters require intricate contour cutting with minimal material waste.
Garments segment anchors volume demand. Industrial fabrics is where technology upgrading concentrates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese apparel factories deploy automated cutting floors for multi-ply throughput, while German technical textile producers prioritize laser precision for sealed-edge synthetic processing. Bangladesh concentrates export-garment automation in the Dhaka-Chittagong corridor. Italian machinery OEMs navigate CE marking and ISO blade-guarding mandates. US automotive textile suppliers contract for outcome-based cutting throughput.
Vietnam
Export-oriented garment hubs in Ho Chi Minh City and Hanoi drive capital deployment toward CNC multi-ply cutters. Factories automate lay-up operations to offset skilled cutter-operator attrition. Foreign direct investment flows into Binh Duong and Dong Nai industrial zones for automated cutting floor expansions.
Germany
Medical textile manufacturers in Baden-Württemberg adopt laser platforms for polyester and aramid sealed-edge finishing. CE marking under the EU Machinery Directive mandates documented risk assessments for blade exposure and emergency stop certification. Stuttgart and Reutlingen clusters concentrate technical textile precision cutting operations.
Bangladesh
The Dhaka-Chittagong industrial corridor anchors export-garment production requiring automated pattern-to-cut workflows. Factory owners deploy nested optimization software to compress unit labor content. Gazipur and Narayanganj sub-districts concentrate capital investment in electromechanical cutting infrastructure.
Italy
Prato and Biella textile districts upgrade legacy equipment to meet ISO 11540 blade-guarding standards. OEMs serving European markets certify control architectures through notified bodies, extending product launch timelines. Premium equipment suppliers absorb compliance costs into higher average selling prices.
United States
Tier-1 automotive textile suppliers in Michigan and Ohio contract for guaranteed cutting throughput rather than owning depreciating capital assets. OSHA lockout-tagout provisions extend commissioning timelines for imported electromechanical systems. Detroit and Toledo manufacturing corridors concentrate just-in-time composite cutting for vehicle assembly schedules.
Fabric Cutting Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the fabric cutting machines market. Premium-tier vendors bundle software-hardware integration with outcome-based service agreements, while mid-tier competitors compete on equipment pricing and regional service proximity. Two strategic archetypes dominate: pattern-to-cut workflow integrators and modular digital cutting platform specialists. Competitive moves concentrate on geographic expansion into underpenetrated Southeast Asian garment hubs and portfolio diversification from apparel into technical textiles and composite materials.
Within the integrated workflow tier, Lectra and Gerber Technology exemplify pattern-to-cut solution anchoring. Zünd Systemtechnik AG occupies a position among modular digital cutting specialists extending platform applicability beyond traditional textiles. KURIS Spezialmaschinen GmbH represents German precision engineering archetype in specialized cutting machinery. These named entities illustrate how competitive positioning stratifies across software-integrated versus hardware-focused strategic vectors.
| Leading Market Players |
|---|
| Gerber Technology |
| Lectra |
| Eastman Machine Company |
| Zünd Systemtechnik AG |
| KURIS Spezialmaschinen GmbH |
| Mimaki Engineering Co., Ltd. |
| SHIMA SEIKI |
| Bullmer GmbH |
| Investronica |
| Others |
Supply & Pricing Matrix
Long-term service contracts with bundled maintenance and throughput guarantees anchor pricing visibility for CNC and laser cutting platforms, locking in multi-year revenue streams for OEMs while insulating apparel manufacturers in Vietnam and Bangladesh from volatile blade and optics replacement costs. This contract-structure pattern concentrates among Tier-1 automotive textile suppliers in Michigan and Ohio, where outcome-based agreements transfer operational risk from capital owners to equipment vendors.
Pricing Analysis
Project-based equipment sales with attached service contracts dominate capital deployment, though subscription-tiered software licensing for nested pattern optimization is displacing perpetual licenses in high-volume garment hubs. Price differentiation rests on CE marking certification grade and after-sales service bundling, with ISO 11540-compliant systems commanding substantial premiums over uncertified alternatives in European markets. Cost compression in mid-tier electric cutters is intensifying because steel alloy input volatility erodes margins for regional assemblers. Small-batch upholstery workshops exhibit highest price sensitivity, while medical textile manufacturers in Germany and Switzerland demonstrate lowest sensitivity due to precision requirements.
Supply Chain Analysis
Inventory buffers for high-precision cutting blades and laser resonator components extend lead times for European and North American deployments, compressing delivery windows for Southeast Asian garment hub expansions. Manufacturing concentration centers on Germany, Italy, and China for control systems and precision mechanics, with Taiwan and Japan anchoring laser optics and motion control electronics. Raw material dependencies draw from specialty steel alloys, rare-earth optical components, and high-grade aluminum castings. Single-source vulnerability in CO2 laser tube supply creates structural risk for technical textile converters. Distribution runs through direct OEM sales for CNC and laser platforms, while manual and electric units flow via industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-hardware integration is reshaping competitive positioning as pattern-to-cut workflow ecosystems lock in customer switching costs, with interoperability between nesting optimization and machine control emerging as the decisive platform battleground.
For Market Incumbents: Consolidate service infrastructure density in Vietnam's Binh Duong and Dong Nai industrial zones to capture retrofit demand from mid-tier garment factories automating lay-up operations. Deepen backward integration into precision blade manufacturing to offset steel alloy price volatility eroding mid-tier margins. CE marking certification investment represents the priority defensive lever against economy-tier competitors withdrawing from European distribution. For New Entrants and Emerging Players: Post-sale training and CNC programming skill development present a service-layer gap where incumbents under-serve, creating entry opportunity for specialized education providers. Vietnam's underpenetrated mid-tier factories offer the most penetrable geography, with foreign direct investment flows enabling greenfield automation deployments. A software-first go-to-market angle—selling nested pattern optimization as standalone SaaS before equipment attachment—sidesteps capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Modular digital cutting platform specialists with composite material expertise beyond traditional textiles represent the acquisition target archetype with strongest strategic optionality. Long-term viability hinges on diversification from apparel cyclicality into automotive and aerospace technical textiles. Watch for inflection signals in outcome-based service contract attach rates at Tier-1 automotive suppliers, as this metric indicates ecosystem lock-in maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Integration | Lectra and Gerber Technology leverage pattern-to-cut workflow bundling to sustain premium positioning against modular competitors. |
| CE Marking Certification Investment | OEMs serving Italy, France, and Spain absorb six-to-twelve-month launch timeline extensions into higher average selling prices. |
| Outcome-Based Service Agreements | Tier-1 automotive textile suppliers in Michigan and Ohio transfer operational risk from capital ownership to OEM service organizations. |
| Technical Textile Diversification | Carbon fiber and aramid cutting capability extends platform applicability beyond apparel into automotive and aerospace supply chains. |
| Southeast Asian Service Infrastructure | Binh Duong and Dong Nai industrial zones in Vietnam concentrate foreign direct investment for automated cutting floor expansions. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and textile manufacturing directors anchors the qualitative findings, with secondary validation drawing from customs and trade data, SEC filings of listed machinery OEMs, ISO certification registries, and EU Machinery Directive notification databases. Bottom-up equipment shipment analysis triangulates against top-down market sizing from regional industrial production indices.
Sensitivity analysis across blade configuration, stack height tolerance, and edge finish specifications informs the analytical framework over the projection horizon. Segmentation dimensions span product type, technology, end user, and application, with regional regulatory cluster and certification tier adding industry-specific granularity. CAGRs derive from installed base evolution and replacement cycle modeling, with labor cost compression targets in Bangladesh and Vietnam informing demand elasticity assumptions.
Underlying assumptions cover skilled operator attrition rates, steel alloy price corridors, and CE marking compliance timelines, with deviation risk concentrated in tariff exposure for European-bound equipment and carbon-border adjustment mechanism implementation pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Embroidery Machine Market