

3D Knitting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
3D Knitting Machines Market Insights
Equipment leasing and subscription-based access models is rewriting competitive entry barriers for mid-scale textile producers. Shima Seiki leverages its integrated design-to-production software stack to dominate premium flat knitting configurations. Karl Mayer anchors warp knitting specialization for technical textiles and industrial fabric applications. Santoni competes through circular knitting scale advantages in seamless sportswear manufacturing.
3D knitting machines execute multi-directional yarn manipulation to produce complex three-dimensional textile structures without cutting or sewing operations, typically operating at gauge ranges from 3 to 18 needles per inch depending on end-product density requirements. These systems serve industrial purposes spanning functional sportswear, medical compression garments, and engineered technical textiles where seam elimination improves structural integrity and wearer comfort. Flat knitting machines occupy the largest installed base across fashion apparel and home furnishing segments where pattern versatility commands premium positioning. Technical textiles represents the fastest-expanding application dimension as aerospace, automotive, and healthcare buyers specify load-bearing and biocompatible knitted structures. Computerized control technology leads R&D allocation among manufacturers modernizing legacy mechanical systems with digital pattern libraries and real-time tension monitoring.
EMA medical device regulations and EU Green Deal textile sustainability frameworks shape product certification requirements for European market access, while GB standards administered by China's SAMR govern electromagnetic compatibility and operational safety for imported knitting equipment. OSHA machine guarding standards in the United States and Japan's METI industrial automation guidelines further fragment compliance obligations across major procurement geographies. Stakeholders must monitor evolving extended producer responsibility mandates and digital product passport requirements that will determine which machine architectures qualify for future public and private sector tenders.
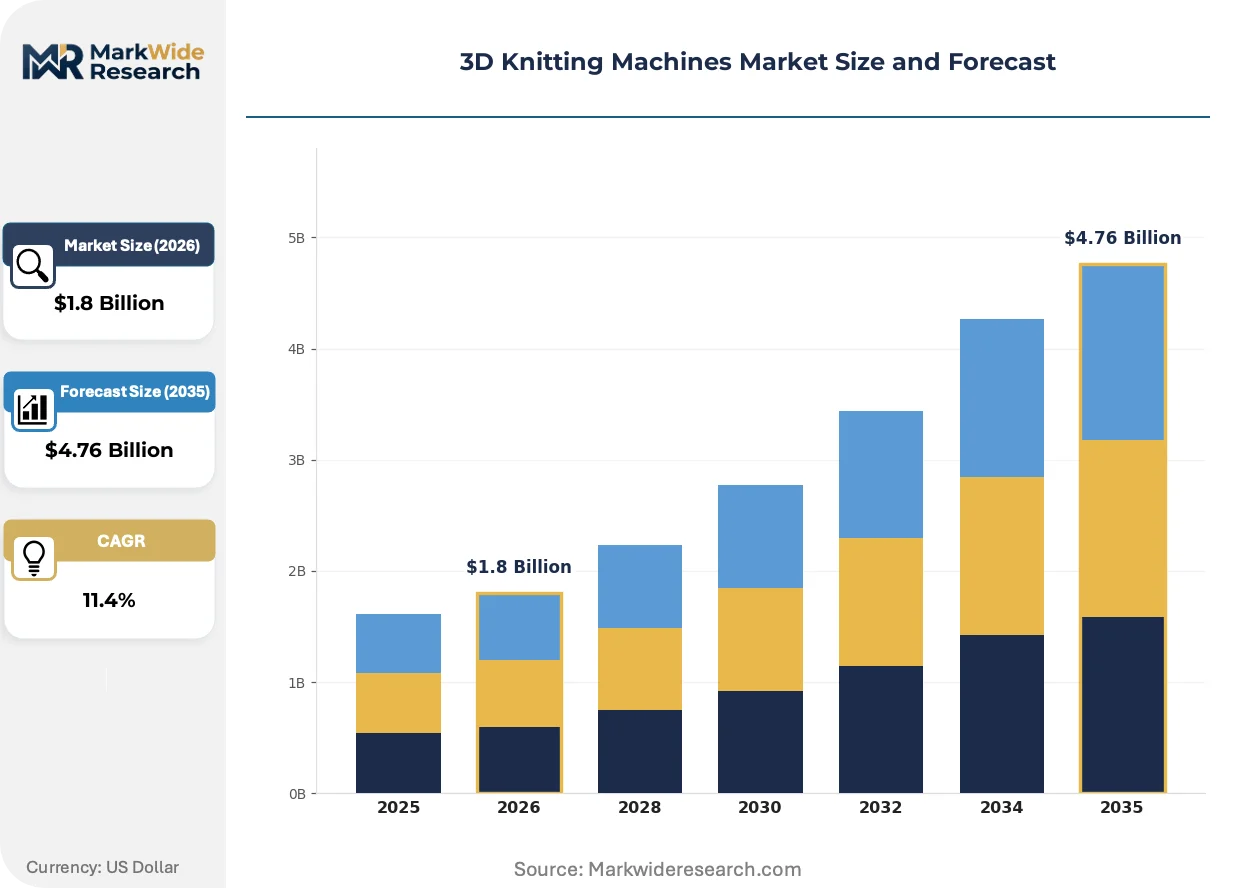
Market Dynamics
Seamless garment production requirements from sportswear brands are compressing traditional cut-and-sew supply chains while forcing capital redeployment toward whole-garment knitting architectures.
Growth Catalysts
- EU Green Deal textile sustainability frameworks:Extended producer responsibility mandates in Europe are accelerating machine replacements as brands seek seam-free construction to minimize post-consumer waste streams.
- Medical compression garment demand:Healthcare systems specify biocompatible knitted structures for patient recovery applications, pulling specialized 3D knitting capacity into pharmaceutical supply chains.
- Technical textile clusters in China, Germany, and Japan:Concentrated aerospace and automotive engineering ecosystems anchor procurement decisions for load-bearing knitted components.
Market Restraints
- High-performance yarn input volatility:Technical filament supply concentrates among specialty chemical producers, exposing machine operators to feedstock cost swings.
- GB electromagnetic compatibility certification:China's SAMR-administered standards create friction for European and Japanese equipment imports, extending deployment timelines.
- Mechanical knitting substitution:Woven technical textiles retain cost advantages in heavy-load industrial applications, capping addressable market expansion.
Strategic Opportunities
- Equipment leasing and subscription access models:Mid-scale textile producers in India and Vietnam bypass capital barriers through usage-based machine procurement.
- Real-time tension monitoring convergence:Integration of computerized control systems with IoT sensor networks enables predictive maintenance revenue streams.
- Digital product passport requirements:EU traceability mandates create competitive differentiation for machine architectures that embed production metadata directly into garment specifications.
Industry Challenges
- Computerized pattern programming expertise:Shortage of operators fluent in design-to-production software stacks constrains utilization rates of installed whole-garment systems.
- Legacy mechanical system integration:Digital pattern libraries face compatibility friction with existing factory floor layouts, requiring custom middleware development.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Knitting Machines Market Trends and Innovations
Active migration from mechanical to digital control architectures is redefining competitive moats, with software-integrated platforms capturing premium positioning across fashion and technical textile segments.
Whole-garment knitting technology is migrating from fashion-centric flat configurations toward multi-needle industrial systems. Aerospace and automotive buyers specify complex three-dimensional structures for structural reinforcement panels. Technical textile producers in Germany and Japan are migrating from cut-and-sew subcontracting networks toward captive seamless production to protect intellectual property.
REACH chemical safety regulations administered by ECHA are tightening material certification requirements for yarn inputs used in medical and infant garment applications. Equipment manufacturers must now validate needle coatings and lubricant formulations against Substance of Very High Concern lists. Italian and Portuguese sportswear suppliers are restructuring supplier qualification protocols to preempt compliance disruptions.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Mid-scale producers in China's Zhejiang and Guangdong provinces now procure maintenance and spare parts through independent technical service networks rather than original manufacturer contracts. This pattern compresses vendor switching costs and accelerates second-hand machine market liquidity.
3D Knitting Machines Market Segmentation
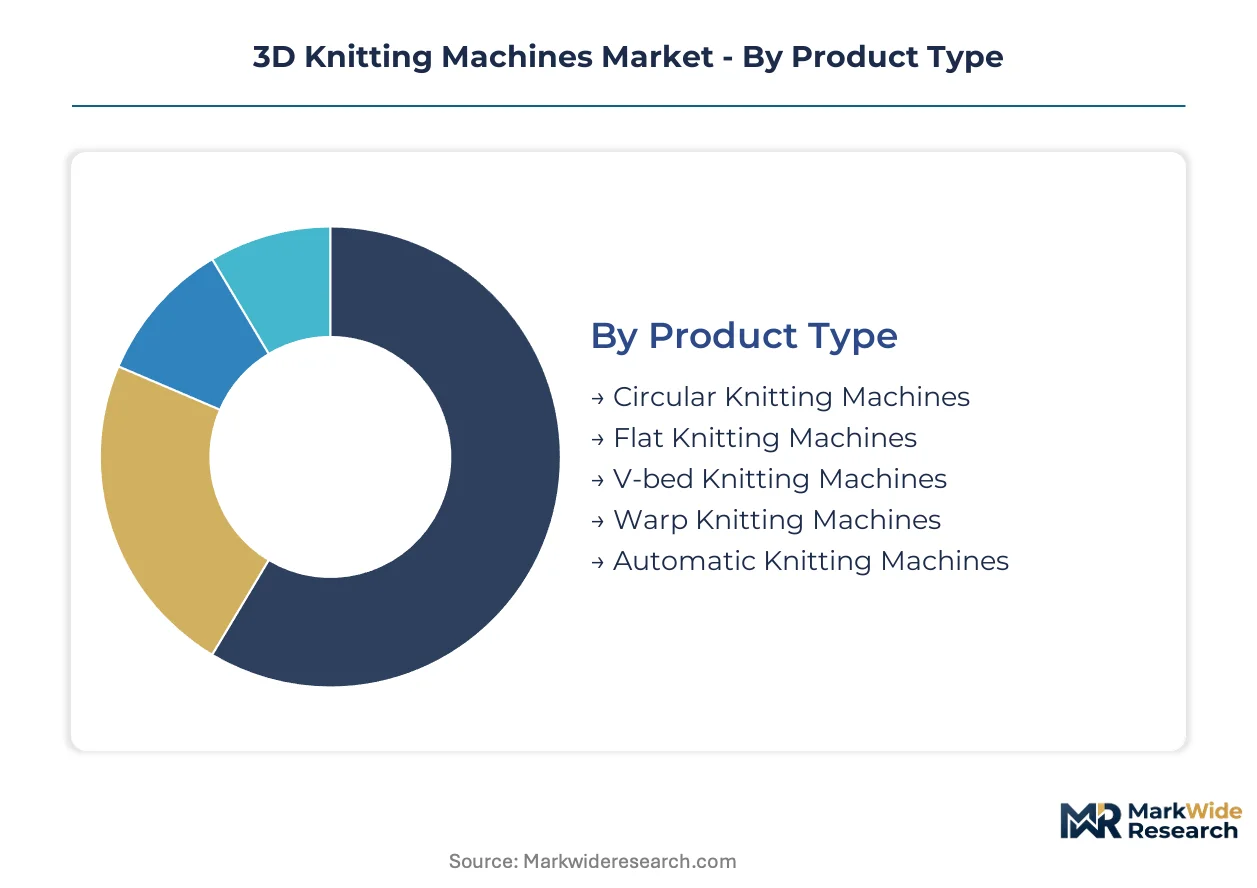
Segmentation in 3D knitting machines reveals how after-sales service intensity varies dramatically across machine architectures, with flat and circular systems demanding specialized technical support networks while warp configurations require minimal field intervention. Understanding these service-to-hardware ratios shapes procurement financing structures and vendor selection criteria for textile producers.
Product Type:
After-sales service intensity diverges sharply across knitting architectures, with multi-needle systems requiring frequent needle bed calibration and electronic component replacement compared to mechanically simpler configurations.
- Flat Knitting Machines:V-bed configurations with individual needle selection enable complex patterning for whole-garment production. Demand concentrates in Italian and Portuguese sportswear clusters where seamless construction eliminates post-knitting labor. Extended producer responsibility mandates under EU Green Deal frameworks accelerate replacement cycles as brands seek waste-minimizing production.
- Circular Knitting Machines:Cylindrical needle beds rotate continuously to produce seamless tubular fabrics at high speeds. Technical fabric suppliers in China's Zhejiang province deploy these systems for medical compression garments requiring consistent circumferential elasticity. Biocompatible certification requirements under EMA medical device regulations elevate service contract premiums.
- V-bed Knitting Machines:Dual needle beds enable rib and purl structures through automated transfer mechanisms.
- Warp Knitting Machines:Parallel yarn feeding produces stable technical textiles for automotive and aerospace reinforcement panels.
- Automatic Knitting Machines:Integrated yarn handling and quality detection reduce operator intervention requirements.
By volume, circular knitting machines lead installed base counts across sportswear supply chains. By growth pace, flat knitting configurations are ahead as whole-garment architectures displace cut-and-sew networks.
Technology:
Cost tier stratification separates premium digital control platforms from mechanically governed entry-level systems, with software licensing fees becoming the dominant lifetime cost component rather than hardware depreciation.
- Computerized Control:Digital pattern libraries and real-time stitch monitoring enable rapid design iteration. Fashion apparel producers in Germany's technical textile clusters prioritize these systems for intellectual property protection through captive production. GB electromagnetic compatibility certification administered by SAMR creates friction for European equipment imports.
- Fully Automated Systems:Robotic yarn loading and automatic fault correction minimize labor input requirements. Medical textile manufacturers in Japan specify these configurations for pharmaceutical-grade compression garment production under METI automation guidelines. Predictive maintenance revenue streams emerge from IoT-enabled tension monitoring convergence.
- Electronic Yarn Feeding:Servo-controlled tension management reduces material waste during high-speed operation.
- Touchscreen Interface:Intuitive programming lowers operator training barriers for mid-scale producers.
- 4D Knitting:Multi-directional yarn manipulation produces complex three-dimensional structures without cutting or sewing.
Computerized control platforms command the highest average selling prices. Fully automated systems are climbing the fastest as labor cost arbitrage erodes in traditional manufacturing geographies.
Application:
Customer type fragmentation separates volume-driven commodity producers from specification-heavy technical buyers, with divergent procurement rhythms and financing preferences across the demand base.
- Technical Textiles:Load-bearing knitted structures for aerospace and automotive applications require gauge precision and material traceability. German engineering ecosystems anchor procurement for structural reinforcement panels. REACH compliance administered by ECHA tightens needle coating and lubricant certification against Substance of Very High Concern lists.
- Sportswear Manufacturing:Seamless garment production compresses traditional cut-and-sew supply chains through whole-garment knitting. Nike and Adidas supplier networks in Vietnam and Indonesia drive deployment of flat knitting architectures. Equipment leasing models bypass capital barriers for mid-scale producers.
- Home Furnishings:Pattern versatility commands premium positioning in upholstery and decorative textile segments.
- Fashion Apparel:Rapid style turnover demands quick pattern changeover capabilities and digital design integration.
- Medical Textiles:Biocompatible knitted structures for patient recovery applications pull specialized capacity into pharmaceutical supply chains.
Sportswear manufacturing maintains the largest revenue share. Technical textiles are gaining share fastest as aerospace and automotive specifications proliferate.
End User:
Supply concentration among technical fabric suppliers in China, Germany, and Japan determines regional equipment procurement patterns, with cluster proximity to engineering ecosystems influencing vendor selection.
- Technical Fabric Suppliers:Aerospace and automotive buyers specify complex three-dimensional structures for structural reinforcement. Japanese producers migrate from cut-and-sew subcontracting toward captive seamless production. Digital product passport requirements under EU traceability mandates create competitive differentiation for metadata-embedded architectures.
- Textile Manufacturers:Integrated spinning-to-garment operations optimize yarn-to-finished-product margins through vertical control. India's PLI scheme incentives accelerate domestic machine procurement for technical textile capacity expansion. Independent technical service networks in China's Guangdong province fragment traditional vendor relationships.
- Ready-made Garment Producers:Contract manufacturers serving international brands prioritize throughput and labor efficiency.
- Design Studios:Small-batch production and rapid prototyping capabilities support premium fashion positioning.
By installed base, textile manufacturers lead. By expansion trajectory, technical fabric suppliers are ahead as captive production displaces outsourced knitting networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives for technical textiles are accelerating domestic machine procurement as manufacturers expand captive knitting capacity. Germany's engineering ecosystems anchor demand for load-bearing structural components in aerospace supply chains. China's Zhejiang and Guangdong provinces concentrate independent technical service networks that fragment traditional vendor relationships.
China
Technical textile clusters in Zhejiang and Guangdong provinces drive equipment procurement for seamless sportswear and medical compression garments. GB electromagnetic compatibility certification administered by SAMR creates friction for European and Japanese equipment imports, extending deployment timelines. Suzhou and Hangzhou industrial zones host the country's densest concentrations of circular knitting capacity serving pharmaceutical-grade applications.
Germany
Aerospace and automotive engineering ecosystems specify complex three-dimensional knitted structures for structural reinforcement panels. REACH compliance administered by ECHA tightens needle coating and lubricant certification against Substance of Very High Concern lists. The Stuttgart and Munich metropolitan regions concentrate technical textile R&D facilities migrating from cut-and-sew subcontracting toward captive seamless production.
Japan
Medical textile manufacturers specify fully automated configurations for pharmaceutical-grade compression garment production. METI industrial automation guidelines govern operational safety requirements for imported knitting equipment. The Nagoya and Osaka industrial corridors anchor procurement decisions for biocompatible knitted structures in patient recovery applications.
United States
Sportswear brands headquartered in the Pacific Northwest and Southeast compress traditional cut-and-sew supply chains through whole-garment knitting deployment. OSHA machine guarding standards fragment compliance obligations alongside state-level environmental regulations. The Carolinas textile corridor and Los Angeles apparel basin concentrate mid-scale producers exploring equipment leasing models.
India
Technical textile capacity expansion accelerates under PLI scheme incentives targeting domestic machine procurement for aerospace and automotive components. BIS certification requirements for imported industrial equipment create qualification friction for European vendors. The Tiruppur knitwear cluster and Surat technical textile zone anchor regional demand for flat and circular knitting architectures.
3D Knitting Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where software-integrated platforms capture premium positioning. The vendor base separates into three strategic archetypes: design-to-production software integrators, warp knitting specialists for technical textiles, and circular knitting scale operators in seamless sportswear. Consolidation pressure intensifies as computerized control technology absorbs R&D allocation and predictive maintenance revenue streams emerge from IoT-enabled systems. Geographic expansion through independent technical service networks and strategic partnerships with mid-scale producers in Vietnam and Indonesia represent dominant competitive moves.
Within the software-integrated tier, Shima Seiki and Stoll exemplify archetypes competing through design-to-production platform control. Karl Mayer anchors warp knitting specialization for technical textile and industrial fabric applications. Santoni occupies a position within circular knitting scale advantages for seamless sportswear manufacturing. These named entities represent competitive positioning patterns rather than specific strategic actions, with each exemplifying how geographic origin and corporate structure correlate with segment focus in this machinery category.
| Leading Market Players |
|---|
| Shima Seiki |
| Stoll |
| Karl Mayer |
| Santoni |
| Brother Industries |
| Mayer & Cie |
| Steiger |
| Groz-Beckert |
| Fukuhara Industrial & Trading |
| Others |
Pricing and Supply Chain Analysis
GB electromagnetic compatibility certification administered by SAMR functions as a regulatory chokepoint that widens pricing tier spreads between certified and non-certified equipment while compressing supply chain options toward domestic Chinese manufacturers and pre-qualified Japanese vendors.
Pricing Analysis
Certification grade—spanning CE marking for European market access, METI compliance for Japanese pharmaceutical applications, and BIS clearance for Indian technical textile procurement—creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects software licensing depth, after-sales bundling intensity, and real-time tension monitoring capabilities. Cost compression in economy-tier flat knitting configurations is intensifying because independent technical service networks in Guangdong province fragment traditional vendor maintenance revenue. Mid-scale textile producers in Vietnam and Indonesia exhibit highest price sensitivity, while aerospace technical fabric suppliers in Germany and Japan prioritize certification reliability over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 180 days offered by equipment financers in China and India are restructuring procurement liquidity for mid-scale producers, drawing machine deployment decisions toward leasing-specialist intermediaries. Supply concentration rests on precision needle bed manufacturing in Germany, computerized control system assembly in Japan, and high-speed circular knitting frame production in China. Critical dependencies include specialty alloy needle components, servo-controlled yarn feeding mechanisms, and biocompatible lubricant formulations. Single-source vulnerability concentrates in specialty chemical producers supplying technical filaments for medical compression applications. Distribution runs through direct OEM relationships for premium whole-garment systems, while independent technical service networks dominate spare parts and maintenance for installed circular knitting bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seamless sportswear specifications from Nike and Adidas supplier networks are fragmenting demand across machine architectures, creating specialization niches that reward focused technical competency over broad portfolio coverage.
For Market Incumbents: Insulate installed base relationships through predictive maintenance revenue streams enabled by IoT-enabled tension monitoring convergence, while deepening backward integration into design-to-production software stacks to lock out modular competitors. The threat of equipment leasing platforms eroding upfront hardware margins demands channel control through captive financing subsidiaries in India and Vietnam. For New Entrants and Emerging Players: India's technical textile zones—particularly Surat and Tiruppur—offer underpenetrated demand for mid-gauge flat knitting systems serving domestic aerospace component suppliers. Medical compression garment producers in Nagoya and Osaka present a second white-space target, as incumbent vendors prioritize fashion-centric configurations. A subscription-based machine access model bypasses capital barriers that constrain mid-scale textile manufacturers. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors software-integrated platform owners over mechanically governed legacy operators. Long-term viability across the analysis window hinges on digital pattern library depth and real-time production metadata capabilities. Acquisition targets should demonstrate embedded EU traceability compliance for digital product passport requirements. The signal to watch is accelerated replacement cycles triggered by extended producer responsibility mandates under EU Green Deal frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Design Software | Shima Seiki's captive control over pattern-to-production workflows locks in premium positioning against modular competitors. |
| Equipment Leasing Platform Launch | Mid-scale producers in Vietnam bypass capital barriers through usage-based procurement, fragmenting traditional vendor relationships. |
| Predictive Maintenance Service Unbundling | IoT-enabled tension monitoring convergence creates recurring revenue streams independent of hardware replacement cycles. |
| EU Green Deal Compliance Certification | REACH-administered needle coating validation against Substance of Very High Concern lists qualifies machines for public sector tenders. |
| Technical Textile Cluster Partnership | Proximity to Stuttgart and Munich engineering ecosystems anchors procurement decisions for aerospace structural reinforcement panels. |
Research Methodology
The analysis maps flat knitting, circular knitting, warp knitting, and V-bed machine architectures, each validated through equipment procurement directors at technical textile manufacturers, aftermarket service heads at independent technical networks, plant engineers at sportswear contract manufacturers, and regulatory affairs leads at medical device textile suppliers. Primary interviews combined with secondary validation against SAMR GB standard filings, ECHA REACH substance registrations, METI industrial automation guidelines, and SEC equipment vendor disclosures. Bottom-up installed base enumeration triangulated against top-down market sizing derived from trade flow analysis.
Forecast assumptions held macroeconomic conditions, regulatory enforcement intensity, and yarn input cost volatility within observed historical bands across the modeling period. Segmentation dimensions modeled include machine architecture type, control technology tier, end-use application intensity, and geographic certification cluster. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements, and leasing platform penetration trajectories. Industry-specific inputs incorporated pharmaceutical-grade compression garment demand curves and aerospace structural panel specification proliferation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers leveraging GB certification friction to capture import-substitution share would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.