
 TWS and Noise-Cancelling Headphone with MEMS Chip Market | 2026-2036
TWS and Noise-Cancelling Headphone with MEMS Chip Market Size, Share, and Industry Trends Forecast 2026-2036
TWS and Noise-Cancelling Headphone with MEMS Chip Market Insights
Silicon is repositioning traditional electret condenser materials across premium headphone architectures. Knowles leverages MEMS microphone integration to sustain its component leadership in noise-cancelling arrays. Apple anchors consumer expectations through proprietary chip-to-acoustic system control. Goertek dominates contract manufacturing scale for TWS assembly, supplying multiple branded OEMs from its Dongguan facilities.
TWS and noise-cancelling headphones with MEMS chips integrate microelectromechanical microphone transducers with active noise cancellation algorithms and Bluetooth audio codecs to deliver spatial audio and voice pickup in compact wireless form factors. MEMS microphones typically measure 3.76 mm by 2.95 mm with signal-to-noise ratios exceeding 64 dB, enabling beamforming arrays that filter ambient sound for clear voice transmission in commercial and professional environments. TWS headphones lead volume shipments while over-ear configurations command the highest average selling prices and margin pools in professional audio segments. Active noise cancellation technology differentiates premium tiers, whereas Bluetooth connectivity standardization commoditizes entry-level positioning across consumer electronics channels.
The FCC enforces hearing aid compatibility and RF exposure limits for wireless audio devices sold in the United States, while the EU Radio Equipment Directive mandates CE marking for electromagnetic compatibility and spectrum efficiency across member states. China's MIIT certifies radio transmission parameters for Bluetooth products manufactured domestically or imported for commercial distribution. Stakeholders must monitor how regulatory divergence in RF power limits and cybersecurity labeling reshapes component sourcing and regional product variant strategies.
Market Dynamics
Enterprise IT procurement teams are consolidating vendor relationships for hybrid work audio deployments, compressing supplier diversity while elevating performance specifications for beamforming MEMS arrays and active noise cancellation algorithms.
Growth Catalysts
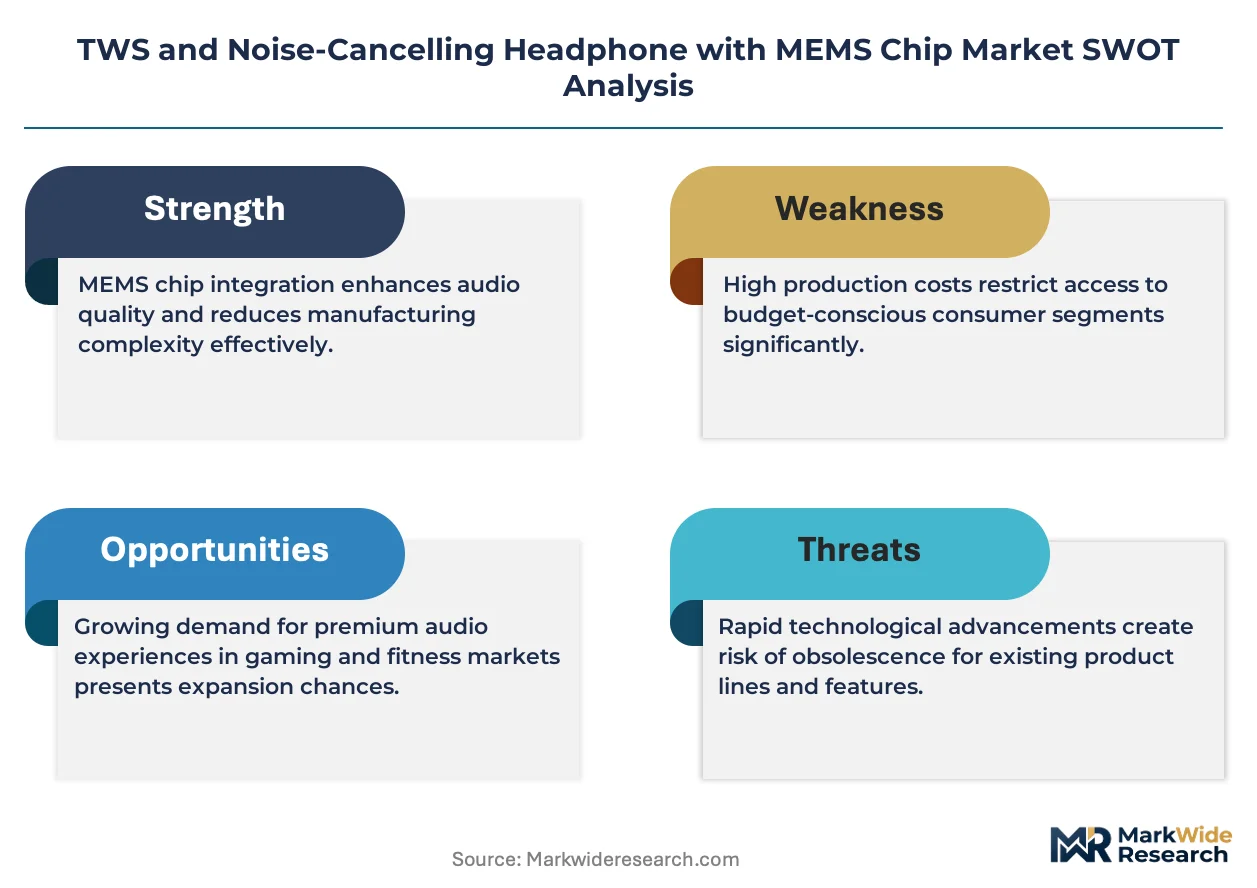
- EU Radio Equipment Directive:CE marking mandates for electromagnetic compatibility are accelerating certification investments among OEMs targeting European distribution channels, filtering out non-compliant suppliers.
- Hybrid work normalization:Enterprise procurement of TWS bundles for distributed teams is sustaining replacement cycles beyond consumer refresh rates, anchoring volume visibility for contract manufacturers.
- Shenzhen MEMS cluster concentration:Proximity of microphone module suppliers to final assembly operations in Guangdong province is compressing logistics costs and enabling rapid prototyping iterations for branded OEMs.
Market Restraints
- Silicon wafer input volatility:MEMS die fabrication depends on 200mm silicon supply contracted through foundry partners, exposing cost structures to semiconductor cycle fluctuations.
- Single-region module concentration:Over 70 percent of MEMS microphone output originates from Dongguan and Shenzhen manufacturing corridors, creating geographic risk exposure for supply continuity.
- Bluetooth codec commoditization:Standardized SBC and AAC implementations eliminate differentiation at entry price tiers, compressing margin pools for non-proprietary ecosystem players.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting TWS assembly investments to Noida and Sriperumbudur corridors, diversifying regional supply footprints.
- Hearing aid compatibility mandates:FCC requirements for HAC certification are opening adjacent revenue streams for MEMS microphone suppliers with medical-grade acoustic validation capabilities.
- Spatial audio convergence:Integration of head-tracking sensors with beamforming arrays is creating premium tier differentiation for professional audio monitoring and immersive entertainment applications.
Industry Challenges
- Acoustic calibration expertise scarcity:Tuning ANC algorithms to variable ear canal geometries requires specialized audio engineering talent concentrated in Copenhagen, Tokyo, and California metro areas.
- Bluetooth SIG certification timelines:Interoperability testing queues for new codec implementations are extending product launch windows by 8-14 weeks for non-priority members.
- RF coexistence complexity:Simultaneous operation of 2.4 GHz Bluetooth with Wi-Fi 6E and UWB radios in compact enclosures demands electromagnetic simulation capabilities that strain mid-tier engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TWS and Noise-Cancelling Headphone with MEMS Chip Market |
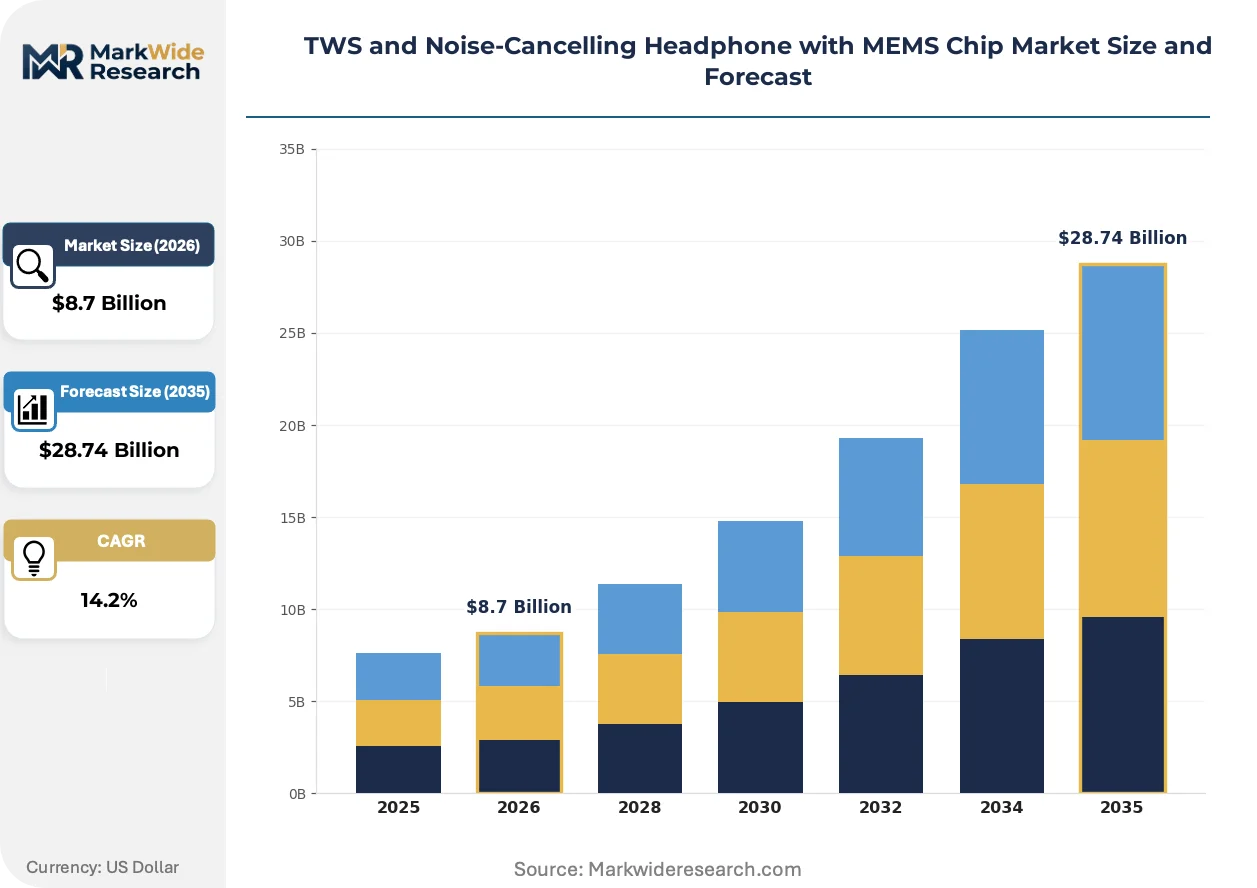
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TWS Headphones, Over-Ear Headphones, On-Ear Headphones, In-Ear Monitors Technology: MEMS Microphones, Active Noise Cancellation, Passive Noise Isolation, Bluetooth Connectivity End User: Consumer Electronics, Professional Audio, Gaming Industry, Automotive Feature: Touch Controls, Voice Assistants, Water Resistance, Long Battery Life |
| Companies Covered | Apple, Sony, Bose, Samsung Electronics, Sennheiser, JBL, Goertek, Knowles, TDK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TWS and Noise-Cancelling Headphone with MEMS Chip Market Trends and Innovations
Acoustic front-end architectures are consolidating multiple transducer functions into single MEMS packages, while regulatory pressure on electromagnetic emissions and enterprise procurement standardization are reshaping competitive requirements across price tiers.
Silicon MEMS microphones are overtaking electret condenser capsules in premium over-ear configurations. Knowles and Goertek are supplying 64 dB+ SNR modules to professional audio monitoring segments. This transition is compressing the addressable market for traditional condenser suppliers while expanding beamforming array adoption in broadcast and conferencing applications.
REACH substance restrictions on persistent organic pollutants are tightening material declarations for headphone housings and cable assemblies. The European Chemicals Agency enforcement is accelerating substitution of halogenated flame retardants with phosphorus-based alternatives. Premium tier manufacturers are responding with modular designs that simplify end-of-life material separation.
Enterprise procurement departments are consolidating audio peripheral vendors under single-source contracts with performance-based renewal clauses. Channel partners are displacing direct OEM relationships for sub-500 unit deployments. This concentration is most visible in North American and Western European IT reseller networks, where managed service providers bundle TWS with device-as-a-service offerings.
TWS and Noise-Cancelling Headphone with MEMS Chip Market Segmentation
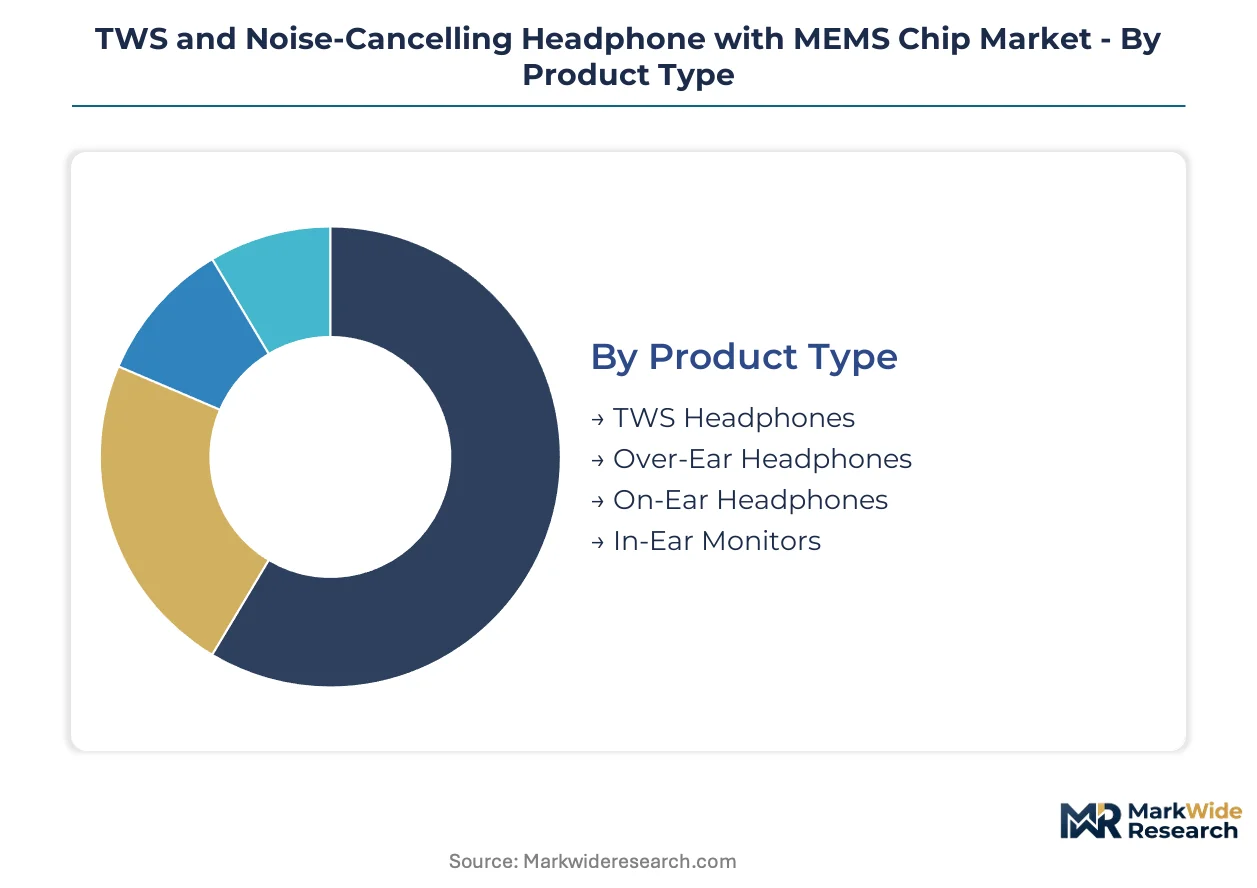
MEMS microphone integration requirements vary sharply across headphone form factors, driving divergent certification burdens and component sourcing strategies. Enterprise procurement teams prioritize beamforming arrays and ANC performance, while consumer segments emphasize codec compatibility and battery endurance.
Product Type:
FCC hearing aid compatibility mandates and EU Radio Equipment Directive CE marking apply differentially across form factors, with over-ear configurations facing stricter electromagnetic compatibility testing due to larger RF enclosures.
- TWS Headphones:Compact true wireless architectures integrate dual MEMS microphones per earbud for beamforming voice pickup. Dongguan contract manufacturers dominate assembly scale, supplying branded OEMs with Shenzhen-sourced microphone modules for consumer and enterprise bundles.
- Over-Ear Headphones:Circumaural designs accommodate larger MEMS arrays with 64 dB+ SNR specifications for professional audio monitoring. Copenhagen and Tokyo engineering clusters concentrate acoustic tuning expertise for ANC algorithm calibration to variable ear geometries.
- On-Ear Headphones:Supra-aural form factors balance portability with passive isolation, targeting mid-tier consumer segments with standardized Bluetooth implementations.
- In-Ear Monitors:Stage and studio applications demand medical-grade acoustic validation under FCC hearing aid compatibility frameworks, opening adjacent revenue streams for validated MEMS suppliers.
Leading the category by volume: TWS Headphones. Expanding most quickly: Over-Ear Headphones in professional audio deployments.
Technology:
Component cost structures stratify sharply between proprietary ecosystem control and standardized commodity implementations.
- MEMS Microphones:Silicon MEMS transducers measuring 3.76 mm by 2.95 mm replace electret condensers in premium tiers. Knowles and Goertek supply 64 dB+ SNR modules, with fabrication concentrated in 200mm foundry partnerships exposed to semiconductor cycle volatility.
- Active Noise Cancellation:Feedforward and feedback microphone arrays enable real-time ambient sound cancellation. Algorithm tuning requires scarce acoustic engineering talent, compressing supplier diversity for enterprise-grade implementations.
- Passive Noise Isolation:Mechanical sealing and damping materials deliver cost-effective isolation without power consumption, dominating entry-tier positioning.
- Bluetooth Connectivity:SBC and AAC codec standardization eliminates differentiation at base price tiers, while proprietary codec implementations sustain margin pools for ecosystem-integrated vendors.
Capturing the steepest expansion trajectory: Active Noise Cancellation. Maintaining the largest installed base: Bluetooth Connectivity.
End User:
Procurement consolidation patterns diverge between enterprise single-source contracts and fragmented consumer retail channels.
- Consumer Electronics:Retail and direct-to-consumer channels drive replacement cycles through feature differentiation. Touch controls and voice assistant integration anchor premium positioning.
- Professional Audio:Broadcast, studio monitoring, and conferencing applications demand validated beamforming performance. North American and Western European IT reseller networks concentrate vendor consolidation under managed service bundles.
- Gaming Industry:Low-latency wireless and spatial audio integration target competitive and immersive entertainment segments.
- Automotive:Cabin-integrated headphone systems for rear-seat entertainment require automotive-grade temperature and vibration specifications.
Enterprise procurement is concentrating fastest in Professional Audio. Consumer Electronics retains the broadest addressable base.
Feature:
Hardware differentiation competes with software-defined functionality as primary purchase drivers across price tiers.
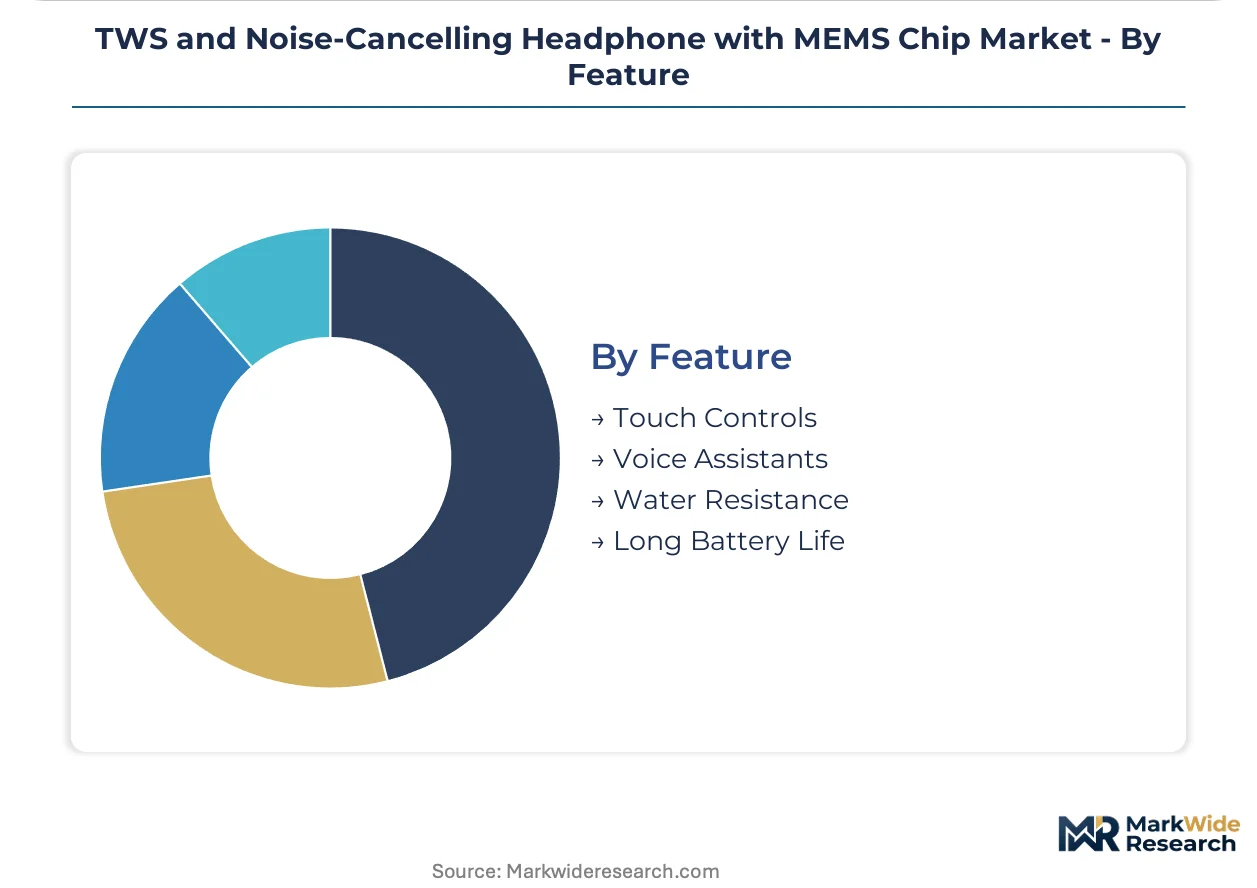
- Touch Controls:Capacitive gesture interfaces enable playback and call management without physical buttons. Water resistance integration complicates sealing design for Shenzhen assembly operations.
- Voice Assistants:Far-field MEMS microphone arrays with wake-word detection require FCC RF exposure compliance for simultaneous Bluetooth and Wi-Fi operation.
- Water Resistance:IP rating certification adds 6-10 weeks to product validation timelines for Dongguan contract manufacturers.
- Long Battery Life:Power management silicon and efficient codec implementations extend playback duration, with cell chemistry sourced from Guangdong battery suppliers.
Voice Assistants command the highest engineering investment intensity. Long Battery Life functions as the primary consumer comparison metric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the majority of MEMS microphone module fabrication and TWS final assembly, with enterprise procurement teams in the United States and Germany driving premium-tier demand for noise-cancelling configurations.
China
Shenzhen-based OEM clusters supply over 70 percent of global MEMS microphone modules for TWS integration. MIIT certifies radio transmission parameters for Bluetooth products manufactured in Guangdong province. Dongguan contract manufacturers dominate assembly scale, compressing logistics costs through proximity to microphone suppliers in the Pearl River Delta.
United States
Enterprise IT procurement teams consolidate vendor relationships for hybrid work audio deployments across distributed teams. FCC enforces hearing aid compatibility and RF exposure limits for wireless audio devices sold domestically. Acoustic calibration expertise concentrates in California metro areas, where ANC algorithm tuning for variable ear canal geometries commands premium engineering talent.
Germany
Professional audio monitoring segments demand validated beamforming performance for broadcast and studio applications. EU Radio Equipment Directive mandates CE marking for electromagnetic compatibility across member states. Berlin-Brandenburg engineering clusters specialize in acoustic tuning for over-ear ANC configurations targeting enterprise conferencing markets.
Japan
Consumer electronics channels emphasize codec compatibility and battery endurance in premium TWS positioning. METI oversees industrial standards coordination for wireless audio device interoperability. Tokyo engineering clusters concentrate scarce acoustic calibration talent for ANC algorithm development in compact form factors.
India
Production-linked incentives for electronics manufacturing attract TWS assembly investments to Noida and Sriperumbudur corridors. TRAI regulates spectrum allocation for Bluetooth and Wi-Fi coexistence in wireless audio devices. Tamil Nadu manufacturing corridors diversify regional supply footprints beyond Guangdong concentration.
TWS and Noise-Cancelling Headphone with MEMS Chip Market Competitive Landscape
Capacity expansion dominates the current landscape as contract manufacturers scale Dongguan facilities to serve branded OEM procurement consolidation. The vendor base stratifies between proprietary ecosystem integrators, specialized MEMS component suppliers, and scale-driven assembly operators. Three archetypes anchor competitive positioning: silicon MEMS microphone specialists, vertically integrated consumer electronics platforms, and contract manufacturing aggregators. Geographic expansion into India PLI corridors and technology licensing for spatial audio integration represent the dominant competitive moves reshaping supplier relationships.
Among Cupertino-based ecosystem integrators, Apple anchors proprietary chip-to-acoustic system control. Tokyo and Berlin-Brandenburg specialists in professional audio monitoring include Sony and Sennheiser, occupying positions where validated beamforming performance commands premium tier positioning. Dongguan-scale contract manufacturers exemplify the assembly-aggregator archetype, with Goertek representing the concentration of final assembly operations supplying multiple branded OEMs from Guangdong facilities.
| Leading Market Players |
|---|
| Apple |
| Sony |
| Bose |
| Samsung Electronics |
| Sennheiser |
| JBL |
| Goertek |
| Knowles |
| TDK |
| Others |
Pricing and Supply Chain Analysis
Captive MEMS microphone production in Shenzhen-Dongguan corridors anchors supply positioning and pricing power for contract manufacturers serving branded OEMs. Knowles and Goertek leverage proximity to 200mm foundry partners to compress component costs while EU Radio Equipment Directive compliance investments filter non-compliant suppliers from premium tiers.
Pricing Analysis
Volume shipments concentrate in TWS earbuds where margin compression runs deepest, while over-ear configurations with medical-grade acoustic validation sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FCC hearing aid compatibility certification from basic Bluetooth implementations. Price differentiation stems from beamforming array complexity and ANC algorithm calibration depth. Cost compression in entry tiers intensifies because Bluetooth codec standardization eliminates feature-based premiums. Enterprise procurement teams demonstrate lowest price sensitivity due to single-source contract structures, while consumer retail channels face acute sensitivity to battery life and codec compatibility metrics.
Supply Chain Analysis
200mm silicon wafer supply rests on foundry partnerships concentrated in Taiwan, South Korea, and Japan for MEMS die fabrication. Raw material dependencies include silicon substrates, rare-earth magnets for speaker drivers, and lithium-ion cells from Guangdong battery suppliers. Single-region module concentration in Dongguan and Shenzhen manufacturing corridors creates geographic risk exposure for supply continuity. Distribution runs through North American and Western European IT reseller networks where managed service providers bundle TWS with device-as-a-service offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Radio Equipment Directive CE marking investments create a barrier-to-entry moat for OEMs with validated electromagnetic compatibility testing capabilities.
For Market Incumbents: Extend beamforming array expertise into adjacent hearing aid compatibility certification streams under FCC frameworks. Deepen captive MEMS microphone supply through backward integration into 200mm foundry partnerships, defending against silicon wafer input volatility that exposes cost structures to semiconductor cycle fluctuations. For New Entrants and Emerging Players: Enter via India PLI scheme corridors in Noida and Sriperumbudur where production-linked incentives attract TWS assembly investments outside Guangdong concentration. Target professional audio monitoring segments in Germany and Japan where acoustic calibration expertise scarcity limits supplier diversity. Pursue white-label contract manufacturing relationships with IT resellers bundling audio peripherals under managed service offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated consumer electronics platforms seeking beamforming IP and validated ANC algorithm portfolios. Long-term viability favors suppliers with medical-grade acoustic validation capabilities spanning hearing aid compatibility and professional monitoring applications. Watch spatial audio convergence with head-tracking sensor integration as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Spatial Audio Integration | Head-tracking sensor convergence with beamforming arrays creates professional monitoring differentiation. |
| India PLI Manufacturing Expansion | Noida and Sriperumbudur corridors diversify supply footprints beyond Guangdong concentration. |
| Hearing Aid Compatibility Certification | FCC mandates open adjacent revenue streams for MEMS suppliers with medical-grade validation. |
| MEMS Microphone Backward Integration | 200mm foundry partnerships reduce silicon wafer input volatility exposure. |
| Enterprise IT Reseller Channel Partnership | Managed service bundles displace direct OEM relationships for sub-500 unit deployments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Bluetooth SIG certification databases, FCC equipment authorization files, and EU CE marking registries supplied compliance tracking metrics. Primary interviews with contract manufacturing procurement leads, acoustic engineering directors, and enterprise IT category managers validated component cost structures and procurement consolidation patterns. SEC filings from MEMS microphone suppliers and foundry partners informed capacity expansion timelines. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across form factor and technology segments.
Product-level granularity modeled TWS, over-ear, on-ear, and in-ear monitor configurations separately across consumer electronics, professional audio, gaming, and automotive end uses. Technology dimensions included MEMS microphone SNR tiers, ANC algorithm implementations, and Bluetooth codec standards. Regional clusters captured China MIIT certification requirements, FCC hearing aid compatibility mandates, and EU Radio Equipment Directive electromagnetic compliance. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and enterprise procurement velocity indicators. Semiconductor cycle volatility and silicon wafer contract pricing informed input cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence in RF power limits and cybersecurity labeling requirements. Forecasts reflect assumptions documented in trade association shipment reports and foundry capacity disclosures. Specific risk factors that could revise projections include REACH substance restriction enforcement accelerating material substitution costs, and Bluetooth SIG certification timeline extensions delaying product launches. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Video Surveillance Chip Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Trackpad Market
Electronic Components
Global Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Touchless Tubes Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Fuse Bases Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Lowpass Filters Market
Electronic Components
Timing Relay Market
Electronic Components
Encoder Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Audio Amplifier Market
Electronic Components
Motherboard Battery Market