
 Firefighter Tape Market | 2026-2036
Firefighter Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighter Tape Market Analysis
Municipal procurement departments is bifurcating from volunteer fire companies as the dominant buyer archetype for high-performance adhesive products. 3M Company leverages its materials science portfolio to dominate North American supply channels for thermal-resistant bonding solutions. ORAFOL Europe anchors continental demand through specialized reflective and safety tape manufacturing in Germany. Brady competes on identification and safety labeling integration with structural firefighting equipment specifications.
Firefighter tape denotes pressure-sensitive adhesive products engineered with flame-retardant substrates, typically silicone or acrylic formulations on fiberglass or aramid backings, designed to maintain adhesion above 260°C for equipment marking, hose repair, and protective gear seam sealing. Kevlar-based tapes command premium positioning due to para-aramid thermal stability and abrasion resistance in structural firefighting applications. Single-sided tape configurations occupy the largest volume share across fire departments globally, while heat-resistant tape variants capture disproportionate margin pools from military and industrial safety end users requiring extended thermal exposure ratings.
NFPA standards in the United States and CE marking requirements under the EU Construction Products Regulation shape product certification pathways and market access conditions for adhesive suppliers serving European emergency services. The EPA oversees volatile organic compound emissions from tape manufacturing facilities, influencing solvent-based adhesive formulations and production location decisions. Stakeholders must monitor evolving flammability testing protocols from ISO and national standards bodies to anticipate reformulation investments and certification renewal cycles.
Market Dynamics
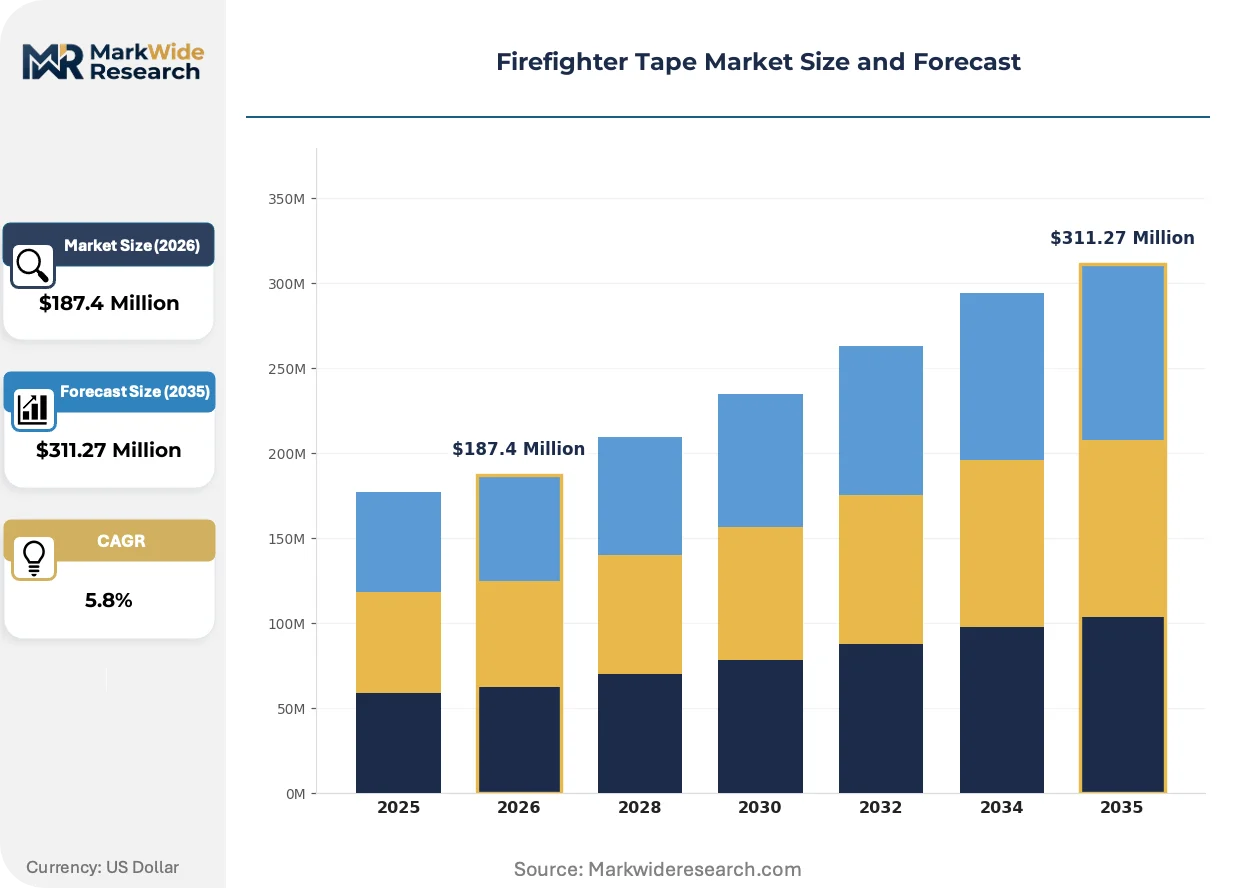
Municipal fire departments are consolidating procurement authority while NFPA 1971 standards tighten thermal performance thresholds, forcing adhesive suppliers to reformulate substrate chemistry and recertify product lines on accelerated timelines.
Growth Catalysts
- NFPA 1971 Standard Revisions:Updated thermal protective equipment requirements in the United States mandate higher heat-resistance ratings for seam-sealing tapes, driving replacement cycles across municipal inventories.
- Aramid Fiber Innovation:Kevlar-based backing materials now achieve sustained adhesion above 260°C, opening structural firefighting applications previously served by bulkier mechanical fasteners.
- German Infrastructure Modernization:Federal funding for aging fire service equipment replacement is concentrating demand for CE-marked reflective and safety tape products.
Market Restraints
- Silicone Raw Material Concentration:Specialty silicone feedstock production clusters in Northeast Asian chemical corridors, exposing tape manufacturers to supply disruption risk and input cost volatility.
- EPA VOC Emission Limits:Solvent-based acrylic adhesive formulations face escalating compliance costs under Clean Air Act enforcement, compressing margins for legacy production lines.
- Mechanical Fastener Substitution:Hook-and-loop closure systems retain preference in rapid-don protective gear applications where tape adhesion degradation poses liability exposure.
Strategic Opportunities
- Wildland-Urban Interface Expansion:California and Australian jurisdictions are procuring specialized heat-resistant tape kits for wildland firefighting vehicle marking and equipment repair.
- EU Green Deal Procurement Mandates:Public tender specifications increasingly favor bio-based adhesive formulations and recyclable aramid substrates, rewarding early reformulation investments.
- Digital Inventory Integration:RFID-enabled tape products for equipment tracking are penetrating municipal fleet management systems, merging safety marking with asset management functionality.
Industry Challenges
- NFPA Certification Timeline Compression:Third-party testing laboratory capacity constraints are extending product validation cycles, delaying revenue recognition for new formulations.
- Multi-Standard Harmonization:Tape manufacturers must simultaneously satisfy NFPA 1971, EN 469, and ISO 11612 testing protocols, multiplying quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighter Tape Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tape, Double-Sided Tape, Waterproof Tape, Heat-Resistant Tape Material: Polyethylene, Polyvinyl Chloride, Kevlar, Fiberglass Application: Firefighting Equipment, Hose Repair, Protective Clothing, Vehicle Maintenance End User: Fire Departments, Industrial Safety, Military, Emergency Services |
| Companies Covered | 3M Company, ORAFOL Europe, Arlon Graphics, Nitto Denko, Brady, Godson Tapes, Lares International, Advance Tapes International, Harris Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighter Tape Market Emerging Trajectories
Adhesive chemistry and substrate engineering are converging to produce tape systems that function across wider thermal ranges while integrating digital tracking capabilities, compressing the traditional separation between safety equipment and smart infrastructure.
Silicone-acrylic hybrid adhesive formulations are supplanting pure silicone chemistries in high-temperature marking applications. Municipal procurement departments in the United States and Germany are specifying these hybrids for hose repair and equipment identification. The shift is compressing price premiums for entry-level thermal tape categories while elevating performance baselines across mid-tier product lines.
REACH restrictions on persistent organic pollutants are forcing reformulation of legacy flame-retardant additives in European-manufactured tapes. ECHA substance evaluation processes have flagged several halogenated compounds previously standard in reflective tape backings. German and French adhesive suppliers are accelerating substitution with phosphorus-nitrogen intumescent systems to maintain CE marking eligibility.
Bulk purchasing consortia organized at state and provincial levels are displacing individual department procurement for standardized tape specifications. California's Office of Emergency Services and Ontario's Municipal Equipment Cooperative are aggregating demand across hundreds of fire departments. This concentration is visible across North American markets where specification authority is migrating from individual fire chiefs to centralized procurement officers with formal value-analysis committees.
Firefighter Tape Market Segmentation
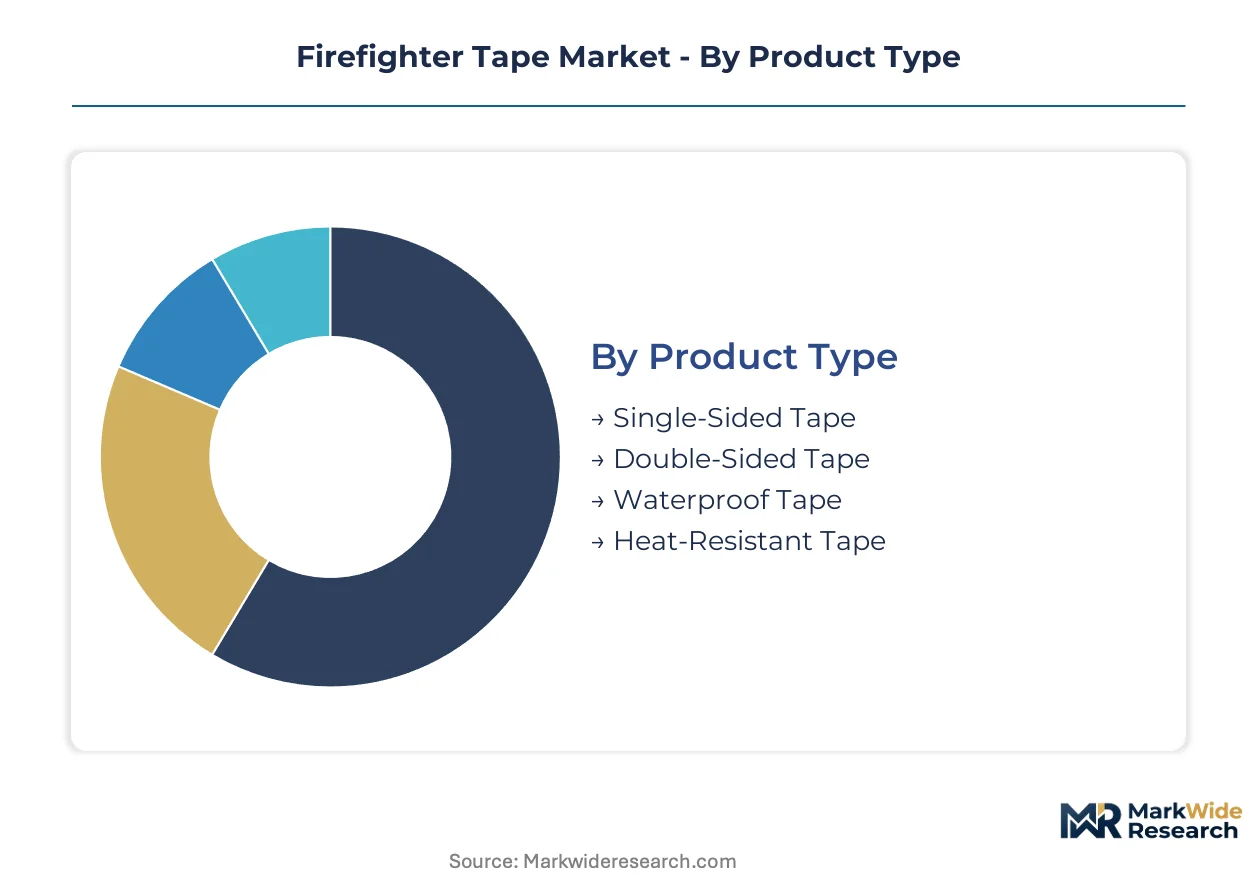
Firefighter tape procurement decisions pivot on thermal certification thresholds and end-use environment severity. Municipal buyers segment specifications by equipment integration point, material compatibility, and regulatory compliance burden rather than adhesive chemistry alone.
Product Type:
NFPA 1971 thermal performance tiers and EN 469 certification requirements create distinct specification tracks for single-sided versus double-sided configurations, with heat-resistance ratings determining access to structural firefighting versus general equipment marking applications.
- Single-Sided Tape:Silicone or acrylic adhesive on fiberglass or aramid backings serves hose identification, equipment marking, and temporary protective gear repairs. Municipal fire departments in the United States specify these for turnout gear seam sealing where rapid application and repositioning dominate operational requirements.
- Heat-Resistant Tape:Hybrid silicone-acrylic formulations sustain adhesion above 260°C for extended thermal exposure in structural firefighting and wildland-urban interface operations. German federal infrastructure modernization programs are concentrating procurement of these certified products for aging fleet replacement cycles.
- Double-Sided Tape:Pressure-sensitive adhesive layers on both faces enable bonding of reflective strips to helmets and protective clothing without mechanical fasteners.
- Waterproof Tape:Butyl or rubberized adhesive systems seal hose couplings and equipment cases against moisture ingress during suppression operations.
Single-sided tape handles the majority of throughput; heat-resistant tape is expanding most quickly on specification authority migrating to centralized procurement officers with formal thermal testing requirements.
Material:
Substrate selection traces directly to thermal stability requirements and abrasion exposure severity, with para-aramid and fiberglass commanding specification premiums in structural applications while commodity polymers serve auxiliary marking functions.
- Kevlar:Para-aramid fiber backings deliver sustained dimensional stability above 400°C with exceptional tear resistance for protective clothing seam sealing and structural firefighting equipment marking. NFPA 1971 standard revisions are accelerating replacement of legacy polyester substrates in United States municipal inventories.
- Fiberglass:Woven glass fiber substrates coated with silicone adhesive provide cost-optimized thermal performance for hose repair and vehicle marking applications where extreme abrasion resistance is secondary to heat dissipation. German fire service infrastructure modernization is concentrating demand for CE-marked fiberglass tapes in reflective safety configurations.
- Polyethylene:Extruded polymer films with pressure-sensitive adhesive serve low-temperature equipment labeling and temporary protective applications.
- Polyvinyl Chloride:Flexible vinyl backings with flame-retardant additives provide conformable marking solutions for curved equipment surfaces and hose identification.
Fiberglass substrates anchor volume throughput in municipal procurement; Kevlar-based configurations are climbing the fastest as thermal performance thresholds tighten across certification regimes.
Application:
Application segmentation follows equipment lifecycle intensity and regulatory exposure, with protective clothing integration facing the most stringent certification burdens while vehicle maintenance offers specification flexibility.
- Protective Clothing:Seam-sealing tapes for turnout gear and station wear must satisfy NFPA 1971 thermal protective performance testing and EN 469 heat resistance requirements. United States municipal departments are consolidating procurement of certified tapes through state-level purchasing consortia to manage compliance documentation overhead.
- Firefighting Equipment:Equipment marking and identification tapes for breathing apparatus, tools, and communication devices integrate RFID tracking capabilities with thermal-resistant substrates. German and French adhesive suppliers are accelerating phosphorus-nitrogen intumescent formulations to maintain CE marking eligibility under REACH restrictions.
- Hose Repair:Field-applied wrapping tapes for damaged suppression hose require rapid adhesion development and chemical resistance to hydraulic fluids and firefighting foams.
- Vehicle Maintenance:Reflective striping and identification marking for fire apparatus and wildland vehicles prioritize visibility compliance over extreme thermal performance.
Firefighting equipment applications concentrate the highest specification complexity; protective clothing is gaining share fastest as NFPA and EN standard harmonization extends certification renewal cycles.
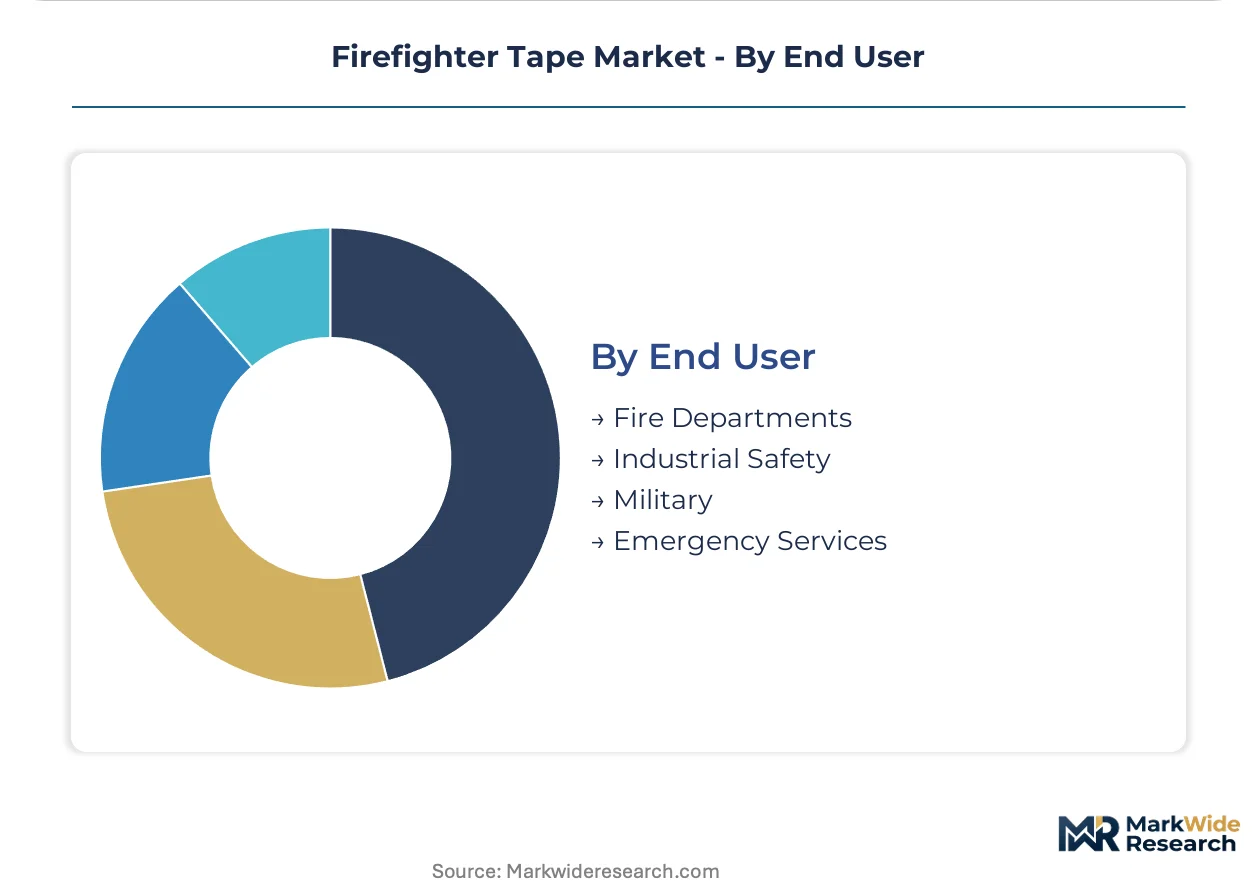
End User:
End user segmentation reflects procurement authority consolidation and specification sophistication, with municipal fire departments displacing volunteer companies as the dominant buyer archetype for certified thermal tape products.
- Fire Departments:Municipal and volunteer fire services specify NFPA 1971 and EN 469 certified tapes for protective gear maintenance, equipment marking, and hose repair. California's Office of Emergency Services and Ontario's Municipal Equipment Cooperative are aggregating demand across hundreds of departments, migrating specification authority from individual fire chiefs to centralized procurement officers.
- Industrial Safety:Petrochemical, mining, and manufacturing facilities procure heat-resistant tapes for emergency response team equipment and confined space rescue gear. EPA VOC emission limits under the Clean Air Act are compressing margins for solvent-based acrylic formulations serving this segment.
- Military:Defense procurement of firefighter tape emphasizes extended thermal exposure ratings and multi-threat protection for combat vehicle crew systems and aircraft rescue operations.
- Emergency Services:Ambulance and technical rescue services specify conformable marking tapes for equipment identification and temporary structural stabilization.
Fire departments handle the majority of procurement volume; industrial safety is the fastest mover on regulatory compliance requirements extending from fire service standards into occupational safety regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and German Autobahn network underpin emergency response logistics, concentrating firefighter tape demand in jurisdictions with aging infrastructure replacement mandates.
United States
Municipal fire departments in California and Texas are consolidating procurement through state-level purchasing consortia. EPA VOC emission limits under the Clean Air Act are forcing reformulation of solvent-based acrylic adhesives. Chicago and Houston metropolitan fire districts are driving specification migration toward NFPA 1971 certified thermal tapes.
Germany
Federal infrastructure modernization programs are channeling equipment replacement funding through North Rhine-Westphalia and Bavaria. CE marking requirements under the EU Construction Products Regulation shape product certification pathways for adhesive suppliers. The Rhine-Ruhr industrial corridor concentrates manufacturing of reflective safety tape for fire apparatus marking.
China
Urban fire service expansion in Shanghai and Beijing is generating procurement of heat-resistant equipment marking tapes. The country's national standards administration oversees flammability testing protocols for protective gear materials. Yangtze River Delta chemical clusters supply specialty silicone feedstock for domestic tape manufacturers.
Japan
Tokyo and Osaka metropolitan fire departments specify high-performance seam-sealing tapes for protective clothing maintenance. METI industrial safety guidelines extend thermal performance requirements into occupational firefighting equipment. The Kanto region anchors demand for aramid-based adhesive products in technical rescue applications.
United Kingdom
London Fire Brigade and Scottish Fire and Rescue Service are harmonizing procurement specifications with EN 469 standards. The country's national standards body influences testing protocol alignment with ISO 11612 thermal resistance benchmarks. Midlands manufacturing clusters produce fiberglass-backed tapes for hose repair and vehicle marking.
Firefighter Tape Market Vendor Landscape
Listed leaders compete with private specialists across materials science capabilities, creating a tiered structure where scale-driven conglomerates and regional specialists coexist. The vendor base separates into diversified adhesive conglomerates with cross-industry portfolios, European reflective materials specialists with safety-focused manufacturing, and regional tape converters serving localized procurement channels. Consolidation pressure is accelerating through strategic partnerships between chemical feedstock suppliers and finished tape manufacturers, while geographic expansion into wildland-urban interface jurisdictions represents a parallel competitive vector.
Within the diversified materials tier, 3M Company and Nitto Denko exemplify scale-driven positioning across thermal adhesive technologies. ORAFOL Europe occupies a specialist position in reflective and safety tape manufacturing anchored in German production. Brady represents the identification and safety labeling integration archetype, sitting within the structural firefighting equipment specification ecosystem.
| Leading Market Players |
|---|
| 3M Company |
| ORAFOL Europe |
| Arlon Graphics |
| Nitto Denko |
| Brady |
| Godson Tapes |
| Lares International |
| Advance Tapes International |
| Harris Industries |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at specialty silicone polymer plants in Northeast Asia directly shapes raw material availability floors for tape manufacturers, compressing margin structures when feedstock runs tight while enabling selective price aggression during oversupply phases. Municipal procurement consortia in the United States and Germany exploit this concentration through aggregated tender specifications that extract volume discounts from adhesive suppliers competing on NFPA 1971 and EN 469 certification credentials.
Pricing Analysis
Volume-discount tiering structures dominate municipal procurement, with California's Office of Emergency Services and Ontario's Municipal Equipment Cooperative extracting graduated rebates based on aggregated department participation. Price differentiation rests on thermal certification tier—NFPA 1971 certified products command substantial premiums over general equipment marking grades—and Kevlar backing content versus fiberglass alternatives. Cost compression in standard-grade silicone-acrylic hybrids is intensifying because REACH-compliant reformulation expenses are spreading across thinner volume bases. Volunteer fire companies exhibit highest price sensitivity, while German federal infrastructure programs show lowest elasticity due to mandated CE marking compliance.
Supply Chain Analysis
Northeast Asian chemical corridor transit through Shanghai and Busan ports underwrites global specialty silicone feedstock availability, exposing tape manufacturers to maritime disruption risk. Raw material sourcing draws from Chinese silicone polymer production, German aramid fiber spinning, and Japanese adhesive resin synthesis. Single-source vulnerability concentrates in para-aramid substrate supply, where limited qualified producers constrain formulation flexibility. Distribution runs through state-level purchasing consortia and municipal procurement cooperatives, with direct OEM relationships penetrating industrial safety and military segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as NFPA 1971 standard revision cycles drive replacement demand across aging municipal inventories, with equipment modernization mandates in Germany and California providing synchronized procurement pull.
For Market Incumbents: Fortify certification moats by accelerating third-party laboratory partnerships to compress NFPA and EN validation timelines, while securing captive silicone feedstock arrangements with Yangtze River Delta producers to neutralize raw material volatility. Mechanical fastener substitution in rapid-don protective gear represents the named threat requiring defensive innovation in repositionable adhesive chemistries. For New Entrants and Emerging Players: Anchor in wildland-urban interface jurisdictions where California and Australian procurement specifications remain fluid and less encumbered by legacy supplier relationships. Wildland firefighting vehicle marking kits offer the most penetrable application segment, with go-to-market traction achievable through direct engagement with state emergency services offices rather than fragmented municipal fire chiefs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive chemistry specialists with demonstrated REACH reformulation capabilities and established CE marking pathways. Long-term viability over the coming decade rests on phosphorus-nitrogen intumescent system expertise displacing legacy halogenated compounds. The specific signal to watch is ECHA substance evaluation acceleration, which would force distressed asset availability among non-compliant European manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| NFPA 1971 Certification Investment | Third-party laboratory partnerships with UL or Intertek accelerate municipal procurement eligibility timelines. |
| Backward Integration into Silicone Feedstock | Captive polymer supply from Yangtze River Delta producers neutralizes raw material cost volatility exposure. |
| Phosphorus-Nitrogen Intumescent Reformulation | ECHA-compliant flame-retardant systems preserve CE marking eligibility under REACH persistent organic pollutant restrictions. |
| RFID-Enabled Tape Development | Digital inventory integration merges safety marking with municipal fleet asset management functionality. |
| Wildland-Urban Interface Geographic Expansion | California Office of Emergency Services procurement specifications offer first-mover positioning in emerging application segment. |
Methodological Framework
Cross-validation between municipal procurement officer interviews and secondary regulatory filing analysis anchors the qualitative findings in documented specification evolution patterns. Primary fieldwork engaged fire service equipment managers, adhesive R&D directors, third-party certification laboratory technicians, and state purchasing cooperative administrators. Secondary sources incorporated NFPA standard revision dockets, EPA Clean Air Act enforcement records, ECHA substance evaluation reports, and customs trade data on silicone polymer imports. Bottom-up demand aggregation from individual fire department inventories was reconciled against top-down federal infrastructure appropriation flows.
Sensitivity analysis around thermal performance threshold assumptions and raw material cost trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product configuration, substrate material tier, application environment severity, and end-user procurement authority structure. CAGRs were derived from equipment replacement cycle analysis and standard revision timing, with inputs from NFPA 1971 adoption curve modeling and German federal infrastructure modernization appropriation schedules.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation in NFPA-EN standard alignment timelines would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA substance evaluation acceleration and EPA VOC enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market