
 UAV GNSS Antenna Market | 2026-2036
UAV GNSS Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
UAV GNSS Antenna Market Insights
Chinese ceramic substrate suppliers is decoupling from legacy L1-only designs, forcing antenna makers to requalify dual-band feed networks. Trimble leverages its survey heritage to dominate high-precision RTK modules for mapping UAVs. Tallysman Wireless specializes in compact helical designs that sustain signal lock under rotor-blade multipath. Septentrio anchors European demand through ASIC-level interference mitigation.
A UAV GNSS antenna converts satellite RF signals into digital position fixes through right-hand circularly polarized elements, typically achieving axial ratios below 3 dB at zenith to maintain lock during banked flight maneuvers. These devices enable centimeter-level positioning for autonomous waypoint navigation, terrain following, and georeferenced payload delivery across commercial drone operations. Patch antennas occupy the volume-constrained consumer tier where cost sensitivity dominates procurement decisions, while helical arrays command premium positioning in survey and inspection applications where multipath rejection determines mission success. BeiDou-enabled variants are gaining share fastest as Chinese OEMs mandate domestic constellation compatibility for government-funded fleet procurements.
The FAA's Part 89 Remote ID rule and EASA's U-space framework mandate certified position sources, directly elevating antenna traceability and interference resilience requirements. China's MIIT enforces GB-standard testing for BeiDou terminals, creating parallel certification pathways that fragment supplier qualification costs. ISO 21384-3 drone operation standards further tighten antenna environmental testing protocols for temperature cycling and vibration survival. Stakeholders must monitor constellation modernization schedules and pre-position multi-frequency architectures before legacy L1-only inventories strand.
Market Dynamics
Multi-frequency receiver architectures are forcing antenna manufacturers to abandon legacy single-band designs, requalify feed networks, and absorb ceramic substrate supply chain reconfiguration costs.
Growth Catalysts
- FAA Part 89 Remote ID mandate:Certified position source requirements are accelerating antenna upgrades across commercial UAV fleets in the United States.
- Precision agriculture expansion:North American operators are deploying multi-constellation receivers to enable centimeter-level autosteering for crop spraying drones.
- Helical array adoption:Survey and inspection applications are demanding compact helical designs that reject rotor-blade multipath interference.
Market Restraints
- Ceramic substrate supply concentration:Chinese substrate suppliers control critical dielectric material flows, creating qualification bottlenecks for dual-band feed networks.
- Parallel certification costs:MIIT GB-standard testing for BeiDou terminals fragments supplier qualification expenses across incompatible regulatory pathways.
- Patch antenna commoditization:Volume-constrained consumer tier procurement prioritizes cost over performance, compressing margins for precision-grade alternatives.
Strategic Opportunities
- EASA U-space framework rollout:European certified position source mandates create upgrade cycles for antenna traceability and interference resilience specifications.
- BeiDou-enabled variant demand:Chinese OEM government-funded fleet procurements are mandating domestic constellation compatibility.
- ASIC-level interference mitigation:Integration of specialized signal processing architectures opens premium positioning in contested RF environments.
Industry Challenges
- Multi-frequency RF engineering talent scarcity:Design capabilities for dual-band feed network optimization concentrate among legacy survey equipment specialists.
- ISO 21384-3 environmental testing timelines:Temperature cycling and vibration survival protocols extend certification cycles for new antenna platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV GNSS Antenna Market |
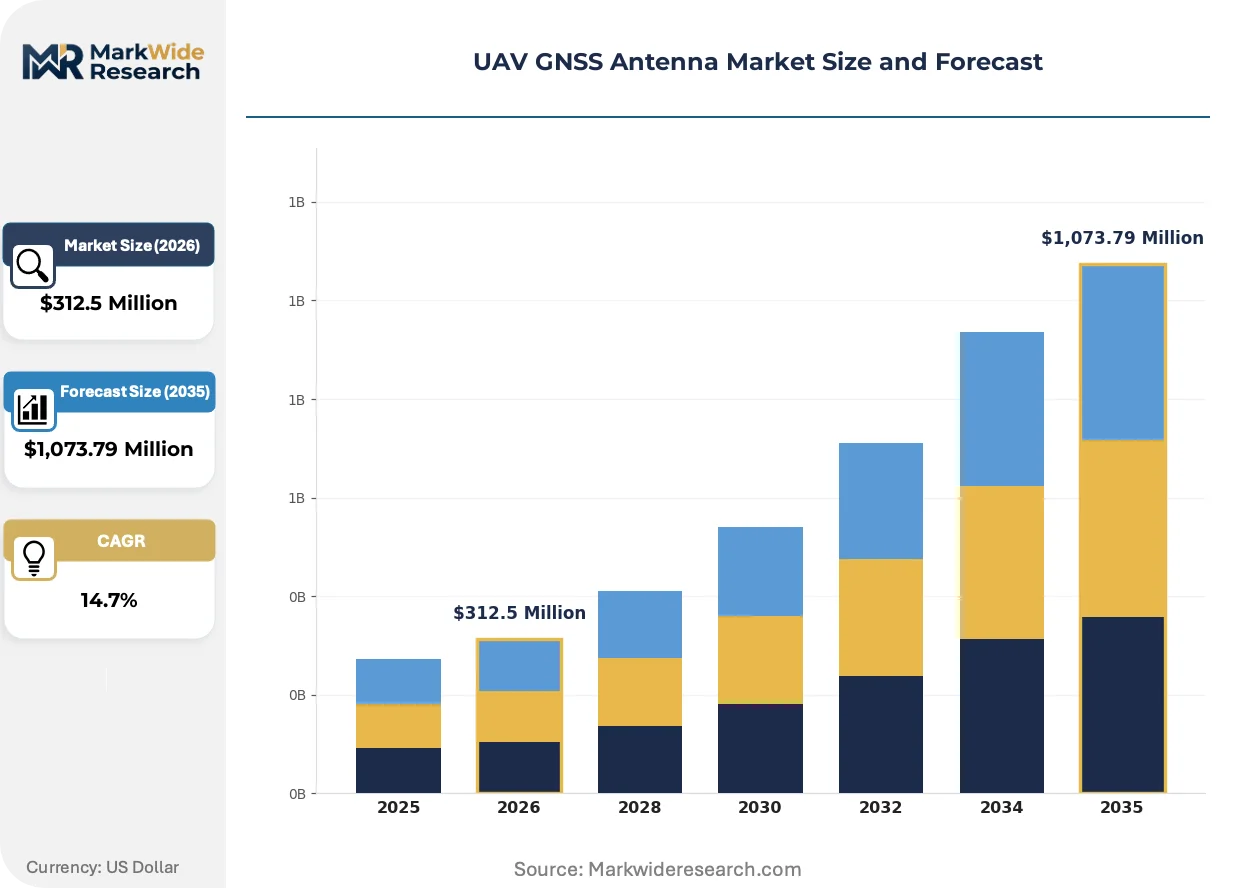
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,073.79 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Antenna, Helical Antenna, Quadrifilar Helix, Microstrip Antenna, Helix Array Technology: GPS, GLONASS, Galileo, BeiDou, IRNSS, QZSS Application: Precision Agriculture, Survey Mapping, Infrastructure Inspection, Environmental Monitoring, Search & Rescue, Forestry Management End User: Drone Manufacturers, Surveyors, Agricultural Specialists, Environmental Agencies, Public Safety Organizations, Research Institutions |
| Companies Covered | Trimble, ComNav Technology, Tallysman Wireless, Topcon Positioning Systems, Septentrio, Hemisphere GNSS, L3Harris Technologies, CHC Navigation, NovAtel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV GNSS Antenna Market Trends and Innovations
Antenna architectures are converging around multi-constellation compatibility and interference-hardened signal chains, compressing development cycles for legacy single-band suppliers.
Multi-frequency helical arrays with integrated low-noise amplifiers are electrifying the transition from patch-dominated consumer tiers to precision positioning modules. Survey and mapping UAV operators are adopting these configurations fastest, demanding axial ratios below 3 dB at zenith for banked flight maneuvers. The technology is electrifying competitive repositioning among ceramic substrate suppliers who must requalify dielectric formulations for wider bandwidth operation.
EASA's U-space framework and the FAA's equivalent Remote ID mandates are mandating certified position sources with traceable calibration chains. These rules elevate antenna interference resilience specifications and disqualify uncertified legacy units from commercial operations. European inspection UAV fleets are responding fastest, prioritizing ASIC-level mitigation over software-defined alternatives.
Buyer procurement patterns are compressing supplier qualification cycles as fleet operators pre-position multi-frequency inventories ahead of constellation modernization deadlines. Direct OEM relationships are displacing distributor channels for volume agricultural and logistics drone deployments. This concentration is most visible in Germany and China, where domestic manufacturing scale advantages accelerate captive antenna sourcing decisions.
UAV GNSS Antenna Market Segmentation
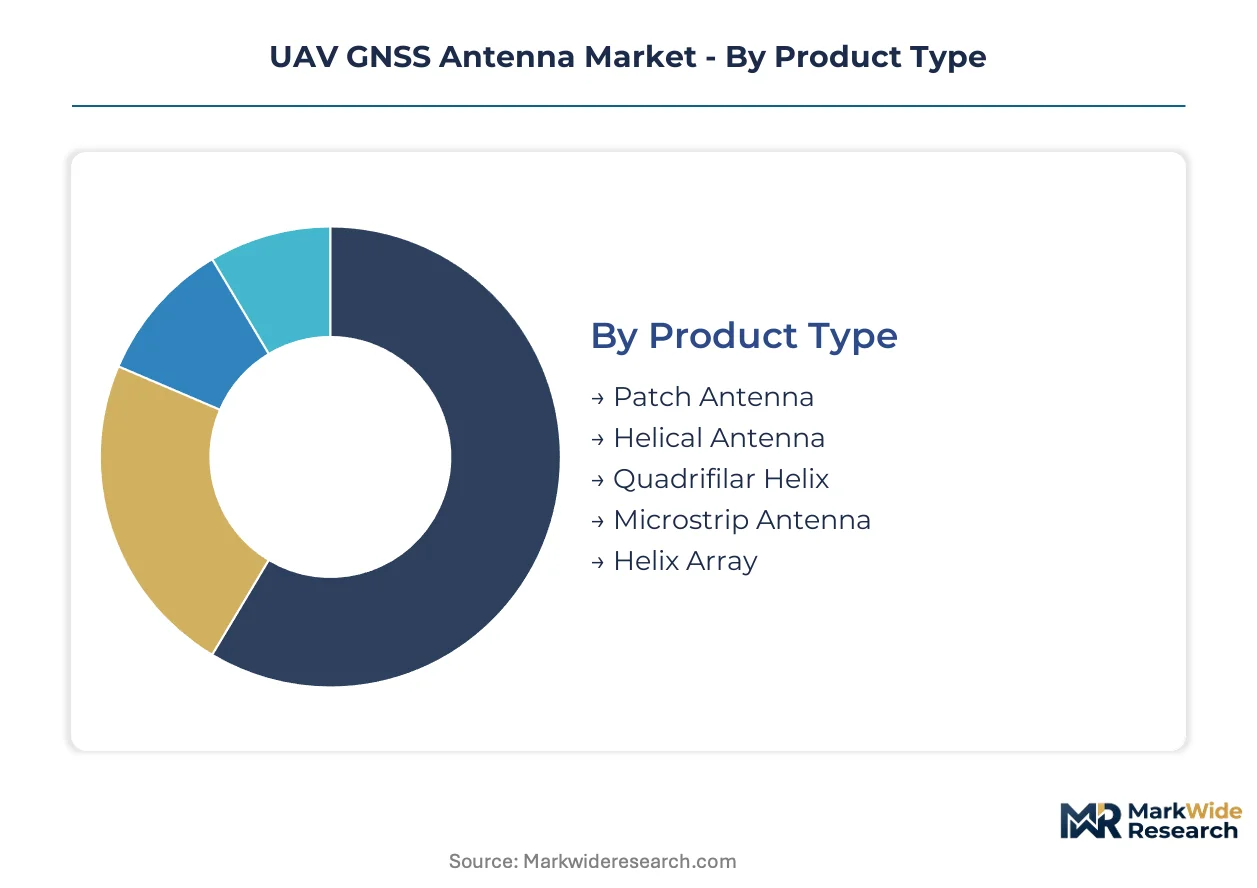
UAV GNSS antenna segmentation reveals how capital allocation, constellation compatibility, and end-use precision requirements fragment procurement patterns. Each dimension carries distinct qualification burdens and margin structures that reshape supplier positioning.
Product Type:
Capital intensity concentrates in helical architectures where ceramic substrate qualification and multi-frequency feed network development absorb the heaviest upfront investment.
- Patch Antenna:Planar radiating elements on dielectric substrates dominate volume-constrained consumer tiers. Agricultural drone OEMs in China source these configurations aggressively for cost-sensitive fleet builds where centimeter precision remains unnecessary.
- Helical Antenna:Right-hand circularly polarized windings deliver axial ratios below 3 dB under rotor-blade multipath. Survey and inspection operators in Germany specify these arrays for banked flight maneuvers where signal lock determines mission completion.
- Quadrifilar Helix:Four-element crossed helical structures achieve hemispherical coverage with compact form factors. Research institutions deploy these for environmental monitoring payloads requiring omnidirectional satellite visibility.
- Microstrip Antenna:Etched conductor patterns on low-loss substrates suit embedded integration. Drone manufacturers favor these for weight-critical racing and cinematography platforms.
- Helix Array:Stacked helical elements with integrated low-noise amplifiers command premium positioning. Public safety organizations in the United States procure these for contested RF environments where interference resilience overrides cost constraints.
Most installed capacity flows through Patch Antenna configurations. Expansion is steepest in Helical Antenna arrays as precision agriculture and survey mapping upgrade from single-band legacy units.
Technology:
Constellation licensing and certification pathway fragmentation determine technology selection economics, with multi-constellation architectures demanding parallel regulatory investment.
- GPS:L1/L2/L5 tri-frequency reception anchors North American commercial fleets. FAA Part 89 Remote ID mandates accelerate L5-capable receiver deployments across United States logistics and inspection operators.
- GLONASS:Russian constellation compatibility persists in Eastern European and Central Asian procurement specifications. Agricultural specialists in former Soviet markets maintain dual-GPS/GLONASS receiver requirements for redundancy.
- Galileo:European GNSS signals with commercial authentication services. EASA U-space framework adoption in Germany and France elevates Galileo-enabled antenna specifications for certified position source compliance.
- BeiDou:Chinese constellation with B1I/B2I/B3I civil signals. MIIT GB-standard testing mandates dominate domestic procurement, with government-funded fleet deployments requiring native constellation compatibility.
- IRNSS:Indian regional navigation system serving South Asian coverage arcs. Indigenous drone programs under ISRO coordination specify IRNSS reception for strategic autonomy in navigation infrastructure.
- QZSS:Japanese quasi-zenith augmentation enhancing GPS availability in urban canyons. Metropolitan inspection fleets in Tokyo and Osaka prioritize QZSS-compatible receivers for high-multipath environments.
Dual and triple-constellation configurations now dominate new procurement. BeiDou-enabled variants are climbing the fastest as Chinese OEM manufacturing scales and export markets adopt multi-constellation standards.
Application:
Precision requirements and mission-criticality stratify antenna performance tiers, with survey and agricultural applications commanding specification premiums over monitoring and rescue deployments.
- Precision Agriculture:Centimeter-level autosteering for crop spraying and variable-rate application. North American operators deploy multi-constellation receivers with RTK correction services across expanding drone fleets.
- Survey Mapping:Georeferenced photogrammetry and LiDAR requiring sub-decimeter absolute accuracy. German engineering firms specify helical arrays with ASIC-level interference mitigation for urban corridor mapping.
- Infrastructure Inspection:Power line, pipeline, and bridge structural assessment. Chinese grid operators mandate BeiDou-compatible antennas for transmission tower thermal monitoring contracts.
- Environmental Monitoring:Atmospheric sampling and wildlife tracking with moderate positioning requirements. Research institutions prioritize weight minimization over precision in remote sensing payloads.
- Search & Rescue:Emergency response coordination demanding rapid satellite acquisition. Public safety organizations in the United States value cold-start time and signal reacquisition speed above absolute accuracy.
- Forestry Management:Canopy-penetrating biomass estimation and fire perimeter mapping. Nordic environmental agencies specify robust axial ratio performance for low-elevation satellite tracking under dense cover.
Agricultural and survey procurement concentrates the highest antenna unit values. Forestry and environmental monitoring applications are expanding most quickly as regulatory mandates extend drone operations into protected land management.
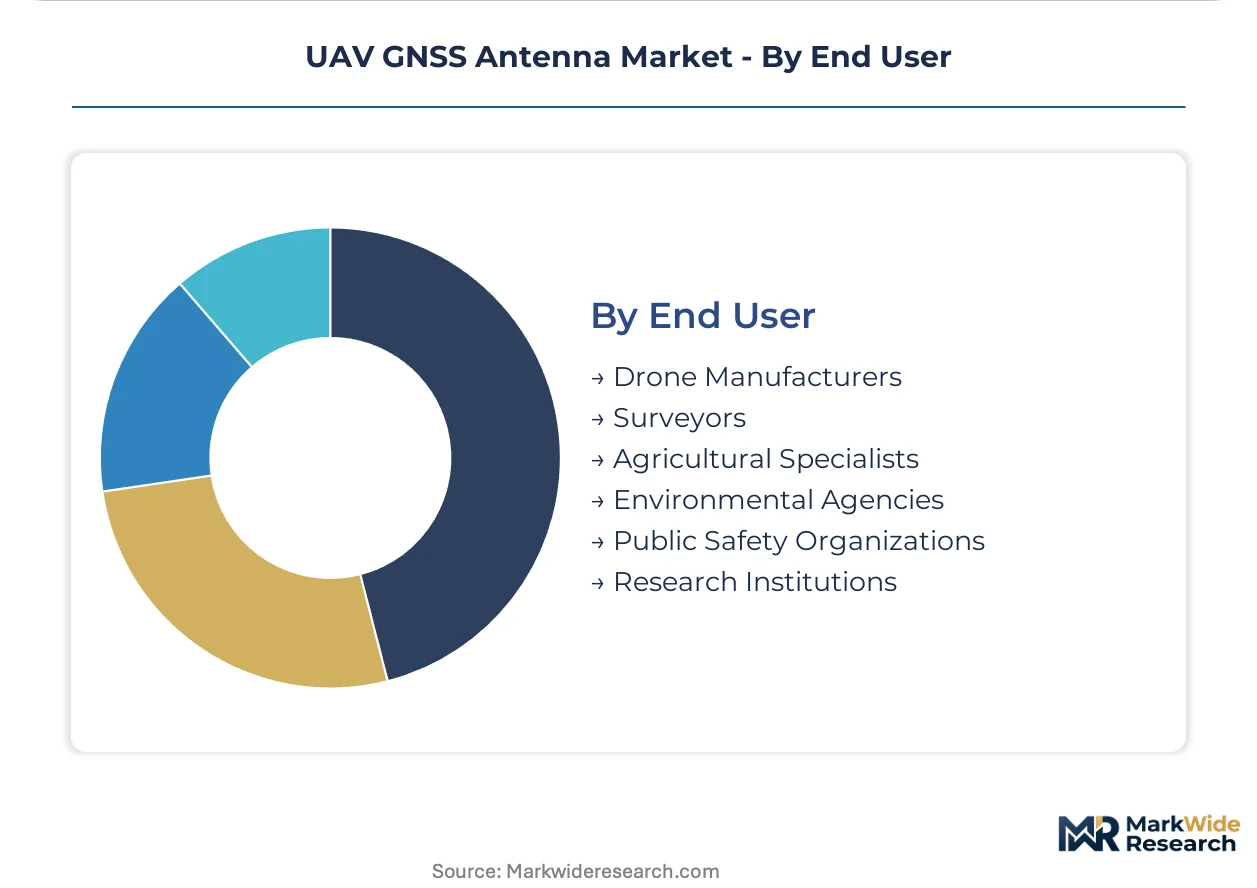
End User:
Procurement authority and technical specification control diverge sharply between OEM integrators and operational end-users, reshaping distribution channel economics.
- Drone Manufacturers:Volume procurement with captive antenna sourcing decisions. Chinese tier-one OEMs verticalize into in-house patch antenna production for consumer and prosumer tier builds.
- Surveyors:High-precision module selection with Trimble and Septentrio heritage equipment preferences. German geomatics firms specify calibrated antenna chains with traceable phase center variation documentation.
- Agricultural Specialists:Fleet-scale procurement through dealer networks with service bundling. North American cooperatives negotiate multi-year RTK subscription and antenna upgrade packages.
- Environmental Agencies:Public tender procurement with sustainability and domestic content weighting. European national parks prioritize repairable modular designs over integrated disposable units.
- Public Safety Organizations:Mission-critical specifications with interference hardening requirements. United States first responder programs fund ASIC-level mitigation through federal homeland security grants.
- Research Institutions:Small-batch procurement with customization tolerance and academic pricing. University labs drive experimental multi-frequency architectures ahead of commercial qualification.
Drone manufacturers absorb the highest absolute antenna volumes. Public safety and research procurement channels are gaining share fastest as specialized performance requirements outstrip standard OEM catalog offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing UAV GNSS antenna manufacturing toward jurisdictions with streamlined certification pathways and concentrated domestic drone demand. Cost-of-compliance gaps between single-market and multi-constellation approval regimes are accelerating supplier relocation decisions.
United States
Precision agriculture operators in the Midwest and California are scaling multi-constellation receiver deployments for autonomous crop spraying. The FAA's Part 89 Remote ID mandate is forcing antenna upgrades across commercial fleets, with certified position source requirements elevating traceability specifications. Texas and Arizona host expanding test ranges where public safety organizations evaluate ASIC-level interference mitigation for contested RF environments.
Germany
Survey and mapping firms in Bavaria and North Rhine-Westphalia specify helical arrays with sub-3 dB axial ratios for urban corridor photogrammetry. EASA's U-space framework mandates are accelerating certified position source procurement ahead of 2025 operational deadlines. The Stuttgart engineering cluster anchors European demand for calibrated antenna chains with documented phase center variation.
China
Domestic OEMs in the Yangtze River Delta and Pearl River Delta are verticalizing into captive patch antenna production for cost-sensitive consumer tiers. MIIT GB-standard testing for BeiDou terminals fragments supplier qualification pathways, creating parallel certification costs. Shenzhen-based drone manufacturers mandate B1I/B2I/B3I signal compatibility for government-funded fleet procurements.
Japan
Metropolitan inspection fleets in Tokyo and Osaka prioritize QZSS-compatible receivers for high-multipath urban canyon operations. METI coordination with domestic drone programs is standardizing multi-constellation architectures for infrastructure assessment contracts. The Nagoya manufacturing corridor concentrates ceramic substrate requalification activity for wider bandwidth dielectric formulations.
UAV GNSS Antenna Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ASIC-level interference mitigation and BeiDou-native architectures. The supplier base stratifies across three capability tiers: legacy survey equipment specialists with RTK heritage, compact helical design houses serving rotorcraft multipath rejection, and vertically integrated Chinese OEMs with captive substrate sourcing. Consolidation pressure is intensifying as multi-frequency RF engineering talent concentrates among a narrowing pool of qualified design teams. Strategic moves center on ceramic substrate supply chain control and parallel regulatory qualification investments across FAA, EASA, and MIIT pathways.
Within the precision-positioning tier, Trimble leverages its survey heritage to anchor high-precision module demand, while Tallysman Wireless exemplifies compact helical specialization for rotor-blade multipath environments. Septentrio occupies a distinct position through ASIC-level interference mitigation capabilities that address contested RF specifications in European and North American public safety procurement.
| Leading Market Players |
|---|
| Trimble |
| ComNav Technology |
| Tallysman Wireless |
| Topcon Positioning Systems |
| Septentrio |
| Hemisphere GNSS |
| L3Harris Technologies |
| CHC Navigation |
| NovAtel |
| Others |
Pricing and Supply Chain Analysis
Captive substrate sourcing by Chinese tier-one OEMs anchors supply positioning and compresses pricing power for independent antenna suppliers competing in consumer-tier procurement. This backward integration into ceramic dielectric production enables domestic drone manufacturers to undercut patch antenna imports while forcing Western helical specialists to defend premium positioning through certification-grade traceability.
Pricing Analysis
Distributor margins in agricultural dealer networks absorb 15-25 point markups before fleet operators negotiate bundled RTK subscription packages. Three-tier pricing structure across premium helical arrays, standard patch configurations, and economy microstrip designs separates survey-grade traceability from consumer-tier cost minimization. Cost compression in patch-dominated tiers is intensifying because Chinese OEM captive production eliminates import duties and logistics overhead. Agricultural cooperatives in North America exhibit highest price sensitivity, while public safety procurement in the United States shows least elasticity due to federal grant funding for interference-hardened specifications.
Supply Chain Analysis
Refurbishment flows for precision agriculture fleets extend antenna replacement cycles, compressing aftermarket revenue for helical array suppliers serving dealer service networks. Ceramic substrate supply concentrates in China, Japan, and Germany, with Yangtze River Delta suppliers controlling critical dielectric material flows for dual-band feed networks. Antenna manufacturing draws from high-purity alumina substrates, copper-clad laminates, and ASIC-level signal processing components. Single-source vulnerability in Chinese ceramic qualification creates bottlenecks when MIIT mandates force feed network redesigns. Distribution runs through direct OEM relationships displacing traditional distributor channels for volume drone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV GNSS antenna market functions as a regulatory compounder where FAA Part 89 Remote ID mandates and EASA U-space frameworks generate sustained upgrade demand across certified position source procurement.
For Market Incumbents: Cement ceramic substrate supply agreements ahead of dual-band requalification waves to lock dielectric material flows before Chinese competitors consolidate captive sourcing. Deepen backward integration into ASIC-level interference mitigation design teams concentrated in European survey equipment heritage clusters to defend against emerging entrants with software-defined alternatives. For New Entrants and Emerging Players: Launch via direct OEM partnerships with Chinese drone manufacturers seeking BeiDou-native antenna alternatives to incumbent Japanese and European suppliers. Target environmental monitoring applications in Nordic agencies where repairable modular specifications and sustainability weighting in public tenders create penetrable white space against integrated disposable units from established players. For Investors and Strategic Acquirers: Roll-up economics work for compact helical design specialists because multi-frequency RF engineering talent concentrates among fewer than twelve qualified teams globally, creating scarcity value in acquisition targets with rotor-blade multipath rejection IP. Monitor EASA U-space enforcement timelines as inflection indicator for European certified position source procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification Investment | Parallel FAA, EASA, and MIIT qualification opens procurement access across three regulatory jurisdictions. |
| Ceramic Substrate Supply Agreement | Locked dielectric material flows from Yangtze River Delta suppliers secure dual-band feed network production continuity. |
| ASIC-Level Interference Mitigation Development | Hardware-hardened signal processing addresses contested RF specifications in public safety and defense procurement. |
| Direct OEM Channel Expansion | Bypassing distributor networks captures volume agricultural and logistics drone deployment contracts in Germany and China. |
| BeiDou-Native Architecture Launch | B1I/B2I/B3I signal compatibility satisfies MIIT mandates for government-funded Chinese fleet procurements. |
Research Methodology
Bottom-up precision agriculture and survey mapping modeling reconciled against top-down ceramic substrate supply tracking forms the analytical core of this study. Primary interviews with antenna design engineers, drone OEM procurement leads, agricultural fleet operators, and regulatory certification specialists combined with secondary validation from FAA Remote ID rulemakings, EASA U-space framework documentation, MIIT GB-standard publications, and ISO 21384-3 environmental testing protocols. Trade data from customs records and semiconductor component import flows triangulated against bottom-up antenna unit deployment estimates.
Input-output matrices map ceramic substrate volumes through feed network fabrication to finished antenna output across product type, constellation compatibility, and end-use precision tiers. Modeled segmentation spans helical versus patch architectures, single versus multi-constellation receiver configurations, and precision agriculture versus survey mapping versus public safety applications. CAGRs derive from regression against constellation modernization schedules and regulatory mandate enforcement timelines. Forecast inputs include ceramic dielectric qualification timelines and RTK correction service subscription growth curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA enforcement or delayed EASA U-space operational deadlines. Practitioners should monitor ceramic substrate requalification completion rates and BeiDou export certification reciprocity agreements for early signals of supply constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Lidar Market
UAV
Europe Tethered Drone Market
UAV
Rc Helicopter Market
UAV
Drone Leasing Market
UAV
Drone Powered Business Solutions Market
UAV
Commercial UAV Market
UAV
Drone Lens Market
UAV
Drone Data Management Market
UAV
GCC Drones Market
UAV
Global VTOL UAV Market
UAV
Middle-East and Africa Drones Market
UAV
Middle-East and Africa Small UAV Market
UAV
Nano Drones Market
UAV
UAV Payload Market
UAV
Drone-In-A-Box Market
UAV
UAV Payload and Subsystems Market