
 Canada Eyeshadow Stick and Blush Stick Market | 2026-2036
Canada Eyeshadow Stick and Blush Stick Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Eyeshadow Stick and Blush Stick Market Outlook
The gap between prestige formulations and mass-market sticks is expanding. L'Oréal SA leverages its dual-brand architecture to occupy both luxury and accessible tiers through M.A.C Cosmetics and Nyx Professional Makeup. The Estée Lauder Companies Inc. anchors its Canadian presence with premium stick products distributed through department store counters in Toronto and Vancouver. ELF Cosmetics competes aggressively on price while sustaining clean-ingredient positioning that resonates with younger Canadian buyers.
Eyeshadow sticks and blush sticks are solid or semi-solid cosmetic formulations delivered in twist-up or retractable tubes, typically composed of waxes, oils, pigments, and film-forming agents that enable direct application without brushes. Cream formulations dominate Canadian retail shelves due to their blendability and compatibility with dry winter climates, while liquid sticks capture professional makeup artist channels demanding higher pigment load and extended wear. Gel sticks represent the fastest-growing product type as consumers seek transfer-resistant finishes for mask-compatible routines. Millennials drive volume across online retail and specialty beauty shops, though professionals command disproportionate margin pools through recurring bulk purchases.
Health Canada enforces the Cosmetic Regulations under the Food and Drugs Act, requiring ingredient disclosure via the Hotlist of prohibited and restricted substances, while the Canadian Environmental Protection Act governs microplastic-free formulations that increasingly influence stick product reformulation. PMRA oversight of preservative safety and the Competition Act's greenwashing provisions tighten marketing claims around clean beauty positioning. Stakeholders must monitor evolving provincial extended producer responsibility schemes in British Columbia and Ontario that will reshape packaging compliance costs for stick-format cosmetics.
Market Dynamics
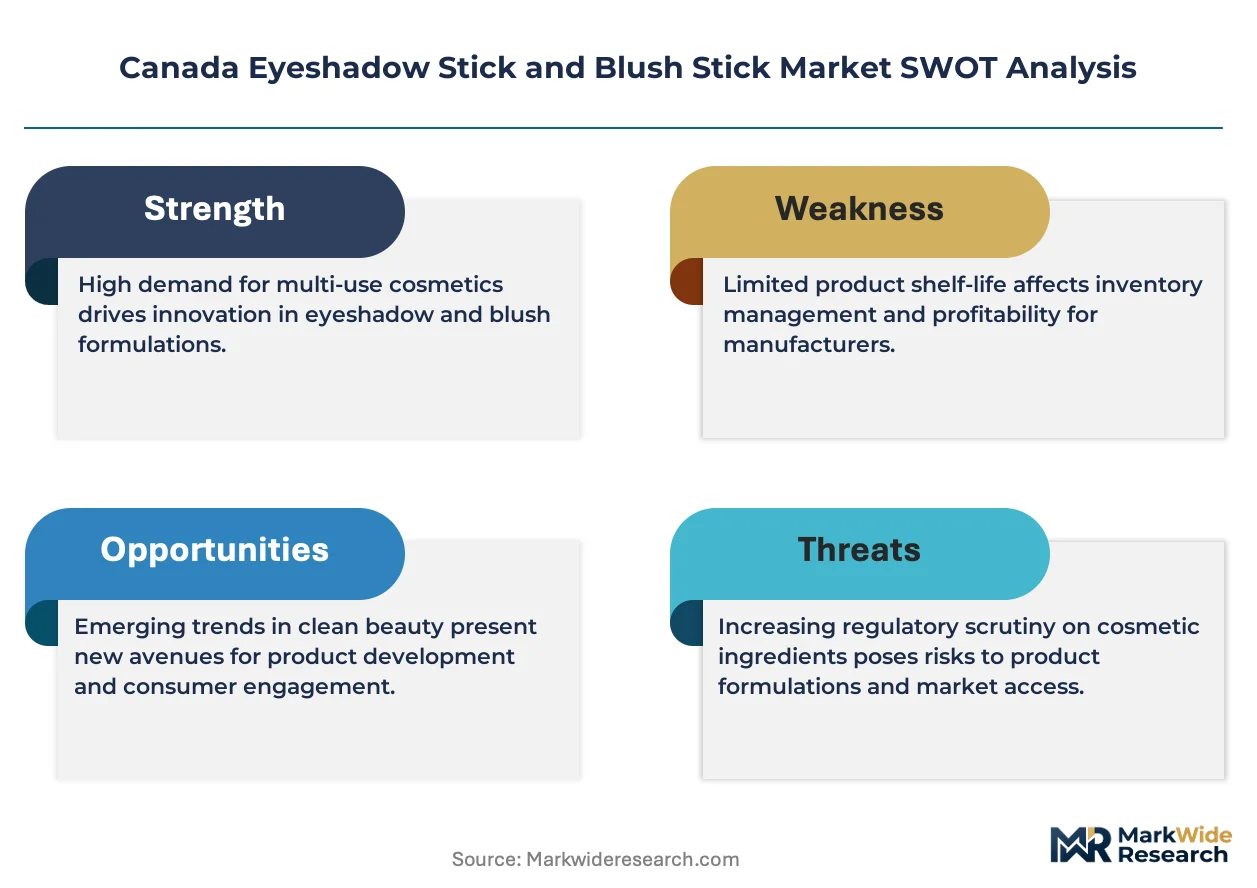
Health Canada's Cosmetic Regulations and provincial extended producer responsibility schemes are forcing reformulation and packaging redesign across Canadian stick cosmetics manufacturing, compressing product development timelines while elevating compliance costs for domestic and imported brands alike.
Growth Catalysts
- Millennial urban density:Toronto's retail corridors and Vancouver's beauty clusters concentrate demand for portable, brush-free formats. Young professionals prioritize convenience-driven application methods.
- Health Canada disclosure mandates:Ingredient transparency requirements under the Food and Drugs Act build consumer trust. Clean-label positioning gains traction among ingredient-conscious buyers.
- Gel stick technology:Transfer-resistant formulations address mask-compatible makeup routines. Professional channels adopt these products for extended-wear client applications.
Market Restraints
- Wax and oil input volatility:Petroleum-derived emollients and natural wax alternatives face price instability. Formulation cost pressures squeeze mid-tier brand margins.
- Asian manufacturing concentration:Packaging components and raw material precursors rely heavily on offshore supply chains. Lead time variability complicates Canadian inventory planning.
- Preservative restriction friction:PMRA oversight of antimicrobial safety limits formulation options. Reformulation cycles extend commercialization timelines for new product launches.
Strategic Opportunities
- British Columbia EPR leadership:Provincial extended producer responsibility schemes create first-mover advantages for recyclable packaging innovation. Brands investing in mono-material tubes capture regulatory goodwill.
- Professional makeup artist channels:Recurring bulk purchases by film, television, and bridal sectors offer stable revenue streams. These buyers prioritize pigment load over unit price.
- Microplastic-free mandates:Canadian Environmental Protection Act provisions accelerate biodegradable film-former adoption. Early compliance differentiates clean-positioned portfolios.
Industry Challenges
- Cosmetic chemist talent scarcity:Specialized expertise in solid-emulsion stability and wax-pigment dispersion commands premium compensation. Recruitment bottlenecks delay NPD timelines.
- Hotlist compliance complexity:Health Canada's evolving prohibited and restricted substance list requires continuous monitoring. Cross-border brands face dual-track regulatory maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Eyeshadow Stick and Blush Stick Market |
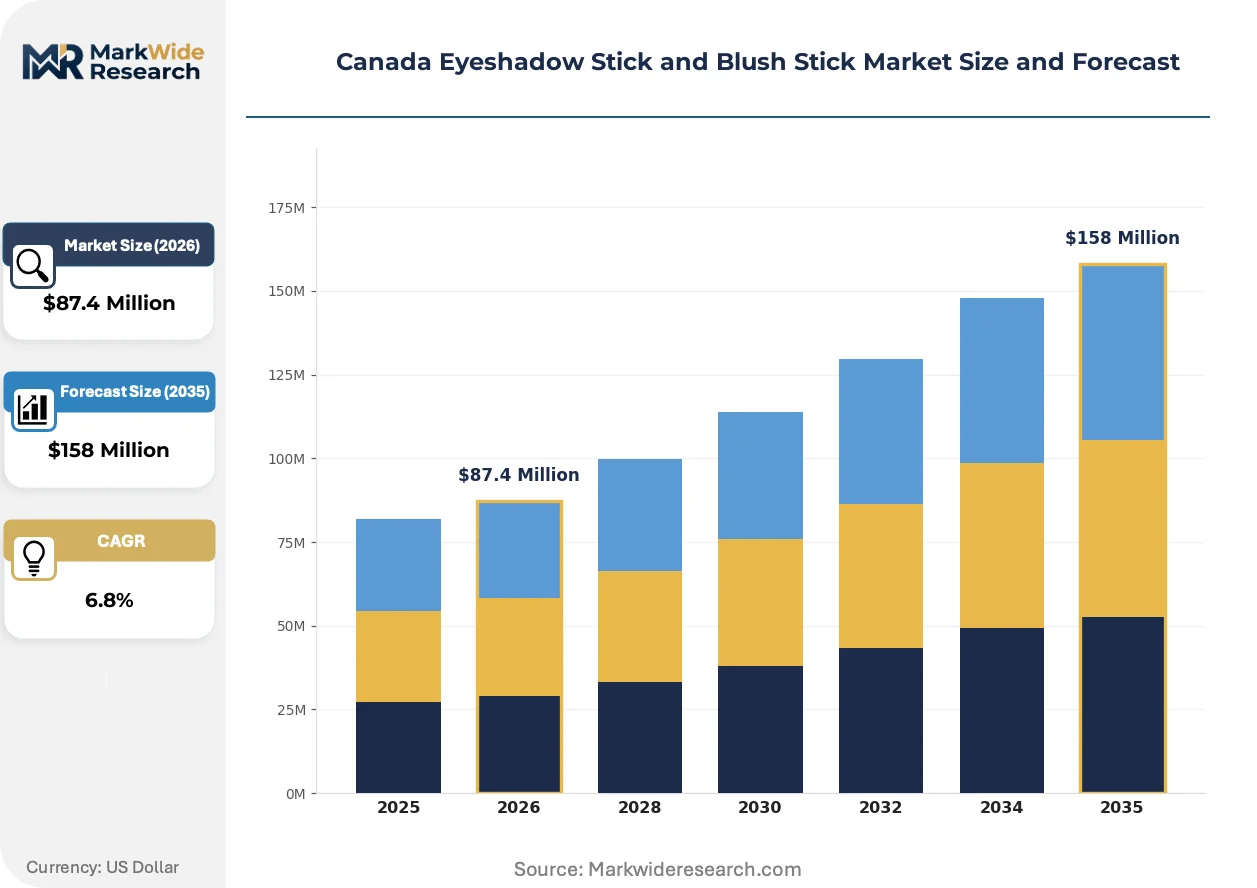
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Liquid, Pencil, Gel Target Customer: Teenagers, Millennials, Professionals, Makeup Artists Distribution Channel: Online Retail, Department Stores, Specialty Beauty Shops, Pharmacies Price Tier: Luxury, Affordable, Mid-range, Discount |
| Companies Covered | L'Oréal SA, Maybelline, Nyx Professional Makeup, Rimmel London, ELF Cosmetics, Revlon, Coty Inc., M.A.C Cosmetics, The Estée Lauder Companies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Eyeshadow Stick and Blush Stick Market Strategic Shifts
Canadian stick cosmetics are undergoing format and formulation convergence as climate-adaptive textures, regulatory-prompted ingredient substitution, and direct-to-consumer channel expansion reshape how products reach urban millennial buyers.
Silicone-free film-forming systems are consolidating market share as brands eliminate cyclopentasiloxane and similar volatile silicones from stick formulations. Ontario-based formulators accelerate adoption of plant-derived alternatives like pullulan and acacia senegal gum. This consolidation is compressing the competitive advantage window for legacy silicone-dependent portfolios.
Health Canada's microplastic-free mandates under the Canadian Environmental Protection Act are forcing substitution of polyethylene and nylon glitter in decorative sticks. Reformulation costs concentrate among mass-market brands with extensive shade ranges. British Columbia retailers are advancing compliance deadlines ahead of federal enforcement, creating uneven implementation timelines across provinces.
Specialty beauty shops in Toronto and Vancouver are displacing department store counters as the primary discovery channel for prestige stick formats. Younger buyers prefer curated retail environments with tester accessibility over traditional service-counter models. This channel rotation is most pronounced in urban cores where experiential retail investments concentrate.
Canada Eyeshadow Stick and Blush Stick Market Segmentation
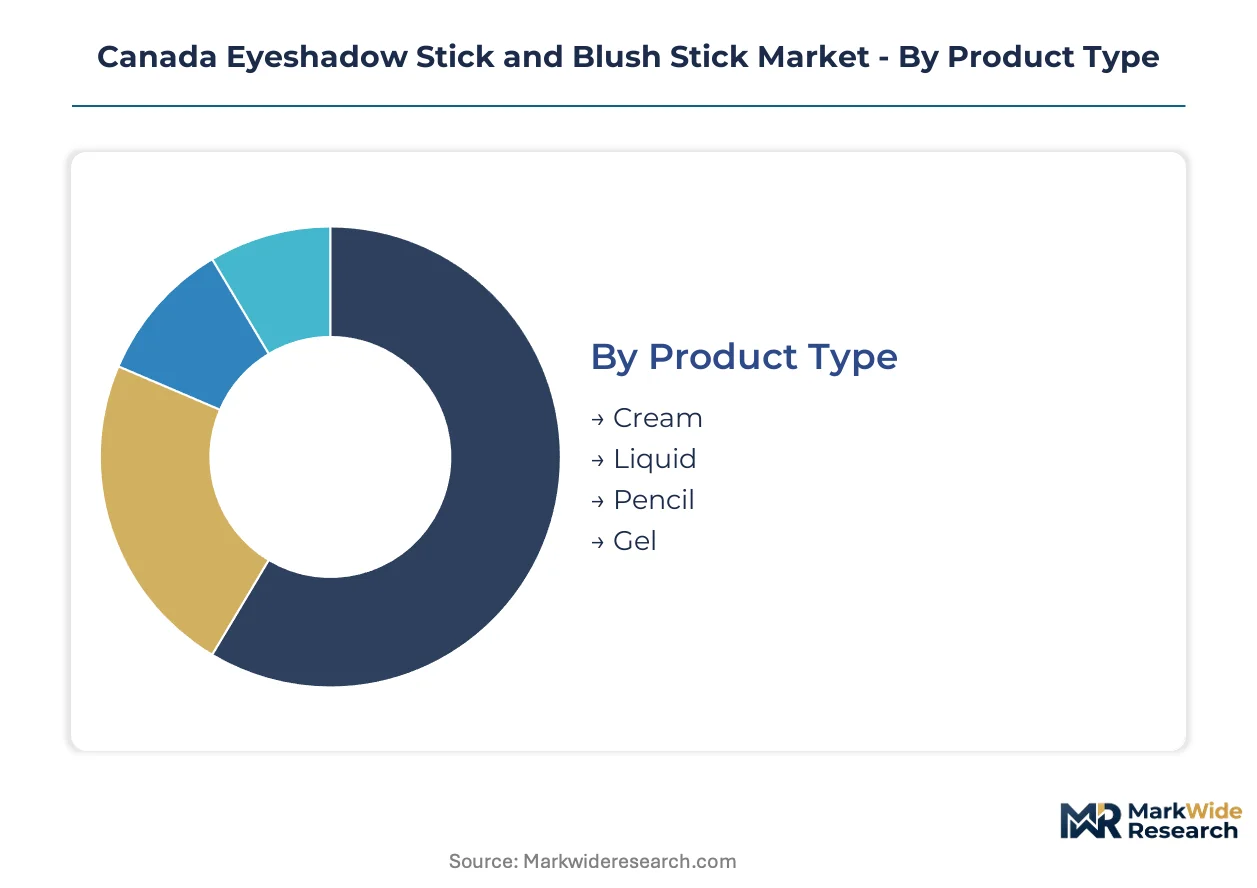
Stick-format cosmetics in Canada fragment across formulation chemistry, buyer lifecycle stage, and retail channel economics. Each segmentation dimension reveals distinct margin structures and regulatory exposure profiles that shape portfolio strategy for domestic and imported brands.
Product Type:
Cream formulations dominate shelf space in Toronto and Vancouver retail corridors due to their forgiving blendability in dry winter conditions.
- Cream:Wax-oil emulsion bases with moderate pigment load suit everyday consumers seeking one-swipe application without primer dependency. Demand concentrates in Ontario's mass-market retail chains where convenience buyers prioritize speed over longevity.
- Liquid:Higher solvent content enables fluid dispersion of metallic and shimmer pigments for editorial and bridal applications. Professional makeup artists in Vancouver's film production cluster drive recurring bulk procurement of these formats for set-ready durability.
- Pencil:Traditional wood-cased or mechanical formats with firmer wax matrices target precision lining and detailed work. These legacy formats retain niche loyalty among mature demographics in Quebec's pharmacy channels.
- Gel:Silicone-free film-forming systems deliver transfer-resistant wear aligned with Health Canada's microplastic-free mandates. Younger buyers in British Columbia's specialty beauty shops gravitate toward these formats for mask-compatible daily routines.
Volume sits with Cream; growth tilts toward Gel.
Target Customer:
Buyer maturity and professional credential status determine price elasticity and repurchase frequency across Canadian provinces.
- Millennials:Urban professionals aged 28-43 in Toronto and Vancouver drive the bulk of prestige stick purchases through curated discovery experiences. This cohort's ingredient literacy pressures brands to maintain Hotlist compliance and transparent sourcing claims.
- Makeup Artists:Certified professionals serving film, television, and bridal markets in Montreal and Calgary command wholesale pricing through recurring bulk orders. Their technical specifications prioritize pigment concentration and flash photography compatibility over unit cost.
- Teenagers:Entry-level buyers entering cosmetics through social media discovery and pharmacy impulse purchases. Price sensitivity limits average transaction values despite high trial rates.
- Professionals:Non-creative white-collar workers seeking polished appearance maintenance with minimal application time. This segment underindexes in stick-format adoption relative to Millennials.
Revenue concentrates with Makeup Artists; expansion opportunity sits with Millennials.
Distribution Channel:
Channel selection dictates packaging compliance burden and tester accessibility policy under Health Canada's Cosmetic Regulations.
- Specialty Beauty Shops:Curated Toronto and Vancouver storefronts with open-sell tester bars displace traditional service counters for prestige discovery. These venues absorb higher packaging costs to meet British Columbia's advancing extended producer responsibility deadlines.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture convenience-driven replenishment purchases. Virtual try-on tools reduce return rates for shade-sensitive stick products.
- Department Stores:Legacy counter models with assisted service retain loyal older demographics in Calgary and Ottawa. Foot traffic compression limits new customer acquisition efficiency.
- Pharmacies:Mass-market access points in suburban Ontario and Quebec corridors drive impulse trial of affordable-tier sticks. Regulatory compliance costs concentrate here due to inventory breadth requirements.
Margin pools concentrate in Specialty Beauty Shops; volume expansion tilts toward Online Retail.
Price Tier:
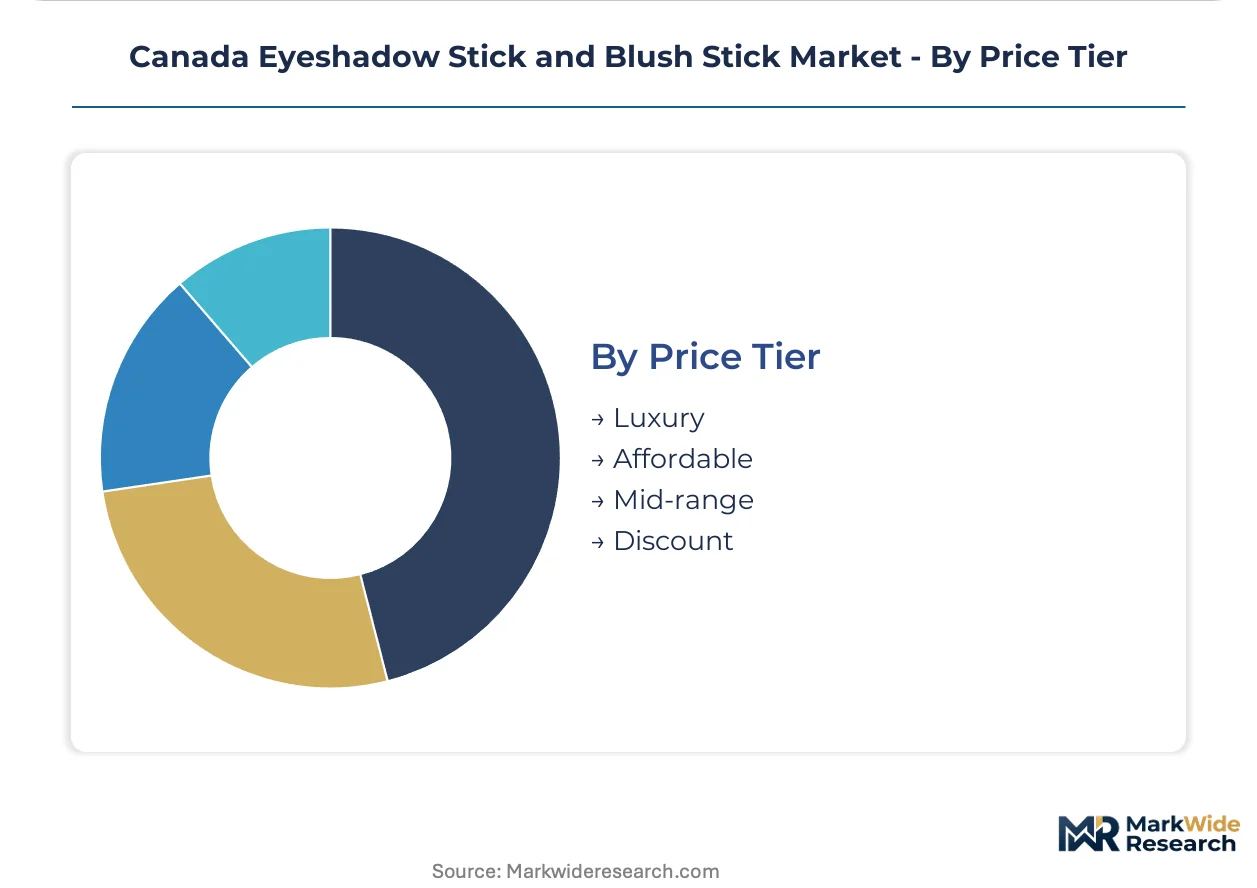
Pricing architecture separates ingredient provenance claims, packaging material grades, and retail service intensity across the Canadian market.
- Luxury:Prestige positioning with mono-material or refillable tubes targeting sustainability-conscious urban buyers. These products command shelf space in Vancouver's Yaletown and Toronto's Yorkville corridors.
- Affordable:Clean-ingredient positioning at accessible price points dominates ELF Cosmetics and similar challenger brand strategies. Younger Canadian buyers validate this tier's growth trajectory.
- Mid-range:Compromised value proposition struggling to differentiate against flanking luxury and affordable alternatives. Distribution consolidation pressures this tier most severely.
- Discount:Price-driven procurement with minimal formulation innovation, concentrated in private-label pharmacy offerings and off-price retail channels.
Profitability clusters in Luxury; unit velocity concentrates in Affordable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto's urban retail corridors concentrate the bulk of Canadian stick cosmetics demand, with Yorkville and Queen Street West hosting flagship discovery venues for prestige formats. Vancouver's Yaletown and Robson Street clusters anchor West Coast volume, while Montreal's Plateau-Mont-Royal sustains Quebec's professional makeup artist procurement channels. Provincial regulatory divergence is accelerating between Ontario's federal-aligned enforcement and British Columbia's advancing extended producer responsibility deadlines.
Ontario
Millennial professionals in Toronto's financial district drive prestige stick purchases through curated specialty beauty shops. Health Canada's Cosmetic Regulations under the Food and Drugs Act mandate ingredient disclosure that shapes product development cycles for brands distributing through Ontario's mass-market retail chains. The Greater Toronto Area concentrates formulation R&D talent and packaging innovation labs serving domestic and imported brands alike.
British Columbia
Vancouver's film production cluster generates recurring bulk procurement from makeup artists seeking high-pigment liquid sticks for set-ready durability. Provincial extended producer responsibility schemes are advancing compliance deadlines ahead of federal enforcement, forcing packaging redesign investments. Yaletown specialty retailers are displacing traditional department store counters as the primary discovery channel for gel-format transfer-resistant products.
Quebec
Montreal's bridal and editorial makeup sectors sustain professional-channel demand for cream and liquid stick formulations. ANSM-aligned provincial enforcement of cosmetic safety standards operates alongside Health Canada mandates, creating dual-track compliance requirements for cross-border brands. The Plateau-Mont-Royal district hosts independent beauty boutiques that prioritize European-imported stick formats with clean-ingredient positioning.
Alberta
Calgary's energy sector professionals underindex in stick-format adoption relative to coastal urban centers, though department store counters retain loyal older demographics. Provincial retail consolidation is compressing mid-tier brand shelf space in favor of luxury and affordable-tier alternatives. The city's bridal makeup artist community sources bulk liquid sticks through professional supply distributors rather than direct retail channels.
Canada Eyeshadow Stick and Blush Stick Market Competitive Environment
Capital-heavy prestige houses compete with asset-light challenger brands across Canada's stick cosmetics sector. The market structure consolidates around dual-brand architectures spanning luxury and accessible tiers, with portfolio diversification and packaging compliance investments serving as dominant competitive moves. Strategic archetypes include multinational conglomerates with regulatory compliance infrastructure, clean-positioned challengers competing on price-accessibility, and professional-channel specialists capturing recurring bulk orders.
Within the multinational tier, L'Oréal SA and The Estée Lauder Companies Inc. anchor Canadian market presence through established distribution relationships with Toronto and Vancouver retail corridors. ELF Cosmetics occupies the affordable-tier challenger position, sustaining clean-ingredient positioning that resonates with younger Canadian buyers entering the category through social media discovery.
| Leading Market Players |
|---|
| L'Oréal SA |
| Maybelline |
| Nyx Professional Makeup |
| Rimmel London |
| ELF Cosmetics |
| Revlon |
| Coty Inc. |
| M.A.C Cosmetics |
| The Estée Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Health Canada's microplastic-free mandates under the Canadian Environmental Protection Act gate qualified supply and premium-tier pricing access, forcing brands to source biodegradable film-formers and mono-material packaging to capture margin pools in British Columbia's advancing extended producer responsibility corridors.
Pricing Analysis
Value-based pricing anchored to transfer-resistant wear duration dominates gel stick premiums, with pigment load and silicone-free certification tier separating luxury mono-material tubes from affordable-tier alternatives. Price differentiation rests on Health Canada Hotlist compliance status and refillable packaging grades. Cost compression in mid-range wax-oil emulsions is intensifying because petroleum-derived input volatility squeezes formulation budgets. Teenage pharmacy buyers exhibit highest price sensitivity, while certified makeup artists prioritize yield-per-application over unit cost.
Supply Chain Analysis
British Columbia's provincial extended producer responsibility schemes are reshaping sourcing toward domestic packaging innovation labs and recyclable mono-material tube suppliers. Raw material procurement draws from China for wax and pigment precursors, South Korea for silicone-free film-forming polymers, and domestic Ontario labs for clean-label formulation R&D. Single-source vulnerability concentrates in Asian packaging component supply. Distribution runs through Toronto and Vancouver specialty beauty shops for prestige discovery, with online retail capturing replenishment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around packaging compliance investments and formulation chemist expertise, with Health Canada's evolving Hotlist forcing undercapitalized mid-tier brands toward exit or acquisition.
For Market Incumbents: Hedge against silicone-free substitution acceleration by securing captive supply of plant-derived film-formers through backward integration into Ontario-based biopolymer suppliers. Deepen channel control in Vancouver's Yaletown specialty retail cluster before British Columbia's EPR deadlines compress competitor response windows. Prioritize R&D investment in gel-stick stability to defend professional makeup artist bulk procurement relationships.
For New Entrants and Emerging Players: Specialty beauty shop buyers in Toronto's Queen Street West corridor offer the most penetrable white-space entry point for clean-positioned affordable-tier challengers. Target millennial urban professionals seeking mask-compatible transfer-resistant formats with social media-native discovery tactics. Deploy direct-to-consumer sampling programs to bypass department store counter infrastructure costs.
For Investors and Strategic Acquirers: British Columbia's advancement of extended producer responsibility enforcement deadlines ahead of federal timelines is the leading indicator that packaging compliance infrastructure will separate viable acquisition targets from stranded assets. Long-term viability favors brands with in-house formulation R&D and mono-material tube supply agreements. Watch for Health Canada Hotlist expansion announcements as the inflection signal for accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | British Columbia's EPR schemes reward early recyclability compliance with regulatory goodwill and shelf access. |
| Silicone-Free Formulation R&D | Health Canada's microplastic-free mandates under the Canadian Environmental Protection Act accelerate pullulan and acacia senegal gum adoption. |
| Professional Channel Bulk Supply Agreements | Vancouver's film production cluster and Montreal's bridal sectors lock in recurring high-margin procurement. |
| Direct-to-Consumer Platform Launch | Virtual try-on tools reduce shade-mismatch returns for pigment-sensitive stick products. |
| Clean-Ingredient Certification Investment | Transparent Hotlist compliance builds millennial trust in Ontario and British Columbia urban corridors. |
Study Parameters
Independent corroboration across Health Canada regulatory filings, provincial extended producer responsibility documentation, and specialty beauty shop inventory audits underwrites the qualitative findings. Primary interviews with cosmetic formulators, packaging compliance officers, category buyers at Toronto and Vancouver retailers, and professional makeup artists serving film and bridal markets combined with secondary validation from customs trade data, Nielsen retail audit records, and PMRA preservative safety assessments. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to pre-pandemic baseline consumption patterns established the forecast trajectory across the analysis window. The analytical framework models segmentation dimensions spanning formulation chemistry, buyer lifecycle stage, distribution channel economics, and price tier positioning. CAGRs derive from trend extrapolation calibrated to regulatory implementation timelines and urban millennial population density shifts. Industry-specific inputs include Health Canada Hotlist revision schedules and British Columbia EPR compliance cost curves.
Caveats apply where Health Canada regulatory acceleration or petroleum-derived input price spikes could materially shift the outlook. Forecasts reflect assumptions around provincial EPR harmonization and silicone-free technology adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
North America Jojoba Oil Market