
 Cosmetic Kaolin Powder Market | 2026-2036
Cosmetic Kaolin Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Kaolin Powder Market Outlook
Talc is decoupling from premium cosmetic formulations across multiple product categories as safety litigation and reformulation mandates accelerate. Imerys leverages captive mining assets in Georgia and Cornwall to secure high-brightness reserves for cosmetic clients. KaMin LLC anchors North American supply through integrated beneficiation plants that sustain consistent particle size distribution. Sibelco competes on European logistics density, positioning its Czech and Ukrainian operations to serve color cosmetic houses with minimal lead times.
Cosmetic kaolin powder is a refined aluminum silicate clay processed to sub-10 micron particle size with controlled brightness above 85 ISO and minimal heavy metal content below 20 ppm lead; manufacturers calcine or surface-treat raw ore to enhance oil absorption and rheological stability for skin-contact applications. Modified kaolin variants command margin premiums as cosmetic manufacturers seek engineered opacity and sebum control in powder makeup formulations. Natural kaolin retains volume leadership in facial masks where consumers associate untreated clay with authenticity, though colored clay from Brazilian deposits is gaining traction in body care lines targeting visual differentiation.
REACH registration through ECHA and FDA color additive regulations under 21 CFR 73.1010 govern cosmetic kaolin purity, with the former mandating full toxicological dossiers and the latter capping arsenic and lead thresholds that directly determine which mines qualify for personal care supply. ISO 16128 natural origin criteria and emerging state-level clean beauty legislation in California and New York are layering additional compliance burdens that favor suppliers with dedicated cosmetic-grade processing circuits. Stakeholders must monitor how biotech-derived alternatives to mineral clays evolve before committing to long-term kaolin offtake agreements.
Market Dynamics
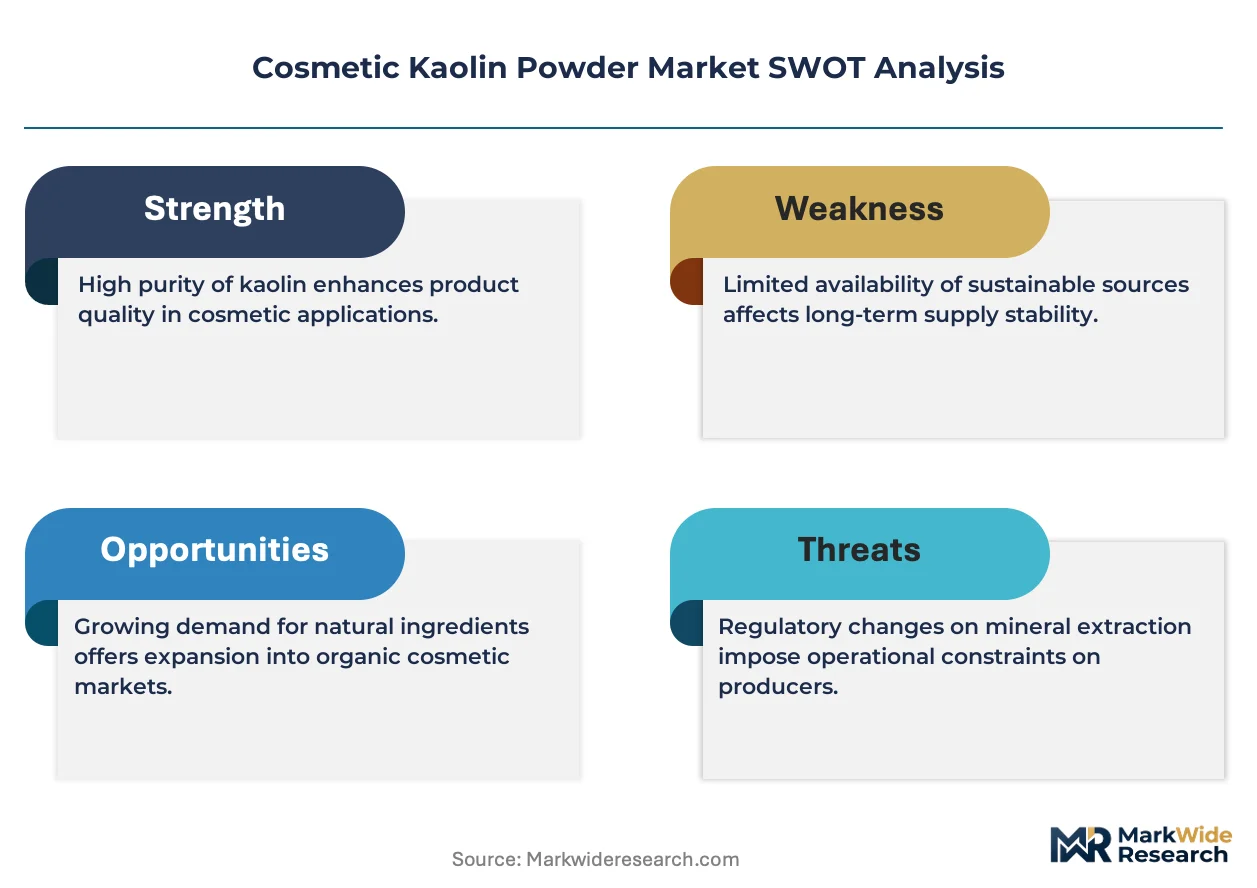
Clean beauty certification requirements are fragmenting supplier qualification criteria across cosmetic kaolin markets, forcing miners to maintain parallel processing circuits for ISO 16128 natural origin claims versus conventional pharmaceutical-grade streams.
Growth Catalysts
- French laboratory clustering:Provence-based cosmetic formulators anchor premium sourcing relationships that pull high-brightness reserves through dedicated supply chains.
- REACH registration depth:ECHA toxicological dossier requirements create defensible moats for incumbent suppliers with existing cosmetic-grade circuits.
- Calcination technology:Surface-modified kaolin variants command margin premiums by delivering engineered opacity in powder makeup formulations.
Market Restraints
- Input cost volatility:Energy-intensive calcination processes expose margins to natural gas price swings at Georgia and Cornish processing facilities.
- Supply concentration risk:Premium cosmetic-grade reserves cluster in specific Georgia deposits and Ukrainian extraction zones, creating geographic vulnerability.
- Substitution pressure:Biotech-derived alternatives to mineral clays threaten long-term offtake commitments as formulators trial fermentation-based sebum control agents.
Strategic Opportunities
- Brazilian colored clay:Untapped deposits in Minas Gerais offer visual differentiation for body care lines targeting Instagram-driven aesthetic rituals.
- California clean beauty legislation:State-level disclosure mandates create first-mover advantages for suppliers with pre-positioned heavy metal testing protocols.
- Direct-to-formulator platforms:Digital procurement channels bypass traditional distributor markups for mid-sized cosmetic houses seeking traceable sourcing.
Industry Challenges
- Beneficiation skill scarcity:Particle size distribution expertise concentrates among aging engineers at integrated Georgia plants, complicating workforce succession.
- Dual certification timelines:Parallel FDA color additive and REACH dossier preparation stretches qualification cycles to 18-24 months for new mine entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Kaolin Powder Market |
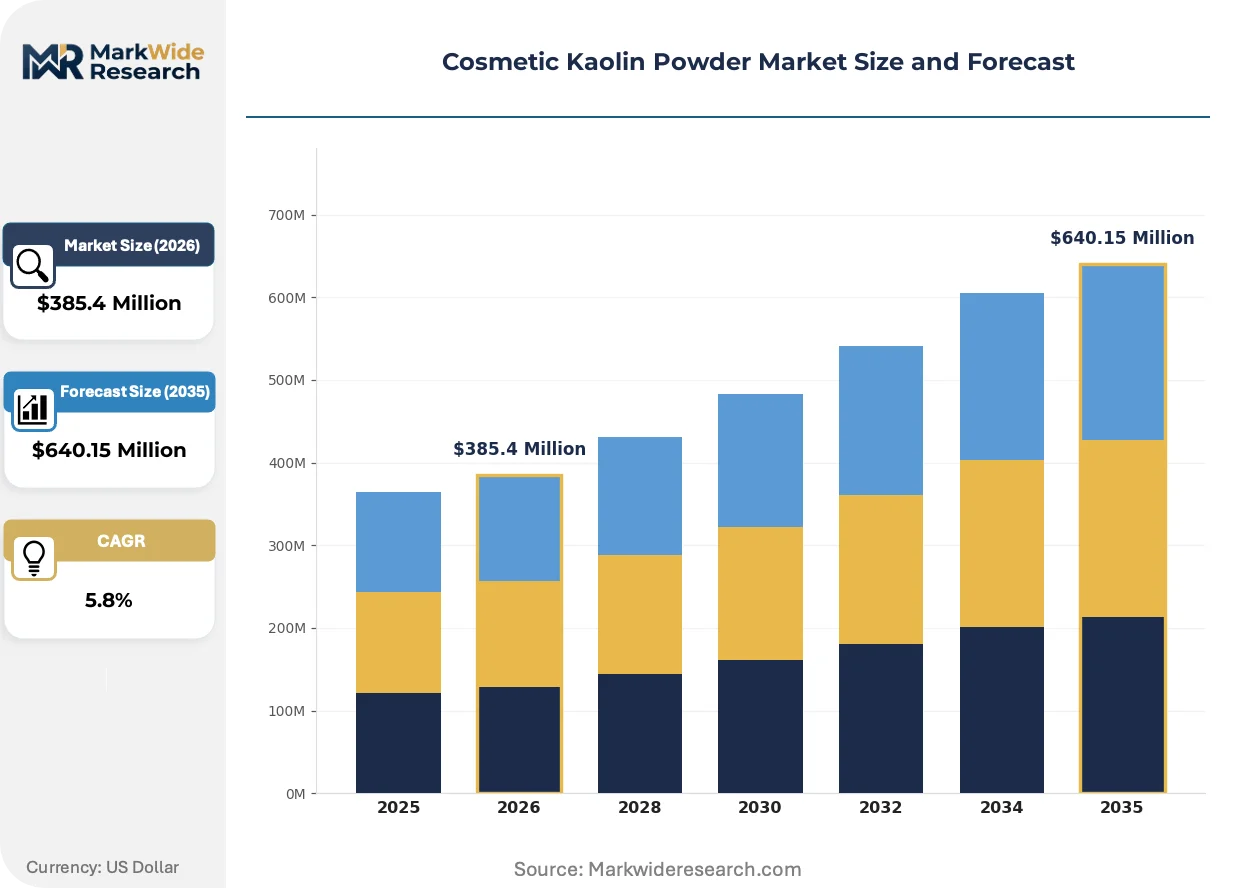
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Kaolin, White Clay, Colored Clay, Modified Kaolin Application: Facial Masks, Powder Makeup, Cleansers, Body Care End User: Cosmetic Manufacturers, Private Label Brands, Retailers, Spa Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Imerys, KaMin LLC, BASF SE, Sibelco, Thiele Kaolin Company, Ashapura Group, Quarzwerke Group, EICL Limited, Sedlecky Kaolin A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Kaolin Powder Market Strategic Shifts
Surface engineering and digital traceability are converging to reshape how cosmetic kaolin suppliers defend premium positioning against commodity clay alternatives.
Laser diffraction particle analysis paired with automated beneficiation control is automating quality consistency at Cornish and Czech processing facilities. Mid-sized color cosmetic houses now specify sub-2 micron median particle size with coefficient of variation below 15 percent, compressing tolerance bands that previously accommodated broader distribution curves. This precision is automating the displacement of manual screening operations while raising capital barriers for smaller miners.
REACH authorization list expansion through ECHA is tightening heavy metal thresholds for cosmetic-grade kaolin beyond FDA 21 CFR 73.1010 baselines. Suppliers must now document full supply chain custody from mine face to formulation facility, increasing compliance overhead disproportionately for traders versus integrated miners. French and German cosmetic houses are responding by consolidating supplier panels to three qualified sources maximum.
Ingredient transparency platforms are reshaping procurement rituals for clean beauty formulators. Sephora and Ulta clean beauty seals now require batch-level heavy metal certificates, displacing annual composite testing that previously sufficed. This verification intensity concentrates demand among suppliers with in-house ICP-MS laboratories, visible most acutely in California and New York brand development pipelines.
Cosmetic Kaolin Powder Market Segmentation
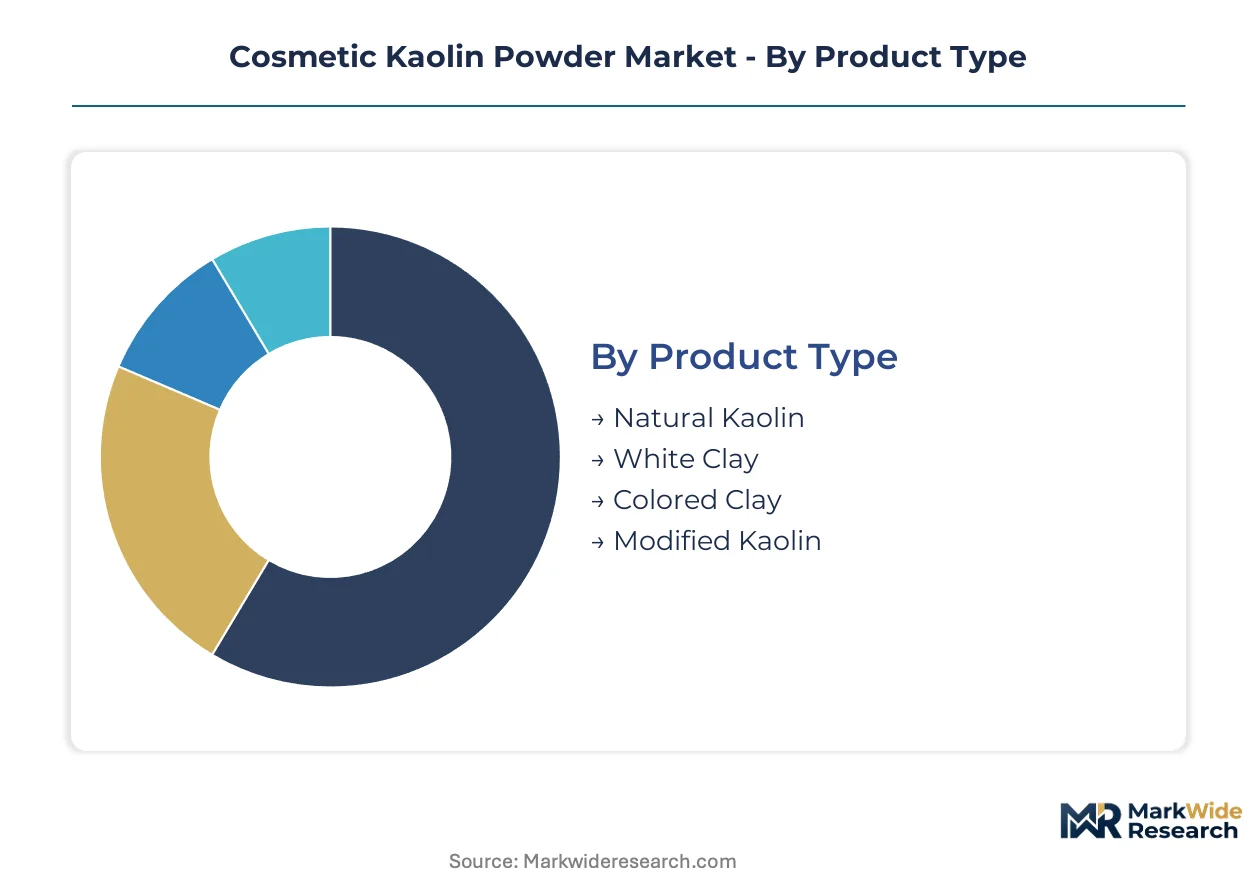
Cosmetic kaolin powder segmentation reflects divergent purity requirements across product categories and the tension between untreated clay authenticity and engineered performance. Formulators select grades based on end-use contact duration, visual opacity needs, and clean beauty certification demands.
Product Type:
Natural kaolin operates as a standalone ingredient in rinse-off applications, while modified variants embed into complex formulations requiring rheological precision.
- Natural Kaolin:Untreated aluminum silicate clay retains crystalline structure and trace mineral content. Facial mask producers in France specify natural grades for consumer-perceived authenticity, though batch-to-batch color variation complicates quality control.
- Modified Kaolin:Surface-treated or calcined variants deliver engineered oil absorption and controlled opacity. Powder makeup manufacturers pay premiums for sub-2 micron particle sizes with consistent brightness above 90 ISO.
- White Clay:High-brightness kaolin from Georgia deposits serves as the baseline for cosmetic-grade specifications. REACH dossiers favor white clay for its documented toxicological history.
- Colored Clay:Iron-rich deposits from Brazilian Minas Gerais provide visual differentiation for body care lines targeting Instagram-driven aesthetic rituals.
Natural kaolin leads volumes today; modified kaolin is gaining share fastest.
Application:
Application segmentation tracks skin contact duration, with leave-on powder makeup demanding the strictest heavy metal thresholds.
- Facial Masks:Rinse-off clay treatments tolerate broader particle size distribution. Provence-based formulators anchor demand for authentic, untreated kaolin in wash-off rituals.
- Powder Makeup:Leave-on applications require sub-10 micron particles with lead content below 10 ppm. FDA 21 CFR 73.1010 compliance separates qualified suppliers from commodity traders.
- Cleansers:Mild exfoliation formulations use coarser kaolin fractions. Suspension stability requirements drive specification of calcined grades.
- Body Care:Lower price sensitivity permits colored clay experimentation. Brazilian deposits supply visual differentiation for premium body mask lines.
Facial masks dominate current volumes; powder makeup shows the steepest expansion trajectory.
End User:
End user segmentation reveals a split between integrated manufacturers with dedicated cosmetic-grade circuits and private label brands dependent on distributor relationships.
- Cosmetic Manufacturers:L'Oréal and Estée Lauder subsidiaries maintain three-supplier panels maximum. ECHA REACH dossier requirements favor incumbents with existing cosmetic-grade processing infrastructure.
- Private Label Brands:Ulta and Sephora clean beauty seals require batch-level heavy metal certificates. Smaller brands lack capital for in-house ICP-MS testing capabilities.
- Retailers:Clean beauty disclosure mandates in California and New York force retailer-side specification of traceable sourcing.
- Spa Services:Professional treatment lines prioritize visual differentiation over pharmaceutical-grade purity. Colored clay from Ukrainian deposits serves this price-sensitive channel.
Cosmetic manufacturers command the largest volume share; private label brands are climbing the fastest.
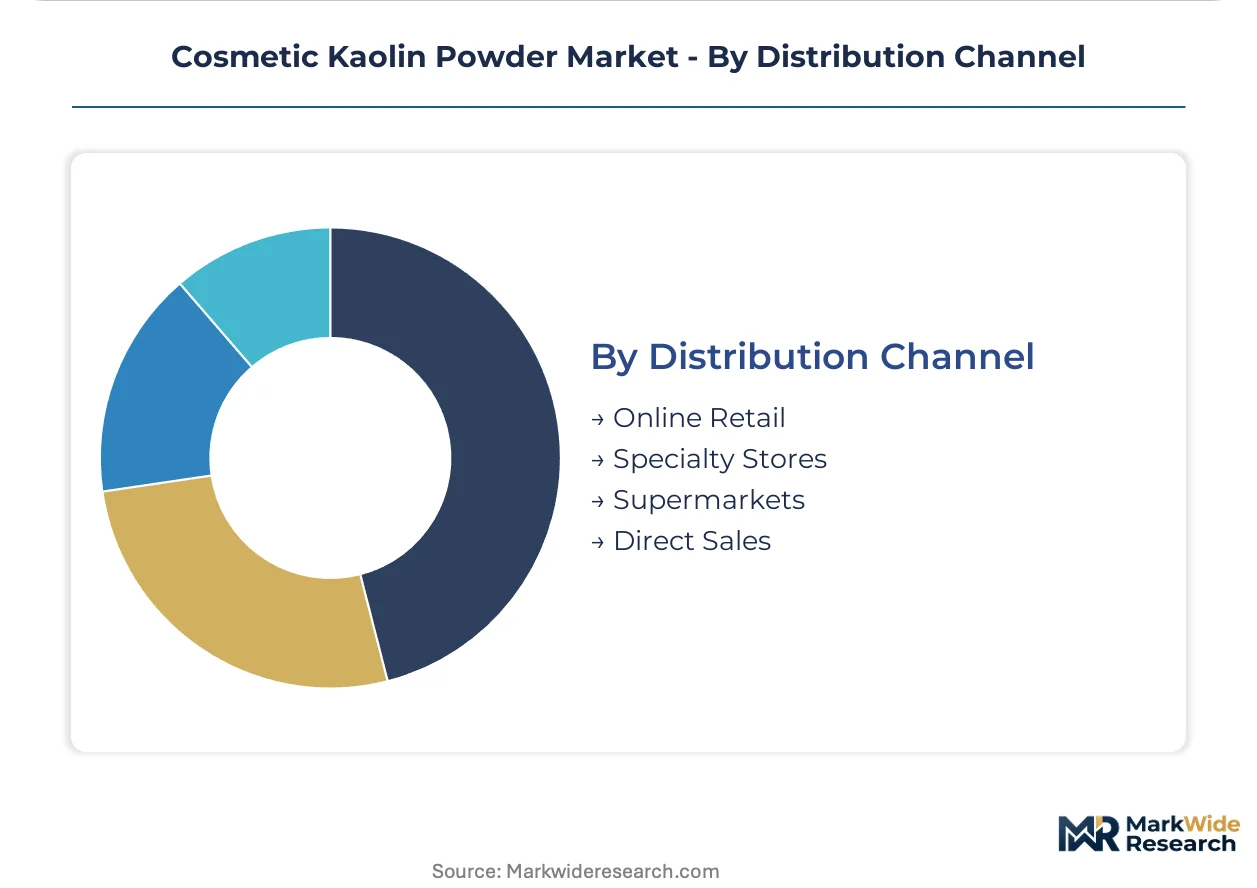
Distribution Channel:
Channel segmentation tracks procurement ritual transformation, with digital platforms compressing traditional distributor markups.
- Online Retail:Direct-to-formulator platforms bypass traditional chemical distributor networks. Mid-sized cosmetic houses in California leverage digital channels for traceable sourcing documentation.
- Specialty Stores:Ingredient transparency platforms consolidate demand among suppliers with pre-positioned heavy metal testing protocols. Sephora clean beauty seals drive specification intensity.
- Supermarkets:Mass-market cosmetic lines prioritize cost over certification depth. Commodity kaolin traders serve this channel with annual composite testing.
- Direct Sales:Integrated miners like Imerys and KaMin LLC maintain direct relationships with top-tier cosmetic houses. Captive mining assets in Georgia secure volume commitments.
Specialty stores anchor current procurement patterns; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence-based cosmetic laboratories anchor premium sourcing relationships that pull high-brightness reserves through dedicated supply chains. France concentrates demand for untreated kaolin in facial mask formulations. REACH compliance through ECHA tightens purity benchmarks across European markets.
France
Provence-Alpes-Côte d'Azur hosts the densest cluster of cosmetic formulators specifying natural kaolin for rinse-off clay treatments. ANSM and ECHA REACH dossier requirements favor suppliers with documented toxicological histories. Grasse-based laboratories maintain three-supplier panels maximum, consolidating procurement around established cosmetic-grade circuits.
United States
California clean beauty legislation and New York disclosure mandates drive batch-level heavy metal certificate requirements. FDA color additive regulations under 21 CFR 73.1010 cap arsenic and lead thresholds that determine mine qualification for personal care supply. Georgia deposits sustain integrated beneficiation plants serving mid-sized cosmetic houses through direct-to-formulator digital channels.
Brazil
Minas Gerais iron-rich deposits supply visual differentiation for body care lines targeting Instagram-driven aesthetic rituals. ANVISA governs cosmetic ingredient safety with evolving purity standards that colored clay producers must navigate. Domestic formulators experiment with untreated variants where consumer-perceived authenticity outweighs pharmaceutical-grade specifications.
Ukraine
Czech and Ukrainian extraction zones serve European color cosmetic houses with minimal lead times through Sibelco's logistics density. ECHA REACH registration creates defensible moats for incumbent suppliers with existing cosmetic-grade processing infrastructure. Spa services channels prioritize visual differentiation over purity, absorbing price-sensitive volumes from regional deposits.
China
Yangtze River Delta cosmetic manufacturers source modified kaolin variants for powder makeup formulations requiring engineered opacity. NMPA and GB standards layer compliance requirements atop international benchmarks for export-oriented production. Shandong Peninsula processing facilities automate laser diffraction particle analysis to meet sub-2 micron median specifications.
Cosmetic Kaolin Powder Market Competitive Environment
Global majors compete with regional champions across integrated mining and beneficiation capabilities. The supplier base stratifies between captive reserve holders with dedicated cosmetic-grade circuits and commodity traders serving mass-market channels. Three archetypes dominate: integrated miners controlling Georgia and Cornish reserves, European logistics specialists with dense distribution networks, and Asian diversified chemical conglomerates with surface-modification expertise. Capacity expansion and REACH dossier depth constitute the primary competitive moves.
Within the integrated miner tier, Imerys and KaMin LLC exemplify archetypes built on captive Georgia reserves and consistent particle size distribution. Sibelco occupies a position among European logistics specialists leveraging Czech and Ukrainian proximity to color cosmetic houses. BASF SE represents the diversified chemical conglomerate archetype with surface-treatment capabilities for engineered opacity applications.
| Leading Market Players |
|---|
| Imerys |
| KaMin LLC |
| BASF SE |
| Sibelco |
| Thiele Kaolin Company |
| Ashapura Group |
| Quarzwerke Group |
| EICL Limited |
| Sedlecky Kaolin A.S. |
| Others |
Value Chain & Pricing Dynamics
Captive mining assets in Georgia and Cornwall anchor supply positions for integrated kaolin processors, creating pricing power through controlled high-brightness reserve access that commodity traders cannot replicate. This upstream consolidation allows Imerys and KaMin LLC to command margin premiums on cosmetic-grade specifications while passing through selective input cost movements to formulation clients.
Pricing Analysis
Natural gas price volatility at calcination facilities in Georgia and Cornwall feeds directly into modified kaolin pricing, with surface-treated variants absorbing sharper cost movements than untreated natural grades. Three-tier pricing structure across premium REACH-registered, standard FDA-compliant, and economy-grade cosmetic tiers separates qualified suppliers from commodity traders. Cost compression in the economy tier intensifies because Brazilian and Ukrainian entrants compete on volume without certification depth. Private label brands at Sephora and Ulta show highest price sensitivity, while L'Oréal subsidiaries accept premiums for batch-level heavy metal documentation.
Supply Chain Analysis
Regional distribution centers in Provence-Alpes-Côte d'Azur, New Jersey, and São Paulo anchor hub-and-spoke patterns that position inventory within 48-hour reach of cosmetic formulators. Geographic supply concentration centers on Georgia deposits, Cornish reserves, and Ukrainian extraction zones, with Brazilian Minas Gerais emerging for colored clay differentiation. Raw material dependencies rest on high-brightness ore quality, natural gas for calcination energy, and specialized flocculants for beneficiation precision. Single-source vulnerability from Georgia's dominance of premium cosmetic-grade reserves threatens continuity during extreme weather events. Distribution runs through integrated miner direct sales for top-tier houses, with chemical distributors serving mid-market brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic kaolin powder market represents a late-cycle quality story as facial mask and powder makeup formulators shift toward sub-2 micron specifications with documented REACH dossiers. Premium positioning now requires batch-level traceability that commodity traders cannot deliver.
For Market Incumbents: Cement defensible positioning by deepening captive reserve control through exclusive offtake agreements with Georgia mine operators facing workforce succession risks. Accelerate in-house ICP-MS laboratory deployment to capture batch-certificate demand from California clean beauty legislation, locking out traders lacking capital for testing infrastructure.
For New Entrants and Emerging Players: Begin with Brazilian colored clay specialization targeting body care lines where Instagram-driven aesthetic rituals tolerate broader purity specifications. Direct-to-formulator digital platforms offer the most penetrable channel angle, bypassing distributor markups that incumbent integrated miners maintain through relationship inertia with top-tier houses.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized beneficiation specialists because ECHA REACH registration creates 18-24 month qualification moats that deter new mine entrants. Target processing facilities with existing cosmetic-grade circuits and aging engineering talent pools. Watch biotech-derived sebum control agent trial results as the inflection signal threatening long-term mineral clay offtake commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Secures Georgia high-brightness reserves against competitor offtake and supply disruption. |
| REACH Dossier Expansion | ECHA toxicological documentation creates 18-24 month barriers for unqualified new entrants. |
| In-House ICP-MS Laboratory Buildout | Batch-level heavy metal certificates satisfy Sephora and Ulta clean beauty seal requirements. |
| Direct-to-Formulator Digital Platform | Bypasses chemical distributor markups for mid-sized California cosmetic houses seeking traceability. |
| Brazilian Colored Clay Capacity Addition | Minas Gerais iron-rich deposits capture Instagram-driven body care aesthetic differentiation demand. |
Study Parameters
Bottom-up cosmetic formulation modeling reconciled against top-down kaolin supply tracking forms the analytical core of this study. Primary interviews with cosmetic R&D directors, regulatory affairs specialists at ECHA-registered suppliers, procurement leads at French laboratory clusters, and beneficiation plant engineers informed demand and supply assumptions. Secondary validation drew from FDA color additive filings, ECHA REACH registration databases, customs trade records, and SEC disclosures from integrated mining companies. Triangulation between end-use consumption estimates and mine production capacity assessments anchored volume integrity.
Historical trendline analysis across natural and modified kaolin price trajectories informed projection frameworks throughout the forecast period. Segmentation modeling captured product type tiers, application contact-duration requirements, end-user integration levels, and distribution channel procurement patterns. CAGRs derived from regression analysis against facial mask and powder makeup formulation growth, with specific inputs including clean beauty certification penetration rates and calcination capacity utilization at Georgia processing facilities.
Several conditions sit outside the modeled scope, including potential REACH authorization list expansions beyond current heavy metal thresholds and commercialization timelines for biotech-derived clay alternatives. Forecasts reflect documented assumptions about regulatory stability and substitution technology development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market