
 Compound Camphor Ointment Market | 2026-2036
Compound Camphor Ointment Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Camphor Ointment Market Outlook
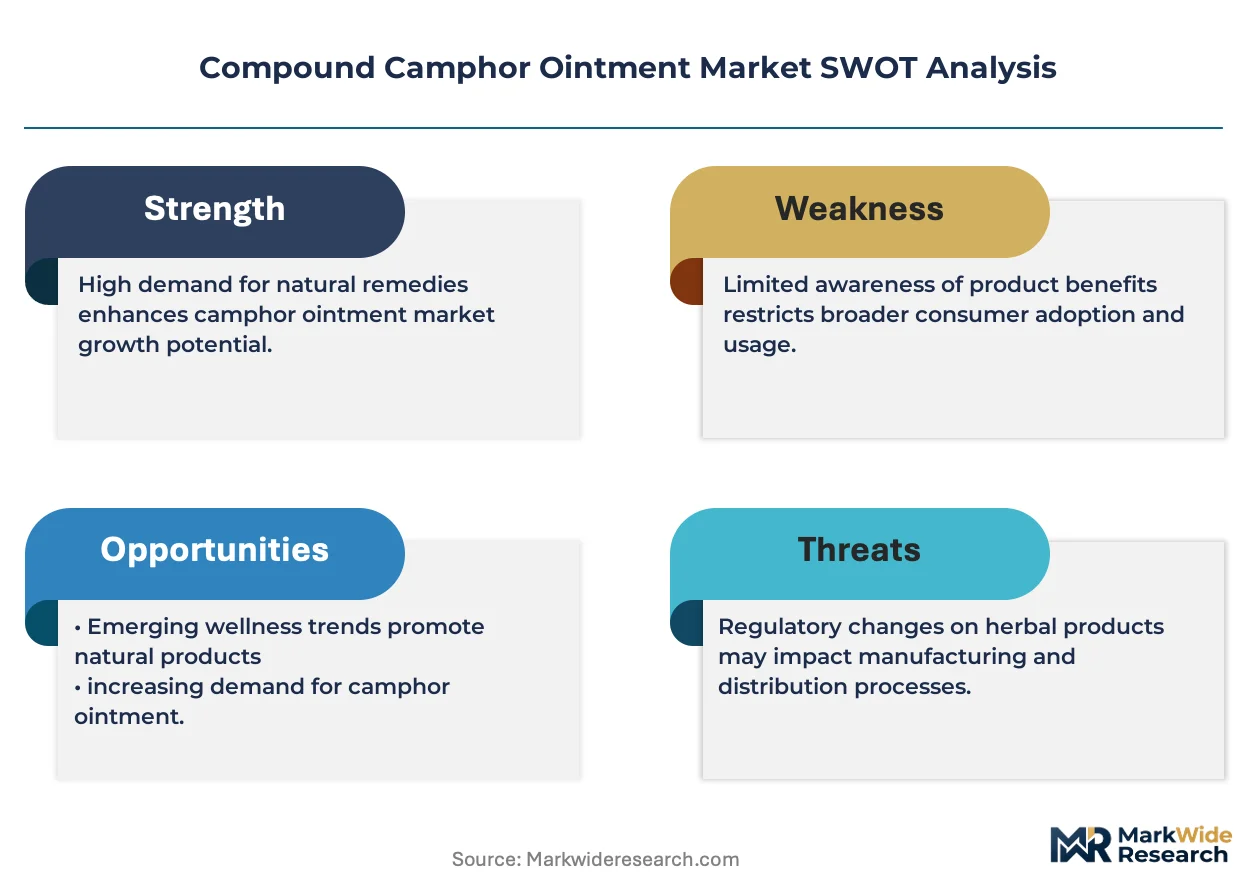
Asset-light contract manufacturing and third-party licensing arrangements is reconfiguring competitive entry barriers, allowing regional formulators to scale without capital-intensive production facilities. Amrutanjan Health Care Limited leverages its century-old brand equity in South India to dominate traditional retail channels. Bayer AG sustains premium positioning through pharmacy-centric distribution and clinical endorsement strategies. Emu Joy differentiates via niche botanical positioning in North American natural-product segments.
Compound camphor ointment is a topical preparation containing refined camphor dissolved in a semi-solid base of waxes, oils, and emollients, typically formulated at concentrations between 4% and 11% for counterirritant and mild analgesic effect. Manufacturers employ hot-melt compounding or cold-processing techniques to preserve volatile terpenoid integrity, with finished products serving consumer self-medication for musculoskeletal discomfort and congestion relief. Muscle Relief formulations occupy the largest volume share within the Application dimension, reflecting aging demographics and occupational strain patterns. E-commerce Platforms represent the fastest-growing End User channel, though Pharmacies still capture the highest-margin transactions through pharmacist-assisted selection. Tubes lead Packaging Type preferences for portability and dosing precision, while Jars retain strength in institutional and family-size segments.
The US FDA regulates camphor concentration limits and child-resistant packaging under OTC monograph standards, while India's CDSCO enforces Ayurvedic drug licensing that bifurcates compliance pathways for traditional and modern formulations. The EU REACH framework governs synthetic camphor imports, creating additional documentation burdens for Asian exporters. Stakeholders must monitor evolving classification debates around natural versus synthetic camphor sourcing, as this distinction increasingly shapes both consumer preference and regulatory scrutiny across major markets.
Market Dynamics
Asset-light contract manufacturing is compressing capital barriers for regional formulators, enabling rapid scaling without captive production facilities while fragmenting competitive moats across traditional and modern distribution channels.
Growth Catalysts
- Aging demographics:Occupational strain patterns and musculoskeletal discomfort prevalence expand self-medication demand for topical analgesics in pharmacy retail chains.
- CDSCO Ayurvedic licensing:India's bifurcated compliance pathway legitimizes heritage formulations alongside modern OTC products, preserving traditional brand equity.
- Hot-melt compounding advances:Improved volatile terpenoid preservation techniques enhance product stability and extend shelf life for export formulations.
Market Restraints
- Synthetic camphor price volatility:Turpentine-derived feedstock fluctuations squeeze margin structures for cost-sensitive regional producers.
- REACH documentation burdens:EU import requirements for synthetic camphor create compliance friction for Asian exporters seeking European market access.
- Child-resistant packaging mandates:US FDA OTC monograph standards elevate packaging costs and complicate tube-format portability advantages.
Strategic Opportunities
- E-commerce platform expansion:Direct-to-consumer channels bypass pharmacy margin extraction while capturing younger demographic segments.
- Natural-synthetic camphor classification:Evolving consumer preference for botanical sourcing creates premium positioning white space for certified natural formulations.
- Congestion relief application extension:Underdeveloped positioning in respiratory symptom management offers cross-category expansion beyond musculoskeletal positioning.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in volatile terpenoid stability and emulsion chemistry constrains product development velocity for mid-tier manufacturers.
- Dual compliance pathway complexity:Simultaneous adherence to Ayurvedic drug licensing and modern pharmaceutical standards fragments quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Camphor Ointment Market |
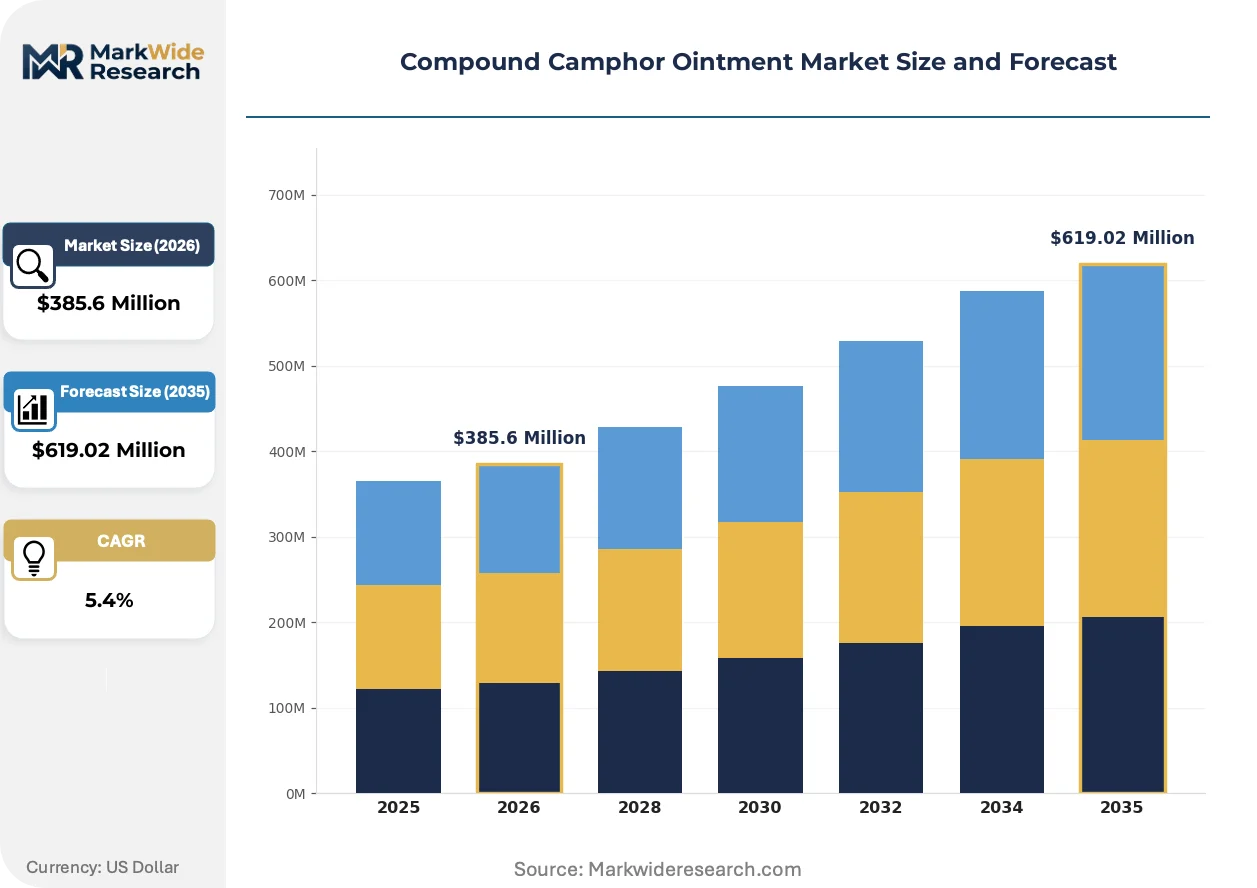
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Muscle Relief, Pain Management, Cold Relief, Skin Irritation End User: Healthcare Providers, Pharmacies, Supermarkets, E-commerce Platforms Formulation: Topical Ointment, Cream, Gel, Liquid Packaging Type: Tubes, Jars, Sachets, Bottles |
| Companies Covered | Cigna, DLC Laboratories, Inc., Thera Wise, Emu Joy, McKesson Canada, Amrutanjan Health Care Limited, Bayer AG, Dabur India Ltd., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Camphor Ointment Market Strategic Shifts
Cold-processing techniques and digital quality assurance systems are redefining manufacturing economics, while regulatory classification debates around natural versus synthetic sourcing reshape competitive positioning strategies.
Microencapsulation technology for volatile terpenoid stabilization is virtualizing traditional hot-melt compounding workflows. Specialty contract manufacturers in India and Southeast Asia adopt these systems to reduce thermal degradation losses. The shift is virtualizing asset-heavy production models by enabling smaller-batch, distributed manufacturing with equivalent active-ingredient integrity.
REACH substance registration requirements for synthetic camphor imports are tightening documentation standards across EU member states. German and French customs authorities now mandate third-party purity certifications for Asian-sourced inputs. Natural camphor suppliers in India and Sri Lanka exploit this friction by positioning certified botanical extracts as compliance-light alternatives.
Pharmacist-assisted selection is yielding to self-directed online research among younger consumers seeking congestion relief and muscle comfort solutions. Amazon and specialized Ayurveda portals capture this behavioral shift with detailed ingredient transparency and review-driven trust mechanisms. North American urban markets exhibit the most pronounced channel migration, though pharmacy chains retain institutional and elderly demographic loyalty.
Compound Camphor Ointment Market Segmentation
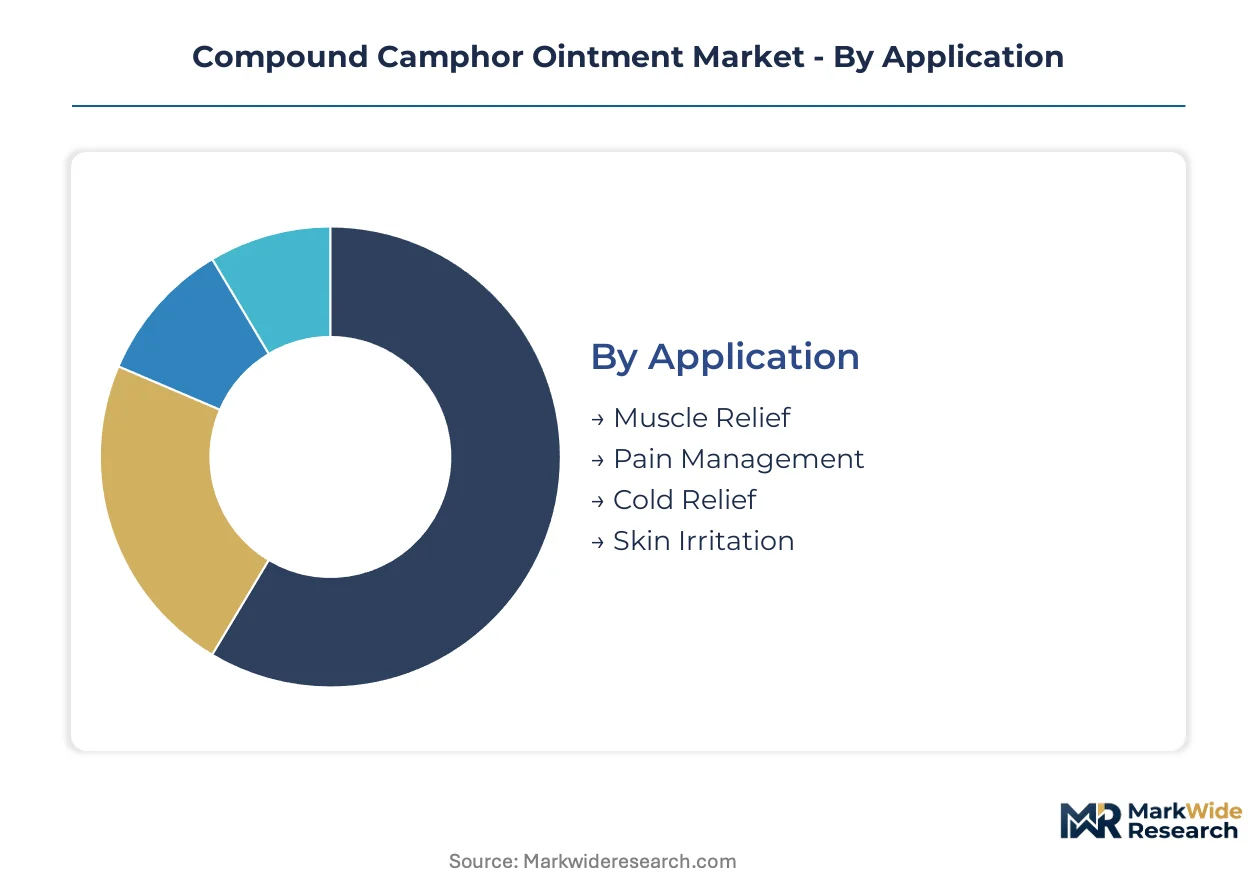
Segmentation in compound camphor ointment markets reveals how formulation chemistry, distribution channel economics, and consumer self-medication behavior create distinct competitive arenas. Manufacturers must align production capabilities with channel-specific margin structures and regulatory pathways.
Application:
Mature musculoskeletal applications dominate volume, while respiratory and dermatological extensions represent emerging expansion vectors for formulators seeking portfolio diversification.
- Muscle Relief:Formulations at 4-11% camphor concentration deliver counterirritant action through vasodilation and sensory nerve stimulation. Aging workforces in India and occupational strain patterns across manufacturing hubs sustain pharmacy retail demand for this segment.
- Pain Management:Multi-ingredient combinations with menthol and methyl salicylate target chronic discomfort conditions. CDSCO's Ayurvedic licensing pathway legitimizes heritage formulations alongside modern OTC approvals in Indian markets.
- Cold Relief:Chest rub applications leverage camphor's decongestant properties through inhalation and topical absorption. Underdeveloped positioning in this category offers cross-category expansion beyond musculoskeletal markets.
- Skin Irritation:Lower-concentration variants address minor dermatological complaints with reduced sensitization risk. Niche botanical positioning in North American natural-product channels differentiates specialized entrants.
Muscle Relief retains volume leadership; Cold Relief holds the steepest expansion curve.
End User:
Channel cost structures fragment pricing power, with assisted-selection environments commanding premium margins against self-directed digital procurement.
- Healthcare Providers:Institutional procurement emphasizes bulk packaging and clinical documentation for therapeutic efficacy. Hospital formulary inclusion requires stability data and bioequivalence studies that elevate compliance investments.
- Pharmacies:Pharmacist-assisted selection captures highest-margin transactions through trust-based recommendation. India's modern OTC distribution networks and traditional retail channels overlap in this segment.
- Supermarkets:Mass-market placement demands economy-tier pricing and high-visibility packaging. Shelf-space competition with private-label alternatives compresses brand marketing returns.
- E-commerce Platforms:Direct-to-consumer channels bypass intermediary margin extraction while capturing younger demographic segments. Amazon and specialized Ayurveda portals exploit review-driven trust mechanisms.
Pharmacies retain margin leadership; E-commerce Platforms are climbing the fastest.
Formulation:
Base chemistry determines volatile terpenoid stability, with semi-solid formats dominating portable self-medication and liquid variants serving institutional applications.
- Topical Ointment:Semi-solid wax and oil bases at 4-11% camphor concentration provide extended skin contact and occlusion. Hot-melt compounding preserves volatile integrity for export formulations facing extended supply chains.
- Cream:Aqueous emulsion systems offer cosmetic elegance and rapid absorption for consumer preference in urban markets. Cold-processing techniques reduce thermal degradation losses for mid-tier manufacturers.
- Gel:Hydroalcoholic bases deliver cooling sensation and non-greasy residue for sports and occupational use. Microencapsulation technology enables smaller-batch distributed manufacturing with equivalent active-ingredient integrity.
- Liquid:Solution and suspension formats serve congestion relief through inhalation and chest application. Child-resistant packaging mandates elevate packaging costs for bottle formats under US FDA standards.
Topical Ointment retains volume leadership; Gel holds the steepest expansion curve.
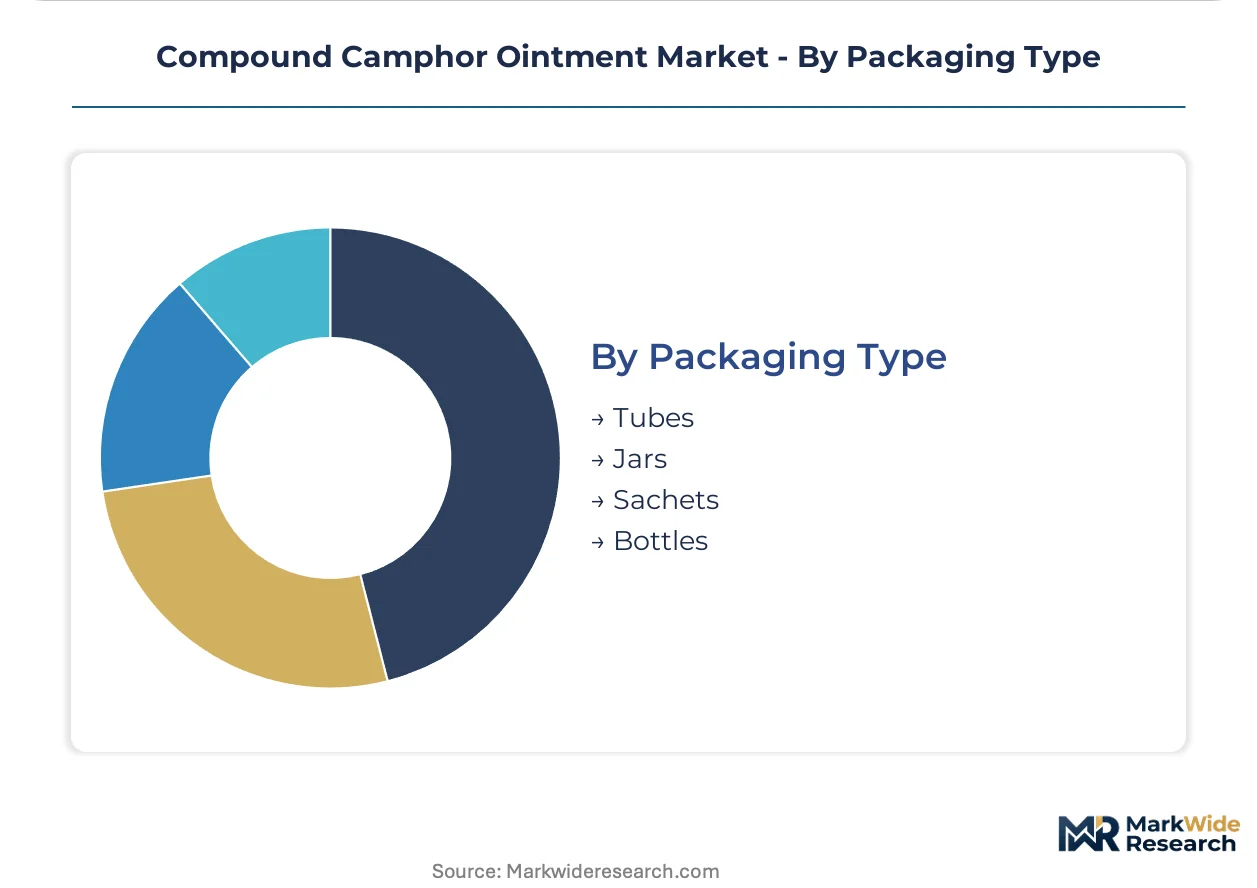
Packaging Type:
Format selection balances dosing precision, portability requirements, and family-size economics across consumer and institutional segments.
- Tubes:Collapsible aluminum and laminate structures enable precise dosing and contamination protection. Portability advantages drive preference among mobile consumers and travel retail channels.
- Jars:Wide-mouth containers accommodate family-size and institutional volumes with scoop-based application. Bulk procurement in hospital and clinic settings sustains demand despite portability limitations.
- Sachets:Single-unit flexible packaging serves trial-size distribution and emerging market affordability requirements. Unit economics constrain margin structures for premium formulation positioning.
- Bottles:Rigid containers with dropper or pour-cap closures serve liquid formulations and congestion relief applications. REACH documentation burdens for EU-bound synthetic camphor inputs complicate export logistics.
Tubes retain volume leadership; Sachets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO Ayurvedic licensing framework preserves heritage brand equity while legitimizing modern OTC pathways. The US FDA enforces concentration limits and child-resistant packaging mandates. Germany's REACH documentation requirements create compliance friction for Asian synthetic camphor exporters.
United States
Pharmacy retail chains capture highest-margin transactions through pharmacist-assisted selection of topical analgesics. The FDA's OTC monograph standards mandate 4-11% camphor concentration limits and child-resistant packaging for all formulations. New Jersey and Pennsylvania host concentrated distribution hubs serving the Northeast corridor's aging demographic demand.
India
Ayurvedic heritage brands overlap with modern OTC networks across Maharashtra and Tamil Nadu manufacturing clusters. CDSCO enforces bifurcated compliance pathways that elevate quality management investments for dual-licensed producers. Mumbai and Chennai anchor contract manufacturing capacity serving domestic pharmacy chains and export markets.
Germany
REACH substance registration requirements tighten documentation standards for synthetic camphor imports from Asian suppliers. German customs authorities mandate third-party purity certifications creating procurement friction for cost-sensitive formulators. The Rhine-Ruhr industrial region concentrates pharmaceutical packaging and logistics infrastructure for EU distribution.
China
Turpentine-derived synthetic camphor production faces feedstock price volatility squeezing margin structures for regional exporters. NMPA pharmaceutical standards govern topical preparation licensing alongside provincial manufacturing permits. Zhejiang and Jiangsu provinces host concentrated wax and emollient base chemical production supporting formulation supply chains.
Canada
Health Canada PMRA standards align with US FDA concentration limits while permitting distinct labeling requirements for bilingual markets. McKesson Canada's distribution infrastructure serves pharmacy retail chains across Ontario and Quebec. Toronto and Montreal metropolitan areas concentrate demand from aging demographics seeking accessible topical analgesics.
Compound Camphor Ointment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented competitive terrain. Pharmacy-centric distributors leverage trust-based recommendation environments while natural-product specialists capture premium positioning in self-directed digital channels. Three archetypes dominate: heritage Ayurvedic houses, multinational pharmaceutical conglomerates, and niche botanical formulators. Strategic moves concentrate on asset-light contract manufacturing adoption and e-commerce platform expansion bypassing traditional margin extraction.
Within the heritage Ayurvedic tier, Amrutanjan Health Care Limited and Dabur India Ltd. exemplify century-old brand equity leveraged across traditional retail and modern pharmacy networks. Bayer AG occupies a position representing multinational pharmaceutical scale with clinical endorsement strategies. Emu Joy anchors the North American natural-product specialist vector with botanical positioning in self-directed consumer segments.
| Leading Market Players |
|---|
| Cigna |
| DLC Laboratories, Inc. |
| Thera Wise |
| Emu Joy |
| McKesson Canada |
| Amrutanjan Health Care Limited |
| Bayer AG |
| Dabur India Ltd. |
| Procter & Gamble |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu provinces anchor global wax and emollient base chemical production, with capacity expansions in these clusters directly moderating formulation cost curves for downstream compound camphor ointment manufacturers. Turpentine-derived synthetic camphor feedstock volatility from Chinese processors transmits pricing pressure through contract manufacturing networks serving Indian and North American brand owners.
Pricing Analysis
Certification level creates the primary spread, with CDSCO Ayurvedic-licensed and FDA OTC-monograph-compliant products commanding premium positioning against unregistered regional alternatives. Three-tier pricing structure separates heritage Ayurvedic brands from modern OTC formulations and private-label economy offerings. Pricing pressure stems from synthetic camphor feedstock volatility squeezing margin structures for cost-sensitive contract manufacturers. Pharmacy retail chains exhibit lowest price sensitivity due to pharmacist-assisted trust premiums, while e-commerce platform consumers demonstrate highest elasticity to unit cost comparisons.
Supply Chain Analysis
Specialty contract manufacturers in Maharashtra and Tamil Nadu manufacturing clusters hold concentrated capacity for both hot-melt and cold-processing formulation techniques. Raw material dependencies center on turpentine-derived synthetic camphor from Chinese processors, natural camphor extracts from Indian and Sri Lankan botanical suppliers, and petroleum-derived wax bases from Zhejiang chemical plants. Single-source vulnerability in synthetic camphor feedstock creates exposure to turpentine price shocks and REACH documentation friction for EU-bound exports. Distribution runs through pharmacy retail chains capturing highest-margin transactions, with e-commerce platforms and supermarket channels expanding downstream reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound camphor ointment markets function as a service-attach opportunity where formulation customization and pharmacist consultation layers expand faster than base product volumes. Recurring revenue from contract manufacturing relationships and licensing arrangements outpaces transactional ointment sales growth across major distribution channels.
For Market Incumbents: Build regulatory certification moats through simultaneous CDSCO Ayurvedic and modern pharmaceutical licensing investments that fragment quality management systems for mid-tier challengers. Defend against asset-light contract manufacturing entrants by securing exclusive capacity agreements with Maharashtra and Tamil Nadu formulation clusters. Prioritize e-commerce platform data capture to anticipate self-directed consumer preference shifts before pharmacy channel erosion accelerates. For New Entrants and Emerging Players: North American natural-product segments offer underpenetrated positioning for certified botanical camphor formulations with transparent supply chain documentation. Target congestion relief applications where heritage Ayurvedic brands maintain weak positioning relative to musculoskeletal dominance. Pursue direct-to-consumer launch through specialized Ayurveda portals with ingredient transparency and review-driven trust mechanisms as primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because asset-light contract manufacturing adoption fragments competitive moats and creates acquisition targets with captive distribution relationships. Focus on heritage Ayurvedic houses with century-old brand equity and modern OTC licensing capabilities as preferred acquisition archetypes. Monitor CDSCO enforcement intensity on dual-compliance pathway producers as inflection indicator for regulatory barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Dual-Licensing Investment | Simultaneous Ayurvedic and modern pharmaceutical approvals fragment competitor compliance capabilities. |
| Microencapsulation Technology Adoption | Cold-processing advances enable smaller-batch distributed manufacturing with equivalent volatile terpenoid integrity. |
| E-Commerce Platform Expansion | Direct-to-consumer channels bypass pharmacy margin extraction while capturing younger demographic segments. |
| Natural Camphor Sourcing Certification | Certified botanical extracts exploit REACH documentation friction for synthetic imports into German markets. |
| Congestion Relief Application Extension | Underdeveloped respiratory positioning offers cross-category expansion beyond musculoskeletal market saturation. |
Study Parameters
Desk research of FDA OTC monograph filings, CDSCO drug licensing records, and EU REACH substance registration databases preceded structured interviews with formulation chemists, contract manufacturing executives, pharmacy retail chain procurement managers, and Ayurvedic brand regulatory affairs leads. Primary fieldwork with Maharashtra and Tamil Nadu manufacturing cluster operators combined with secondary validation through customs trade data and pharmaceutical packaging industry reports. Bottom-up volume modeling across application and formulation segments triangulated against top-down market sizing from distribution channel economics.
Assumptions held regulatory pathway bifurcation and synthetic camphor feedstock volatility within observed historical patterns while varying e-commerce penetration rates and natural-sourcing preference shifts across sensitivity scenarios. Segmentation dimensions modeled include application type, end-user channel, formulation chemistry, packaging format, and regional regulatory cluster. CAGRs derived from trend extrapolation of aging demographic demand, occupational strain prevalence, and channel migration patterns with volatile terpenoid stability technology adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated multinational pharmaceutical conglomerates or rapid CDSCO enforcement escalation would shift outcomes beyond modeled ranges. Quarterly review of synthetic camphor feedstock pricing, REACH documentation requirement changes, and e-commerce platform share metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market