
 Cosmetic Emulsifier Market | 2026-2036
Cosmetic Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Emulsifier Market Analysis
Buyer concentration in the cosmetic emulsifier space is expanding as indie beauty brands and direct-to-consumer formulators fragment traditional procurement channels once dominated by multinational CPG houses. BASF SE leverages its integrated surfactant portfolio to serve both mass-market and premium skin care lines. Evonik Industries AG anchors high-performance emulsifier supply through its specialty liposome and phospholipid technologies. Stepan Company competes on oleochemical-based solutions tailored to natural-positioned brands.
Cosmetic emulsifiers are surface-active agents that stabilize oil-water interfaces in formulations, typically functioning at concentrations between one and ten percent by weight to deliver texture, shelf stability, and active ingredient delivery. Their primary commercial purpose centers on enabling consistent sensory profiles across lotions, creams, and serums while maintaining physicochemical integrity under varied storage conditions. Non-ionic emulsifiers command structural importance due to broad pH tolerance and compatibility with sensitive actives, whereas natural-source emulsifiers represent the fastest-growing origin category as formulators respond to consumer preference shifts. Skin care applications generate the deepest margin pools given higher emulsifier loadings in facial creams and anti-aging serums relative to rinse-off hair care formats.
The EU REACH framework and ECHA microplastic restriction proposals are forcing reformulation timelines across European cosmetic manufacturers, while the FDA maintains ingredient safety review pathways that influence North American product registrations. China's NMPA and GB standards for cosmetic raw materials impose additional testing requirements for imported emulsifiers entering domestic formulation facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid supply chain disruptions and compliance-driven cost escalations.
Market Dynamics
Clean-label procurement is fragmenting buyer concentration across the cosmetic emulsifier value chain, as indie formulators and direct-to-consumer brands displace legacy multinational procurement volumes with smaller-batch, certification-intensive orders.
Growth Catalysts
- EU REACH compliance deadlines:Reformulation mandates under the ECHA microplastic restriction proposals are forcing cosmetic manufacturers to replace synthetic stabilizers with bio-based alternatives, expanding addressable demand for natural-source emulsifiers.
- K-beauty manufacturing corridor:South Korean contract manufacturers are scaling dedicated clean-beauty production lines, creating concentrated procurement pull for high-performance natural emulsifiers in sheet mask and essence formulations.
- Phospholipid encapsulation technology:Liposome delivery systems for active ingredients require specialized emulsifier chemistries, deepening emulsifier loadings in premium facial serum categories.
Market Restraints
- Palm oil price volatility:Oleochemical feedstock costs for natural emulsifier production swing with Malaysian and Indonesian export policy shifts, compressing margin predictability for formulators.
- Specialty phospholipid supply concentration:Pharmaceutical-grade lecithin and phospholipid precursors concentrate among a limited supplier base in Germany and the Netherlands, creating single-source risk for high-performance cosmetic grades.
- Natural emulsifier performance ceiling:Bio-based stabilizers face shelf-stability and pH-tolerance limitations versus synthetic alternatives, restricting substitution rates in long-life cream formulations.
Strategic Opportunities
- India domestic skincare expansion:BIS certification pathways for imported cosmetic raw materials are streamlining, opening formulation-grade emulsifier supply to India's accelerating domestic beauty manufacturing base.
- China GB standards alignment:NMPA cosmetic ingredient filing reforms are reducing registration timelines for compliant emulsifiers, lowering market entry friction for international suppliers.
- Upcycled feedstock valorization:Olive pomace and fruit-seed oil byproduct streams are converging with cosmetic-grade emulsifier processing, creating circular-economy positioning for cost-competitive natural alternatives.
Industry Challenges
- Formulation chemist scarcity:Clean-label emulsifier compatibility testing requires specialized expertise in natural-synthetic hybrid stabilization, a skill set concentrated among senior cosmetic chemists in Basel and Seoul.
- Multi-jurisdiction certification timelines:Simultaneous EU REACH, China NMPA, and US FDA cosmetic ingredient reviews extend product launch cycles by 18-24 months for new emulsifier chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Emulsifier Market |
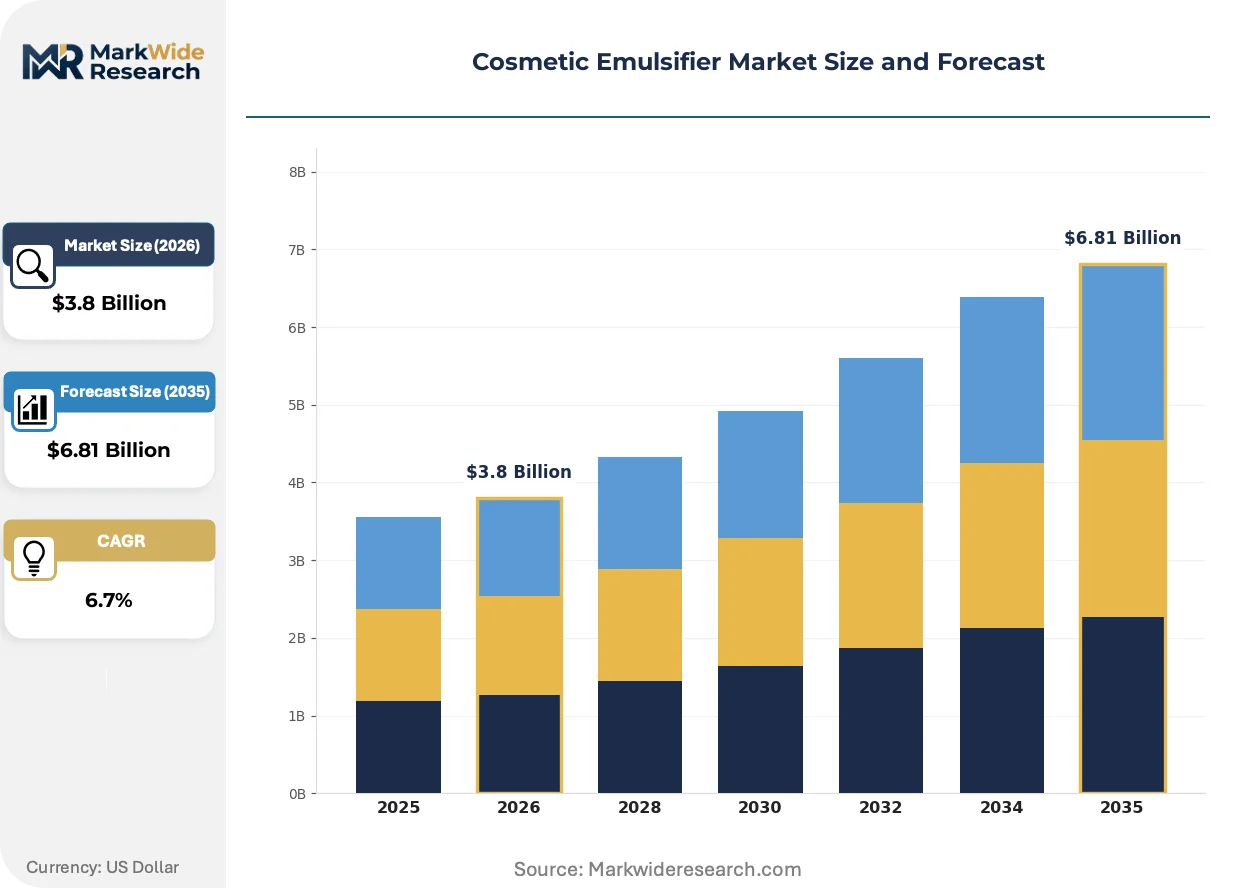
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Emulsifier Type: Anionic, Cationic, Non-Ionic, Amphoteric Product Form: Lotions, Creams, Gels, Serums Application Area: Skin Care, Hair Care, Makeup, Sun Care Source: Synthetic, Natural, Semi-Synthetic, Derived |
| Companies Covered | Evonik Industries AG, Kerry Group Plc, BASF SE, Clariant International Ltd, Air Liquide SA, ADM (Archer Daniels Midland), The Dow Chemical Company, Stepan Company, dsm-firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Emulsifier Market Emerging Trajectories
Biotechnology-derived emulsifiers are compressing the performance gap between synthetic and natural stabilizers, while regulatory chemistry restrictions are accelerating raw material substitution timelines across major formulation centers.
Lecithin-based and fermentation-derived phospholipid emulsifiers are consolidating technical credibility in premium skin care applications. Indie beauty formulators in Copenhagen and Los Angeles are adopting these materials at accelerated rates for clean-positioned facial creams. The technology is consolidating supply relationships around biotechnology partners capable of pharmaceutical-grade purity at cosmetic-scale volumes.
ECHA microplastic restriction proposals under the EU Green Deal are forcing cosmetic manufacturers to eliminate synthetic polymer-based stabilizers from rinse-off formulations by 2029. The regulation compresses reformulation windows for European personal care brands and redirects R&D spending toward bio-based emulsifier validation. Facial cleanser and body wash segments are most affected, with German and French formulators accelerating natural emulsifier qualification programs.
Direct-to-consumer beauty brands are disintermediating traditional distributor channels for cosmetic raw materials, establishing direct technical relationships with emulsifier manufacturers for customized specification development. This pattern compresses order minimums and fragments volume concentration previously captured by multinational CPG procurement offices. The shift is most visible in California and South Korea, where indie formulators operate dedicated clean-beauty manufacturing facilities.
Cosmetic Emulsifier Market Segmentation
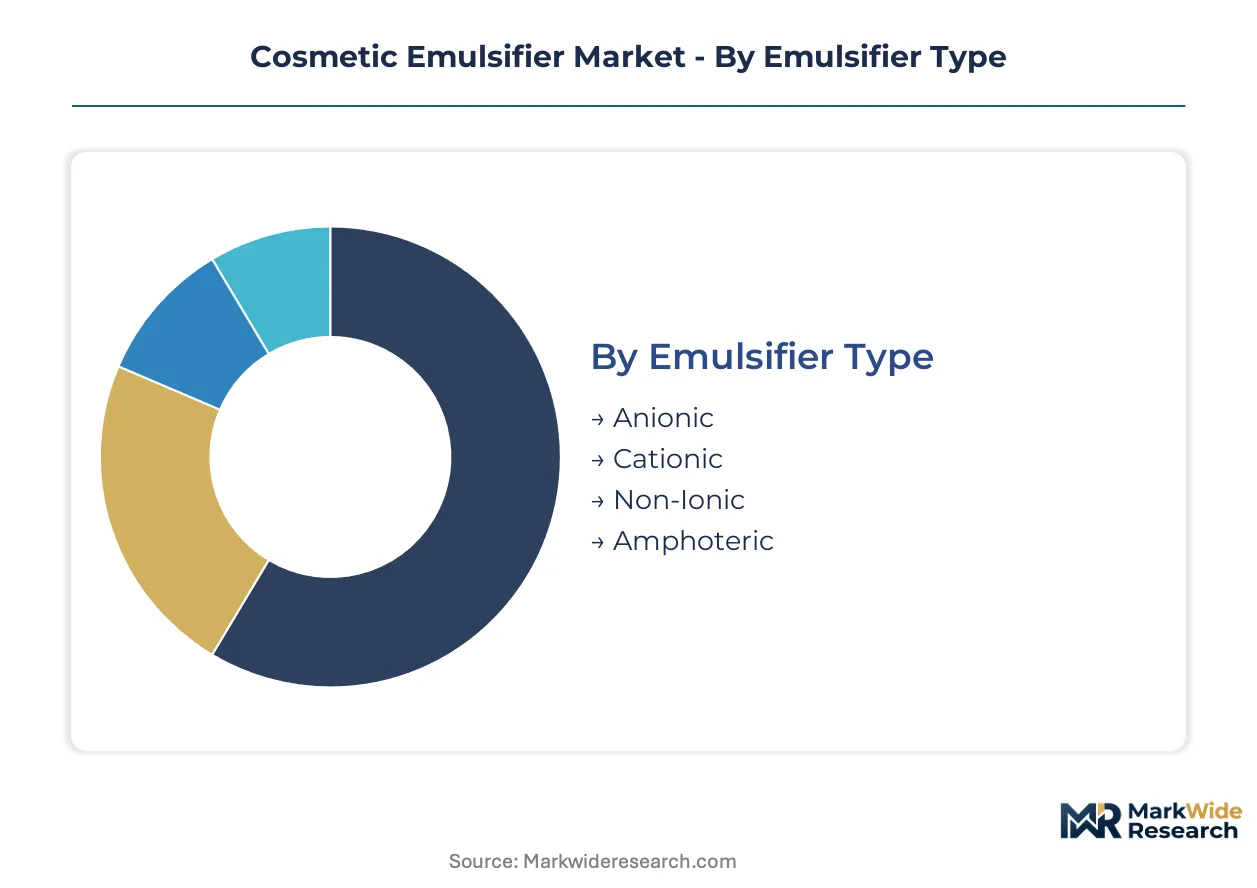
Cosmetic emulsifier procurement fragments across technical specifications, formulation formats, and regulatory compliance tiers. Manufacturers configure production assets around specific emulsifier chemistries and source-origin certifications to capture premium positioning in clean-label skin care.
Emulsifier Type:
Supply concentration for ionic and non-ionic surfactant chemistries diverges sharply between petrochemical and oleochemical feedstock bases.
- Non-Ionic:Polyethoxylated fatty alcohols and sorbitan esters deliver broad pH tolerance and compatibility with sensitive actives. Facial serum formulators in South Korea concentrate procurement here for K-beauty essence production, driven by ECHA microplastic restriction timelines forcing synthetic polymer replacement.
- Anionic:Sulfate and sulfonate-based surfactants stabilize rinse-off formulations with strong foaming profiles. Hair care manufacturers leverage these emulsifiers for shampoo and conditioner bases, though natural-source substitution pressures intensify from EU REACH compliance deadlines.
- Cationic:Quaternary ammonium compounds condition hair fiber surfaces through electrostatic deposition.
- Amphoteric:Betaine derivatives balance mildness with cleansing efficacy in baby care and sensitive skin lines.
Non-ionic emulsifiers absorb the bulk of installed capacity; natural-source anionic alternatives are expanding most quickly.
Product Form:
Emulsifier loading concentrations scale inversely with formulation viscosity and water-phase stability requirements.
- Creams:High-viscosity oil-in-water systems demand 5-10% emulsifier loadings to maintain shelf stability across temperature cycles. Anti-aging facial creams from German and French formulators drive specification intensity here, constrained by natural emulsifier performance ceilings in long-life formulations.
- Serums:Lightweight, high-active delivery vehicles require specialized phospholipid and liposome emulsifier systems. Premium skin care lines in Los Angeles and Copenhagen accelerate adoption of lecithin-based stabilizers for clean-positioned positioning.
- Lotions:Flowable emulsions with moderate oil-phase content serve mass-market moisturization.
- Gels:Water-dominant matrices with minimal oil-phase employ polymeric thickeners alongside low-dose emulsifiers.
Cream formulations command the deepest emulsifier volumes per unit; serum applications are climbing the fastest on value-per-kilogram metrics.
Application Area:
End-use margins separate leave-on facial treatments from rinse-off formats through emulsifier specification intensity.
- Skin Care:Facial creams, moisturizers, and treatment serums carry premium emulsifier specifications for active ingredient encapsulation and sensory profile consistency. China's domestic skincare sector concentrates procurement pull here, amplified by NMPA cosmetic ingredient filing reforms streamlining import pathways.
- Sun Care:UV filter stabilization demands photostable emulsifier systems resistant to degradation under solar exposure. Formulators face reformulation pressure from ECHA microplastic restrictions targeting synthetic polymer thickeners in beach and sport formulations.
- Hair Care:Shampoo and conditioner bases prioritize foaming and conditioning over emulsifier loadings.
- Makeup:Pigment dispersion and wear-time stability drive specialized emulsifier selection for color cosmetics.
Skin care absorbs the bulk of formulation-grade emulsifier capacity; sun care is gaining share fastest on regulatory-driven substitution cycles.
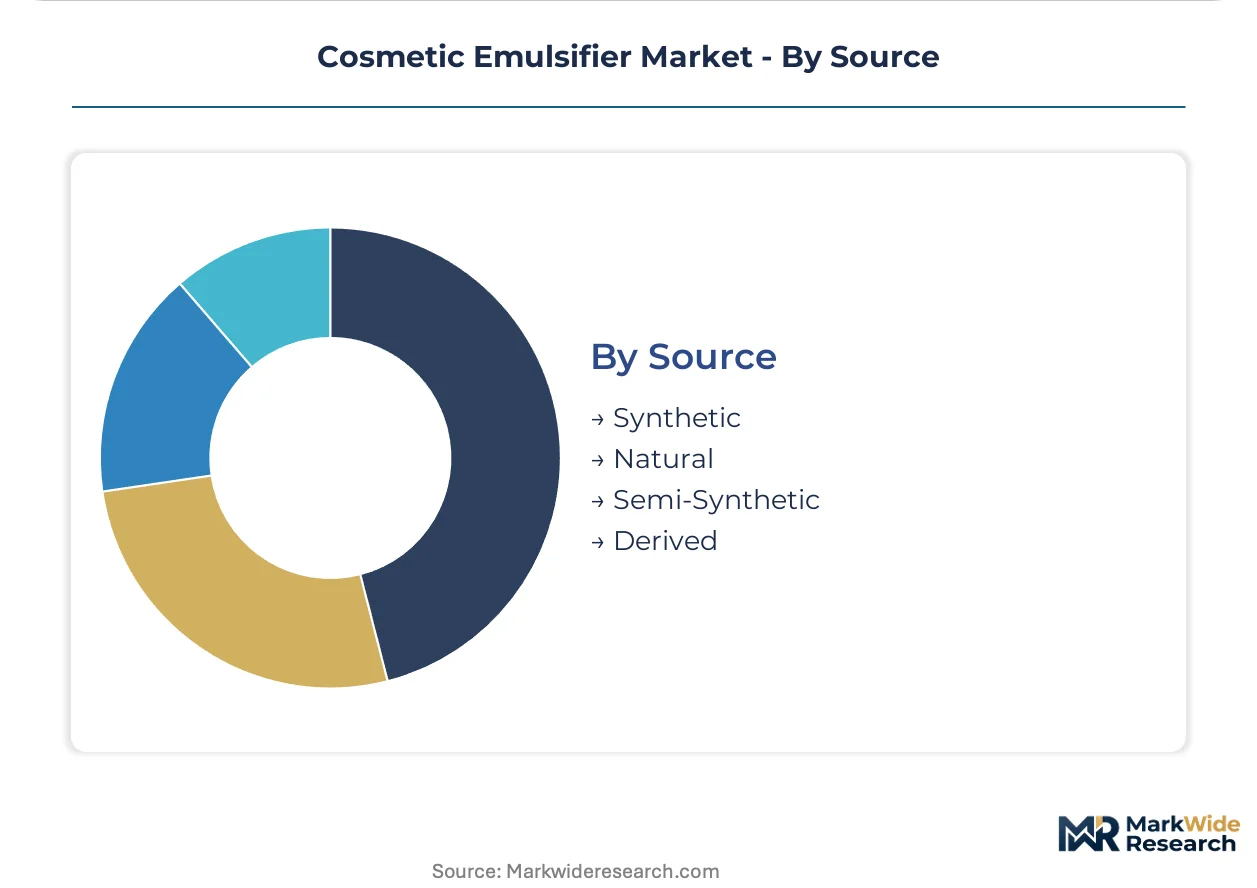
Source:
Feedstock provenance determines certification complexity and price positioning across natural, synthetic, and hybrid origin categories.
- Natural:Plant-derived lecithin, saponins, and polysaccharide emulsifiers command premium positioning through clean-label certification. Indie beauty brands in California and South Korea fragment procurement channels with smaller-batch, certification-intensive orders.
- Synthetic:Petrochemical-based ethoxylates and silicone emulsifiers retain cost advantages and performance predictability. Mass-market manufacturers defend formulations here where natural alternatives face shelf-stability limitations.
- Semi-Synthetic:Chemically modified natural feedstocks bridge performance and positioning requirements.
- Derived:Biotechnology-fermented and upcycled feedstock emulsifiers emerge from olive pomace and fruit-seed oil byproduct streams.
Synthetic sources retain the bulk of volume throughput; natural-origin emulsifiers are expanding most quickly on clean-label procurement fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cosmetic emulsifiers concentrates in manufacturing corridors where clean-beauty formulators cluster near specialized chemical production assets. South Korea and China anchor volume procurement through K-beauty contract manufacturers and domestic skincare brands respectively. Regulatory divergence across REACH, NMPA, and FDA jurisdictions fragments supply chain compliance requirements.
South Korea
K-beauty contract manufacturers in Seoul Capital Area and Busan-Ulsan corridor drive concentrated procurement of high-performance natural emulsifiers for sheet mask and essence formulations. MFDS cosmetic ingredient safety standards enforce rigorous documentation for imported raw materials. Incheon's free economic zone hosts specialized distributors serving indie beauty brands with smaller-batch, certification-intensive orders.
China
Domestic skincare sector expansion in Yangtze River Delta and Pearl River Delta generates deepening emulsifier volumes for facial cream and serum production. NMPA cosmetic ingredient filing reforms streamline registration timelines for compliant international suppliers. Shanghai's formulation R&D clusters accelerate qualification of bio-based stabilizers for clean-positioned local brands.
Germany
Premium skin care formulators in North Rhine-Westphalia and Bavaria specify pharmaceutical-grade phospholipid emulsifiers for anti-aging cream lines. ECHA microplastic restriction proposals under EU REACH compress reformulation windows for synthetic polymer replacement. BASF SE's Ludwigshafen complex anchors integrated surfactant supply serving both mass-market and premium European brands.
United States
Indie beauty brands in California and direct-to-consumer formulators in Greater New York fragment traditional procurement channels with customized specification development. FDA cosmetic ingredient safety review pathways influence North American product registration timelines. Los Angeles clean-beauty manufacturing facilities establish direct technical relationships with emulsifier suppliers, bypassing legacy distributor networks.
India
Domestic beauty manufacturing expansion in Maharashtra and Gujarat creates procurement pull for formulation-grade emulsifiers as local brands scale production. BIS certification pathways for imported cosmetic raw materials are streamlining, reducing market entry friction. Mumbai's contract manufacturing sector qualifies natural-source emulsifiers for ayurveda-positioned skin care lines targeting middle-class consumers.
Cosmetic Emulsifier Market Vendor Landscape
German and Swiss producers anchor the premium phospholipid tier; American oleochemical specialists hold volume positions in natural-source categories. The vendor base splits between integrated chemical conglomerates with surfactant portfolios and focused biotechnology players with fermentation-derived capabilities. Three archetypes dominate: integrated petrochemical-surfactant producers, natural-source oleochemical refiners, and specialty phospholipid technology licensors. Competitive dynamics center on backward integration into feedstock supply and geographic expansion into Asian formulation clusters.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify divergent strategic positions. BASF SE represents the petrochemical-integrated archetype with broad surfactant coverage across mass-market and premium applications. Evonik Industries AG occupies the specialty phospholipid technology position, anchoring high-performance supply through liposome and encapsulation expertise. Stepan Company sits within the natural-source oleochemical segment, competing on plant-derived solutions tailored to clean-label brand positioning. Kerry Group Plc and ADM represent the agribusiness-integrated pathway, leveraging oilseed processing assets to supply lecithin-based emulsifiers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Kerry Group Plc |
| BASF SE |
| Clariant International Ltd |
| Air Liquide SA |
| ADM (Archer Daniels Midland) |
| The Dow Chemical Company |
| Stepan Company |
| dsm-firmenich |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade phospholipid supply concentration in Germany and the Netherlands creates a steep certification ladder that separates premium facial serum emulsifiers from commodity rinse-off grades, with each tier locking in distinct feedstock sourcing strategies and buyer relationship structures. Natural-source emulsifiers command 40-60% price premiums over synthetic alternatives, yet oleochemical feedstock volatility in Malaysian and Indonesian palm oil markets compresses margin predictability across all tiers.
Pricing Analysis
Volume-margin splits separate mass-market rinse-off formulations from premium leave-on facial treatments, with skin care serums capturing value-per-kilogram premiums despite lower absolute throughput. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade certifications anchors differentiation, with EU REACH compliance timelines intensifying cost compression in synthetic polymer segments. Pricing pressure stems from palm oil export policy swings in Southeast Asia, eroding natural emulsifier margin stability. Indie beauty brands in California and South Korea exhibit highest price sensitivity, while German anti-aging formulators absorb premium phospholipid costs for liposome encapsulation performance.
Supply Chain Analysis
Phospholipid precursor supply rests on German and Dutch pharmaceutical chemical producers, with oleochemical feedstock drawing from Malaysian and Indonesian palm oil processing clusters. Specialty lecithin and fermentation-derived inputs hinge on oilseed crushing assets in the United States and Brazil, while upcycled olive pomace streams from Mediterranean processing facilities feed emerging circular-economy emulsifier grades. Single-source vulnerability concentrates in pharmaceutical-grade phospholipid purification capacity, where cosmetic-grade qualification requires dedicated production lines. Distribution runs through specialized chemical distributors in Incheon's free economic zone and direct technical relationships with indie formulators in Los Angeles and Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty phospholipid production capacity constraints in Germany and the Netherlands prop pricing premiums, with fermentation-scale expansion timelines extending supply scarcity through the analysis window.
For Market Incumbents: Extend phospholipid purification capacity in Basel and Ludwigshafen corridors to capture premium skin care formulation demand, while securing backward integration into non-palm oleochemical feedstocks to defend margin position against Malaysian export policy volatility. Certification investment in China NMPA and India BIS pathways creates channel control moats as indie brand procurement fragments. For New Entrants and Emerging Players: Contract manufacturers in South Korea's Busan-Ulsan corridor present the most penetrable entry point, with K-beauty clean-beauty production lines demanding smaller-batch, certification-intensive natural emulsifier orders that incumbents struggle to serve profitably. Upcycled feedstock valorization from olive pomace and fruit-seed oil byproducts offers differentiated positioning at cost-competitive price points. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology-fermented emulsifier specialists given ECHA microplastic restriction enforcement compressing synthetic substitute viability over a five-to-ten-year demand transition. Fermentation-scale pharmaceutical-grade purity capabilities at cosmetic volumes represent the acquisition target archetype. Watch NMPA filing reform implementation velocity as inflection indicator for China market entry friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-Palm Oleochemical Feedstocks | Stepan Company and ADM leverage oilseed crushing assets to reduce Malaysian palm oil price volatility exposure. |
| Fermentation-Scale Phospholipid Capacity Expansion | Evonik Industries AG anchors liposome delivery system supply as K-beauty essence formulations deepen emulsifier loadings. |
| China NMPA Cosmetic Ingredient Filing Investment | BASF SE streamlines registration timelines for imported emulsifiers entering Yangtze River Delta formulation facilities. |
| Direct-to-Consumer Brand Technical Partnership Programs | Indie beauty formulators in Los Angeles bypass legacy distributors for customized natural emulsifier specification development. |
| Upcycled Feedstock Qualification for Circular Positioning | Olive pomace and fruit-seed oil byproduct streams create cost-competitive natural alternatives with clean-label certification. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cosmetic formulation chemists, raw material procurement managers at contract manufacturers, regulatory affairs specialists, and specialty chemical distribution executives. Cefic surfactant production statistics, ECHA restriction proposal documentation, China NMPA ingredient filing databases, and U.S. FDA cosmetic ingredient safety review pathways provided cross-referenced validation points. Bottom-up emulsifier volume estimates by formulation type and source origin triangulated against top-down market sizing from chemical producer revenue disclosures.
Segment-level granularity modeled emulsifier type, product form, application area, and source origin dimensions across the projection horizon, with regional splits calibrated to manufacturing cluster concentration in South Korea, China, Germany, the United States, and India. CAGRs derived from regression analysis of historical procurement volume trends and forward-looking regulatory compliance-driven substitution assumptions. Industry-specific forecast inputs incorporated ECHA microplastic restriction implementation timelines, NMPA filing reform velocity, and K-beauty contract manufacturing capacity expansion plans.
Several conditions sit outside the modeled scope, including abrupt palm oil export policy shocks, unanticipated biotechnology fermentation yield breakthroughs, and geopolitical trade restriction escalations affecting phospholipid precursor cross-border flows. Forecasts reflect documented assumptions around regulatory implementation schedules and feedstock cost trajectories. A small set of named triggers warrants ongoing watch: ECHA restriction enforcement velocity, China NMPA filing approval rate acceleration, and specialty phospholipid capacity addition announcements in Germany and Switzerland.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Methylisothiazolinone Market