
 Global Sirolimus Market | 2026-2036
Global Sirolimus Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sirolimus Market Foresight
Maintenance contracts for drug-eluting stent monitoring and patient compliance programs is restructuring how pharmaceutical firms capture recurring revenue from sirolimus portfolios. Pfizer Inc. leverages its hospital formulary relationships to sustain premium positioning in immunosuppression. Dr. Reddy's Laboratories Ltd. anchors its competitive stance through cost-efficient oral tablet manufacturing. Biocon specializes in biosimilar development pathways for oncology applications.
Sirolimus is a macrocyclic lactone compound produced via fermentation of Streptomyces hygroscopicus, functioning as an mTOR inhibitor that suppresses T-cell and B-cell activation by disrupting cytokine signaling pathways. The compound serves primarily to prevent organ rejection in renal transplantation and to treat lymphangioleiomyomatosis. Oral tablets dominate current prescription volumes due to established reimbursement pathways and patient self-administration convenience, while drug-eluting stents command concentrated margin pools within cardiology segments where interventional procedures generate higher per-procedure economics. Injectable solutions compete for share in acute transplant settings where bioavailability monitoring proves critical.
The FDA regulates sirolimus through its Center for Drug Evaluation and Research with stringent bioequivalence requirements for generic entrants, while the EMA's Committee for Medicinal Products for Human Use enforces centralized marketing authorization procedures across EU member states. The WHO includes sirolimus on its Essential Medicines List, shaping procurement standards for national health systems in emerging markets. Stakeholders must monitor evolving mTOR inhibitor combination protocols and biosimilar litigation outcomes to anticipate shifts in therapeutic positioning and pricing power.
Market Dynamics
The FDA's orphan drug designation framework is compressing development timelines for sirolimus derivatives, while mTOR inhibitor combination protocols in oncology are redirecting R&D investment away from standalone immunosuppression applications.
Growth Catalysts
- Orphan Drug Incentives:The FDA's seven-year market exclusivity provisions accelerate clinical trial enrollment for lymphangioleiomyomatosis indications, shortening time-to-revenue for pipeline candidates.
- Japan's Elderly Transplant Protocols:METI reimbursement adjustments for calcineurin-inhibitor-sparing regimens expand sirolimus utilization in renal transplant centers across Osaka and Tokyo clusters.
- Drug-Eluting Stent Coatings:Polymer-free sirolimus-eluting platforms are capturing cardiology procedure volumes in German interventional centers where restenosis rates drive stent selection criteria.
Market Restraints
- Fermentation Capacity Concentration:Streptomyces hygroscopicus cultivation facilities cluster in South Korean and Chinese bioreactor parks, creating single-source vulnerability for active pharmaceutical ingredient supply.
- Bioequivalence Burden:The FDA's 90% confidence interval requirements for generic sirolimus tablets extend ANDA review timelines, protecting incumbent pricing power but delaying cost competition.
- Metabolic Substitutes:Everolimus and temsirolimus analogues are displacing sirolimus in certain oncology protocols where shorter half-lives enable tighter dose titration.
Strategic Opportunities
- Indian Transplant Infrastructure:CDSCO streamlined approval pathways for immunosuppressants align with government hospital expansion in Tamil Nadu and Karnataka, opening volume growth corridors.
- Topical Formulation Development:Sirolimus creams for tuberous sclerosis complex facial angiofibromas address unmet pediatric demand outside current oral and injectable delivery paradigms.
- WHO Prequalification:Essential Medicines List procurement standards in sub-Saharan African markets create institutional purchasing channels previously dominated by tacrolimus.
Industry Challenges
- mTOR Biomarker Expertise Gap:Clinical pharmacology departments lack sufficient therapeutic drug monitoring specialists to optimize sirolimus dosing in complex transplant populations.
- Cross-Indication Manufacturing Complexity:Oral tablet, injectable solution, and stent-coating sirolimus variants require distinct GMP suites, fragmenting production economics across low-volume specialty batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sirolimus Market |
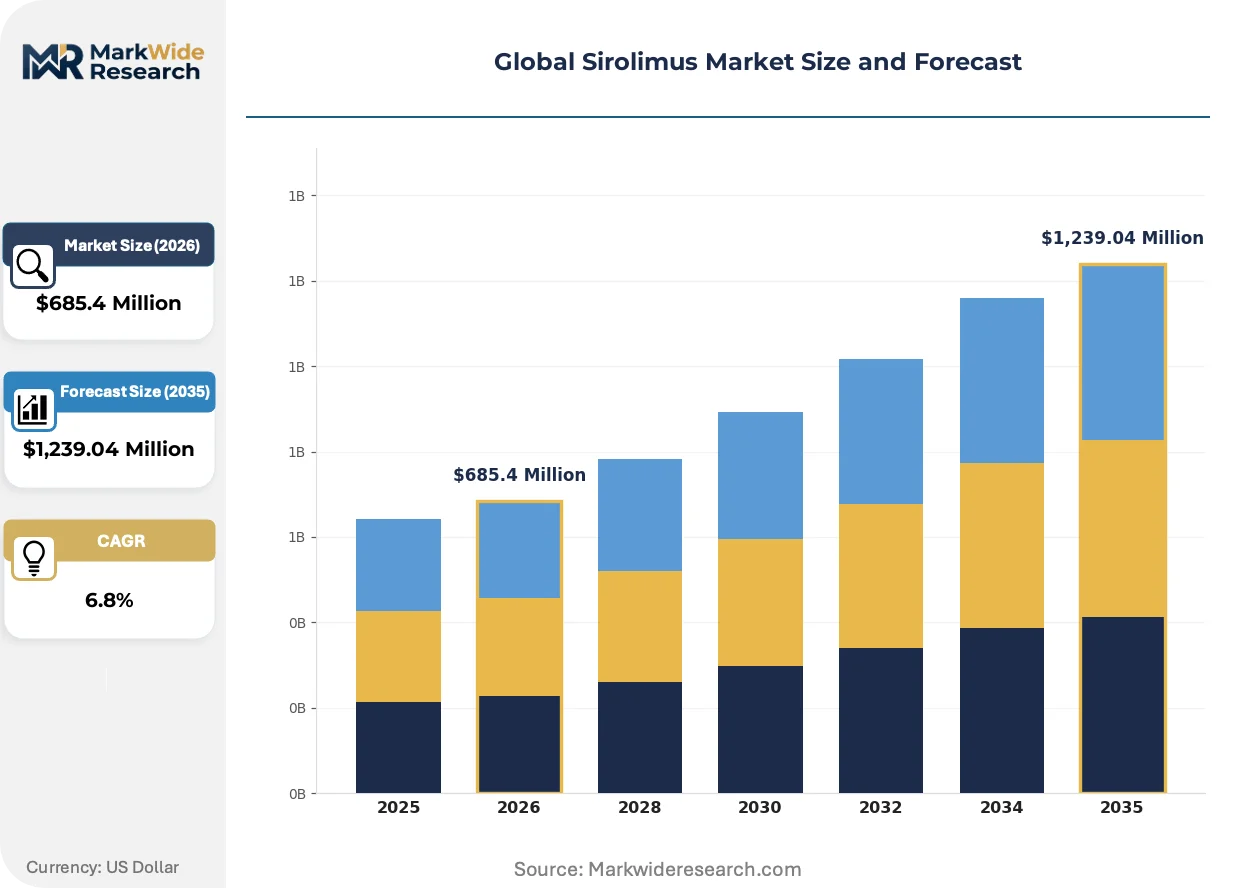
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Injectable Solution, Topical Formulations, Drug-Eluting Stents Therapy Area: Immunosuppression, Oncology, Dermatology, Cardiology Route of Administration: Oral, Intravenous, Transdermal, Subcutaneous End User: Hospitals, Specialty Clinics, Research Institutes, Home Care Providers |
| Companies Covered | Pfizer Inc., Dr. Reddy's Laboratories Ltd., Biocon, Zydus Cadila, Torrent Pharmaceuticals Ltd., Intas Pharmaceuticals Ltd, Concept Medical, Accord Healthcare, Apotex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sirolimus Market Shifts & Advancements
mTOR pathway science is expanding sirolimus utility beyond immunosuppression into oncology, vascular intervention, and rare disease domains. Three developments are restructuring competitive positioning.
Nanoparticle-encapsulated sirolimus formulations are absorbing development resources from conventional oral tablets. Transplant centers in the United States are piloting these platforms for patients with erratic gastrointestinal absorption. The technology is absorbing margin from standard generics by enabling premium pricing for bioavailability-guaranteed delivery.
EMA's Committee for Medicinal Products for Human Use revised centralized authorization procedures for fixed-dose sirolimus combinations, compressing review timelines for tacrolimus-sirolimus co-formulations. German and French transplant networks are accelerating protocol adoption in response. Cardiology segments face parallel pressure from MDR device classification changes affecting drug-eluting stent recertification cycles.
Hospital formulary consolidation is compressing supplier rosters for immunosuppression protocols. Procurement committees in Japanese prefectural medical centers now mandate single-source contracts for mTOR inhibitors to secure volume discounts. This concentration is most visible in the Kanto region, where inter-hospital purchasing alliances displace fragmented physician-directed ordering.
Global Sirolimus Market Segmentation
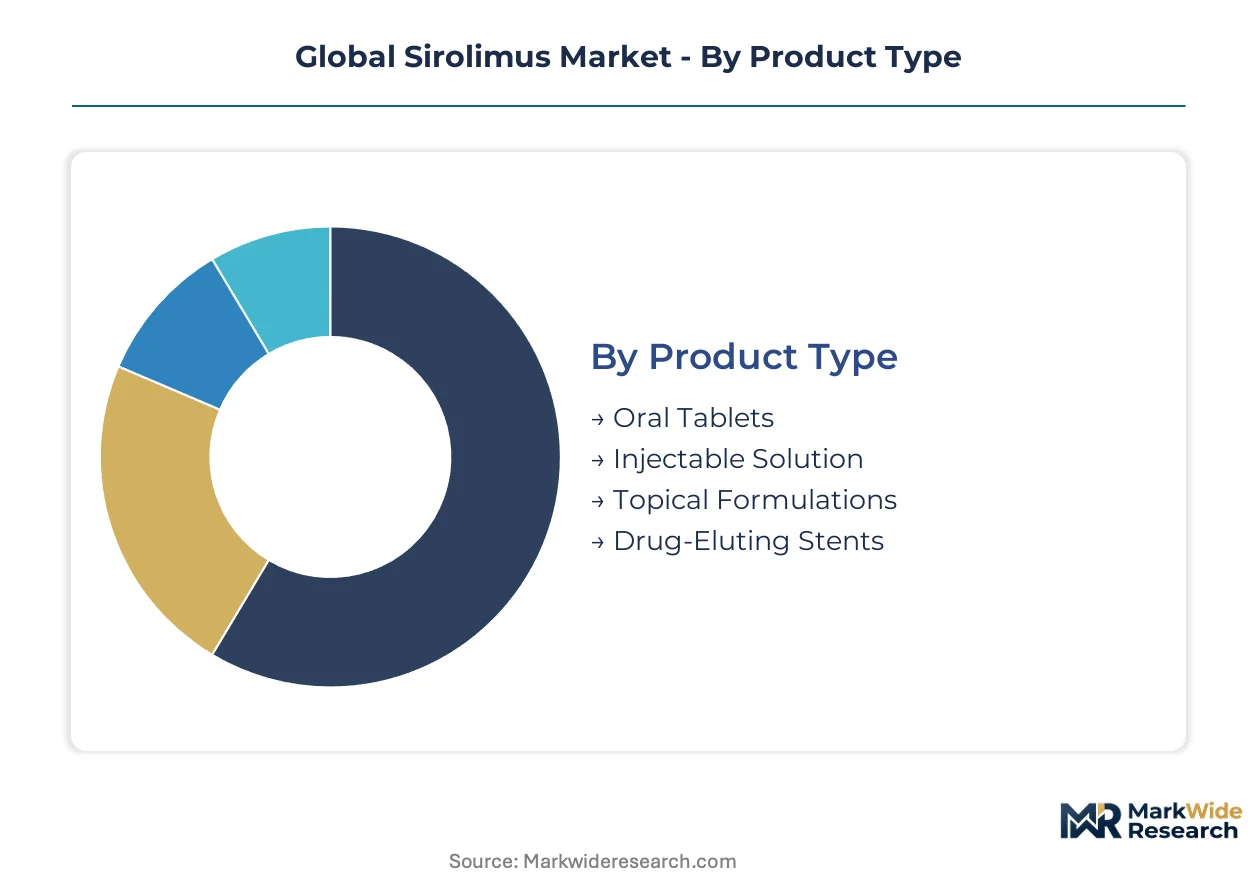
Sirolimus market segmentation reflects divergent manufacturing requirements across delivery platforms, with fermentation-derived API flowing into distinct GMP suites for oral, parenteral, and device-coating applications. Understanding these supply chain bifurcations clarifies where margin pools concentrate and which segments attract capital investment.
Product Type:
Active pharmaceutical ingredient from Streptomyces hygroscopicus fermentation feeds into four distinct manufacturing tracks, each with specialized equipment and regulatory pathways.
- Oral Tablets:Compressed formulations with established bioequivalence benchmarks dominate prescription volumes in renal transplant maintenance. Demand concentrates in United States Medicare Part B reimbursement channels where patient self-administration reduces hospitalization costs.
- Injectable Solution:Sterile formulations for acute transplant settings and bioavailability monitoring command premium pricing in tertiary care centers. Supply concentrates in Pfizer's legacy manufacturing network and select South Korean CMO facilities serving Japanese transplant networks.
- Topical Formulations:Creams and gels for tuberous sclerosis complex facial angiofibromas address pediatric populations in European dermatology clinics.
- Drug-Eluting Stents:Polymer-free and polymer-based coatings from Abbott and Boston Scientific generate per-procedure economics in German and Japanese interventional cardiology suites.
Oral tablets absorb the bulk of installed fermentation capacity; topical formulations are expanding most quickly into rare disease indications.
Therapy Area:
Clinical application determines pricing architecture, with immunosuppression protocols anchoring volume and oncology trials redirecting pipeline investment.
- Immunosuppression:Renal transplant rejection prophylaxis remains the anchor indication with standardized dosing protocols across United States transplant centers. Japanese elderly transplant protocols under METI reimbursement adjustments are expanding calcineurin-inhibitor-sparing regimens in Osaka and Tokyo clusters.
- Oncology:mTOR inhibitor combinations in solid tumor trials are displacing standalone sirolimus in certain protocols, though lymphangioleiomyomatosis maintains orphan drug exclusivity protections.
- Dermatology:Topical sirolimus for tuberous sclerosis complex addresses unmet pediatric demand outside oral delivery paradigms, with EMA centralized procedures enabling EU-wide market access.
- Cardiology:Drug-eluting stent coatings compete on restenosis rate data in German interventional centers where procedure volumes drive stent selection.
Immunosuppression commands the largest share of commercial infrastructure; oncology applications are climbing the fastest as combination protocols advance through clinical pipelines.
Route of Administration:
Delivery mechanism selection hinges on bioavailability requirements, patient compliance constraints, and acute versus chronic care settings.
- Oral:First-pass metabolism variability drives therapeutic drug monitoring requirements in transplant populations with erratic gastrointestinal absorption.
- Intravenous:Bioavailability-guaranteed delivery in acute settings supports premium positioning for nanoparticle-encapsulated formulations under development in United States transplant centers.
- Transdermal:Pediatric dermatology applications in tuberous sclerosis complex are gaining traction in European markets with streamlined pediatric investigation plans.
- Subcutaneous:Emerging delivery platforms for oncology applications enable outpatient administration, reducing infusion center burden in Japanese prefectural medical networks.
Oral administration retains the deepest manufacturing footprint; subcutaneous delivery is gaining share fastest through oncology pipeline prioritization.
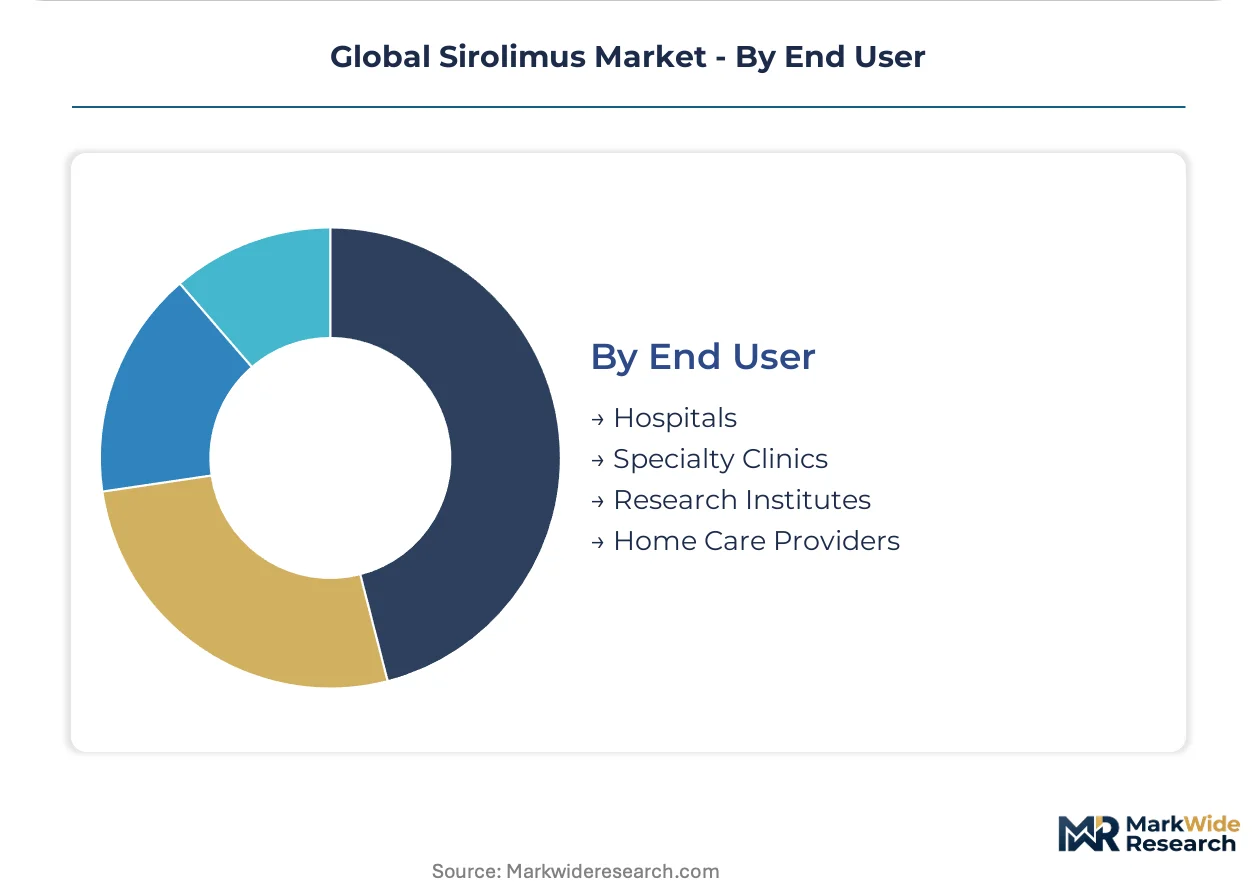
End User:
Procurement authority and reimbursement pathways segment demand across institutional settings with varying formulary control structures.
- Hospitals:Transplant centers in the United States, Germany, and Japan consolidate purchasing through formulary committees, with Japanese prefectural alliances in the Kanto region mandating single-source mTOR inhibitor contracts.
- Specialty Clinics:Interventional cardiology suites in German urban centers drive drug-eluting stent selection based on restenosis performance data and physician preference.
- Research Institutes:Academic medical centers in the United States and Japan conduct mTOR pathway combination trials, influencing future standard-of-care protocols.
- Home Care Providers:Oral tablet dispensing for stable transplant outpatients expands in United States Medicare Advantage networks with medication therapy management incentives.
Hospitals absorb the bulk of procurement volume; home care providers are expanding most quickly as reimbursement shifts toward outpatient management models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean and Chinese bioreactor parks supply most active pharmaceutical ingredient, while transplant centers in the United States, Germany, and Japan absorb the bulk of finished formulation demand. This production-consumption divide shapes regulatory arbitrage opportunities and supply chain vulnerability profiles.
United States
Renal transplant centers in Philadelphia and Houston drive oral tablet volumes through Medicare Part B reimbursement channels. The FDA's Center for Drug Evaluation and Research enforces stringent bioequivalence requirements that extend ANDA review timelines for generic entrants. Massachusetts academic medical centers pilot nanoparticle-encapsulated formulations for patients with erratic gastrointestinal absorption.
Germany
Interventional cardiology suites in Munich and Berlin select polymer-free sirolimus-eluting stents based on restenosis rate performance data. The EMA's Committee for Medicinal Products for Human Use revised centralized authorization procedures for fixed-dose combinations, compressing review timelines. Bavarian transplant networks accelerate tacrolimus-sirolimus co-formulation adoption in response.
Japan
Prefectural medical centers in the Kanto region mandate single-source contracts for mTOR inhibitors to secure volume discounts. METI reimbursement adjustments for calcineurin-inhibitor-sparing regimens expand utilization in Osaka and Tokyo transplant clusters. Nagoya-based CMO facilities serve domestic injectable solution demand.
India
Government hospital expansion in Tamil Nadu and Karnataka opens volume growth corridors for oral immunosuppressants. CDSCO streamlined approval pathways align with national transplant infrastructure investment. Hyderabad and Ahmedabad manufacturing clusters specialize in cost-efficient oral tablet production for export markets.
South Korea
Streptomyces hygroscopicus cultivation facilities in Songdo and Osong bioreactor parks concentrate global active pharmaceutical ingredient supply. The MFDS regulates finished formulations under harmonized ICH guidelines. Seoul-based CMOs supply Japanese transplant networks with sterile injectable solutions.
Global Sirolimus Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fermentation-derived active pharmaceutical ingredient and finished formulation segments. The market structure concentrates around incumbent pharmaceutical conglomerates with hospital formulary relationships, mid-cap generic manufacturers with cost-efficient oral tablet capacity, and specialty device-coating firms with interventional cardiology expertise. Three archetypes dominate: premium-priced innovators with orphan drug exclusivities, scale-driven generic houses with ANDA portfolios, and hybrid device-pharma players with stent-coating capabilities. M&A activity targets topical formulation specialists, while capacity expansion concentrates in Indian and South Korean bioreactor parks.
Among established pharmaceutical conglomerates, Pfizer Inc. occupies a position exemplifying premium-tier immunosuppression positioning through hospital formulary relationships. Dr. Reddy's Laboratories Ltd. and Biocon represent the mid-cap generic and biosimilar archetypes respectively, with the former anchoring cost-efficient oral manufacturing and the latter specializing in oncology pathway development. These three entities illustrate the competitive spectrum from branded incumbent to emerging biosimilar challenger.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Biocon |
| Zydus Cadila |
| Torrent Pharmaceuticals Ltd. |
| Intas Pharmaceuticals Ltd |
| Concept Medical |
| Accord Healthcare |
| Apotex Inc. |
| Others |
Supply & Pricing Matrix
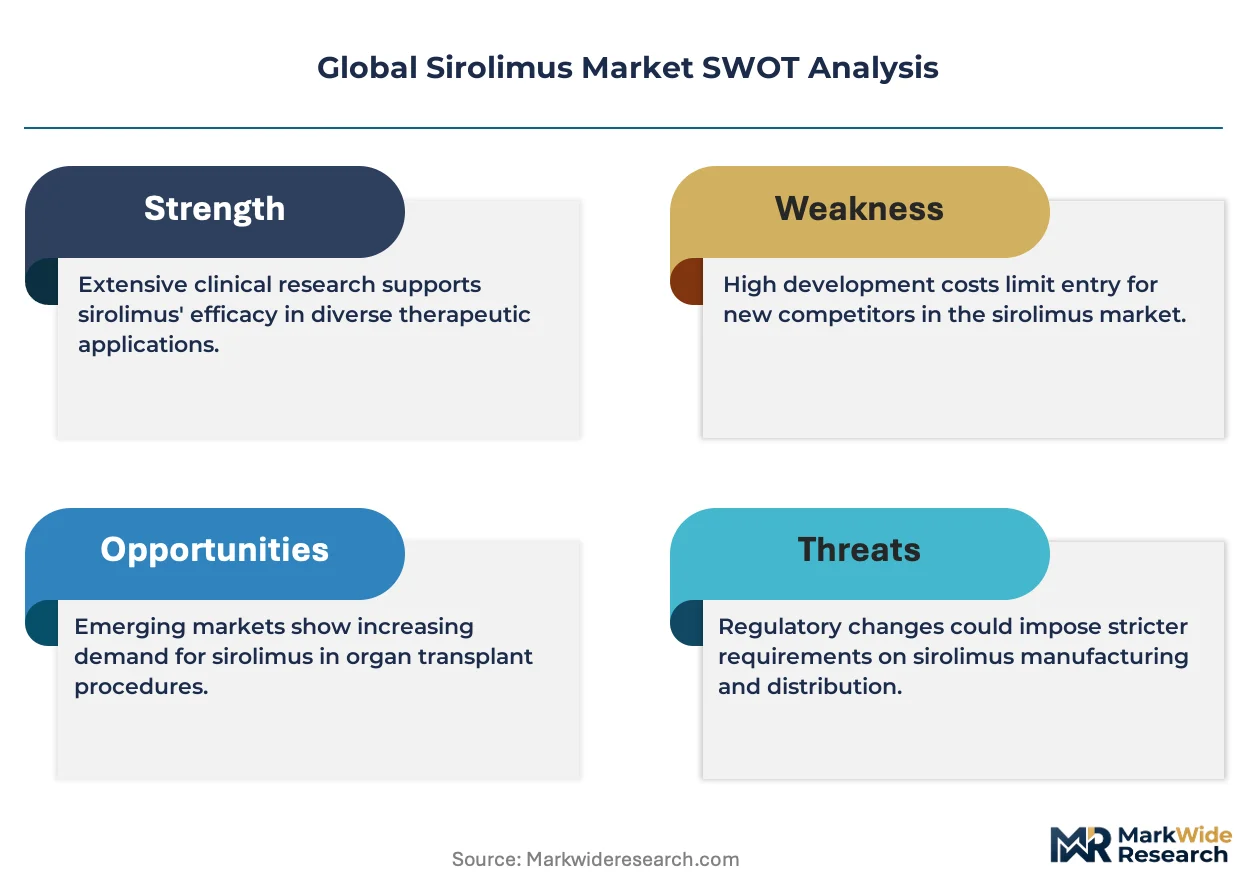
Nanoparticle-encapsulated formulation development is simultaneously elevating R&D cost structures and concentrating manufacturing expertise among fermentation-capable bioreactor operators in South Korea and China. This technological transition fragments pricing power between premium bioavailability-guaranteed delivery platforms and commoditized oral tablets facing generic erosion.
Pricing Analysis
Margin tightening in oral tablet tiers reflects extended FDA ANDA review timelines that protect incumbent pricing while delaying cost competition from Dr. Reddy's Laboratories and Intas Pharmaceuticals. Three-tier pricing structure across premium nanoparticle formulations, standard oral tablets, and economy generics anchors the market, with FDA bioequivalence certification and hospital formulary status serving as the primary differentiation drivers. Pricing pressure intensifies in the injectable segment as Seoul-based CMOs expand sterile capacity for Japanese transplant networks. Academic medical centers in the United States exhibit lowest price sensitivity due to bioavailability monitoring requirements, while Indian government hospital procurement demonstrates highest sensitivity.
Supply Chain Analysis
Direct-to-transplant-center channels handle acute injectable demand, while oral tablet distribution runs through hospital formulary committees and retail pharmacy networks. Active pharmaceutical ingredient supply concentrates in South Korean Songdo bioreactor parks, Chinese fermentation facilities, and select Indian Hyderabad manufacturing clusters. Streptomyces hygroscopicus cultivation, sterile filtration equipment, and polymer-coating technology for stent applications constitute critical input dependencies. Single-source vulnerability in South Korean API supply creates structural risk exposure, particularly for Japanese prefectural medical networks dependent on Nagoya CMO finishing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fermentation-capable manufacturers with hospital formulary relationships, as FDA bioequivalence burdens and GMP suite fragmentation force sub-scale oral tablet producers toward exit.
For Market Incumbents: Deepen backward integration into Streptomyces hygroscopicus cultivation capacity in South Korean bioreactor parks to secure API supply against single-source concentration risk. Fortify hospital formulary positioning through therapeutic drug monitoring service bundling, countering everolimus and temsirolimus displacement in oncology protocols. Expand nanoparticle formulation R&D partnerships with Massachusetts academic medical centers to capture premium pricing for bioavailability-guaranteed delivery.
For New Entrants and Emerging Players: Begin with topical formulation development for tuberous sclerosis complex facial angiofibromas, exploiting EMA centralized procedures and unmet pediatric demand outside oral delivery paradigms. Target CDSCO streamlined approval pathways in Tamil Nadu and Karnataka government hospital expansions, where national transplant infrastructure investment creates volume growth corridors. Pursue WHO prequalification for Essential Medicines List procurement in sub-Saharan African markets previously dominated by tacrolimus.
For Investors and Strategic Acquirers: Re-rating potential sits with topical formulation specialists given EMA pediatric investigation plan streamlining and orphan drug exclusivity extensions. Long-term viability favors asset-light developers with regulatory arbitrage capabilities across FDA, EMA, and CDSCO frameworks. Monitor biosimilar litigation outcomes and mTOR inhibitor combination protocol adoption as inflection indicators for therapeutic positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA centralized procedures for fixed-dose tacrolimus-sirolimus combinations compress review timelines across German and French transplant networks. |
| Manufacturing Scale-Up | South Korean Songdo bioreactor park expansion addresses single-source vulnerability in Streptomyces hygroscopicus API supply. |
| Pipeline Diversification | Topical sirolimus creams for tuberous sclerosis complex exploit unmet pediatric demand outside established oral delivery paradigms. |
| Strategic Partnership | Massachusetts academic medical center alliances accelerate nanoparticle-encapsulated formulation pilots for erratic gastrointestinal absorption patients. |
| Geographic Expansion | CDSCO streamlined pathways align with Tamil Nadu and Karnataka government hospital transplant infrastructure investment. |
Research Methodology
Multi-period observation of FDA ANDA approval timelines, EMA centralized authorization patterns, and METI reimbursement adjustments anchored the trend analysis, supplemented by interviews with drug development executives at fermentation-capable manufacturers, regulatory affairs leads navigating orphan drug designation frameworks, hospital formulary directors in United States transplant centers, and procurement managers at Japanese prefectural medical alliances. Secondary validation drew from FDA Orange Book filings, EMA CHMP assessment reports, ClinicalTrials.gov mTOR inhibitor protocol registrations, and WHO Essential Medicines List procurement databases. Bottom-up oral tablet volume estimates and top-down immunosuppression market sizing were triangulated against hospital dispensing data.
Segment-weighted modeling across oral tablet, injectable solution, topical formulation, and drug-eluting stent delivery platforms structured the analytical framework, with therapy area splits for immunosuppression, oncology, dermatology, and cardiology applications further refining projections across the analysis window. CAGRs were derived from fitted growth curves calibrated to historical Medicare Part B reimbursement trends and Japanese METI policy adjustment impacts. Forecast inputs incorporated nanoparticle formulation adoption rates in United States academic centers and CDSCO approval velocity for Indian government hospital tenders.
Biosimilar litigation resolutions, mTOR biomarker expertise availability in clinical pharmacology departments, and fermentation capacity expansion decisions are the dominant revision risks for forecast trajectories. Practitioners should monitor EMA fixed-dose combination authorization timelines and Japanese prefectural purchasing alliance contract awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Global Biosimilars Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Dasatinib Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Etanercept Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market