
 Immunology Biosimilars Market | 2026-2036
Immunology Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Immunology Biosimilars Market Analysis
A shift from single-source reference biologics toward multi-source biosimilar procurement is rebalancing hospital and payer contracting strategies across major markets. Novartis AG leverages its Sandoz division's established European manufacturing footprint to sustain volume leadership in infliximab supply. Pfizer Inc. anchors its position through deep hospital system partnerships, while Samsung Bioepis differentiates via subcutaneous formulation development that reduces infusion center dependency.
Immunology biosimilars are recombinant protein therapeutics engineered to match the reference monoclonal antibody's amino acid sequence, glycosylation profile, and three-dimensional structure, manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter scale. These products serve primarily to expand patient access to TNF-alpha and CD20-targeted therapies for autoimmune indications at reduced cost. Adalimumab biosimilars command the largest revenue pool as the reference Humira franchise faced US patent expiry, while subcutaneous delivery modes are attracting the fastest volume growth due to home administration economics. Rheumatoid arthritis remains the most mature therapy area with established switching protocols, whereas inflammatory bowel disease presents higher margin potential given gastroenterologist preference for real-world efficacy data.
The FDA's interchangeable designation pathway and the EMA's biosimilar guidelines collectively determine prescriber substitution authority and pharmacy-level substitution across their respective jurisdictions. Health Canada's post-market surveillance requirements and Australia's PBS listing criteria further shape which products achieve sustainable reimbursement. Stakeholders must monitor evolving interchangeability legislation at the US state level and the EU's pending revisions to pharmacovigilance reporting obligations for switched patients.
Market Dynamics
The transition from intravenous to subcutaneous delivery formats is compressing infusion center capacity requirements and redistributing site-of-care economics across autoimmune therapy administration.
Growth Catalysts
- Interchangeable Designation Pathway:The FDA's interchangeable biosimilar framework grants pharmacy-level substitution authority without prescriber intervention, accelerating volume uptake in US retail and hospital outpatient settings.
- TNF-alpha Inhibitor Patent Expiry Wave:Reference product exclusivity losses across adalimumab and infliximab franchises in Germany, Japan, and the United States are triggering mandatory tendering processes and formulary restructuring.
- Continuous Manufacturing Adoption:Single-use bioreactor technology and perfusion cell culture methods are reducing batch-to-batch variability and accelerating time-to-market for secondary biosimilar entrants.
Market Restraints
- High Biosimilar Development Costs:Analytical characterization, clinical immunogenicity studies, and extensive PK/PD trials require capital deployment exceeding $100 million per molecule, creating barriers for mid-scale developers.
- Reference Product Lifecycle Management:Originators are deploying patent thickets, device-specific formulations, and indication expansion strategies to delay biosimilar erosion in inflammatory bowel disease and psoriasis segments.
- Immunogenicity Surveillance Burden:Post-market pharmacovigilance requirements for switched patients under EMA guidelines and FDA REMS programs impose ongoing data collection costs that compress net margins.
Strategic Opportunities
- Japan's Accelerated Biosimilar Pathway:PMDA's streamlined review process for well-characterized biologics offers reduced approval timelines for developers with established European or US dossiers.
- Home Administration Economics:Subcutaneous pen and autoinjector formats enable self-injection protocols that shift reimbursement from hospital outpatient to pharmacy benefit structures, capturing margin from site-of-care differentials.
- Biosimilar-to-Biosimilar Switching Data:Real-world evidence generation from NOR-SWITCH, DANBIO, and other national registries is creating clinical confidence that supports multiple substitution cycles beyond the first switch.
Industry Challenges
- Analytical Biosimilarity Demonstration:Glycosylation pattern matching, charge variant profiling, and higher-order structure confirmation require specialized mass spectrometry and nuclear magnetic resonance capabilities that concentrate in limited contract testing organizations.
- Prescriber Confidence Building:Gastroenterology and rheumatology specialists demand indication-specific switching data that extends development timelines and requires investment in phase IV commitment studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunology Biosimilars Market |
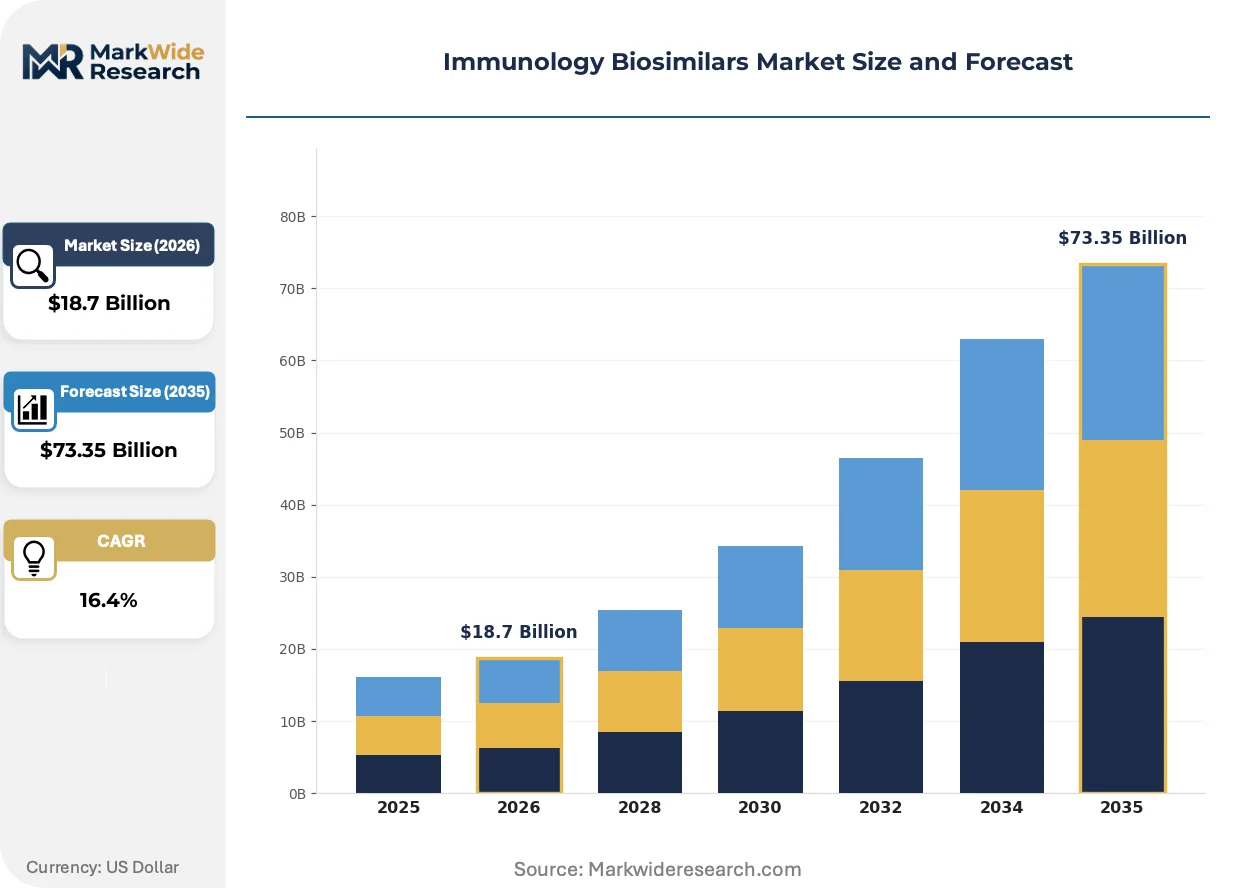
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infliximab, Adalimumab, Etanercept, Rituximab Therapy Area: Rheumatoid Arthritis, Psoriasis, Inflammatory Bowel Disease, Ankylosing Spondylitis Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Intramuscular Injection End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions |
| Companies Covered | Novartis AG, Pfizer Inc., Amgen Inc., AbbVie Inc., Celltrion Inc., Sandoz International GMBH, Samsung Bioepis, Biocon Ltd., Alvotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunology Biosimilars Market Emerging Trajectories
Delivery technology maturation and regulatory framework evolution are simultaneously expanding patient access channels and compressing the commercialization timeline for follow-on biologics in autoimmune therapy.
Subcutaneous formulation engineering is converging with connected health device integration. Autoinjector systems incorporating dose confirmation sensors and adherence tracking are capturing preference among US rheumatology practices managing large patient panels. This convergence is enabling pharmacy benefit managers to deploy outcomes-based contracts that tie reimbursement to injection frequency compliance.
EMA's pending revision to pharmacovigilance reporting obligations for switched patients will mandate enhanced adverse event capture across national registries. The industrial consequence is expanded investment in real-world data infrastructure by biosimilar sponsors seeking competitive differentiation through safety database depth. Germany's DIMDI and France's SNDS systems are most affected, with sponsors pre-positioning health economics and outcomes research capabilities.
Hospital pharmacy and therapeutics committees are consolidating formulary decisions through centralized procurement consortia. Multi-hospital health systems in the United States are displacing individual facility contracting with enterprise-level biosimilar agreements that bundle infliximab, adalimumab, and rituximab volumes. This concentration is most visible in Texas, California, and Florida, where integrated delivery networks command sufficient scale to negotiate reference product parity pricing.
Immunology Biosimilars Market Segmentation
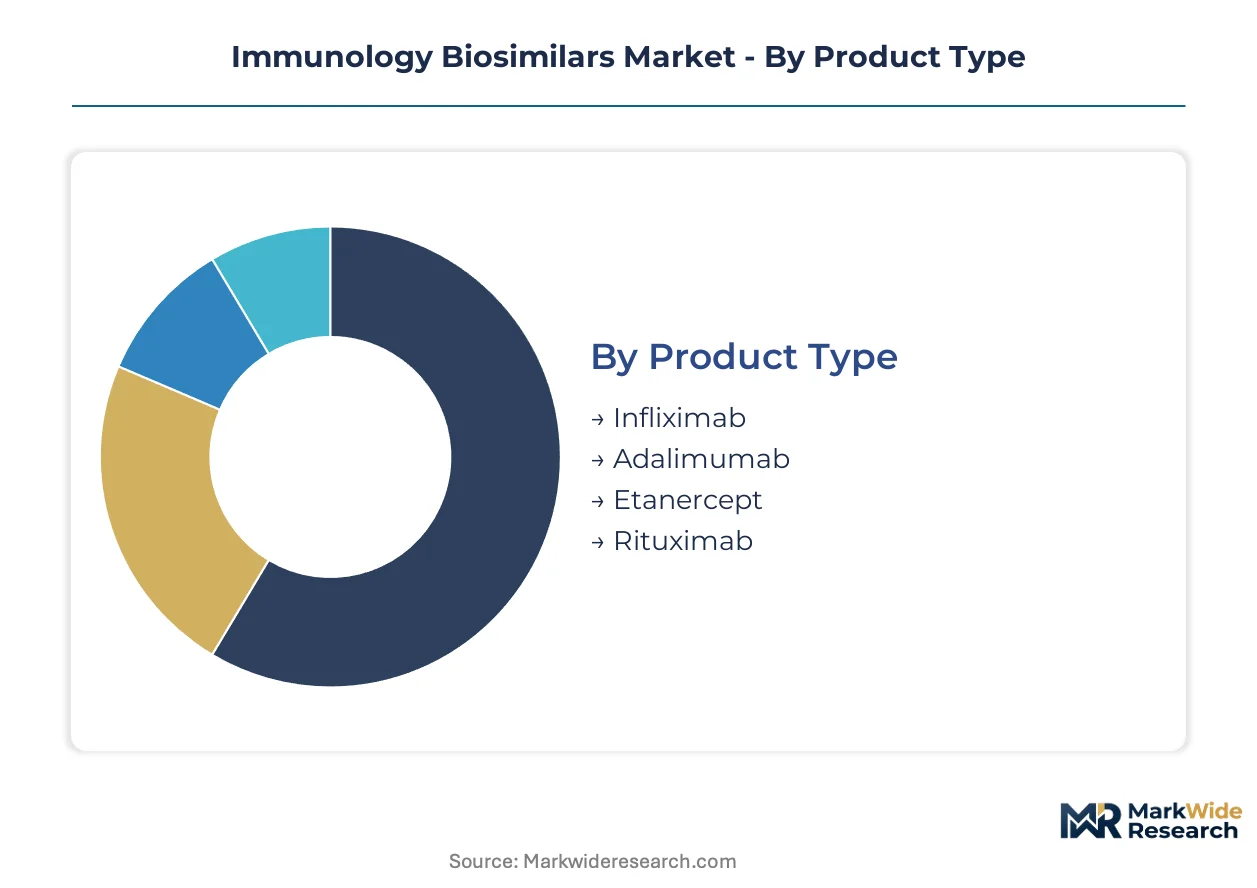
Segmentation in immunology biosimilars determines procurement pathways, reimbursement tiers, and site-of-care economics across autoimmune therapy administration. Each dimension shapes manufacturing scale requirements, regulatory dossier complexity, and prescriber substitution authority in distinct ways.
Product Type:
Standardization dominates infliximab and adalimumab manufacturing, while etanercept and rituximab retain greater formulation differentiation across sponsors.
- Adalimumab:Fully human anti-TNF-alpha monoclonal antibody with identical amino acid sequence to reference Humira. Demand concentrates in the United States where FDA interchangeable designation accelerates pharmacy-level substitution without prescriber consent.
- Infliximab:Chimeric monoclonal antibody requiring intravenous administration in infusion centers. Hospital procurement in Germany drives volume through mandatory tendering processes under national cost-containment mandates.
- Etanercept:Fusion protein construct linking TNF receptor to Fc portion of IgG1, manufactured in CHO cell lines with distinct glycosylation patterns from monoclonal antibodies.
- Rituximab:Anti-CD20 chimeric monoclonal antibody targeting B-cell depletion in rheumatoid arthritis, with oncology crossover applications complicating manufacturing capacity allocation.
Leading the category by volume: Adalimumab. Expanding most quickly: Infliximab biosimilars capturing hospital infusion center contracts.
Therapy Area:
Cost tier stratification separates mature rheumatoid arthritis protocols from higher-margin inflammatory indications where real-world evidence requirements delay biosimilar penetration.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis indications where gastroenterologists demand indication-specific switching data beyond rheumatology-derived immunogenicity profiles. Japan's PMDA accelerated pathway reduces approval timelines for developers with established European dossiers in this high-margin segment.
- Rheumatoid Arthritis:Most mature autoimmune indication with established NOR-SWITCH and DANBIO registry data supporting multiple substitution cycles. Home administration economics through subcutaneous pen formats shift reimbursement from hospital outpatient to pharmacy benefit structures.
- Psoriasis:Dermatology-managed indication where originator lifecycle management through device-specific formulations delays biosimilar erosion.
- Ankylosing Spondylitis:Spondyloarthritis subset with smaller patient populations but higher per-patient dosing intensity in axial skeleton involvement.
Dominant by patient volume: Rheumatoid Arthritis. Steepest margin expansion: Inflammatory Bowel Disease.
Delivery Mode:
Volume concentration favors intravenous formats in hospital systems, while margin capture shifts toward subcutaneous devices enabling site-of-care redistribution.
- Intravenous Infusion:Hospital-based administration requiring infusion center capacity and nursing supervision. Texas and California integrated delivery networks bundle infliximab volumes through enterprise-level procurement consortia.
- Subcutaneous Injection:Autoinjector and pen formats enabling self-administration with connected health device integration for dose confirmation and adherence tracking. Samsung Bioepis differentiates through reduced infusion center dependency in this fastest-climbing segment.
- Oral Administration:Small molecule immunosuppressants rather than biosimilars, included for competitive context in formulary positioning.
- Intramuscular Injection:Limited application in depot formulations for extended-release corticosteroid combinations, marginal to monoclonal antibody biosimilar portfolios.
Highest volume share: Intravenous Infusion. Gaining share fastest: Subcutaneous Injection.
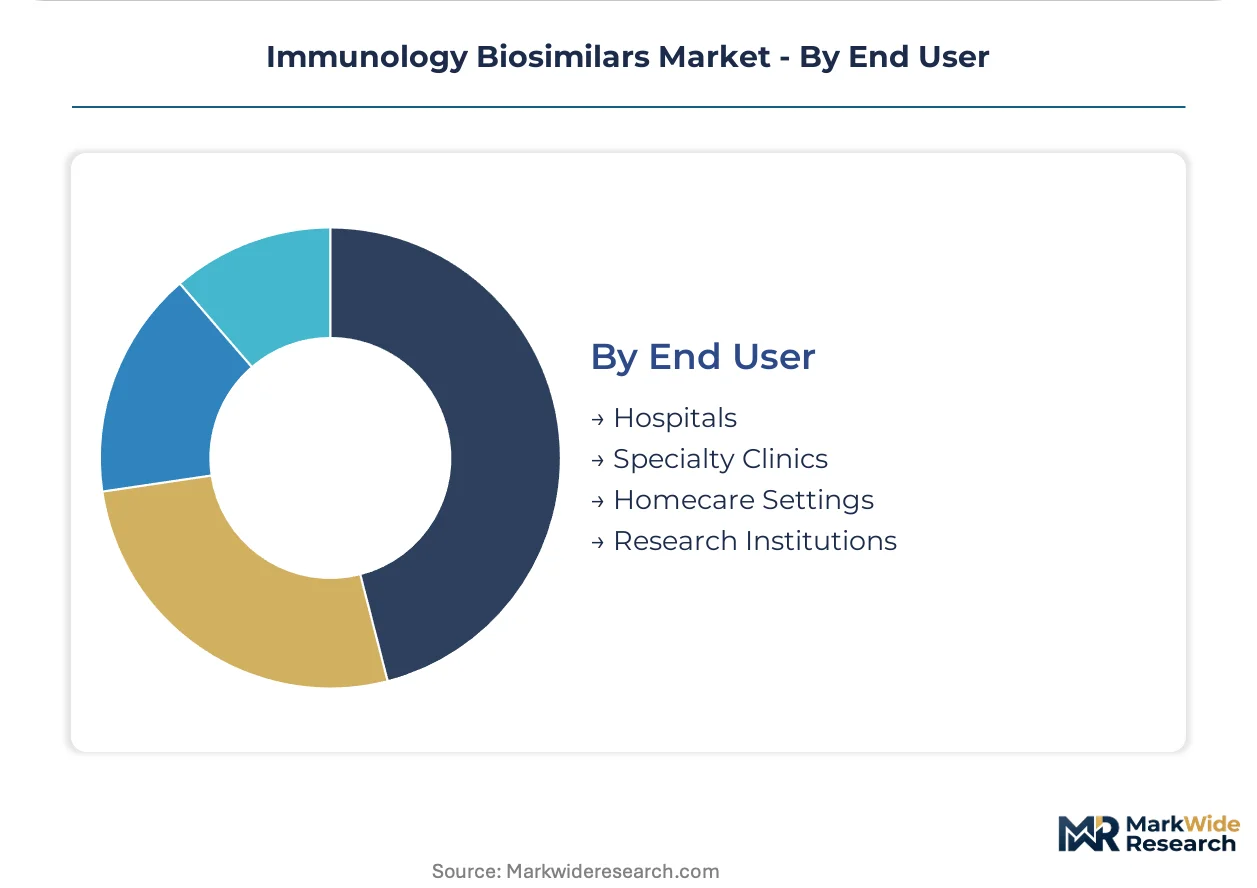
End User:
Customer type determines contracting sophistication, with hospital systems consolidating purchasing power while homecare channels capture pharmacy benefit margin.
- Hospitals:Pharmacy and therapeutics committees expanding formulary inclusion through multi-source procurement strategies. Pfizer Inc. anchors position through deep hospital system partnerships in Florida and Texas multi-hospital networks.
- Homecare Settings:Self-injection protocols shifting reimbursement structures and capturing site-of-care differentials through subcutaneous delivery economics.
- Specialty Clinics:Rheumatology and gastroenterology practices managing large patient panels with preference for real-world efficacy data.
- Research Institutions:Phase IV commitment studies and post-market surveillance generating switching data for EMA pharmacovigilance reporting obligations.
Procurement concentration: Hospitals. Fastest channel expansion: Homecare Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentration in the United States, Germany, and Japan is reshaping tendering dynamics and formulary restructuring across immunology biosimilars. National cost-containment mandates in these markets align with reference product patent cliffs to accelerate multi-source adoption. Manufacturing scale requirements favor established European and Asian production footprints.
United States
FDA interchangeable designation for adalimumab biosimilars grants pharmacy-level substitution authority without prescriber intervention. The IRA's Medicare price negotiation provisions compress reference product pricing power and expand biosimilar volume eligibility. Texas and California integrated delivery networks bundle infliximab, adalimumab, and rituximab volumes through enterprise-level procurement consortia commanding reference product parity pricing.
Germany
Mandatory tendering processes under national cost-containment mandates drive infliximab biosimilar penetration through hospital pharmacy committees. EMA pharmacovigilance reporting obligations for switched patients mandate enhanced adverse event capture through Germany's DIMDI registry system. Bavaria and North Rhine-Westphalia manufacturing clusters sustain Sandoz division's European volume leadership in mammalian cell culture production.
Japan
PMDA's accelerated biosimilar pathway reduces approval timelines for developers with established European or US dossiers, particularly in inflammatory bowel disease indications. National health insurance reimbursement revisions favor subcutaneous delivery formats shifting site-of-care economics. The Kanto region around Tokyo anchors specialist rheumatology and gastroenterology practice networks generating real-world switching data.
United Kingdom
NHS England's biosimilar procurement frameworks mandate rapid uptake targets for adalimumab and infliximab following reference product exclusivity loss. NICE technology appraisals increasingly incorporate real-world evidence from NOR-SWITCH and DANBIO registries to support multiple substitution cycles. The Greater London and Southeast England hospital networks concentrate pharmacy and therapeutics committee formulary decision-making.
India
CDSCO streamlined approval processes for well-characterized biologics attract secondary biosimilar entrants seeking cost-advantaged manufacturing scale. Domestic demand for TNF-alpha inhibitors expands through government health insurance schemes covering autoimmune indications. Hyderabad and Bangalore biotech clusters concentrate contract development and manufacturing capabilities serving European and US sponsor requirements.
Immunology Biosimilars Market Vendor Landscape
Capacity expansion dominates the current landscape as established players scale mammalian cell culture facilities beyond 10,000-liter bioreactor volumes. The market structure concentrates around three strategic tiers: originator biopharmaceuticals defending franchise erosion, diversified generics-multinationals leveraging hospital system partnerships, and Asian biotech specialists pursuing subcutaneous formulation differentiation. Vertical integration into single-use bioreactor technology and perfusion cell culture methods represents the primary competitive vector, alongside real-world evidence generation capabilities for pharmacovigilance compliance.
Within the diversified generics-multinational tier, Novartis AG and Pfizer Inc. exemplify divergent geographic anchoring strategies. Novartis leverages its Sandoz division's established European manufacturing footprint to sustain volume leadership in infliximab supply chains serving German hospital procurement. Pfizer anchors position through deep hospital system partnerships in Texas and Florida multi-hospital networks. Samsung Bioepis occupies a distinct position among Asian biotech specialists, differentiating through subcutaneous formulation development that reduces infusion center dependency and captures pharmacy benefit margin.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| AbbVie Inc. |
| Celltrion Inc. |
| Sandoz International GMBH |
| Samsung Bioepis |
| Biocon Ltd. |
| Alvotech |
| Others |
Supply Flow & Price Mechanics
CHO cell culture media price indices cascade through mammalian bioreactor operations into three-tier pricing structures across premium interchangeable, standard biosimilar, and economy tender-contract tiers. German hospital procurement consortia leverage this input-cost transparency to negotiate reference product parity pricing for infliximab volumes.
Pricing Analysis
Volume concentration in intravenous infusion formats compresses per-unit margins, while subcutaneous autoinjector delivery commands premium-mid-economy pricing differentiation through pharmacy benefit structures. FDA interchangeable designation and EMA pharmacovigilance tiering separate premium-certified from standard-approved products, with cost compression in economy tiers intensifying due to mandatory tendering in German hospital systems. Hospital pharmacy committees exhibit highest price sensitivity through centralized procurement consortia, whereas specialty clinics managing large rheumatology panels demonstrate lowest sensitivity to device-integrated delivery premiums.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale procurement demand from Texas and California integrated delivery networks, while specialty distributors serve fragmented gastroenterology practices. Manufacturing gravity centers on Bavaria and North Rhine-Westphalia in Germany, the Kanto region in Japan, and Hyderabad-Bangalore clusters in India. Supply chains draw from recombinant protein feedstocks, single-use bioreactor assemblies, and glycosylation analysis reagents. Single-source vulnerability in contract testing organization capacity for mass spectrometry characterization presents structural risk to batch release timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over mammalian cell culture capacity and downstream real-world evidence generation infrastructure defines competitive durability in this vertical-integration race. Players securing captive bioreactor volumes and registry data partnerships capture sustainable margin positions.
For Market Incumbents: Acquire single-use bioreactor manufacturing assets and perfusion cell culture technology licenses to defend against Asian biotech specialists with subcutaneous formulation capabilities. Consolidate position through backward integration into glycosylation analysis contract testing capacity, countering the threat of EMA pharmacovigilance reporting obligations that favor sponsors with deep safety databases. For New Entrants and Emerging Players: The premium-to-economy tier price gap in Japanese inflammatory bowel disease indications opens white-space entry through PMDA's accelerated biosimilar pathway. Target homecare settings with connected health autoinjector devices, penetrating the fastest-expanding channel through pharmacy benefit reimbursement capture and adherence-tracking value propositions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale developers with established European dossiers and stranded manufacturing capacity in India's CDSCO-approved facilities. Long-term viability hinges on real-world evidence infrastructure depth; monitor NOR-SWITCH and DANBIO registry publication velocity as the inflection signal for substitution confidence maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | 10,000-liter bioreactor capacity expansion in Bavaria sustains Sandoz volume leadership for German hospital tenders. |
| Regulatory Approval Pathway | PMDA accelerated review for well-characterized biologics reduces time-to-market for inflammatory bowel disease entrants. |
| Backward Integration | In-house perfusion cell culture technology reduces batch-to-batch variability and accelerates secondary entrant commercialization. |
| Real-World Evidence Generation | Phase IV commitment studies in Germany's DIMDI registry build pharmacovigilance databases for competitive differentiation. |
| Distribution Channel Expansion | Homecare setting partnerships capture pharmacy benefit margin from subcutaneous self-injection economics. |
Methodological Framework
Multi-period observation of FDA interchangeable designation grants, EMA pharmacovigilance submission volumes, and German hospital tender award patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down revenue reconciliation provided analytical triangulation.
The input-output matrix framed demand projections across therapy area, delivery mode, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from patent expiry timing, mandatory tendering implementation schedules, and subcutaneous adoption curve modeling. Biosimilar-to-biosimilar switching registry publication rates and PMDA accelerated pathway utilization frequencies informed scenario-weighted outputs.
Inputs from FDA Orange Book listings and German DIMDI adverse event repositories were available through the study window; gaps in biosimilar-to-biosimilar switching immunogenicity data introduce uncertainty bands around inflammatory bowel disease penetration assumptions. Forecasts reflect documented assumptions regarding interchangeability legislation progression and EMA guideline revision timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Global Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Imatinib Drug Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Dasatinib Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Fusion Protein and Biosimilars Market