
 Global Biosimilars Market | 2026-2036
Global Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biosimilars Market Analysis
The capital-intensity divergence between large-scale biomanufacturers and emerging developers is rotating competitive advantage toward integrated production networks. Sandoz Group AG leverages its Novartis heritage to sustain European regulatory relationships and manufacturing depth. Samsung Bioepis anchors its position through captive cell-line development and South Korean bioprocessing infrastructure. Celltrion competes via aggressive pricing in oncology biosimilars across multiple markets.
Biosimilars are highly similar, non-inferior versions of approved biologic medicines, manufactured through recombinant DNA technology in living cell systems with demonstrated physicochemical and functional equivalence to reference products. Their primary purpose is expanding patient access to costly biologic therapies while generating healthcare cost savings for payers and health systems. Monoclonal antibodies command the largest revenue pool due to blockbuster reference product expirations and complex manufacturing barriers that limit competition. The autoimmune disorders therapy area generates substantial volume as payers mandate substitution policies for tumor necrosis factor inhibitors.
FDA interchangeability designations, EMA biosimilar approval pathways, and WHO prequalification standards collectively determine market access timelines and prescriber confidence across jurisdictions. These frameworks shape demand by defining switching protocols, pharmacovigilance requirements, and reimbursement eligibility that manufacturers must satisfy before commercial traction materializes. Stakeholders must monitor evolving FDA guidance on automatic substitution and emerging pharmacoeconomic evidence from real-world switching studies to anticipate which product categories will face accelerated competitive entry.
Market Dynamics
Patent cliff expirations for blockbuster monoclonal antibodies are compressing reference product exclusivity windows, forcing originators to defend franchises through litigation and formulation tweaks while biosimilar developers accelerate development timelines.
Growth Catalysts
- EMA interchangeability guidelines:Maturing standards across European member states enable automatic substitution protocols in hospital formularies, expanding prescriber confidence and payer adoption.
- Tumor necrosis factor inhibitors:Statutory health insurance funds in Germany mandate therapeutic substitution policies, generating volume commitments that anchor manufacturer revenue visibility.
- Continuous bioprocessing:Single-use bioreactor technologies reduce facility capital requirements and batch-to-batch variability, lowering barriers for emerging developers entering oncology biosimilars.
Market Restraints
- Cell-line development costs:Proprietary expression systems and clone selection timelines require substantial upfront investment before regulatory filing, concentrating viable development among well-capitalized players.
- Reference product lifecycle management:Originators deploy secondary patents, device improvements, and indication expansions to delay biosimilar entry, particularly in the US market where FDA exclusivity periods interact with patent thickets.
- Immunogenicity surveillance requirements:Post-marketing pharmacovigilance obligations for switching studies impose ongoing clinical trial burdens that extend cost recovery timelines.
Strategic Opportunities
- WHO prequalification pathway:Emerging market procurement through UN agencies and Gavi creates volume anchors for manufacturers willing to accept tiered pricing structures in low-income countries.
- Ophthalmology biosimilars:Ranibizumab and aflibercept reference product expirations open therapeutic areas with limited manufacturing competition and concentrated retinal specialist prescriber bases.
- Japan's biosimilar promotion policy:METI incentives for domestic manufacturing and PMDA accelerated review timelines reward localized production investments with faster market access.
Industry Challenges
- Analytical biosimilarity demonstration:Characterization of post-translational modifications and higher-order structure requires mass spectrometry and nuclear magnetic resonance expertise that competes with innovative biotech hiring pools.
- Commercial infrastructure buildout:Field medical teams, key account management for hospital systems, and payer contracting capabilities demand organizational investment that strains emerging developer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biosimilars Market |
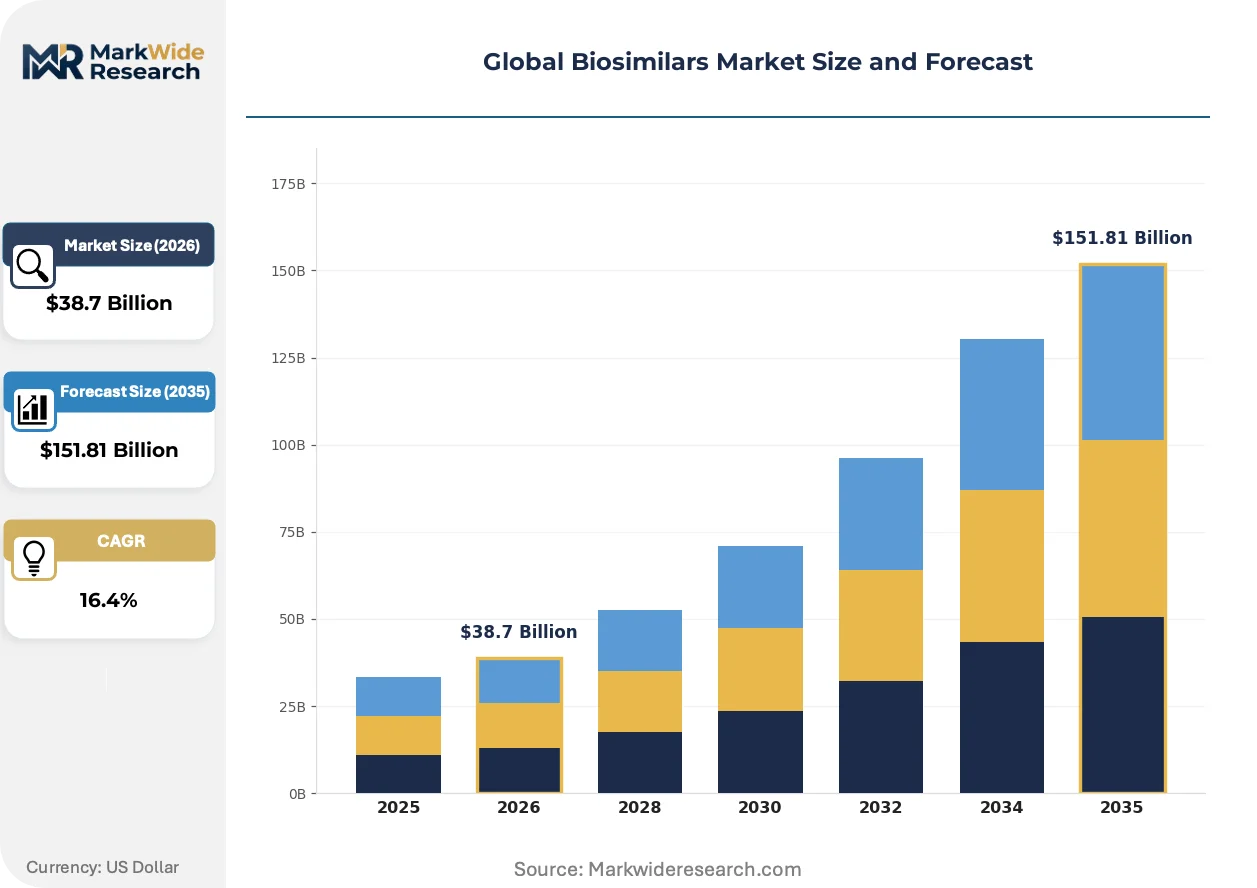
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Erythropoietin, Growth Factors Therapy Area: Oncology, Diabetes, Autoimmune Disorders, Infectious Diseases End User: Hospitals, Clinics, Specialty Pharmacies, Research Institutions Distribution Channel: Online Pharmacies, Retail Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Sandoz Group AG, Pfizer Inc., Amgen Inc., Novartis AG, Biocon Biologics, Samsung Bioepis, Celltrion, Shanghai Henlius Biotech, Coherus Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biosimilars Market Emerging Trajectories
Manufacturing technology convergence and regulatory science advances are compressing development timelines while expanding the addressable therapeutic space beyond established monoclonal antibody categories.
Single-use bioreactor systems with integrated process analytical technology controls are supplanting stainless-steel facilities for clinical-scale production. Mid-cap developers in South Korea and India adopt these platforms to avoid fixed-asset intensity. The shift enables rapid capacity scaling for Phase III material without multi-year construction timelines, compressing competitive entry for second-wave biosimilars.
FDA's evolving guidance on interchangeability designation criteria creates pathway clarity for automatic substitution eligibility. The industrial consequence is redirected R&D investment toward analytical similarity packages that support switching study designs. Oncology and immunology segments face the most pronounced response, with developers prioritizing indications where pharmacy benefit managers can implement formulary exclusion without prescriber intervention.
Hospital system consolidation across the US and Western Europe concentrates purchasing decisions into centralized pharmacy and therapeutics committees. Integrated delivery networks negotiate exclusive contracts with single biosimilar suppliers, displacing fragmented physician-level prescribing. Germany's statutory health insurance tendering system exemplifies this concentration, where national procurement volumes anchor manufacturer commitment to supply security and price stability.
Global Biosimilars Market Segmentation
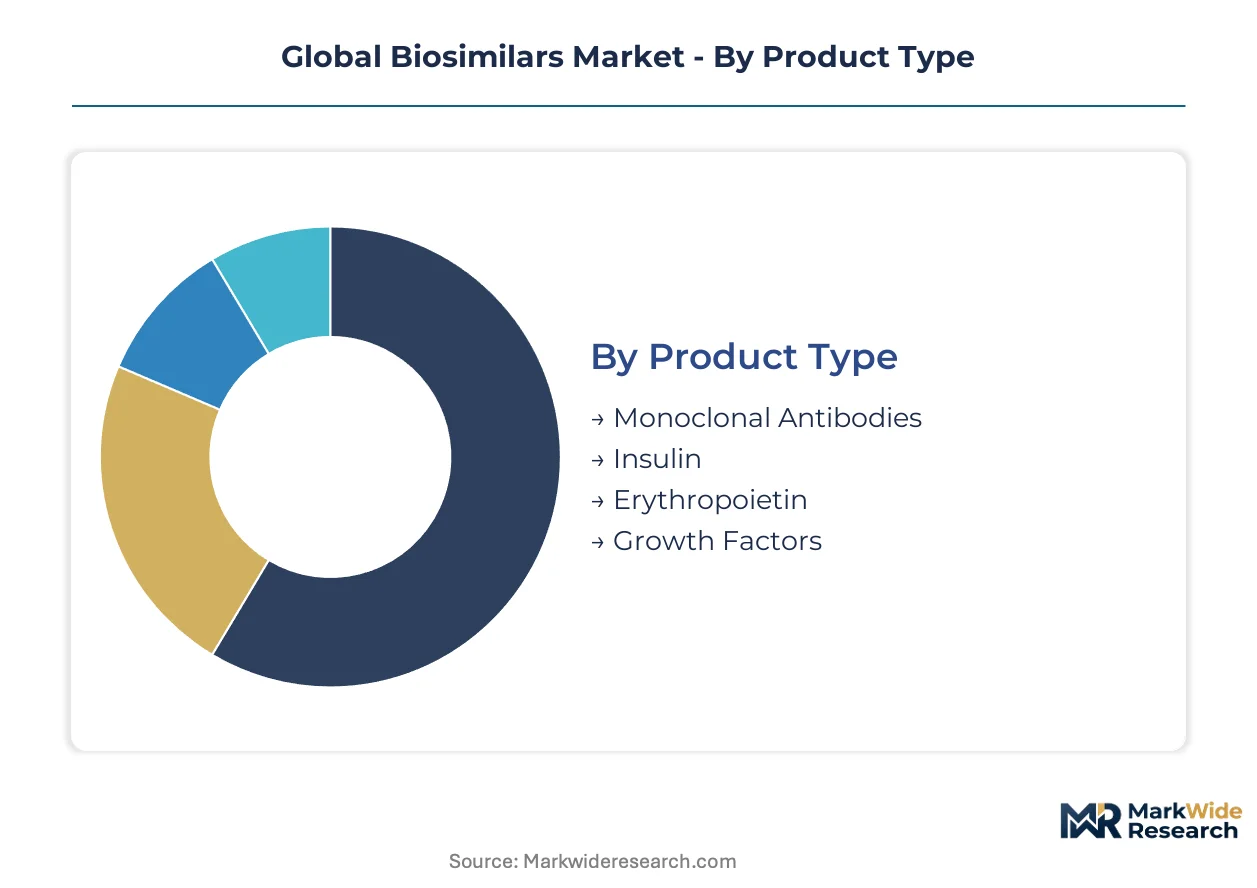
Segmentation in biosimilars reveals how manufacturing complexity, prescriber concentration, and payer procurement power distribute value across the value chain. Understanding these divisions clarifies where development investment concentrates and which access pathways determine commercial viability.
Product Type:
Margin pools concentrate in molecules with the highest manufacturing barriers and longest reference product exclusivity windows.
- Monoclonal Antibodies:Complex glycosylated proteins requiring mammalian cell culture and extensive analytical characterization. Demand concentrates in German hospital tenders for adalimumab and trastuzumab biosimilars as statutory health insurance funds mandate therapeutic substitution.
- Insulin:Recombinant peptide hormones with established biosimilar pathways but narrower price spreads due to reference manufacturer rebate strategies. Indian and South Korean developers target this segment for emerging market volume through WHO prequalification.
- Erythropoietin:Well-characterized biologics with mature competitive dynamics and compressed margins in European dialysis markets.
- Growth Factors:Niche oncology supportive care molecules with limited prescriber bases and hospital formulary gatekeeping.
Monoclonal antibodies hold installed capacity. Insulin is rotating up the share rankings.
Therapy Area:
Application concentration follows prescriber specialty density and payer reimbursement leverage.
- Oncology:Curative and supportive care indications with concentrated hospital-based prescribing and EMA interchangeability guidelines enabling automatic substitution. German statutory health insurance tendering anchors manufacturer revenue visibility for trastuzumab and rituximab biosimilars.
- Autoimmune Disorders:Chronic therapy models with pharmacy benefit manager formulary exclusion power. US commercial payers deploy step-therapy protocols that accelerate TNF inhibitor biosimilar uptake.
- Diabetes:Primary care prescribing with fragmented physician decision-making and insulin rebate complexity limiting biosimilar penetration.
- Infectious Diseases:Limited biosimilar development due to antimicrobial resistance priorities and vaccine-dominant prevention models.
Oncology commands prescriber attention. Autoimmune disorders are expanding most quickly through payer mandate expansion.
End User:
Customer type determines procurement concentration and the required field medical investment intensity.
- Hospitals:Centralized pharmacy and therapeutics committees with exclusive supplier contracting. Integrated delivery networks in the US and Western Europe displace fragmented physician prescribing through formulary control.
- Specialty Pharmacies:Hub-and-spoke distribution models for self-administered biologics with patient adherence programs and prior authorization management.
- Clinics:Outpatient infusion centers with mixed buy-and-bill and white-bag distribution depending on payer mix.
- Research Institutions:Limited commercial volume with investigator-initiated trial sourcing and biosimilar development partnerships.
Hospitals anchor procurement concentration. Specialty pharmacies are gaining share through patient support program differentiation.
Distribution Channel:
Channel selection shapes working capital requirements and direct-to-payer contracting relationships.
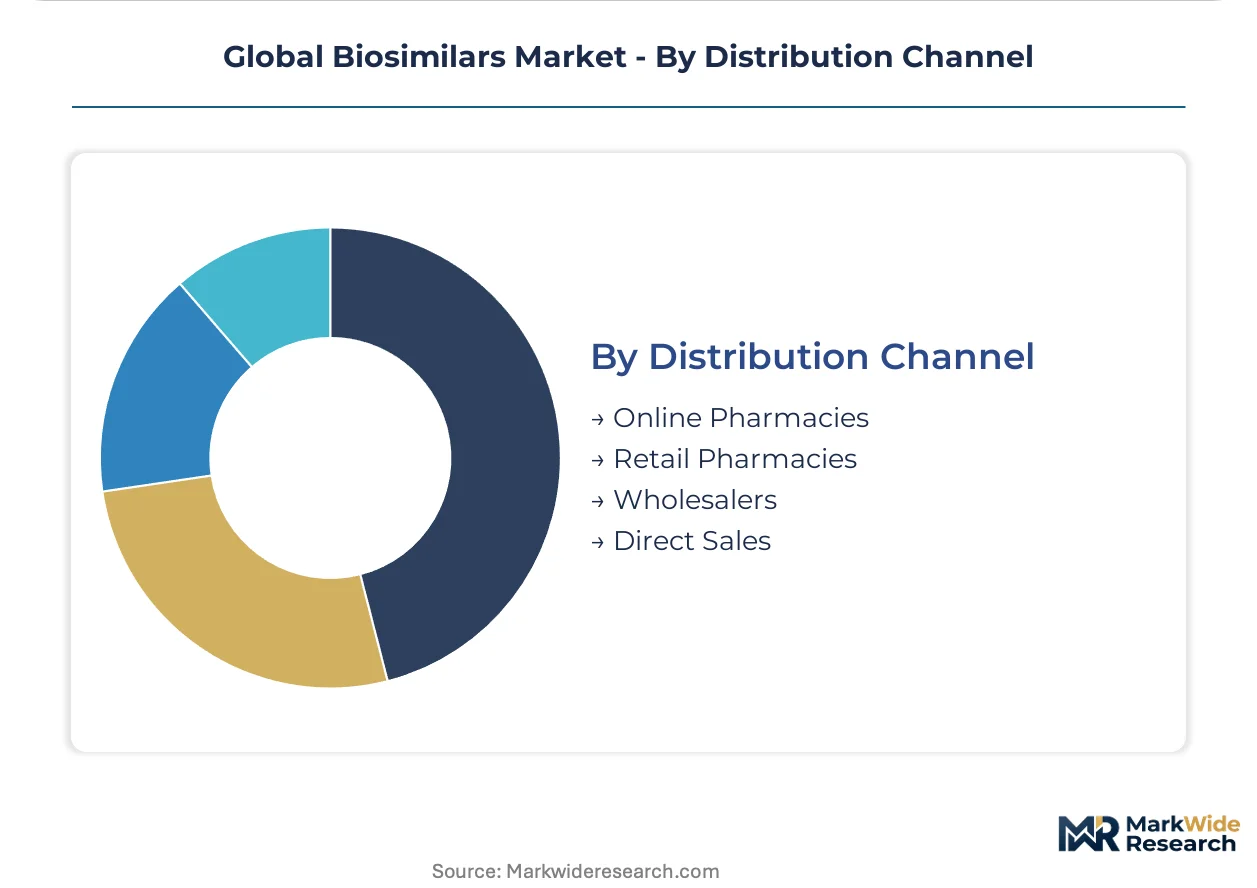
- Wholesalers:Three-tier distribution with chargeback administration and inventory financing for hospital system customers. McKesson, AmerisourceBergen, and Cardinal Health control US biosimilar logistics.
- Direct Sales:Manufacturer-to-hospital contracting for high-volume oncology biosimilars with price stability commitments and supply security guarantees.
- Retail Pharmacies:Limited biosimilar role due to cold-chain requirements and specialty dispensing complexity for self-injectable biologics.
- Online Pharmacies:Emerging channel for patient-direct fulfillment in markets with relaxed substitution regulations and mail-order pharmacy benefit designs.
Wholesalers maintain infrastructure dominance. Direct sales are climbing the fastest as hospital consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes biosimilars through centralized statutory health insurance tenders, while the United States relies on fragmented pharmacy benefit manager negotiations. Japan's METI promotion policy accelerates domestic manufacturing uptake. South Korean developers export through WHO prequalification pathways.
United States
FDA interchangeability designations and pharmacy benefit manager formulary exclusion power drive oncology and autoimmune biosimilar uptake. The Inflation Reduction Act reshapes Medicare reimbursement timelines. New Jersey and Massachusetts biopharma clusters host Sandoz and Amgen manufacturing and regulatory operations.
Germany
Statutory health insurance funds mandate therapeutic substitution for adalimumab and trastuzumab biosimilars through national tendering. EMA interchangeability guidelines enable automatic hospital formulary protocols. Bavaria's Munich biotech corridor anchors Celltrion European distribution headquarters and cold-chain logistics infrastructure.
Japan
METI biosimilar promotion policy incentivizes domestic manufacturing investments through tax credits and accelerated PMDA review timelines. Aging demographics expand oncology and diabetes biosimilar demand. Kansai's Osaka pharmaceutical cluster concentrates Samsung Bioepis partnership manufacturing and quality control operations.
South Korea
Samsung Bioepis and Celltrion anchor export-oriented production for EMA and FDA submission pathways. WHO prequalification opens emerging market procurement through UN agencies. Songdo biotech cluster integrates captive cell-line development with single-use bioreactor manufacturing scale.
India
Biocon Biologics leverages cost-advantaged bioprocessing for insulin and trastuzumab biosimilar exports to regulated markets. CDSCO accelerated approval pathways compress development-to-commercialization timelines. Karnataka's Bangalore biotech corridor concentrates contract development and manufacturing organization capacity for global sponsors.
Global Biosimilars Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with Swiss and German heritage conglomerates controlling European regulatory relationships and South Korean chaebol-affiliated developers dominating export manufacturing. Three archetypes define positioning: Novartis-heritage spinoffs with legacy manufacturing depth, captive bioprocessing specialists with in-house cell-line platforms, and emerging market cost leaders with WHO prequalification focus. Competitive moves concentrate on backward integration into expression system ownership and exclusive hospital system contracting through integrated delivery network partnerships.
Among heritage-integrated players, Sandoz Group AG and Novartis AG occupy positions sustained by European regulatory relationships and multi-product manufacturing depth. South Korean specialists Samsung Bioepis and Celltrion exemplify the captive development model, anchoring export competitiveness through integrated bioprocessing infrastructure and accelerated EMA filing timelines.
| Leading Market Players |
|---|
| Sandoz Group AG |
| Pfizer Inc. |
| Amgen Inc. |
| Novartis AG |
| Biocon Biologics |
| Samsung Bioepis |
| Celltrion |
| Shanghai Henlius Biotech |
| Coherus Biosciences |
| Others |
Supply Flow & Price Mechanics
Single-use bioreactor adoption replacing stainless-steel infrastructure simultaneously redistributes manufacturing toward South Korea and India while compressing capital-recovery timelines and intensifying price competition in oncology biosimilars. This substitution dynamic weakens incumbent facility advantages and accelerates tender-driven price erosion in German statutory health insurance markets.
Pricing Analysis
Long-term offtake agreements with hospital systems and integrated delivery networks dominate pricing structures, anchoring volume commitments against supply security guarantees. Three-tier pricing structure across premium EMA-interchangeable, standard approved, and economy WHO-prequalified levels differentiates based on regulatory certification tier and geographic delivery scope. Cost compression in TNF inhibitor segments is intensifying because statutory tendering in Germany mandates therapeutic substitution without prescriber override. Pharmacy benefit managers in the US exhibit highest price sensitivity through formulary exclusion power, while Japanese hospital procurement committees show lowest sensitivity due to METI quality premiums.
Supply Chain Analysis
Strategic stockpiling of master cell banks and working cell banks dominates inventory strategy given the multi-year clone selection timelines and single-source vulnerability for proprietary expression systems. Biomanufacturing supply concentrates in South Korea, Germany, and Switzerland, drawing from Chinese-sourced single-use bioreactor consumables, German-engineered process analytical technology systems, and US-origin cell culture media. Tariff exposure on Chinese-manufactured single-use components presents structural supply chain risk amid ongoing trade policy volatility. Distribution runs through wholesaler-mediated chargeback systems for hospital customers and direct manufacturer contracting for high-volume oncology tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biosimilars market sits in early-cycle expansion as EMA interchangeability guidelines mature and automatic substitution protocols activate across European hospital formularies, accelerating prescriber confidence and payer adoption velocity.
For Market Incumbents: Compound manufacturing depth advantages through captive cell-line platform ownership and exclusive integrated delivery network partnerships that lock out emerging competitors. Defend position against South Korean export specialists by accelerating FDA interchangeability submissions for automatic substitution eligibility, while building cold-chain logistics redundancy to meet German tender supply security requirements.
For New Entrants and Emerging Players: Differentiate on WHO prequalification pathway speed and tiered pricing structures for emerging market procurement through UN agencies and Gavi. Ophthalmology biosimilars for ranibizumab and aflibercept represent the most penetrable segment given limited manufacturing competition and concentrated retinal specialist prescriber bases. Target Japan's METI incentive framework for domestic manufacturing investments that unlock accelerated PMDA review timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated bioprocessing specialists with in-house expression system ownership over asset-light developers dependent on contract manufacturing. Acquisition targets should demonstrate captive cell-line platforms, EMA filing track records, and established relationships with German statutory health insurance tendering bodies. The signal to watch is FDA interchangeability designation velocity for automatic substitution eligibility as an inflection indicator for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Interchangeability Submission | Automatic substitution eligibility in German hospital formularies accelerates prescriber adoption and payer commitment. |
| Captive Cell-Line Development | In-house expression system ownership reduces clone selection timelines and insulates against proprietary platform licensing costs. |
| Integrated Delivery Network Partnership | Exclusive contracting with US hospital systems displaces fragmented physician prescribing through centralized pharmacy control. |
| WHO Prequalification Pathway | UN agency and Gavi procurement opens emerging market volume anchors with tiered pricing acceptance. |
| Single-Use Bioreactor Scale-Up | South Korean and Indian manufacturing avoids fixed-asset intensity and compresses competitive entry timelines. |
Methodological Framework
A standing panel of regulatory affairs leads, hospital formulary directors, payer access specialists, and bioprocess engineers provided ongoing calibration across the research period. Primary interviews with biosimilar development executives and procurement managers at German statutory health insurance funds combined with secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital tender documentation. Bottom-up manufacturer capacity assessments and top-down payer expenditure analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including monoclonal antibody product types, oncology and autoimmune therapy areas, hospital and specialty pharmacy end users, and regional regulatory clusters. CAGRs were derived from patent expiration timelines, biosimilar approval pathway velocity, and tender adoption curves. Forecast inputs incorporated EMA interchangeability guideline evolution, FDA automatic substitution policy development, and WHO prequalification expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EMA regulatory convergence, continued German tender mandate expansion, and stable single-use supply chain access would require recalibration. Forecasts reflect assumptions regarding prescriber confidence building, payer substitution policy enforcement, and manufacturing scale-up execution. Revision becomes warranted when FDA interchangeability designation criteria or EMA automatic substitution protocols cross material threshold changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Europe Generic Injectables Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Etanercept Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market