
 Global Biosimilar Testing and Development Services Market | 2026-2036
Global Biosimilar Testing and Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biosimilar Testing and Development Services Market Analysis
Buyer concentration among large biopharmaceutical developers is recalibrating contract priorities toward full-service outsourcing partnerships. WuXi AppTec leverages integrated analytical and clinical capabilities to anchor multi-phase programs for multinational sponsors. Eurofins Scientific competes through specialized biosimilar characterization platforms that extend across European and North American laboratories. Charles River Laboratories dominates preclinical toxicology segments where regulatory stringency demands dedicated capacity.
Biosimilar testing and development services encompass analytical characterization, immunogenicity assessment, clinical pharmacokinetic studies, and regulatory dossier preparation to establish biosimilarity with reference biologics. These services employ high-resolution mass spectrometry, surface plasmon resonance, and cell-based potency assays to demonstrate structural and functional equivalence for commercial authorization. Analytical testing and clinical trials command the deepest margin pools as therapy-area complexity rises in oncology and autoimmune disorders. Outsourced services capture expanding share as sponsors seek to reduce fixed-cost infrastructure while accelerating timeline-sensitive regulatory submissions.
FDA biosimilar guidance and EMA scientific advice procedures shape development program design and endpoint selection for sponsors targeting major markets. India's CDSCO and Germany's BfArM participate in reference-standard harmonization that streamlines multi-jurisdiction filing strategies. The EU AI Act introduces computational validation requirements that will reshape bioanalytical data integrity protocols. Stakeholders must monitor evolving FDA interchangeability standards and emerging WHO prequalification pathways to align capability investments with accessible revenue pools.
Market Dynamics
Regulatory convergence between FDA and EMA approval pathways is compressing development timelines while concentrating outsourced testing demand among laboratories with dual-jurisdiction capabilities. Sponsors now prioritize contract partners who can execute analytical characterization and clinical pharmacology under unified quality systems.
Growth Catalysts
- EMA Scientific Advice Procedures:Streamlined biosimilar development pathways in the European Union reduce regulatory uncertainty and accelerate sponsor decisions to outsource complex analytical packages.
- Oncology Biosimilar Pipelines:Rising development activity in monoclonal antibody therapies is expanding demand for immunogenicity assessment and cell-based potency validation services.
- India CDSCO Harmonization:Alignment with WHO prequalification standards positions Indian contract laboratories to capture multi-jurisdiction filing support from emerging-market sponsors.
Market Restraints
- Reference Standard Supply Constraints:Limited availability of originator biologic batches for comparability studies creates bottlenecks in analytical program initiation.
- Specialized Equipment Capital Intensity:High-resolution mass spectrometry and surface plasmon resonance platforms require seven-figure investments that restrict laboratory expansion.
- EU AI Act Validation Burden:Computational data integrity requirements for bioanalytical software are extending method qualification timelines and increasing compliance costs.
Strategic Opportunities
- Brazil ANVISA Pathway Expansion:Underdeveloped local testing capacity creates openings for international laboratories to establish South American reference-standard distribution hubs.
- Continuous Manufacturing Integration:Convergence of process analytical technology with biosimilar characterization enables real-time release testing service offerings.
- Interchangeability Study Demand:FDA switching study requirements for automatic substitution designation represent a discrete, high-margin service category.
Industry Challenges
- Mass Spectrometry Specialist Scarcity:Shortage of PhD-level analytical scientists with biopharmaceutical method development experience constrains laboratory throughput expansion.
- Multi-Site Study Coordination Complexity:Global clinical pharmacology trials spanning United States, Germany, and India sites require harmonized bioanalytical methods across disparate regulatory inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biosimilar Testing and Development Services Market |
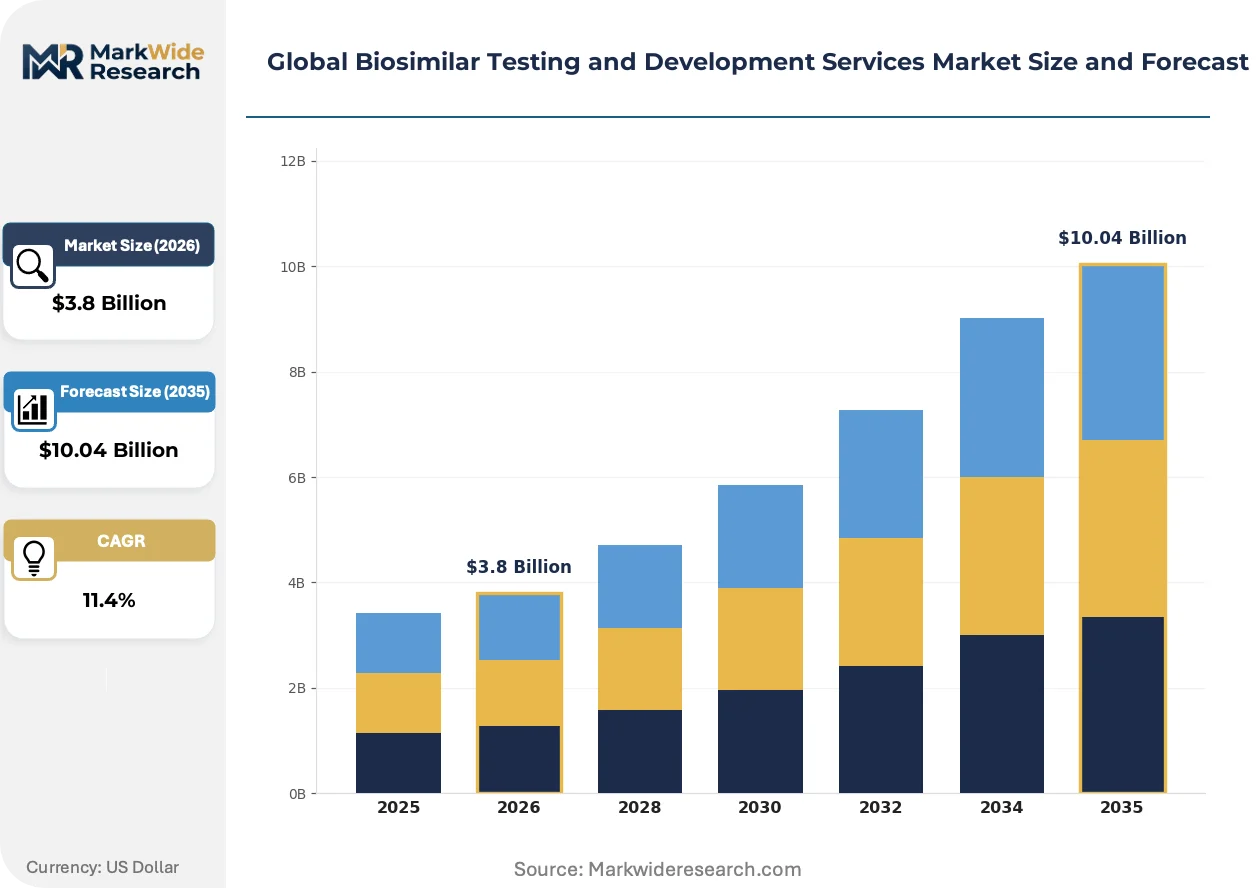
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Analytical Testing, Clinical Trials, Regulatory Services, Stability Testing Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Cardiology Delivery Model: In-House Services, Outsourced Services, Hybrid Model, Strategic Alliances Phase: Preclinical, Phase I, Phase II, Phase III |
| Companies Covered | Intertek Group, WuXi AppTec, Eurofins Scientific, Pacific BioLabs, Sartorius, SGS, Thermo Fisher Scientific, Syngene International, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biosimilar Testing and Development Services Market Emerging Trajectories
High-resolution analytical platforms are compressing the traditional separation between structural characterization and functional assessment, enabling sponsors to submit integrated biosimilarity packages earlier in development cycles.
Multi-attribute monitoring by mass spectrometry is rewriting how sponsors demonstrate molecular equivalence to reference products. Large biopharmaceutical developers are adopting this platform for lot-release testing of biosimilar candidates. The technology is compressing the timeline between cell-line selection and regulatory dossier submission by integrating critical quality attribute assessment into a single analytical workflow.
EU AI Act computational validation mandates are reshaping data governance requirements for bioanalytical laboratories serving European markets. Automated system qualification protocols now require documented algorithmic transparency for analytical software. Contract testing organizations with pre-validated artificial intelligence frameworks are capturing preference among sponsors targeting EMA approval pathways.
Consolidated outsourcing models are displacing fragmented service procurement across analytical, clinical, and regulatory functions. Mid-sized biopharmaceutical developers are abandoning discrete vendor relationships in favor of integrated program management from single contract research organizations. This pattern is most visible among sponsors based in Germany and the United States who face compressed submission deadlines for oncology biosimilars.
Global Biosimilar Testing and Development Services Market Segmentation
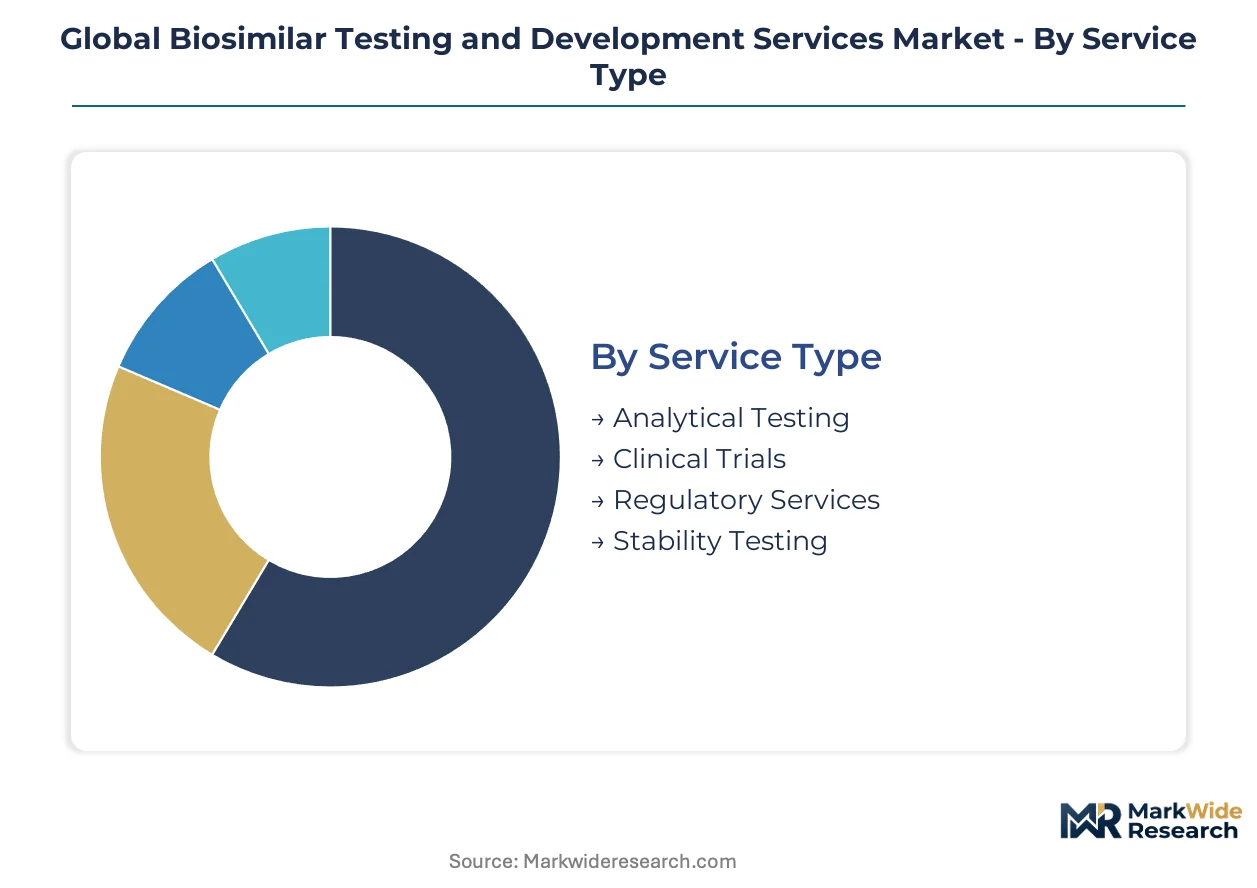
Biosimilar testing and development services fragment across four distinct dimensions that determine capital allocation, regulatory risk, and margin capture. Each segmentation layer reveals divergent cost structures and capability requirements that reshape vendor selection criteria for biopharmaceutical sponsors.
Service Type:
Analytical testing platforms demand the heaviest upfront capital commitment, with high-resolution mass spectrometry and surface plasmon resonance systems requiring seven-figure investments per installation.
- Analytical Testing:Structural and functional characterization employs mass spectrometry, chromatography, and binding assays to demonstrate molecular equivalence with reference biologics. Demand concentrates among United States and German sponsors seeking EMA and FDA dual-jurisdiction filing support, driven by regulatory stringency around critical quality attribute assessment.
- Clinical Trials:Pharmacokinetic and immunogenicity studies in human subjects require specialized bioanalytical laboratories with GLP certification and multi-site coordination capabilities. Sponsors in India and the United States are expanding outsourced clinical pharmacology programs to accelerate biosimilarity demonstration timelines.
- Regulatory Services:Dossier preparation and scientific advice navigation for FDA, EMA, and CDSCO submissions.
- Stability Testing:Long-term storage studies and forced degradation protocols under ICH guidelines.
Most installed capacity flows through Analytical Testing. Expansion is steepest in Clinical Trials.
Therapy Area:
Oncology commands premium pricing due to complex monoclonal antibody characterization requirements and higher immunogenicity risk profiles.
- Oncology:Monoclonal antibody biosimilars for cancer treatment require extensive cell-based potency assays and receptor binding studies. United States sponsors dominate demand as FDA interchangeability designations become critical for automatic substitution in oncology infusion centers.
- Autoimmune Disorders:TNF-alpha inhibitor biosimilars for rheumatoid arthritis and psoriasis demand rigorous immunogenicity assessment due to chronic dosing regimens. German and Indian sponsors are expanding development pipelines following EMA and CDSCO pathway harmonization.
- Infectious Diseases:Biosimilar development for antiviral and antibacterial biologics with shorter development timelines.
- Cardiology:Emerging biosimilar activity around anticoagulant and cardiovascular biologics with specialized safety endpoints.
Oncology absorbs the largest share of outsourced analytical spending. Autoimmune Disorders are gaining share fastest among emerging-market sponsors.
Delivery Model:
Hybrid arrangements balance fixed-cost control with surge capacity access during critical regulatory milestones.
- In-House Services:Captive analytical and clinical capabilities maintained by large biopharmaceutical developers with multi-product pipelines. United States and German sponsors retain structural characterization and regulatory strategy functions while outsourcing specialized bioanalytical work.
- Outsourced Services:Full-service contract research organization engagement for analytical, clinical, and regulatory functions. Indian sponsors increasingly favor this model to avoid capital-intensive laboratory infrastructure while accessing WHO prequalification-aligned capabilities.
- Hybrid Model:Split arrangements with in-house method development and outsourced confirmatory testing.
- Strategic Alliances:Long-term partnerships with preferred vendors across multiple development programs.
Outsourced Services carry the highest transaction volume. Strategic Alliances are expanding most quickly among mid-cap developers.
Phase:
Preclinical and Phase I stages concentrate analytical method development investment before pivotal trial initiation.
- Preclinical:In vitro and in vivo comparability studies establishing pharmacological and toxicological equivalence with reference products. Sponsors in Germany and the United States prioritize this phase for analytical platform qualification and critical quality attribute definition.
- Phase I:First-in-human pharmacokinetic studies demonstrating bioequivalence in healthy volunteers or target populations. Indian contract research organizations are capturing expanding Phase I volume due to cost advantages and CDSCO inspection readiness.
- Phase II:Confirmatory efficacy and safety studies in target patient populations.
- Phase III:Pivotal trials supporting regulatory submission and interchangeability designation.
Preclinical absorbs the deepest analytical investment per program. Phase I is climbing the fastest among outsourced service categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sponsors concentrate analytical spending on FDA interchangeability pathways, while German developers leverage EMA scientific advice to compress regulatory timelines. India contract laboratories capture Phase I volume through CDSCO-aligned capabilities and cost positioning.
United States
FDA interchangeability designations and oncology biosimilar pipelines drive demand for immunogenicity assessment and switching studies. The Biologics Price Competition and Innovation Act framework shapes sponsor outsourcing decisions toward full-service partners. Boston and San Francisco biotech clusters anchor multi-phase program management for monoclonal antibody developers.
Germany
BfArM reference-standard harmonization and EMA centralized procedures attract analytical characterization investment from European sponsors. The country's national pharmaceutical regulator maintains stringent GLP inspection protocols that favor established contract laboratories. Munich and Heidelberg life science corridors concentrate preclinical toxicology capacity for TNF-alpha inhibitor development.
India
CDSCO alignment with WHO prequalification standards positions domestic contract research organizations for emerging-market filing support. The national regulator's inspection readiness programs accelerate sponsor adoption of outsourced clinical pharmacology. Hyderabad and Bangalore biotech parks anchor Phase I bioequivalence studies for autoimmune disorder biosimilars.
China
NMPA biosimilar technical guidelines and expanding domestic biopharmaceutical pipelines elevate demand for analytical method development services. The national medical products administration's convergence with ICH standards enables multi-jurisdiction dossier preparation. Shanghai and Suzhou biopharma clusters integrate process analytical technology with biosimilar characterization workflows.
Switzerland
Swissmedic scientific advice procedures and proximity to EMA decision-making attract regulatory strategy outsourcing from mid-sized developers. The national regulatory agency's efficiency in biosimilar approvals compresses sponsor timeline risk. Basel and Zurich pharmaceutical corridors anchor stability testing and forced degradation protocols for European market access.
Global Biosimilar Testing and Development Services Market Vendor Landscape
United States-based laboratories anchor the premium analytical tier; Indian specialists hold cost-advantaged clinical pharmacology positions. The vendor base concentrates among integrated contract research organizations with dual-jurisdiction capabilities and specialized characterization platforms. Three archetypes dominate: full-service program managers, niche analytical specialists, and preclinical toxicology leaders. Capacity expansion and strategic technology licensing represent the dominant competitive moves as sponsors consolidate vendor relationships.
Within the integrated services tier, WuXi AppTec and Eurofins Scientific exemplify archetypes spanning analytical and clinical functions. Charles River Laboratories occupies a position representing preclinical toxicology concentration. These entities anchor competitive positioning through geographic coverage and regulatory jurisdiction alignment rather than discrete technology claims.
| Leading Market Players |
|---|
| Intertek Group |
| WuXi AppTec |
| Eurofins Scientific |
| Pacific BioLabs |
| Sartorius |
| SGS |
| Thermo Fisher Scientific |
| Syngene International |
| Charles River Laboratories |
| Others |
Supply Flow & Price Mechanics
Specialized mass spectrometry consumables and PhD-level analytical labor in United States and German laboratories cascade through three distinct pricing tiers, with reference-standard procurement costs in the premium segment compressing margins for mid-tier clinical pharmacology providers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for bioanalytical services, forcing established United States and European laboratories to differentiate on regulatory certification rather than cost. Three-tier pricing structure across premium, standard, and economy levels separates FDA-interchangeability-ready packages from emerging-market filing support. Pricing pressure stems from sponsor consolidation toward full-service outsourcing partnerships. Emerging-market biopharmaceutical developers exhibit highest price sensitivity; multinational sponsors with oncology pipelines prioritize regulatory certainty over cost minimization.
Supply Chain Analysis
Mass spectrometry specialist scarcity in United States and German manufacturing geographies constrains laboratory throughput expansion and extends method development lead times. Equipment manufacturing concentrates in United States, Germany, and Japan; reference biologic sourcing draws from Switzerland and United States originator repositories. Single-source vulnerability pervades high-resolution analytical platform supply. Distribution runs through direct manufacturer-laboratory relationships with extended qualification protocols for GLP-certified installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA interchangeability designations and EMA scientific advice procedures generate recurring demand for integrated testing capabilities.
For Market Incumbents: Anticipate sponsor consolidation toward full-service partners by deepening analytical-clinical integration and securing dual-jurisdiction GLP certifications. Defend against emerging-market cost competition through proprietary multi-attribute monitoring platforms and pre-validated EU AI Act compliance frameworks. Capacity additions in India threaten mid-tier pricing; anchor premium positioning through oncology immunogenicity specialization. For New Entrants and Emerging Players: Digital-channel routes through sponsor procurement platforms enable direct access to mid-cap biopharmaceutical developers abandoning fragmented vendor relationships. Target Brazil ANVISA pathway expansion and continuous manufacturing integration as white-space opportunities with limited incumbent saturation. Position through CDSCO-aligned Phase I capabilities for emerging-market sponsors seeking WHO prequalification support. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory networks lack dual United States-European jurisdiction coverage and sponsors demand unified program management. Five-to-ten-year viability favors integrated contract research organizations with validated AI frameworks and reference-standard distribution control. Monitor FDA interchangeability study volume as inflection indicator for high-margin service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Integration | Unified FDA-EMA submission packages reduce sponsor timeline risk and vendor switching. |
| Multi-Attribute Monitoring Platform Deployment | Mass spectrometry integration compresses cell-line selection to dossier submission timelines. |
| EU AI Act Compliance Pre-Validation | Algorithmic transparency documentation captures EMA pathway preference among European sponsors. |
| Reference Standard Distribution Hub Establishment | Brazil ANVISA-aligned storage infrastructure addresses South American supply constraints. |
| Continuous Manufacturing Partnership | Process analytical technology convergence enables real-time release testing service offerings. |
Methodological Framework
Direct dialogue with biosimilar development executives, regulatory affairs leads at contract research organizations, reference standard procurement managers, and CDSCO inspection coordinators grounded qualitative findings in operational reality. Secondary validation drew from FDA biosimilar approval databases, EMA scientific advice records, ClinicalTrials.gov protocol registrations, and WHO prequalification inspection reports. Bottom-up and top-down triangulation reconciled laboratory capacity estimates with sponsor pipeline announcements.
Bottom-up modeling built from individual service line volumes across analytical testing, clinical trials, regulatory services, and stability testing, while top-down constraints applied therapy-area development trends and jurisdiction-specific filing patterns. Segmentation dimensions encompassed service type, therapy area, delivery model, and development phase. CAGRs derived from sponsor outsourcing propensity curves and regulatory pathway maturation timelines, with reference standard availability and mass spectrometry specialist supply as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence validation in bioanalytical software would alter the outlook for European market service demand. Forecasts reflect sponsor consolidation assumptions and regulatory convergence trajectories that could revise with FDA interchangeability standard changes or CDSCO inspection protocol shifts. Material deviation in reference standard supply availability or EU AI Act implementation timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Dasatinib Market
Biosimilars
Global Sirolimus Market
Biosimilars
Etanercept Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
US Biosimilars Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market