
 Service Lifecycle Management Application Market | 2026-2036
Service Lifecycle Management Application Market Size, Share, and Industry Trends Forecast 2026-2036
Service Lifecycle Management Application Market Outlook
Subscription-based software-defined maintenance is expanding the addressable revenue pool beyond perpetual licenses. PTC leverages its CAD-to-service data thread to anchor aftermarket revenue streams for industrial equipment makers. ServiceNow competes through workflow automation that unifies field service dispatch with enterprise IT operations. Siemens extends its digital twin infrastructure into predictive service scheduling for energy and rail clients.
Service Lifecycle Management Application denotes integrated software platforms that orchestrate post-sale service delivery, warranty administration, spare parts logistics, and field technician dispatch across product-installed bases. These systems typically integrate with ERP and IoT sensor networks to trigger condition-based interventions and automate entitlement verification. Cloud-based deployment captures the fastest expansion as manufacturers abandon on-premises infrastructure for elastic capacity during seasonal service peaks. The artificial intelligence technology segment leads margin contribution where predictive failure models reduce unplanned downtime for telecommunications and healthcare end users. Big data analytics remains mature but essential for warranty fraud detection and parts demand forecasting across multi-echelon distribution networks.
FDA 21 CFR Part 820 quality system requirements shape healthcare SLM configurations where service records must support device traceability. The EU AI Act and GDPR impose algorithmic transparency and data residency constraints on automated diagnostic and customer-facing service tools. NIST cybersecurity frameworks in the United States harden remote access protocols for connected field service equipment. Stakeholders must monitor evolving cross-border data localization mandates that fragment cloud architecture strategies and determine whether multi-tenant or sovereign private cloud deployment becomes the compliance default for regulated industries.
Market Dynamics
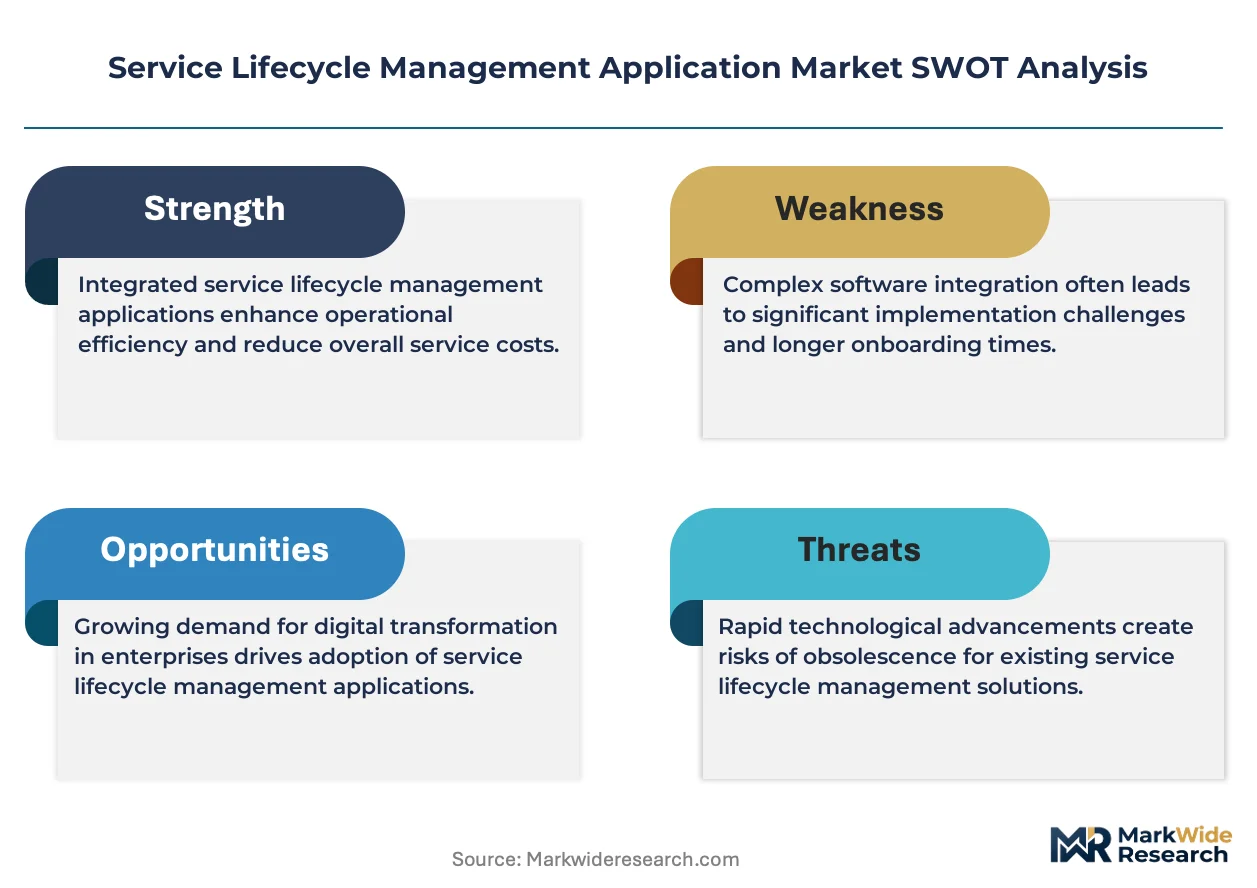
Cloud-native service orchestration is compressing deployment cycles from months to weeks while embedding AI-driven predictive maintenance directly into industrial equipment operating systems. This architectural shift forces vendors to restructure pricing models and partner ecosystems around consumption-based telemetry rather than seat licenses.
Growth Catalysts
- EU AI Act compliance mandates:Automated diagnostic tools require algorithmic transparency modules, driving replacement of legacy entitlement systems in Germany and France.
- Telecommunications infrastructure refresh:5G base station densification creates installed bases requiring condition-based intervention at scale.
- IoT sensor cost collapse:MEMS vibration and thermal sensors enable predictive failure models for mid-market industrial machinery previously served by scheduled maintenance.
Market Restraints
- Data residency fragmentation:Cross-border localization mandates in Saudi Arabia and India force multi-tenant architecture abandonment for sovereign private cloud builds.
- Legacy ERP integration debt:SAP and Oracle on-premises instances resist API-native connectivity, extending implementation timelines.
- Cybersecurity certification lag:NIST framework compliance for remote field equipment access adds six to nine months to product release cycles.
Strategic Opportunities
- Brazilian agricultural equipment aftermarket:Combine harvester OEMs lack integrated warranty-to-parts logistics, creating white space for cloud-native entrants.
- CSRD-driven service transparency:EU corporate sustainability reporting requirements position SLM platforms as carbon accounting infrastructure for industrial asset lifecycles.
- Digital twin convergence with AR:Siemens and PTC interoperability standards enable remote technician guidance overlaying real-time equipment telemetry.
Industry Challenges
- Field service engineer scarcity:Mechatronics technician training pipelines in Germany and Japan fail to match retirement-driven attrition.
- FDA 21 CFR Part 820 validation timelines:Healthcare device service records require traceability audits that compress software release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Lifecycle Management Application Market |
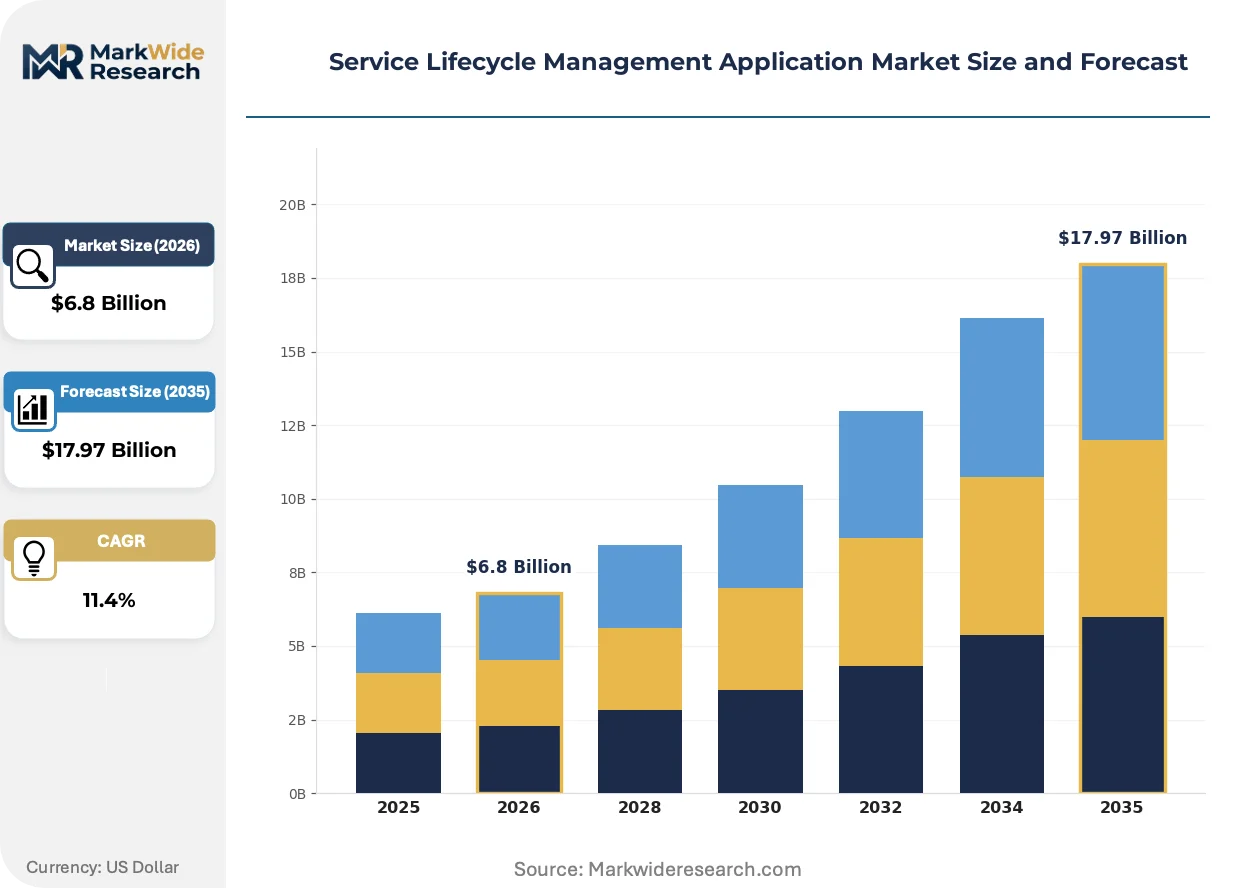
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Mobile End User: Manufacturing, Telecommunications, IT Services, Healthcare Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Single-Tenant Technology: Artificial Intelligence, Internet of Things, Big Data Analytics, Blockchain |
| Companies Covered | Atlassian, PTC, IBM, ServiceNow, SAP, Siemens, Oracle, Dassault Systèmes, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Lifecycle Management Application Market Strategic Shifts
Embedded AI inference at the edge is rewriting how service interventions trigger, shifting latency-sensitive diagnostics from cloud data centers to equipment-mounted processors. This decentralization demands new hardware-software co-design partnerships between SLM vendors and industrial OEMs.
Agentic AI systems are overtaking rule-based workflow automation in field service dispatch. These autonomous systems parse unstructured technician notes and IoT anomaly streams to generate intervention recommendations without human triage. German rail operators and Japanese precision tool manufacturers are piloting deployments that compress mean-time-to-repair by eliminating escalation layers. The structural consequence is overtaking traditional ERP-integrated ticketing systems that require manual status updates and supervisor approval loops.
REACH chemical substance restrictions are forcing spare parts logistics networks to requalify coating and lubricant inventories across European distribution hubs. Industrial valve and pump manufacturers must now trace SVHC content through multi-tier supplier declarations to maintain CE marking validity. German and Dutch MRO providers are responding by consolidating supplier bases to reduce documentation overhead, compressing available vendor pools for specialized components.
Equipment-as-a-service contracting is displacing traditional warranty-plus-break-fix procurement in compressed air and power generation verticals. Buyers in the United States and Japan now contract for guaranteed uptime rather than discrete repair events, transferring operational risk to OEMs. This shift forces SLM vendors to price predictive maintenance accuracy into platform subscriptions rather than per-incident service revenue.
Service Lifecycle Management Application Market Segmentation
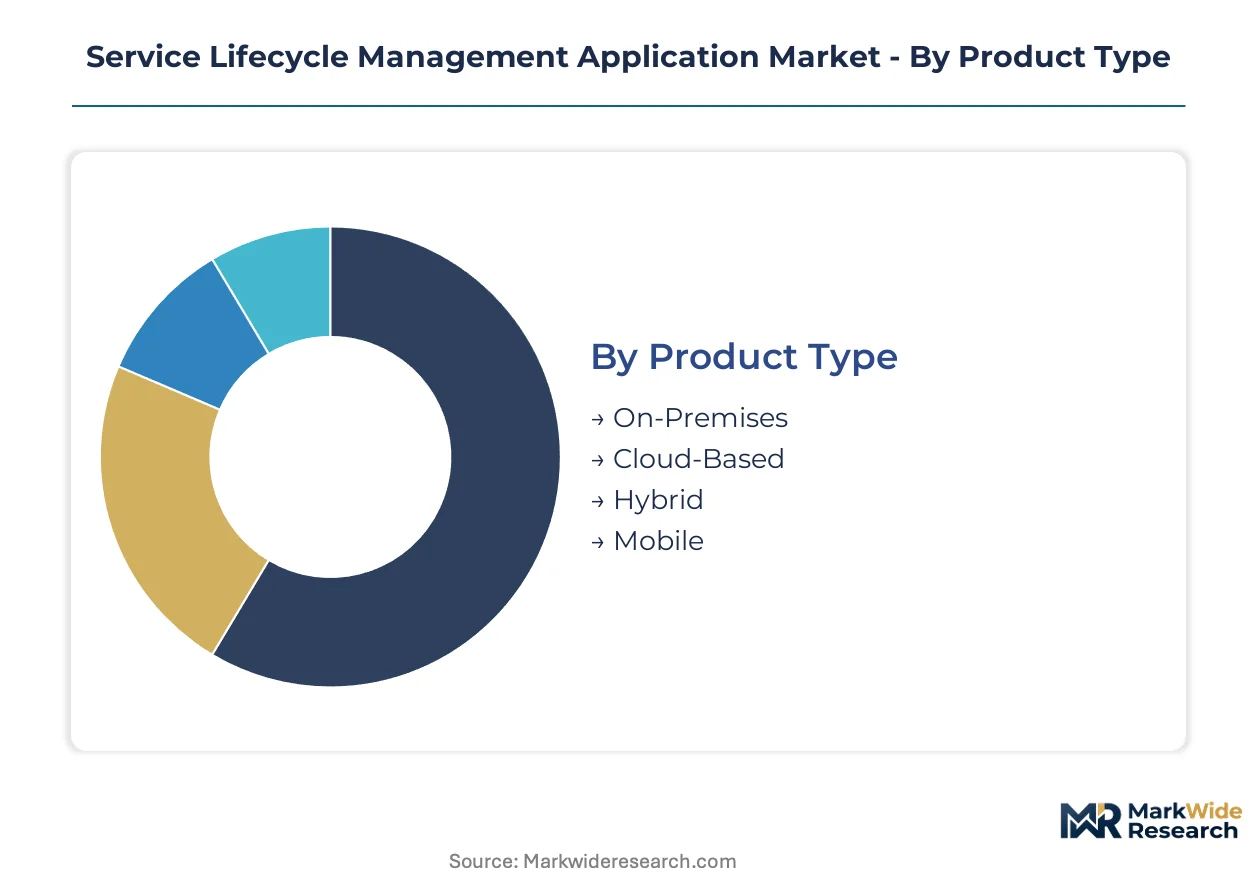
Service Lifecycle Management platforms serve heterogeneous operational environments where deployment architecture, data sensitivity, and regulatory exposure determine technology selection. Segmentation reveals how capital intensity and compliance requirements fragment purchasing behavior across industrial verticals.
Product Type:
Capital intensity varies sharply across deployment modes, with on-premises infrastructure demanding the heaviest upfront investment in server hardware, data center space, and dedicated IT staffing.
- Cloud-Based:Elastic compute resources eliminate fixed infrastructure commitments. Manufacturing enterprises in Germany and Japan favor this model for seasonal service peaks, though GDPR and EU AI Act compliance add governance module costs.
- On-Premises:Dedicated hardware installations support air-gapped environments for defense and classified industrial sites. Healthcare providers under FDA 21 CFR Part 820 requirements maintain these configurations for device traceability audit trails.
- Hybrid:Split architectures isolate sensitive entitlement data on-premises while pushing analytics workloads to public cloud tiers.
- Mobile:Lightweight field technician applications run on hardened tablets with offline synchronization capabilities.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated industries seek architectural compromise.
End User:
Application complexity and service network scale create divergent functional requirements across buyer categories.
- Manufacturing:Industrial OEMs manage multi-echelon spare parts distribution and warranty administration across global installed bases. German automotive suppliers and Japanese precision tool makers drive demand for predictive maintenance integration with digital twin platforms.
- Telecommunications:5G infrastructure densification creates geographically dispersed assets requiring condition-based intervention. Tower maintenance workflows in the United States compress mean-time-to-repair through AI-driven dispatch prioritization.
- IT Services:Managed service providers embed SLM capabilities into multi-tenant client delivery frameworks.
- Healthcare:Medical device manufacturers face FDA validation timelines that slow software release velocity while mandating service record traceability.
Manufacturing captures the largest revenue share. Telecommunications is gaining share fastest as infrastructure refresh cycles accelerate.
Deployment Model:
Data sovereignty requirements and cybersecurity certification lag reshape cloud architecture preferences across regulated jurisdictions.
- Private Cloud:Single-tenant environments satisfy Saudi Arabian and Indian data localization mandates. Sovereign builds add six to nine months to implementation timelines but prevent multi-tenant abandonment.
- Public Cloud:Shared infrastructure delivers lowest unit economics for mid-market industrial machinery operators with limited compliance exposure.
- Multi-Cloud:Distributed workloads across AWS, Azure, and regional providers reduce vendor concentration risk for critical service operations.
- Single-Tenant:Physically isolated instances support defense contractors and nuclear facility maintenance networks.
Private Cloud carries the highest implementation cost. Multi-Cloud adoption is climbing the fastest as buyers seek resilience against provider outages.
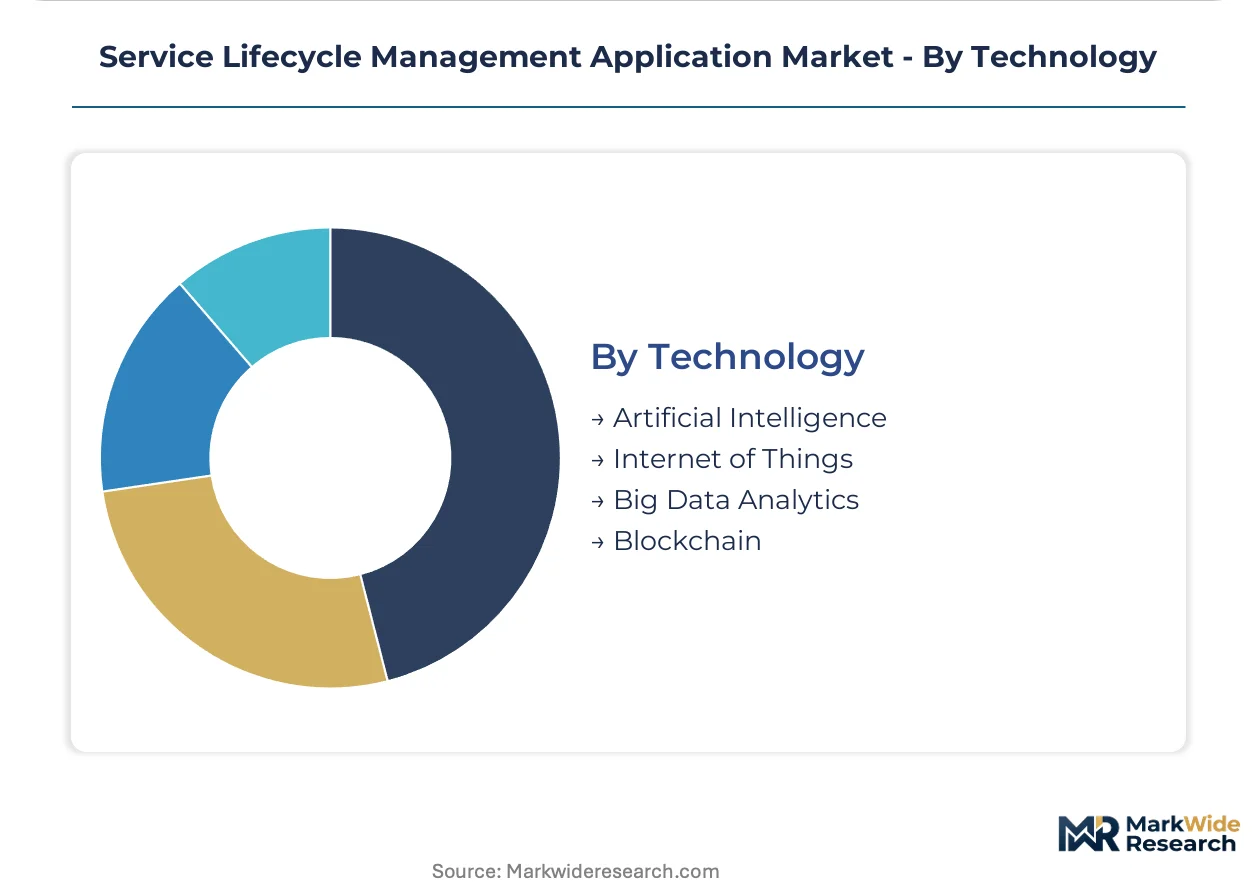
Technology:
Margin contribution and implementation maturity separate leading-edge capabilities from established infrastructure components.
- Artificial Intelligence:Predictive failure models reduce unplanned downtime for telecommunications base stations and healthcare imaging equipment. Edge inference capabilities shift latency-sensitive diagnostics from cloud data centers to equipment-mounted processors.
- Big Data Analytics:Warranty fraud detection and parts demand forecasting across distribution networks represent mature but essential applications. Multi-echelon inventory optimization relies on these pipelines.
- Internet of Things:MEMS vibration and thermal sensors enable condition-based maintenance for mid-market machinery previously served by scheduled interventions.
- Blockchain:Immutable service records support CE marking compliance and SVHC traceability under REACH chemical substance restrictions.
Big Data Analytics underpins the largest installed base. Artificial Intelligence is expanding most quickly as agentic systems overtake rule-based workflow automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as compliance costs diverge across jurisdictions. Manufacturers are relocating service data infrastructure to exploit gaps between EU AI Act stringency and emerging market enforcement timelines.
United States
Telecommunications infrastructure densification and defense contractor aftermarket networks drive platform demand. FDA 21 CFR Part 820 requirements enforce device traceability standards for medical equipment service records. Boston's healthcare technology cluster anchors predictive maintenance deployments for imaging equipment OEMs.
Germany
Industrial machinery OEMs manage complex multi-echelon spare parts distribution across European installed bases. EU AI Act algorithmic transparency mandates accelerate replacement of legacy entitlement systems in Bavaria and Baden-Württemberg. Stuttgart's automotive supplier ecosystem integrates SLM platforms with digital twin infrastructure for precision tool maintenance.
Japan
Precision equipment manufacturers and rail operators pilot agentic AI systems for autonomous field service dispatch. METI industrial data governance guidelines shape cloud architecture decisions for equipment-as-a-service contracts. Nagoya's manufacturing belt concentrates predictive maintenance deployments for machine tool OEMs transitioning to outcome-based revenue models.
India
IT services providers embed SLM capabilities into multi-tenant managed service delivery frameworks. BIS data localization requirements and RBI cybersecurity norms influence sovereign private cloud adoption for financial services equipment maintenance. Bengaluru's technology corridor hosts development centers for cloud-native service orchestration platforms targeting mid-market industrial machinery.
Brazil
Agricultural equipment OEMs lack integrated warranty-to-parts logistics, creating white space for cloud-native entrants. ANVISA medical device regulations extend to service record traceability for diagnostic equipment installed bases. São Paulo state's combine harvester manufacturing cluster represents the primary addressable market for aftermarket service digitization.
Service Lifecycle Management Application Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors holding consolidated positions in regulated verticals while mid-market niches fragment across regional specialists. The vendor ecosystem organizes around three strategic archetypes: CAD-integrated platform providers, ERP-native workflow orchestrators, and cloud-native field service specialists. Dominant competitive moves include AI capability acquisitions and vertical-specific compliance module development.
Within the CAD-integrated tier, PTC and Dassault Systèmes occupy positions anchoring aftermarket revenue streams through design-to-service data threads. ServiceNow and Atlassian exemplify the workflow automation archetype, with the former unifying field service dispatch with enterprise IT operations. These named entities represent how platform specialization vectors—engineering data heritage versus enterprise process orchestration—determine competitive positioning without overlapping segment coverage.
| Leading Market Players |
|---|
| Atlassian |
| PTC |
| IBM |
| ServiceNow |
| SAP |
| Siemens |
| Oracle |
| Dassault Systèmes |
| Microsoft |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracting in the United States and Japan is compressing margins on traditional break-fix revenue, forcing vendors to embed predictive maintenance accuracy into subscription tiers and restructure partner economics around consumption telemetry rather than per-incident fees.
Pricing Analysis
Distributor margins for on-premises SLM implementations run 15-25% above cloud-native equivalents due to hardware provisioning and dedicated staffing requirements. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive modules from basic entitlement management and legacy workflow tools. Pricing pressure stems from mid-market manufacturers in India and Brazil demanding consumption-based telemetry without upfront infrastructure commitments. Healthcare providers under FDA 21 CFR Part 820 requirements show lowest price sensitivity given validation timeline costs that lock in vendor relationships.
Supply Chain Analysis
Reverse logistics for refurbished spare parts and remanufactured field equipment concentrate in Germany, the United States, and China, where OEMs operate closed-loop inventory networks to satisfy REACH chemical substance traceability mandates. Critical component dependencies include MEMS vibration sensors from Japanese suppliers, edge inference processors from Taiwanese foundries, and hardened tablet hardware from South Korean manufacturers. Single-source vulnerability in EU-based cloud infrastructure threatens compliance timelines for GDPR data residency requirements. Distribution runs through direct OEM channels for enterprise accounts and regional system integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where buyers prioritize algorithmic transparency certifications and sovereign cloud deployment options over raw feature expansion, concentrating procurement authority with industrial OEMs managing complex aftermarket networks.
For Market Incumbents: Extend digital twin infrastructure into predictive service scheduling to anchor outcome-based contracts before cloud-native specialists capture equipment-as-a-service transitions. Consolidate API-native connectivity with SAP and Oracle ERP instances to reduce implementation timeline drag from legacy integration debt. Prioritize sovereign private cloud builds in Saudi Arabia and India ahead of data localization mandate enforcement. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for algorithmic transparency modules that displace legacy entitlement systems in Bavaria and Baden-Württemberg. Target Brazilian agricultural equipment OEMs lacking integrated warranty-to-parts logistics, where combine harvester clusters in São Paulo state represent immediate addressable white space. Lead with cloud-native deployment compressing implementation cycles from months to weeks against incumbent on-premises inertia. For Investors and Strategic Acquirers: Asymmetric upside sits with agentic AI specialists possessing autonomous field service dispatch capabilities that eliminate escalation layers in German rail and Japanese precision tool pilot deployments. Five-to-ten-year viability favors platforms with embedded governance modules satisfying cross-border compliance fragmentation rather than point solutions requiring custom integration. Monitor NIST cybersecurity certification timelines for remote field equipment access as inflection indicator for product release velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies field service dispatch with ERP and IoT sensor networks for condition-based intervention triggers. |
| Acquisition of Specialist Firm | Captures agentic AI capabilities for autonomous technician note parsing and anomaly stream processing. |
| Geographic Expansion | Establishes sovereign private cloud infrastructure in India and Saudi Arabia ahead of data localization enforcement. |
| Product Launch | Introduces embedded edge inference modules shifting latency-sensitive diagnostics from cloud to equipment-mounted processors. |
| Strategic Partnership | Aligns with Siemens and PTC interoperability standards for AR-enabled remote technician guidance overlays. |
Study Parameters
Coverage spans the United States, Germany, Japan, India, and Brazil, with primary inputs from each market combining structured interviews with aftermarket service heads, maintenance directors at industrial OEMs, platform engineers at cloud-native vendors, and procurement leads at telecommunications infrastructure operators. Secondary validation draws from FDA 510(k) filings for device service record requirements, EU AI Act implementation guidance, METI industrial data governance publications, BIS data localization circulars, and SEC 10-K disclosures from enterprise software providers. Bottom-up sizing of installed base management workflows triangulates against top-down IT services spending allocations.
Rate-of-change decomposition separates cloud deployment velocity from AI capability adoption curves and regulatory compliance investment cycles across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, technology layer, and regional regulatory cluster complexity. CAGRs derive from elasticity-adjusted replacement rates for legacy entitlement systems and pilot-to-production conversion timelines for agentic AI deployments. Industry-specific inputs incorporate IoT sensor cost trajectories and equipment-as-a-service contract penetration assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement timelines or prolonged NIST cybersecurity certification delays. Forecasts reflect documented assumptions regarding cloud migration velocity and sovereign infrastructure buildout commitments. Practitioners should monitor field service engineer training pipeline shortfalls in Germany and Japan and cross-border data localization mandate proliferation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Decision Support System Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Turkey ICT Market
Digital Solutions
India ICT Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Global Hybrid Integration Platform Market