
 Global Sebacic Acid Market | 2026-2036
Global Sebacic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sebacic Acid Market Foresight
The split between monomer-grade and industrial-grade sebacic acid is realigning around bio-based certification requirements. Arkema SA leverages its integrated castor oil-to-polyamide 10,10 chain to command premium positioning in European automotive sourcing. Jayant Agro Organics anchors India's dominant castor seed processing base, sustaining raw material cost advantages that competitors struggle to replicate. Tianxing Biotechnology Co. Ltd. specializes in oxidation-process refinement, occupying a technical niche between commodity suppliers and specialty chemical houses.
Sebacic acid is a C10 dicarboxylic acid derived primarily from castor oil via alkaline cleavage of ricinoleic acid, yielding a white crystalline solid with melting point near 134°C and purity thresholds dictating end-use suitability. Plasticizers and polyamide production represent the largest application segments, with polyamide demand pulling fastest as OEMs substitute metal components in under-hood and electrical housing applications. Bio-based process methods are gaining structural share against conventional oleic acid oxidation, though chemical synthesis still dominates total volume due to established capacity and lower capital intensity.
REACH registration requirements and EU Green Deal sustainable chemistry benchmarks are tightening feedstock traceability rules for European chemical producers, while China's GB standards and MEE environmental compliance protocols shape export eligibility from Shandong-based manufacturers. FDA food-contact and pharmaceutical-grade specifications govern US market access for high-purity grades, creating tiered certification barriers that fragment supplier pools. Stakeholders must track bio-based content verification schemes and castor oil price volatility as the primary variables affecting margin stability and sourcing strategy.
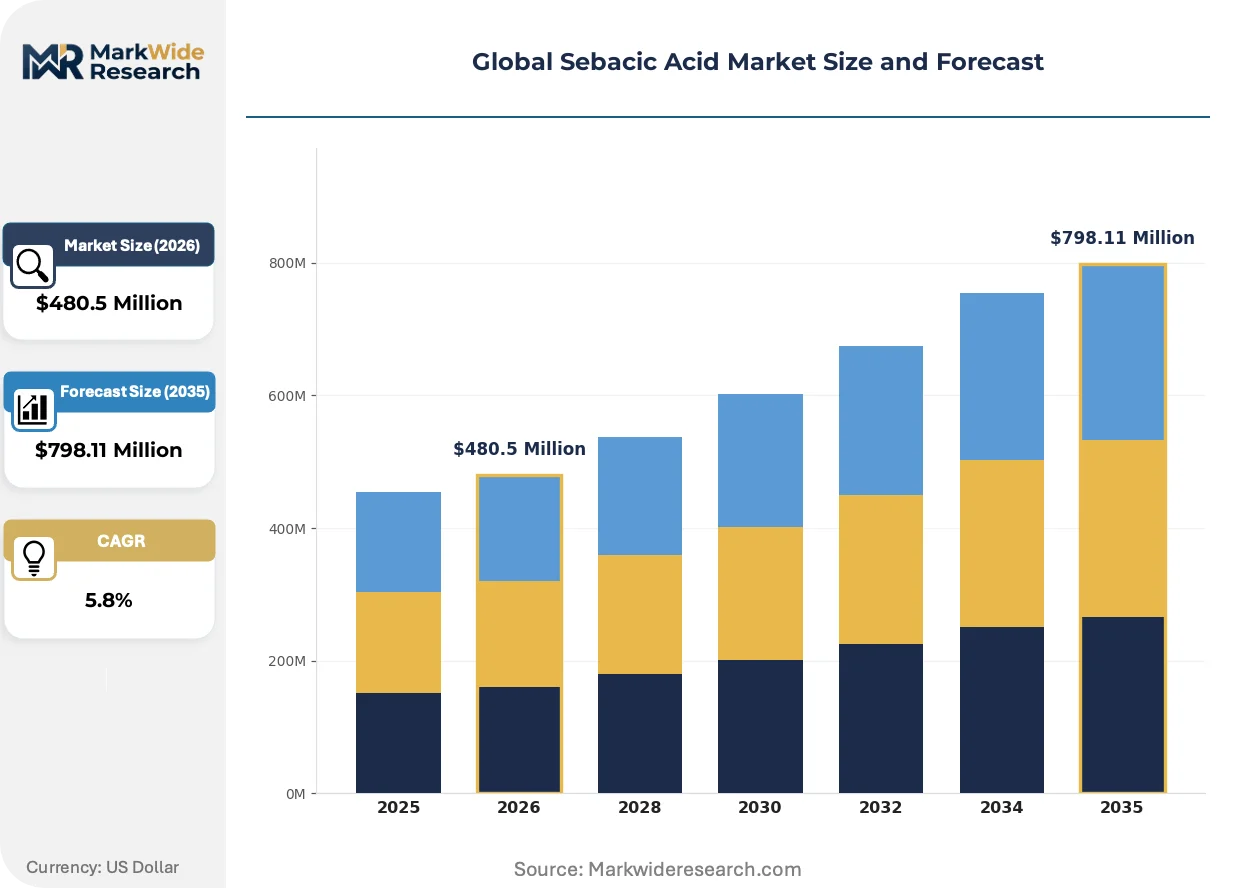
Market Dynamics
The sebacic acid market pivots on castor oil supply concentration in India and China, where seed processing clusters and oxidation capacity determine feedstock access and pricing power for downstream polyamide and plasticizer manufacturers.
Growth Catalysts
- EU Green Deal sustainable chemistry mandates:REACH registration requirements and bio-based content benchmarks redirect European procurement toward certified sebacic acid routes, tightening traceability rules for automotive and packaging applications.
- Automotive lightweighting demand:Polyamide 6,10 and 10,10 formulations replace metal components in under-hood and electrical housing systems, pulling monomer-grade volumes from OEM specification programs.
- Castor oil processing expansion:Gujarat and Shandong province clusters deepen seed crushing and derivative capacity, anchoring raw material cost structures that downstream oxidation plants depend on.
Market Restraints
- Castor oil price volatility:Weather-dependent Indian harvests and speculative trading in seed futures transmit cost instability through the entire C10 dicarboxylic acid value chain.
- Single-source feedstock dependency:Ricinus communis cultivation concentrates in semi-arid Indian and Brazilian zones, creating geographic concentration risk that no alternative oilseed currently mitigates.
- Alkaline cleavage process limitations:Conventional ricinoleic acid oxidation generates sodium sulfate waste streams that MEE environmental compliance protocols in China and state pollution control boards in India increasingly restrict.
Strategic Opportunities
- Bio-based certification premiums:USDA BioPreferred and TÜV OK Compost labels enable pricing differentiation for sebacic acid routed through verified sustainable castor programs in European and North American specialty chemical markets.
- Pharmaceutical-grade purification:USP and EP monograph compliance for high-purity C10 diacid opens formulation opportunities in controlled-release drug delivery and medical device polymers where FDA 21 CFR 177.1395 governs food-contact suitability.
- Biodegradable lubricant base stocks:Ester derivatives from sebacic acid penetrate hydraulic and metalworking fluid formulations as EU F-Gas Regulation and national oil discharge standards tighten petroleum-based alternatives.
Industry Challenges
- Specialized oxidation engineering talent:Refinery-scale continuous cleavage reactor design and catalyst optimization require process chemists with ricinoleic acid chemistry expertise that few technical institutes currently train.
- Multi-jurisdiction certification timelines:Concurrent REACH, FDA food-contact, and GB standards compliance for export-oriented Chinese manufacturers stretches quality assurance resources across incompatible documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sebacic Acid Market |
| Market Size in 2026 | $480.5 Million |
| Market Size in 2035 | $798.11 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomer Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade Application: Plasticizers, Lubricants, Coatings, Corrosion Inhibitors, Polyamide Production End User Industry: Packaging Manufacturers, Coating Companies, Personal Care Brands, Chemical Producers Production Method: Oxidation of Oleic Acid, Microbial Fermentation, Chemical Synthesis, Bio-based Process |
| Companies Covered | Sebacic India Ltd., Tianxing Biotechnology Co. Ltd., Arkema SA, Jayant Agro Organics Ltd., Shandong Siqiang Chemical Group Co. Ltd., Hengshui Jinghua Chemical Co. Ltd., Inolex Inc., Evonik, Hokoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sebacic Acid Market Shifts & Advancements
Process intensification and bio-based verification systems are compressing the technical and commercial distance between commodity chemical suppliers and specialty-grade producers in sebacic acid value chains.
Continuous-flow alkaline cleavage technology is consolidating batch-process capacity in Shandong and Hebei oxidation plants. Automotive polyamide compounders in Germany and Japan specify mass-balance-certified sebacic acid with documented bio-based carbon content. This technology compression forces standalone commodity producers to upgrade or exit as integrated castor-to-polyamide chains capture specification-grade premiums.
REACH registration dossier updates and EU Green Deal sustainable feedstock traceability requirements tighten substance identity and supply chain documentation obligations. European formulators now require lot-level castor origin verification and third-party sustainability certification. Polyamide 10,10 producers with captive sebacic acid supply are absorbing compliance costs that merchant-market competitors struggle to pass through.
Specification-driven procurement now separates certified bio-based grades from uncertified commodity volumes in European and Japanese purchasing protocols. Tier-1 automotive suppliers mandate ISCC PLUS or REDcert chain-of-custody documentation for under-hood polymer components. This behavioral shift concentrates contract volumes with integrated processors in Gujarat and Arkema's French manufacturing complex while spot-market traders face margin compression.
Global Sebacic Acid Market Segmentation
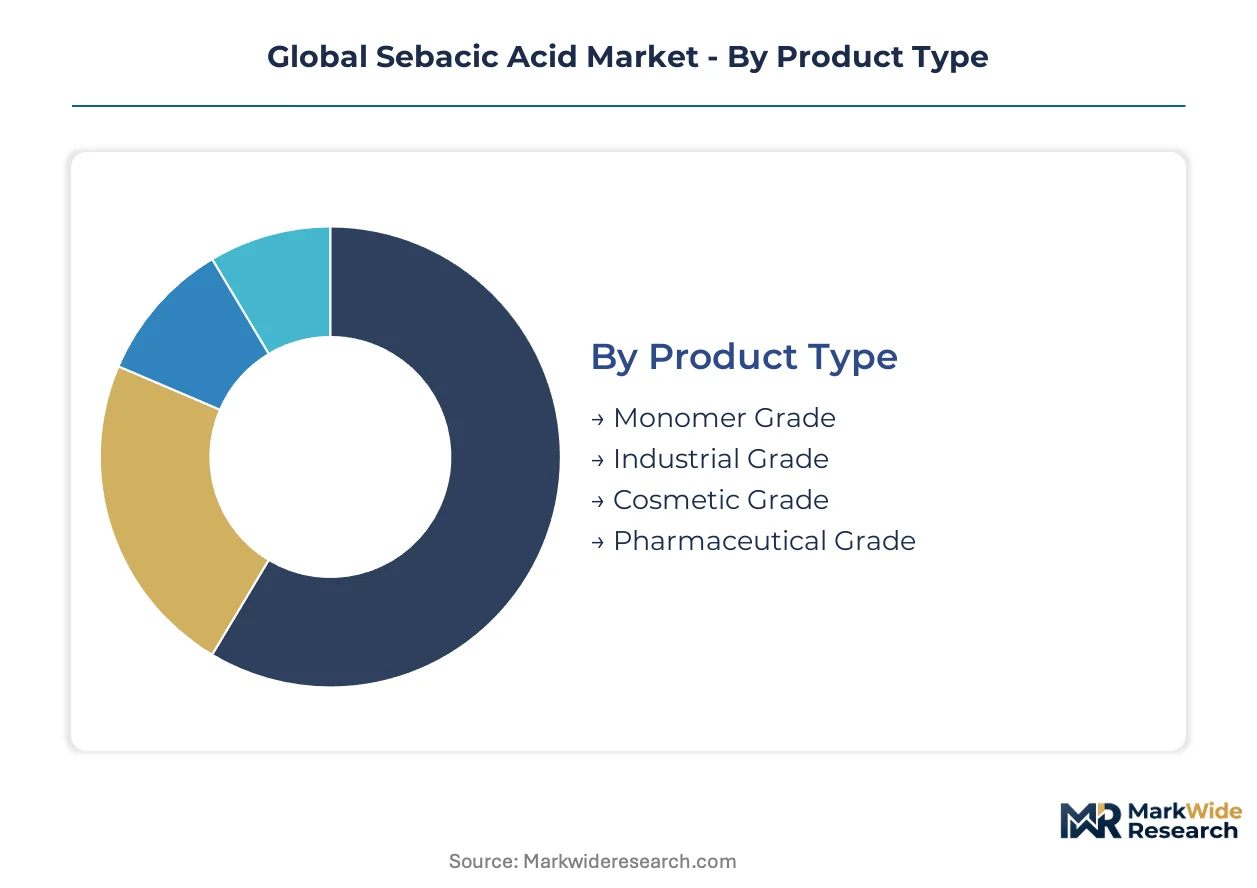
Sebacic acid specifications fragment sharply across end-use requirements, with polyamide producers and pharmaceutical formulators demanding purity thresholds that commodity oxidation plants cannot meet. Supply chain configuration separates integrated castor oil processors from standalone chemical manufacturers.
Product Type:
Castor oil cleavage yields diverge sharply between specification-grade and commodity outputs, with purity thresholds determining access to automotive OEM and pharmaceutical procurement channels.
- Monomer Grade:Purity exceeds 99.5% with controlled moisture content below 0.1%, enabling polyamide 6,10 and 10,10 polymerization for under-hood automotive components. German and Japanese automotive compounders specify lot-level bio-based carbon verification from this grade.
- Industrial Grade:Standard purity ranges of 98-99% serve plasticizer and lubricant base stock formulations where color stability matters less than cost efficiency. Shandong oxidation plants concentrate capacity here due to lower wastewater treatment burdens.
- Cosmetic Grade:Heavy metal limits below 10 ppm and microbial specifications meet personal care formulator requirements in EU and US markets.
- Pharmaceutical Grade:USP and EP monograph compliance with documented impurity profiles for controlled-release drug delivery systems.
Monomer grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
End-use concentration in automotive and packaging sectors creates volume anchors that stabilize feedstock procurement for integrated processors.
- Plasticizers:Di-2-ethylhexyl sebacate and dibutyl sebacate formulations provide low-temperature flexibility for PVC wire insulation and food-contact films. REACH registration requirements tighten phthalate substitution demand in European cable and flooring applications.
- Polyamide Production:Nylon 6,10 and 10,10 resins replace metal in engine covers, electrical housings, and fuel line connectors. OEM lightweighting programs in Germany, Japan, and the US specify mass-balance-certified monomer inputs.
- Lubricants:Ester base stocks penetrate hydraulic fluids and metalworking applications as EU F-Gas Regulation restricts synthetic alternatives.
- Coatings:Alkyd and polyester modifications improve flexibility and weather resistance in industrial protective systems.
- Corrosion Inhibitors:Metal salt derivatives protect ferrous substrates in cooling water and drilling fluid formulations.
Polyamide production commands the steepest expansion trajectory; plasticizers retain the largest volume base.
End User Industry:
Procurement sophistication varies dramatically across customer types, with automotive tier-1 suppliers imposing documentation burdens that commodity traders cannot satisfy.
- Chemical Producers:Integrated polyamide manufacturers in France, India, and China represent the largest contract volumes, often with captive sebacic acid supply or long-term offtake agreements with Gujarat-based processors.
- Packaging Manufacturers:Food-contact film and bottle producers drive pharmaceutical-grade demand in the US and EU, with FDA 21 CFR 177.1395 compliance mandatory for migration limits.
- Coating Companies:Industrial and automotive paint formulators specify color-stable industrial grades for high-solids alkyd systems.
- Personal Care Brands:Cosmetic-grade volumes concentrate with multinational formulators requiring RSPO- or similar sustainability certification for castor oil derivatives.
Chemical producers lock in the majority of forward capacity; packaging manufacturers are scaling specification-grade procurement fastest.
Production Method:
Process economics and regulatory positioning separate established chemical routes from emerging bio-based verification systems.
- Bio-based Process:Alkaline cleavage of castor oil-derived ricinoleic acid yields certified renewable content for EU Green Deal procurement mandates. ISCC PLUS and REDcert chain-of-custody documentation enables premium positioning in European automotive and packaging markets.
- Chemical Synthesis:Butadiene-based routes and oleic acid oxidation dominate total volume due to lower capital intensity and established capacity in China and India.
- Oxidation of Oleic Acid:Petrochemical feedstock routes face margin pressure as bio-based certification becomes a procurement filter in European and Japanese markets.
- Microbial Fermentation:Cell-culture C10 diacid production remains at pilot scale, with yield and titer economics unproven at commercial volume.
Chemical synthesis retains the dominant capacity share; bio-based process is climbing the fastest as certification premiums widen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors global sebacic acid oxidation capacity, with cleavage reactor clusters in Zibo and Weifang processing castor oil derivatives for polyamide and plasticizer supply chains.
China
Shandong and Hebei provinces concentrate alkaline cleavage capacity serving domestic polyamide 6,10 producers and export markets. MEE environmental compliance protocols tighten wastewater discharge standards for sodium sulfate byproduct streams. Tianxing Biotechnology occupies technical niche between commodity suppliers and specialty chemical houses in this corridor.
India
Gujarat's castor seed crushing belt around Kutch and Banaskantha districts supplies ricinoleic acid feedstock at cost structures competitors struggle to replicate. DGFT export promotion schemes and PLI scheme incentives support downstream chemical processing investments. Jayant Agro Organics anchors the dominant seed processing base in this western cluster.
Germany
Rhine-Ruhr automotive compounders specify mass-balance-certified monomer-grade inputs for under-hood polymer components. REACH registration requirements and EU Green Deal sustainable feedstock traceability rules tighten procurement filters. Arkema's integrated manufacturing complex serves tier-1 supplier certification programs from this industrial heartland.
United States
Gulf Coast plasticizer manufacturers and pharmaceutical formulators drive demand for industrial-grade and USP-compliant sebacic acid derivatives. FDA 21 CFR 177.1395 food-contact specifications govern migration limits for packaging applications. Inolex represents specialty chemical positioning in this regulated environment.
Japan
Kansai region polyamide compounders and precision chemical manufacturers source high-purity grades for automotive and electronics applications. METI industrial standards and JIS certification requirements shape import specifications. Hokoku Corporation occupies position within this quality-driven procurement landscape.
Global Sebacic Acid Market Competitive Landscape
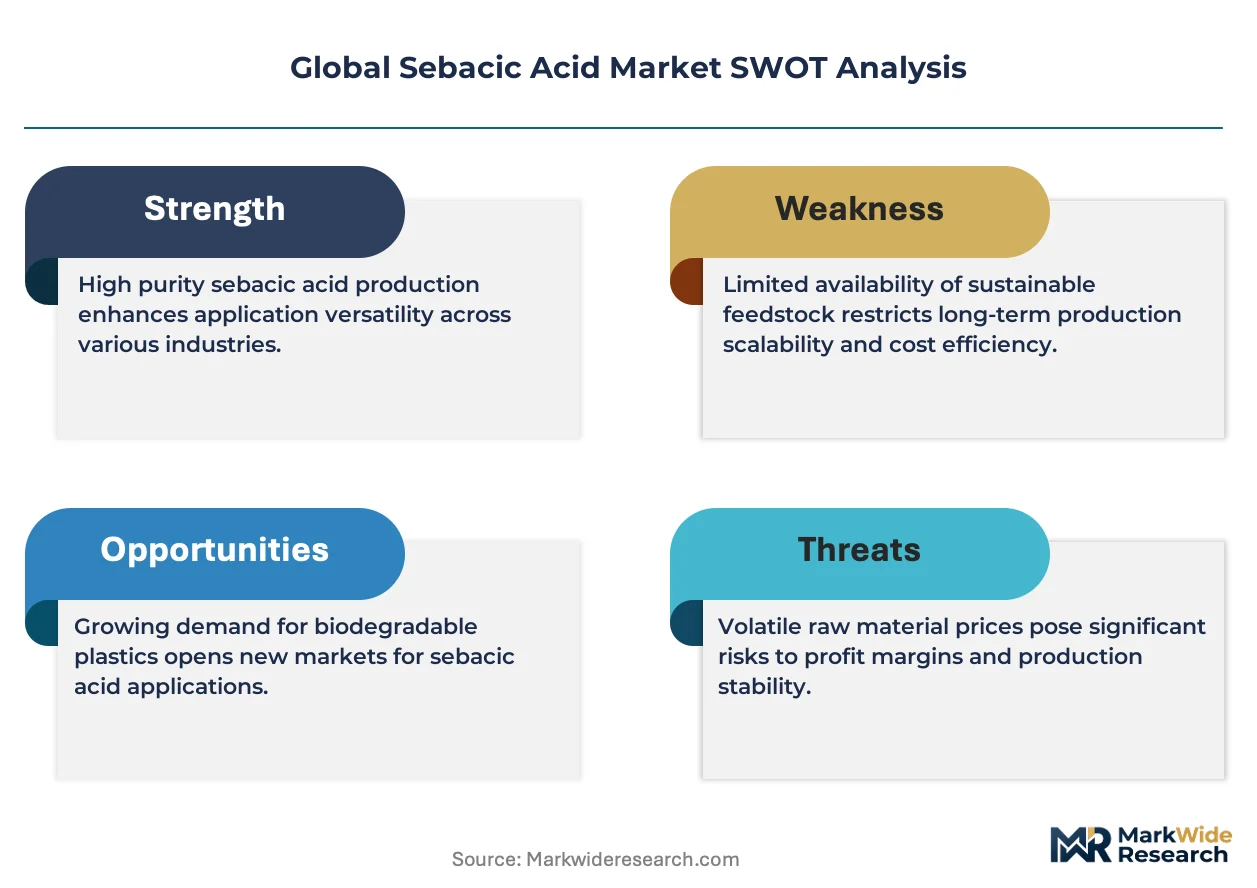
Premium-margin players sit above commodity-margin players across certification-grade and traceability dimensions. The vendor base separates into integrated castor oil processors with captive oxidation capacity, standalone chemical manufacturers dependent on merchant feedstock, and specialty-grade purifiers serving pharmaceutical and cosmetic channels. Three archetypes dominate: backward-integrated agricultural processors, technology-focused oxidation specialists, and diversified chemical conglomerates with polyamide downstream. Competitive moves concentrate on bio-based certification acquisition and continuous-flow process upgrades.
Within the integrated processor tier, Jayant Agro Organics and Arkema SA exemplify contrasting geographic anchoring—Indian seed-crushing dominance versus European downstream polymer integration. Tianxing Biotechnology occupies the oxidation-specialist archetype between these poles. Among diversified chemical houses, Evonik and Hokoku Corporation represent German and Japanese positioning within specification-grade procurement channels. Sebacic India Ltd. and Shandong Siqiang Chemical Group anchor volume-scale production in South Asian and Chinese commodity supply respectively.
| Leading Market Players |
|---|
| Sebacic India Ltd. |
| Tianxing Biotechnology Co. Ltd. |
| Arkema SA |
| Jayant Agro Organics Ltd. |
| Shandong Siqiang Chemical Group Co. Ltd. |
| Hengshui Jinghua Chemical Co. Ltd. |
| Inolex Inc. |
| Evonik |
| Hokoku Corporation |
| Others |
Supply & Pricing Matrix
Specialized oxidation engineering talent clustering in Shandong and Hebei provinces compresses labor-cost differentials between commodity and specification-grade production tiers. This workforce concentration enables Chinese plants to undercut European purification costs while maintaining REACH-compliant documentation standards.
Pricing Analysis
Yield-optimized throughput pricing anchors contract negotiations between automotive polyamide compounders and integrated castor oil processors. Three-tier pricing structure across monomer-grade, industrial-grade, and pharmaceutical-grade levels separates certified bio-based premiums from uncertified commodity volumes. Cost compression in industrial-grade segments intensifies as Shandong oxidation plants expand continuous-flow capacity. Pharmaceutical formulators exhibit least price sensitivity due to USP compliance barriers that filter supplier pools.
Supply Chain Analysis
Freight cost differentials between Gujarat seed-crushing clusters and Shandong oxidation corridors shape procurement routing for European automotive compounders. Supply concentrates in India, China, and Brazil where Ricinus communis cultivation and derivative processing anchor feedstock access. Sodium sulfate waste stream disposal requirements under MEE protocols and state pollution control boards constrain capacity expansion. Distribution runs through long-term offtake agreements with integrated polyamide manufacturers rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sebacic acid market sits in a process-technology transition phase as continuous-flow alkaline cleavage displaces legacy batch oxidation systems.
For Market Incumbents: Deploy backward integration into castor seed crushing to secure feedstock cost advantages against merchant-market competitors. Arkema's integrated French manufacturing complex demonstrates how captive ricinoleic acid supply absorbs REACH compliance costs that standalone oxidation plants struggle to pass through. Invest in ISCC PLUS certification infrastructure before EU Green Deal traceability mandates harden procurement filters. For New Entrants and Emerging Players: Specialty chemical distributors represent the most accessible channel partner type for penetrating pharmaceutical-grade purification segments. White-space opportunities concentrate in USP-compliant C10 diacid for controlled-release drug delivery systems where FDA 21 CFR 177.1395 compliance creates certification barriers. Target cosmetic-grade formulations requiring heavy metal limits below 10 ppm and microbial specifications. For Investors and Strategic Acquirers: Re-rating potential sits with oxidation-process specialists possessing continuous-flow engineering capabilities given automotive lightweighting demand for mass-balance-certified monomer inputs. Long-term viability hinges on bio-based content verification infrastructure rather than commodity volume scale. Watch castor oil futures volatility as the primary inflection indicator for margin stability across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Process Upgrade | Shandong and Hebei plants compress batch-cycle times while reducing sodium sulfate waste streams under MEE protocols. |
| Bio-Based Certification Investment | ISCC PLUS and REDcert documentation enables premium positioning in EU automotive and packaging procurement channels. |
| Backward Integration into Seed Processing | Gujarat-based crushing capacity secures ricinoleic acid feedstock at cost structures competitors cannot replicate. |
| Pharmaceutical-Grade Purification Capacity | USP and EP monograph compliance opens formulation opportunities in controlled-release drug delivery systems. |
| Long-Term Supply Agreement with Automotive Compounders | Tier-1 OEM specification programs lock in monomer-grade volumes with documented bio-based carbon verification. |
Research Methodology
Multi-period observation of castor oil price volatility, oxidation capacity utilization, and certification adoption rates anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Hebei cleavage facilities, procurement leads at German automotive compounders, technical R&D directors at polyamide manufacturers, and distribution channel partners in specialty chemical markets. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and REACH registration dossiers. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume estimates.
Input-output matrices mapped ricinoleic acid feedstock availability against polyamide, plasticizer, and pharmaceutical formulation demand across grade tiers, end-use industries, and regional production hubs. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of automotive lightweighting penetration rates. Industry-specific forecast inputs included castor seed harvest yield variability in Gujarat and Banaskantha districts and MEE environmental compliance cost trajectories for sodium sulfate waste treatment.
Several conditions sit outside the modeled scope, including breakthrough microbial fermentation yields at commercial scale and geopolitical disruption of India-China castor oil trade corridors. Forecasts reflect documented assumptions about continuous-flow technology adoption curves and EU Green Deal implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
North America Carbon Black Market