
 Global Cosmetic Skin Care Market | 2026-2036
Global Cosmetic Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Skin Care Market Foresight
Retinol is shifting toward bakuchiol and other plant-derived alternatives as brands reformulate to reduce irritation profiles and meet clean-beauty positioning. L'Oréal S.A. leverages its Active Cosmetics division to anchor dermatologist-endorsed distribution across pharmacy channels in France and Brazil. The Estée Lauder Companies sustains premium pricing through concentrated serum formats that command higher per-unit margins. Beiersdorf AG differentiates via Nivea's mass-market scale while competing in the dermocosmetic tier with Eucerin.
Cosmetic skin care encompasses topical formulations designed to maintain, protect, or improve skin appearance, typically containing active concentrations between 0.1% and 10% depending on regulatory classification and intended function. These products employ emulsion chemistry, penetration enhancers, and stabilizing agents to deliver functional benefits through the stratum corneum barrier. Serums and peptide complexes capture the fastest margin expansion as consumers trade up from basic moisturizers toward targeted treatments with clinical positioning. Nanotechnology delivery systems remain concentrated in premium tiers due to manufacturing complexity and regulatory scrutiny over particle safety profiles.
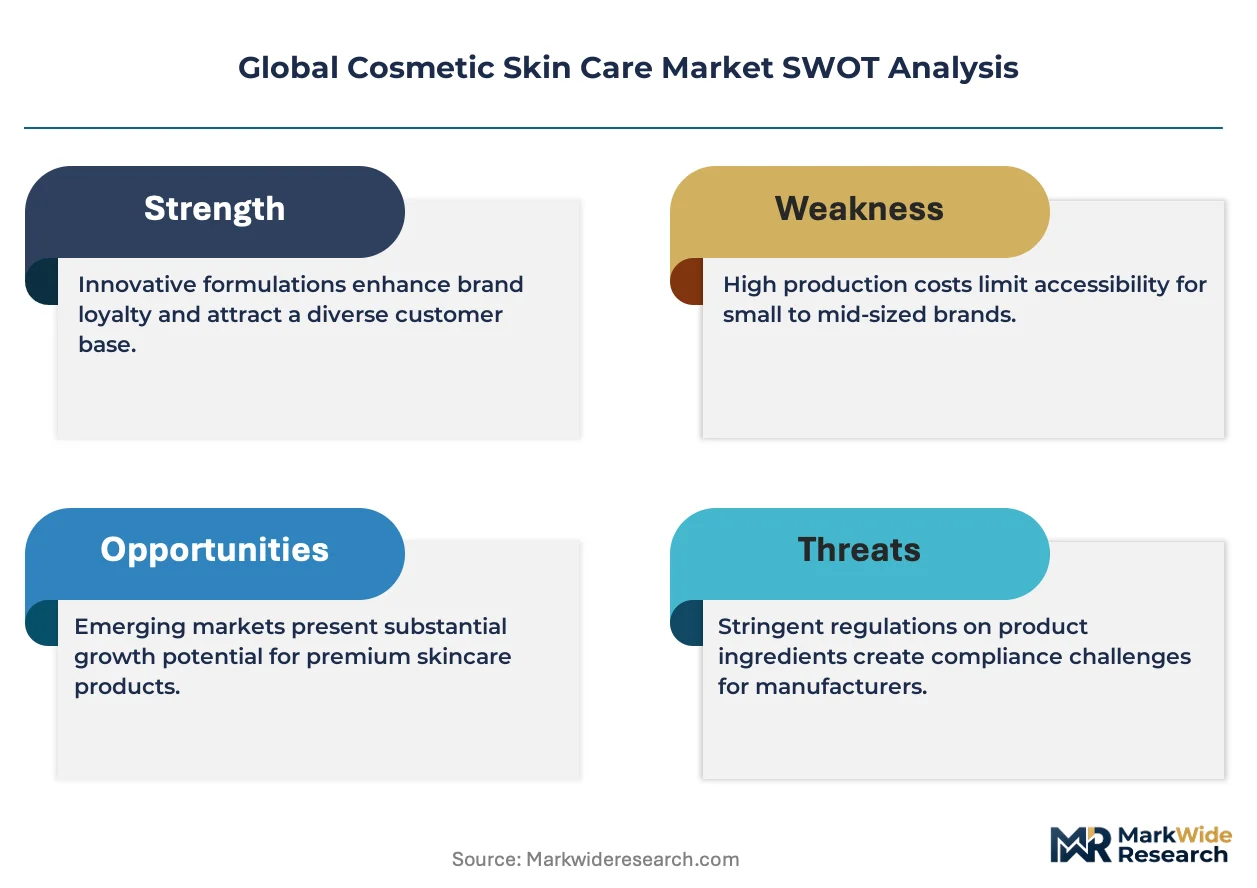
The EU REACH framework and FDA's oversight of cosmetic ingredient safety jointly determine which novel actives achieve commercial scale across Western markets. China's NMPA registration requirements for imported cosmetics create a dual-track compliance burden that favors established multinationals with dedicated regulatory affairs capacity. Japan's Quasi-Drug classification system opens distinct positioning for skin-brightening and anti-aging claims that standard cosmetics cannot make. Stakeholders must monitor how evolving microbiome science influences both probiotic ingredient approvals and marketing claim permissibility across jurisdictions.
Market Dynamics
The EU's microplastic ban under REACH is forcing mass reformulation of rinse-off products, compressing legacy ingredient supply chains while opening procurement contracts for biodegradable alternatives.
Growth Catalysts
- Gen Z regimen expansion:Young consumers in China and South Korea now adopt multi-step routines with dedicated treatment steps, expanding addressable product slots per capita.
- REACH microplastic prohibition:The EU regulation eliminates polyethylene beads and film-forming polymers from cleansers, creating mandatory replacement demand for cellulose and mineral alternatives.
- Bakuchiol substitution:Plant-derived retinol alternatives are capturing formulation share as brands reduce irritation liability and access clean-beauty positioning.
Market Restraints
- Shea butter price volatility:West African supply interruptions and climate stress on karité trees are compressing margins for mass-market moisturizers.
- NMPA registration burden:China's dual-track compliance for imported cosmetics requires animal testing waivers and extended safety dossiers that freeze smaller entrants.
- Peptide synthesis capacity:Contract manufacturers in Switzerland and South Korea command premium pricing due to limited GMP-certified facilities for cosmetic-grade oligopeptides.
Strategic Opportunities
- Brazil pharmacy channel:Dermatologist-endorsed distribution remains underdeveloped outside São Paulo and Rio de Janeiro, offering first-mover positioning for clinical brands.
- Microbiome claim permissibility:Evolving EFSA and FDA guidance on live culture stability is creating regulatory white space for probiotic serum launches with differentiated positioning.
- AI formulation platforms:Machine learning tools for emulsion stability prediction are compressing R&D cycles and enabling rapid regional adaptation of base formulations.
Industry Challenges
- Cosmetic chemist scarcity:Formulation expertise in encapsulation technology and penetration enhancer safety is concentrating at specialty contract labs in France and Japan.
- Nanoparticle toxicology dossiers:ECHA's evolving nanoform registration requirements demand extended safety studies that delay premium tier launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Skin Care Market |
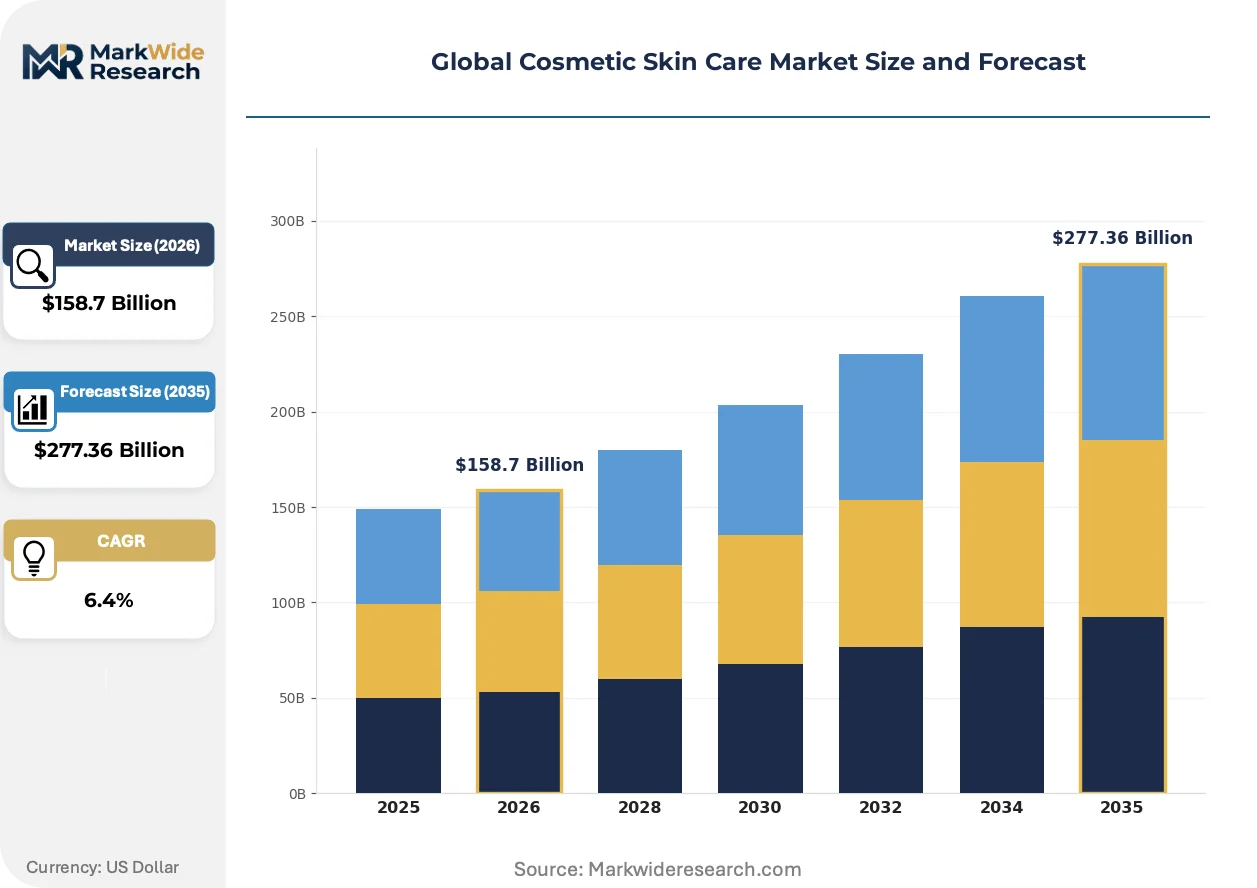
| Market Size in 2026 | $158.7 Billion |
| Market Size in 2035 | $277.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Serums, Cleansers, Exfoliants, Face Masks Technology: Nanotechnology, Microencapsulation, Liposome Delivery, Peptide Complexes, Botanical Extracts, Probiotics Application: Anti-Aging, Sun Protection, Acne Treatment, Skin Brightening, Hydration, Anti-Pollution End User: Beauty Salons, Dermatology Clinics, Spas, Pharmacies, E-commerce Platforms, Specialty Stores |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies, Procter & Gamble, Johnson & Johnson, Beiersdorf AG, Shiseido Company, Unilever, Coty Inc., Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Skin Care Market Shifts & Advancements
Biotechnology-derived actives and delivery system miniaturization are compressing the performance gap between cosmetic and pharmaceutical topical efficacy claims.
Liposomal encapsulation systems are absorbing manufacturing investment from premium brands seeking to stabilize vitamin C and retinoid actives against oxidation. Korean and Chinese consumers demonstrate highest willingness-to-pay for serum formats with documented dermal penetration data. This technology is absorbing shelf space from conventional emulsion moisturizers in pharmacy and specialty retail channels.
Japan's Quasi-Drug classification system is tightening evidentiary standards for skin-brightening claims, requiring clinical endpoint data that standard cosmetic registrations cannot satisfy. Domestic brands with existing PMDA dossiers are extending market share in whitening and anti-aging segments. Multinationals without Quasi-Drug portfolios are retreating to basic moisturizing positioning in Japanese distribution.
Subscription direct-to-consumer models are displacing department store counter sales for core replenishment items in North American and Western European markets. Younger buyers prioritize convenience and personalization over in-person consultation for established product categories. This channel rotation is most visible in the United States and United Kingdom, where legacy retailers are ceding volume to specialized skin care platforms.
Global Cosmetic Skin Care Market Segmentation
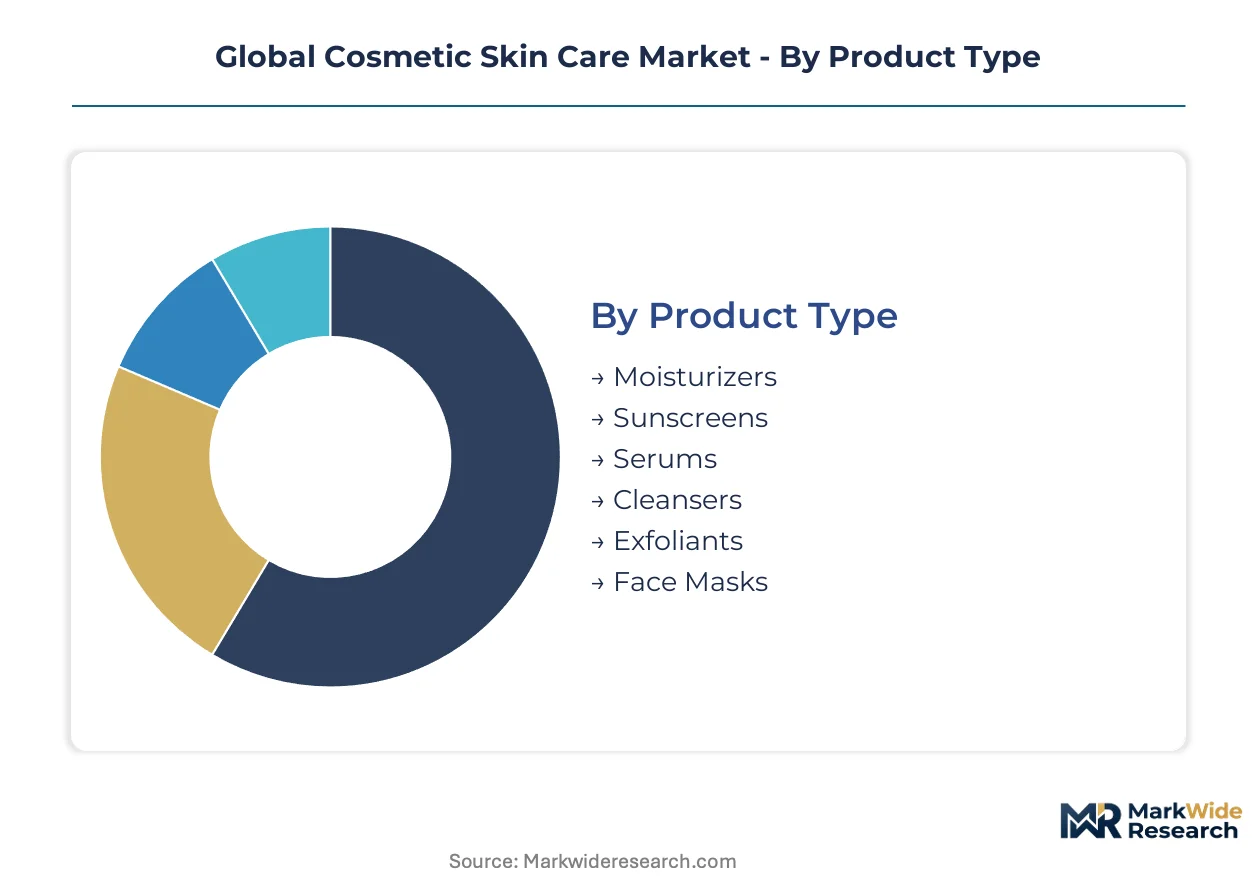
Segmentation in cosmetic skin care reflects divergent paths between mass-market scale and clinical-grade precision. Formulation complexity, delivery technology, and channel positioning create distinct margin architectures across each dimension.
Product Type:
The customization-to-standardization spectrum spans from bespoke compounding in professional settings to off-the-shelf formats optimized for manufacturing throughput.
- Serums:Concentrated aqueous or oil-based formulations with active loadings between 5% and 20% enable targeted dermal penetration. Korean and Chinese consumers demonstrate highest willingness-to-pay for documented bioavailability data, compressing conventional emulsion margins in pharmacy channels.
- Moisturizers:Occlusive and humectant blends with shea butter, ceramides, or hyaluronic acid form the volume foundation of daily regimens. West African supply interruptions for karité derivatives are forcing reformulation toward synthetic emollients in mass-market tiers.
- Sunscreens:Mineral and organic UV filter suspensions require photostability engineering and regulatory dossier depth that favors established multinationals.
- Cleansers:Surfactant systems face mandatory reformulation under EU REACH microplastic prohibitions, accelerating procurement shifts toward cellulose and mineral abrasives.
- Exfoliants:Alpha-hydroxy acid and enzymatic formats occupy professional and home-use boundary zones with concentration-dependent regulatory classification.
- Face Masks:Sheet, clay, and hydrogel formats concentrate manufacturing in South Korean and Chinese contract facilities with flexible batch sizing.
Most installed capacity flows through Moisturizers. Expansion is steepest in Serums.
Technology:
Cost tier stratification separates premium delivery systems with manufacturing complexity barriers from commodity extraction methods with open supply chains.
- Liposome Delivery:Phospholipid bilayer encapsulation stabilizes oxidation-sensitive actives including vitamin C and retinoids. Japanese and Swiss manufacturers command premium pricing due to limited GMP-certified capacity for cosmetic-grade phosphatidylcholine sourcing.
- Peptide Complexes:Synthetic oligopeptide sequences with documented cell-signaling activity require solid-phase synthesis expertise concentrated in Basel and Seoul contract labs. Extended lead times for cosmetic-grade GMP certification freeze smaller brand entrants.
- Nanotechnology:Sub-100nm particle systems for enhanced penetration face ECHA registration delays of 18-24 months for toxicology dossiers.
- Microencapsulation:Polymer shell systems enable time-release functionality with broader regulatory acceptance than nano-scale alternatives.
- Botanical Extracts:Plant-derived active concentration through solvent extraction or supercritical CO2 processing carries supply volatility from agricultural yield cycles.
- Probiotics:Live culture stability in topical formats awaits clarified EFSA and FDA guidance on shelf-life validation and claim permissibility.
Peptide Complexes absorb the highest R&D investment intensity. Probiotics are climbing the fastest as regulatory white space opens.
Application:
Customer type differentiation separates clinical-positioned claims requiring evidentiary support from cosmetic claims with lower regulatory burden.
- Anti-Aging:Retinoid, peptide, and antioxidant formulations target collagen synthesis and cellular turnover. Japan's PMDA Quasi-Drug classification restricts certain structural claims to dossier-backed registrations that domestic brands exploit.
- Sun Protection:Broad-spectrum UV defense combines cosmetic and photodermatology positioning with reef-safe formulation mandates in Hawaii and Palau driving mineral filter demand.
- Skin Brightening:Tyrosinase inhibitors and melanin pathway modulators face tightening evidentiary standards in Japan and ingredient prohibitions in EU markets.
- Hydration:Barrier repair and transepidermal water loss reduction claims span mass-market to clinical tiers with lowest regulatory friction.
- Acne Treatment:Salicylic acid and benzoyl peroxide formats overlap with OTC drug classification in US FDA jurisdiction.
- Anti-Pollution:Particulate shielding and oxidative stress prevention claims concentrate in urban Chinese and Indian metropolitan demand.
Anti-Aging commands the highest per-unit pricing. Anti-Pollution is gaining share fastest in Asia-Pacific urban corridors.
End User:
Geographic concentration of channel development creates divergent access economics between mature pharmacy networks and emerging digital platforms.
- E-commerce Platforms:Direct-to-consumer subscription models displace department store replenishment in US and UK markets, with AI-driven personalization engines capturing repeat purchase loyalty.
- Pharmacies:Dermatologist-endorsed distribution in France and Brazil anchors clinical brand credibility, with underpenetration outside São Paulo and Rio offering expansion terrain.
- Dermatology Clinics:Professional-only dispensing of high-concentration actives requires medical channel relationships and training infrastructure.
- Specialty Stores:Curated assortments with in-person consultation concentrate in premium urban districts of London, Paris, and New York.
- Beauty Salons:Service-integrated retail ties product purchase to treatment protocols with recurring revenue attachment.
- Spas:Wellness-positioned environments favor aromatherapy and sensory formulation over clinical efficacy claims.
Pharmacies retain the highest margin per square meter. E-commerce Platforms are expanding most quickly in customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's contract manufacturing corridor anchors formulation innovation for liposomal encapsulation systems serving premium serum brands across Asia-Pacific and Western markets.
United States
Subscription direct-to-consumer platforms displace department store replenishment in New York and Los Angeles metro areas, with AI-driven personalization engines capturing repeat purchase loyalty. FDA oversight of cosmetic ingredient safety determines which novel actives achieve commercial scale. Greater Boston concentrates biotechnology-derived active research with documented dermal penetration data.
China
Domestic brands capture share through digital-native distribution on Tmall and Douyin, while urban consumers in Shanghai and Beijing adopt multi-step regimens with dedicated treatment steps. NMPA registration requirements for imported cosmetics create dual-track compliance burdens that freeze smaller entrants. The Yangtze River Delta houses flexible batch manufacturing for sheet mask and hydrogel formats.
Japan
PMDA's Quasi-Drug classification system restricts certain structural anti-aging and skin-brightening claims to dossier-backed registrations that domestic brands exploit. Domestic manufacturers with existing PMDA portfolios extend market share in whitening segments. Osaka and Tokyo anchor GMP-certified phosphatidylcholine sourcing for cosmetic-grade liposome production.
Germany
ECHA's evolving nanoform registration requirements demand extended safety studies that delay premium tier launches by 18-24 months, favoring established multinationals with dedicated regulatory affairs capacity. REACH microplastic prohibitions eliminate polyethylene beads from cleansers, mandating procurement shifts toward cellulose alternatives. Basel-adjacent facilities in Baden-Württemberg command premium pricing for cosmetic-grade oligopeptide synthesis.
Brazil
Dermatologist-endorsed distribution remains underdeveloped outside São Paulo and Rio de Janeiro, offering first-mover positioning for clinical brands seeking pharmacy channel credibility. ANVISA registration pathways determine which imported formulations achieve commercial scale. São Paulo's pharmacy network anchors mass-market scale while clinical tiers concentrate in affluent southern districts.
Global Cosmetic Skin Care Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance mass-market scale against clinical-grade precision positioning. The vendor base stratifies across three tiers: multinational conglomerates with regulatory affairs capacity, regional specialists with pharmacy channel relationships, and digital-native challengers with direct-to-consumer infrastructure. Strategic archetypes include dermatology-endorsed clinical brands, clean-beauty positioned plant-derived formulators, and AI-enabled personalization platforms. M&A activity and capacity expansion in peptide synthesis facilities represent the dominant competitive vectors.
Within the multinational conglomerate tier, L'Oréal S.A., The Estée Lauder Companies, and Beiersdorf AG exemplify divergent strategic positioning. L'Oréal S.A. occupies a position anchoring dermatologist-endorsed distribution across pharmacy channels. The Estée Lauder Companies exemplifies premium-tier concentration through serum formats commanding higher per-unit margins. Beiersdorf AG represents dual-track positioning via mass-market scale and dermocosmetic tier competition.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies |
| Procter & Gamble |
| Johnson & Johnson |
| Beiersdorf AG |
| Shiseido Company |
| Unilever |
| Coty Inc. |
| Amorepacific Corporation |
| Others |
Supply & Pricing Matrix
Shea butter from West African karité groves flows through formulation houses in France and Germany before reaching pharmacy shelves at tiered price points that separate mass-market Nivea tubs from Eucerin clinical positioning. The karité derivative's climate-driven supply interruptions force rapid substitution toward synthetic emollients in economy tiers while premium brands absorb input volatility through concentrated serum formats.
Pricing Analysis
Input-cost pass-through from peptide synthesis and liposomal phosphatidylcholine feeds directly into premium tier markups, with Swiss and Japanese contract manufacturers commanding 40-60% spreads over standard emulsion bases. Price differentiation separates GMP-certified clinical grades from cosmetic-grade alternatives, with certification level and volume scale as twin drivers. Pricing pressure stems from shea butter volatility and extended ECHA nanoform registration timelines that freeze premium launches. Mass-market moisturizers face highest buyer price sensitivity, while Korean and Chinese consumers demonstrate lowest sensitivity for documented dermal penetration data.
Supply Chain Analysis
Cosmetic chemist scarcity in France and Japan constrains batch capacity for encapsulation technology and penetration enhancer safety dossiers. Manufacturing concentrates in South Korea for flexible sheet mask production, Switzerland for solid-phase peptide synthesis, and Germany for REACH-compliant reformulation. Raw material dependencies include West African karité derivatives, Chinese hydrogel substrates, and Japanese phosphatidylcholine for liposome bilayers. Single-source vulnerability runs through GMP-certified oligopeptide facilities in Basel and Seoul. Distribution runs through pharmacy channels in France and Brazil, direct-to-consumer platforms in the US and UK, and digital-native Tmall/Douyin ecosystems in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cosmetic skin care rests on bakuchiol substitution reducing retinoid synthesis costs and serum formats capturing premium positioning away from commodity moisturizers.
For Market Incumbents: Anticipate REACH microplastic prohibitions forcing second-wave reformulation of leave-on products beyond current rinse-off mandates. Secure captive supply of cellulose abrasives and mineral alternatives before procurement contracts lock. Deepen vertical integration into liposomal encapsulation capacity in Osaka and Tokyo to offset Swiss phosphatidylcholine premiums. For New Entrants and Emerging Players: Brazilian pharmacy buyers outside São Paulo and Rio de Janeiro represent an underserved archetype with dermatologist endorsement gaps and limited clinical brand presence. Target this geography through ANVISA-registered peptide complexes with pharmacy channel training infrastructure. Launch via dermatologist seeding programs rather than mass advertising to establish credibility before incumbent expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where GMP-certified peptide synthesis capacity concentrates in Basel-adjacent facilities and Seoul contract labs. Long-term viability favors targets with existing PMDA Quasi-Drug dossiers in Japan or NMPA animal-testing waiver pathways in China. Watch EFSA/FDA probiotic guidance clarity as inflection signal for microbiome claim permissibility and associated valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capacity Expansion | Basel and Seoul GMP facilities command premium pricing due to cosmetic-grade oligopeptide scarcity. |
| Bakuchiol Formulation Substitution | Plant-derived retinol alternatives reduce irritation liability and unlock clean-beauty positioning premiums. |
| Pharmacy Channel Development | Brazil's underpenetrated dermatologist endorsement network offers first-mover clinical credibility. |
| Direct-to-Consumer Platform Launch | AI-driven personalization engines displace department store replenishment in US and UK markets. |
| Quasi-Drug Dossier Acquisition | Japan's PMDA-backed structural claims restrict whitening and anti-aging segments to registered portfolios. |
Research Methodology
Bottom-up serum and moisturizer modeling reconciled against top-down peptide synthesis capacity tracking forms the analytical core of this study. Primary interviews with cosmetic chemists, pharmacy category buyers, regulatory affairs leads at multinationals, and contract manufacturing executives in Switzerland and South Korea combined with secondary validation from ECHA nanoform registration databases, NMPA import cosmetics filings, and PMDA Quasi-Drug approval records. Nielsen retail audit data and Tmall/Douyin transaction analytics provided channel-level triangulation against formulation house production records.
Input-output matrices mapped active ingredient loading rates to finished product pricing tiers across the projection horizon, with segmentation dimensions including delivery technology (liposome, peptide complex, nanotechnology), application (anti-aging, hydration, skin brightening), and end-user channel (pharmacy, e-commerce, dermatology clinic). CAGRs derived from growth rate convergence modeling against per-capita regimen expansion in China and South Korea, with shea butter supply volatility and REACH compliance timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; serum and peptide complex data carry tighter precision than probiotic and nanotechnology categories where regulatory guidance remains unresolved. Forecasts reflect assumptions around NMPA registration pathway continuity, ECHA nanoform dossier approval timelines, and karité supply recovery trajectories. Material deviation in EU microbiome claim permissibility, West African climate patterns, or Chinese domestic brand share acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Preoperative Skin Preparation Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Acne Treatment Market
Skincare
Herbal Skincare Products Market
Skincare
Skin Care Supplements Market
Skincare
Europe Functional Cosmetics Market
Skincare
Global Anti-Aging Market
Skincare
Skin Grafting System Market
Skincare
Biocellulose Mask Market
Skincare
Dermal Regeneration Market
Skincare
Facial Skincare Market
Skincare
Ampoule Cream Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Vitamin C Serum Market
Skincare
Peel Off Face Mask Market