
 Global Maintenance Management Software Market | 2026-2036
Global Maintenance Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maintenance Management Software Market Foresight
Buyer concentration among utilities providers and transportation operators is hardening as procurement teams consolidate vendor relationships across multi-site portfolios. SAP leverages its ERP-installed base to anchor maintenance modules within existing enterprise workflows. IBM competes through AI-infused asset health analytics that extend its Watson IoT footprint. Schneider Electric dominates in energy-intensive environments where its EcoStruxure platform integrates power and maintenance data streams.
Maintenance management software encompasses computerized systems that schedule, track, and optimize physical asset upkeep through work order orchestration, condition monitoring interfaces, and spare parts inventory algorithms, typically deploying via cloud architectures with mobile field access and API connectivity to SCADA or building automation layers. Cloud-based deployment leads volume as SaaS subscription models displace perpetual licenses in mid-market accounts, while predictive maintenance commands premium pricing due to sensor integration complexity and machine learning model training requirements. On-premise solutions sustain share in defense and critical infrastructure segments where data sovereignty requirements block external hosting.
The EU AI Act imposes algorithmic transparency obligations on automated maintenance decision systems, while ISO 55000 and IEC 61508 shape functional safety benchmarks for asset-intensive operators. The US FAA and NHTSA enforce equipment reliability standards that drive aviation and fleet operators toward auditable digital maintenance logs. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform ecosystems consolidate around industrial IoT data models.
Market Dynamics
Cloud-first mandates from the EU AI Act and ISO 55000 asset management standards are accelerating platform upgrades as manufacturing oversight teams consolidate vendor relationships across multi-site portfolios.
Growth Catalysts
- EU AI Act algorithmic transparency obligations:Automated maintenance decision systems face mandatory explainability requirements, pushing operators toward auditable SaaS platforms with built-in compliance documentation.
- Predictive maintenance modules:Sensor integration complexity and machine learning model training requirements command premium pricing as energy-intensive facilities prioritize uptime optimization over reactive repair cycles.
- Germany's industrial digitization depth:Manufacturing clusters in Bavaria and Baden-Württemberg anchor European demand concentration, with Mittelstand firms replacing legacy CMMS installations at accelerated refresh rates.
Market Restraints
- Data sovereignty requirements:Defense and critical infrastructure segments block external hosting, sustaining on-premise solution share despite higher total cost of ownership.
- Sensor hardware cost volatility:Vibration monitoring and thermal imaging equipment price fluctuations compress predictive maintenance project margins during budget planning cycles.
- Interoperability fragmentation:Proprietary industrial IoT data models from dominant platform ecosystems create switching friction that locks mid-market accounts into suboptimal vendor relationships.
Strategic Opportunities
- Japan's aging asset base:METI-backed Smart Maintenance initiatives target steel and chemical plants with thirty-year-old control systems ripe for connected monitoring retrofits.
- Digital twin convergence:Asset health analytics is converging with 3D facility modeling to enable simulation-driven maintenance scheduling in complex process manufacturing environments.
- Outcome-based service contracting:Aviation and fleet operators under FAA and NHTSA equipment reliability standards are unbundling maintenance software from MRO provider agreements to secure direct data ownership.
Industry Challenges
- SCADA integration complexity:Brownfield facilities struggle to bridge proprietary protocols from legacy building automation layers into modern API-first maintenance platforms without operational disruption.
- Condition monitoring specialist scarcity:Industrial data science talent gaps delay machine learning model deployment in mid-market manufacturing accounts lacking internal analytics capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maintenance Management Software Market |
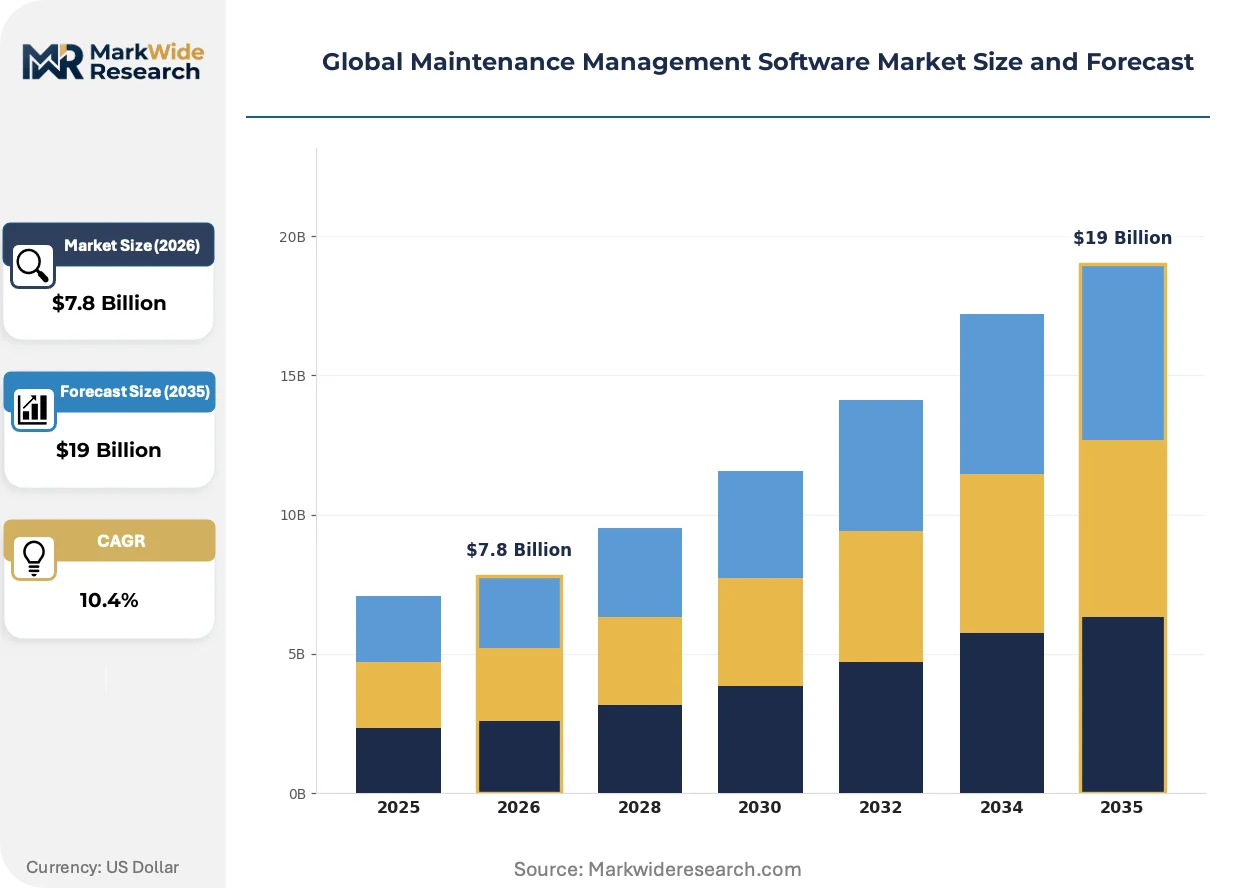
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $19 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Mobile-Enabled Solution Offering: Asset Management, Work Order Management, Inventory Control, Predictive Maintenance, Compliance Tracking Use Case: Facility Management, Manufacturing Oversight, Fleet Upkeep, Energy Management, Infrastructure Monitoring End User: Utilities Providers, Transportation Operators, Educational Institutions, Real Estate Firms, Government Agencies |
| Companies Covered | IBM, SAP, Oracle, Infor, Rockwell Automation, Honeywell, Schneider Electric, GE Digital, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maintenance Management Software Market Shifts & Advancements
Asset-intensive operators are reconfiguring technology stacks around real-time data streams, with regulatory pressure and procurement centralization acting as simultaneous accelerants.
Edge computing architectures are converging with maintenance management platforms to process vibration and thermal sensor data locally before cloud transmission. Chemical processors with continuous operations prioritize sub-50-millisecond anomaly detection that pure SaaS latency cannot deliver. This hybrid deployment model is converging with traditional cloud-first roadmaps, forcing vendors to support dual infrastructure strategies.
The EU AI Act imposes algorithmic transparency obligations on automated maintenance decision systems that trigger work orders without human intervention. Industrial operators must now document training data provenance and model drift monitoring for regulatory inspection. Aviation maintenance organizations under EASA oversight are most affected, with German and French MRO providers investing in explainable AI overlays for existing predictive analytics engines.
Buyer committees at utilities and transportation operators are consolidating vendor relationships across multi-site portfolios, displacing point solutions in favor of integrated enterprise suites. Procurement teams now require API connectivity to ERP, EAM, and power management systems as table stakes. This concentration pattern is most visible in United States municipal utilities, where regional aggregation boards negotiate framework agreements covering hundreds of distributed generation and distribution assets.
Global Maintenance Management Software Market Segmentation
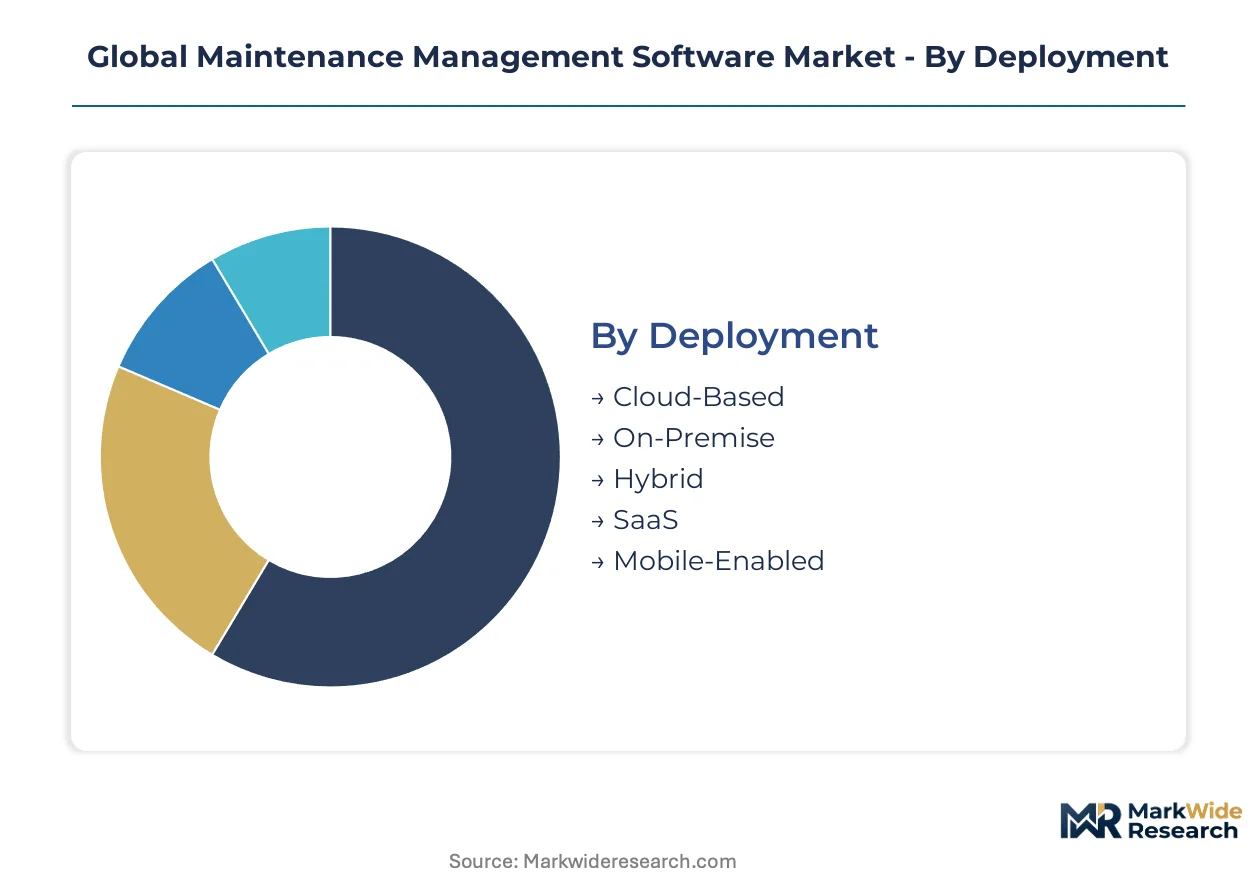
Segmentation in maintenance management software reveals how deployment architecture, functional depth, and operational context shape procurement patterns. Buyers prioritize integration pathways over isolated feature sets when consolidating technology stacks across asset portfolios.
Deployment:
Integration depth varies sharply by infrastructure model, with standalone cloud deployments offering rapid activation while hybrid architectures embed maintenance logic deeper into operational technology layers.
- Cloud-Based:Multi-tenant SaaS architectures enable rapid deployment across distributed facilities without capital infrastructure commitments. German automotive suppliers and US municipal utilities favor this model for centralized oversight of multi-site maintenance operations, driven by EU AI Act transparency requirements that favor auditable platform documentation.
- SaaS:Subscription licensing with automatic feature updates displaces perpetual licenses in mid-market manufacturing accounts. Japanese chemical processors under METI Smart Maintenance directives select SaaS platforms to accelerate predictive module adoption without internal IT expansion.
- On-Premise:Localized data residency satisfies defense and critical infrastructure sovereignty mandates.
- Hybrid:Edge-to-cloud pipelines process sensor data locally before selective cloud transmission.
- Mobile-Enabled:Field technician access layers extend core platform functionality to asset locations.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Hybrid configurations bridging operational technology gaps.
Solution Offering:
Functional modules stratify by data intensity, with basic scheduling tools commanding commodity pricing while AI-infused analytics sustain premium positioning through sensor integration complexity.
- Predictive Maintenance:Machine learning models trained on vibration, thermal, and acoustic sensor streams forecast equipment failure before functional degradation. Energy-intensive facilities in Germany's Ruhr industrial cluster prioritize these modules to minimize unplanned downtime in continuous process operations, with IEC 61508 functional safety standards mandating auditable decision trails.
- Asset Management:Lifecycle cost tracking and depreciation modeling integrate with ERP financial systems. US transportation operators under NHTSA equipment reliability standards deploy these capabilities to maintain auditable digital maintenance logs across fleet portfolios.
- Work Order Management:Digital ticketing systems orchestrate labor scheduling and spare parts allocation.
- Inventory Control:Spare parts optimization algorithms balance carrying costs against stockout risk.
- Compliance Tracking:Regulatory documentation workflows align maintenance records with inspection requirements.
Revenue concentration sits with Asset Management modules; Predictive Maintenance claims the steepest expansion trajectory as sensor hardware costs decline.
Use Case:
Application context determines integration architecture, with discrete manufacturing favoring modular deployments while continuous process industries require real-time data pipelines.
- Manufacturing Oversight:Production line maintenance systems synchronize with MES and SCADA layers to minimize changeover disruption. Bavarian Mittelstand firms replace legacy CMMS installations at accelerated refresh rates, embedding maintenance triggers directly into production scheduling algorithms.
- Energy Management:Power generation and distribution asset monitoring integrates renewable intermittency forecasting with traditional equipment upkeep. German municipal utilities consolidate vendor relationships across hundreds of distributed generation assets through regional procurement boards.
- Facility Management:Commercial building maintenance coordinates HVAC, electrical, and structural upkeep across property portfolios.
- Fleet Upkeep:Vehicle maintenance scheduling aligns with utilization patterns and regulatory inspection intervals.
- Infrastructure Monitoring:Civil asset condition assessment supports long-term capital planning for bridges, tunnels, and pipelines.
Deployment scale favors Facility Management; Manufacturing Oversight generates the highest per-seat pricing through operational technology integration requirements.
End User:
Buyer sophistication and procurement centralization create distinct segment profiles, with regulated industries prioritizing compliance documentation while commercial operators emphasize cost optimization.
- Utilities Providers:Multi-site generation and distribution networks require enterprise-grade scalability with FERC reliability standards compliance. US regional transmission organizations negotiate framework agreements covering distributed asset portfolios, demanding API connectivity to power management and outage management systems.
- Transportation Operators:Aviation and rail maintenance organizations under FAA and EASA oversight maintain strict documentation chains. German and French MRO providers invest in explainable AI overlays to satisfy algorithmic transparency mandates for automated work order generation.
- Government Agencies:Public infrastructure maintenance balances budget constraints with service level agreements.
- Educational Institutions:Campus facility management spans academic, residential, and research building portfolios.
- Real Estate Firms:Commercial property operators prioritize tenant satisfaction metrics in maintenance prioritization.
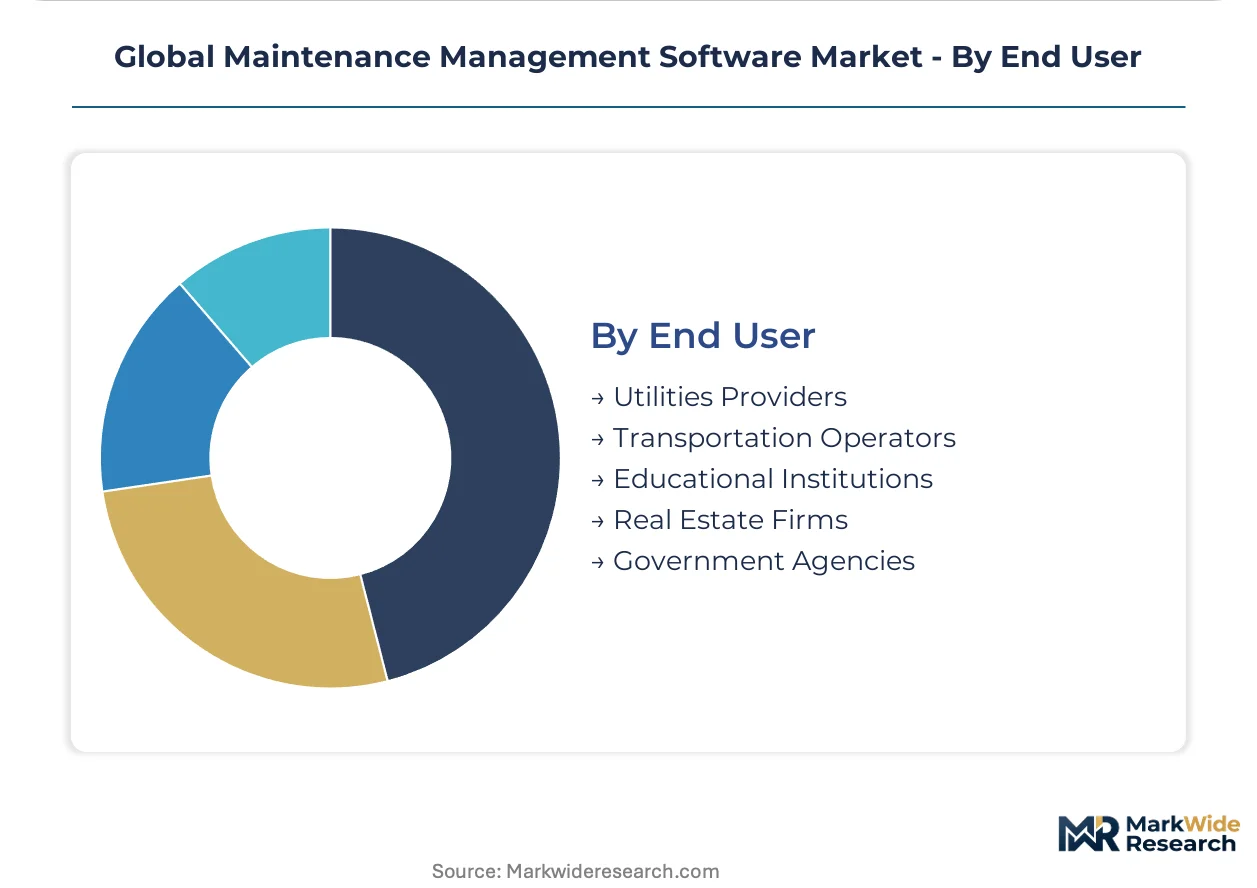
Contract value concentrates among Utilities Providers; Transportation Operators are gaining share fastest through aviation fleet expansion and rail modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for maintenance management software concentrates in Germany, the United States, and Japan where industrial digitization programs are deepest. Manufacturing oversight teams across these markets are expanding adoption of predictive maintenance modules. Cloud-first mandates from the EU AI Act and ISO 55000 asset management standards are accelerating platform upgrades.
United States
Utilities providers and transportation operators are consolidating vendor relationships across multi-site portfolios. The FAA and NHTSA enforce equipment reliability standards that drive aviation and fleet operators toward auditable digital maintenance logs. Regional aggregation boards in municipal utilities negotiate framework agreements covering hundreds of distributed generation assets.
Germany
Manufacturing clusters in Bavaria and Baden-Württemberg anchor European demand concentration, with Mittelstand firms replacing legacy CMMS installations at accelerated refresh rates. The EU AI Act imposes algorithmic transparency obligations on automated maintenance decision systems. EASA oversight drives German MRO providers to invest in explainable AI overlays for predictive analytics engines.
Japan
METI-backed Smart Maintenance initiatives target steel and chemical plants with thirty-year-old control systems ripe for connected monitoring retrofits. The country's aging asset base creates urgency for predictive module adoption. Kansai and Chubu industrial corridors prioritize uptime optimization in continuous process operations.
United Kingdom
Cloud-based SaaS architectures enable rapid deployment across distributed facilities without capital infrastructure commitments. GDPR compliance requirements shape procurement decisions for mid-market manufacturing accounts. London and Southeast England concentrate financial services and commercial property management demand for integrated facility maintenance platforms.
India
Mid-market manufacturing accounts lacking internal analytics capabilities seek SaaS platforms to accelerate predictive module adoption without IT expansion. The PLI scheme supports industrial digitization investments in automotive and electronics manufacturing clusters. Maharashtra and Gujarat host expanding deployment of mobile-enabled field technician access layers.
Global Maintenance Management Software Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in energy-intensive and regulated environments. The market structure reflects moderate consolidation around enterprise software incumbents with ERP-installed bases, alongside industrial automation vendors leveraging operational technology integration. Three archetypes dominate: ERP-extended maintenance modules, AI-infused asset health platforms, and industrial IoT-native suites. Competitive moves center on API ecosystem expansion and outcome-based service contracting unbundling software from MRO provider agreements.
Within the ERP-extended tier, SAP leverages its installed base to anchor maintenance modules within existing enterprise workflows. IBM competes through AI-infused asset health analytics that extend its Watson IoT footprint. Schneider Electric dominates in energy-intensive environments where its EcoStruxure platform integrates power and maintenance data streams. These three exemplify how competitive positioning depends on pre-existing customer relationships and vertical integration depth rather than standalone feature differentiation.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Oracle |
| Infor |
| Rockwell Automation |
| Honeywell |
| Schneider Electric |
| GE Digital |
| Siemens |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs from hyperscale providers cascade through SaaS subscription tiers, compressing margins for mid-market vendors while enabling premium pricing for predictive modules with embedded sensor hardware and machine learning training overhead.
Pricing Analysis
Volume concentrates in standardized SaaS subscriptions with automatic feature updates displacing perpetual licenses, while margins accrue to predictive maintenance tiers commanding premium positioning due to vibration sensor integration complexity and IEC 61508 functional safety certification requirements. Price differentiation hinges on operational technology integration depth and API connectivity to SCADA layers, with German automotive suppliers and US municipal utilities showing lowest price sensitivity due to compliance-driven procurement mandates. Cost compression runs through commodity work order management tiers as vendor consolidation intensifies competitive pressure. Mid-market manufacturing accounts lacking internal analytics capabilities exhibit highest price sensitivity, prioritizing rapid deployment without capital infrastructure commitments.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for edge computing chipsets that underpin hybrid deployment architectures, while vibration monitoring sensor hardware draws from German and Japanese precision manufacturing clusters. Raw material dependencies span silicon wafers, thermal imaging components, and industrial-grade lithium batteries for mobile field access devices. Tariff exposure on semiconductor imports from East Asian fabrication centers threatens margin stability for hardware-integrated predictive modules. Distribution runs through direct enterprise sales teams for large utilities and transportation operators, with channel partners serving mid-market manufacturing accounts lacking dedicated procurement infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act algorithmic transparency mandates are forcing smaller point-solution vendors toward exit or acquisition as compliance documentation requirements escalate fixed costs beyond sustainable thresholds.
For Market Incumbents: Acquire specialized condition monitoring startups with pre-trained machine learning models for vibration and thermal anomaly detection to neutralize talent scarcity threats in industrial data science. Deepen API ecosystem partnerships with Schneider Electric and Rockwell Automation to embed maintenance modules deeper into operational technology layers, defending against ERP-native competitors. Prioritize explainable AI overlay investments to satisfy EASA oversight requirements for automated work order generation in aviation maintenance organizations. For New Entrants and Emerging Players: Mid-market chemical processors in Japan's Kansai industrial corridor represent the most penetrable buyer archetype, with METI Smart Maintenance directives creating procurement urgency without incumbent lock-in. Target brownfield facilities struggling with SCADA integration complexity by offering protocol-translation middleware as a bundled service layer. Pursue outcome-based service contracting models that unbundle software from MRO provider agreements, securing direct data ownership for aviation and fleet operators under FAA equipment reliability standards. For Investors and Strategic Acquirers: Accelerated refresh rates among Bavarian Mittelstand firms replacing legacy CMMS installations is the leading indicator that consolidation momentum will intensify across European manufacturing clusters. Position acquisition targets around hybrid deployment specialists bridging edge-to-cloud pipelines for continuous process industries requiring sub-50-millisecond anomaly detection. Monitor FAA and NHTSA enforcement patterns for digital maintenance log requirements as the primary signal for aviation and fleet operator software procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity to ERP and SCADA layers anchors vendor relationships in multi-site utility portfolios. |
| Acquisition of Specialist Firm | Condition monitoring startups with pre-trained models neutralize industrial data science talent gaps. |
| Strategic Partnership | Collaboration with hyperscale cloud providers reduces infrastructure cost exposure for SaaS tiers. |
| Product Launch | Explainable AI overlays satisfy EU AI Act transparency mandates for automated maintenance decisions. |
| Geographic Expansion | Entry into Japan's Kansai and Chubu corridors captures METI-backed Smart Maintenance retrofit demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across maintenance directors, plant engineers, IT procurement officers, and OEM aftermarket service heads. Bottom-up triangulation validated against top-down macroeconomic indicators drew from EASA oversight documentation, FAA equipment reliability standards, METI Smart Maintenance program disclosures, and ISO 55000 implementation reports. SEC filings from ERP-extended maintenance module providers and hyperscaler capex disclosures supplied infrastructure cost benchmarks.
Granularity-level modeling deployed deployment architecture, solution offering depth, use case complexity, and end-user sophistication as core segmentation dimensions across the projection horizon. CAGRs derived from trend extrapolation of sensor hardware cost decline curves and SaaS subscription displacement rates in mid-market accounts. Industry-specific inputs incorporated EU AI Act implementation timelines, IEC 61508 functional safety adoption patterns, and regional procurement centralization metrics from US municipal utility aggregation boards.
Revisions become necessary when algorithmic transparency enforcement intensity shifts, sensor hardware supply disruptions materialize, or hyperscale cloud pricing architectures restructure SaaS margin economics. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and industrial digitization program funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
EDA Tools Market
Software & Services
Metal Recycling Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
File Analysis Software Market
Software & Services
Global VR Game Engine Software Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Webcasting Software Market
Software & Services
Winery Management Software Market
Software & Services
Event Management Software Market
Software & Services
Mining Simulation Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Attendance Management Software Market
Software & Services
Document Capture Software Market