
 Movie Editing Software Market | 2026-2036
Movie Editing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Movie Editing Software Market Insights
Professional-grade color grading and 4K finishing is reorganizing competitive dynamics in movie editing software. Adobe Inc. leverages deep integration across creative workflows to sustain enterprise loyalty. Blackmagic Design anchors its position through aggressive pricing of hardware-software bundles. Apple Inc. differentiates via silicon-optimized performance on proprietary devices.
Movie editing software comprises digital tools for non-linear video assembly, visual effects compositing, audio synchronization, and final output mastering, typically supporting codecs from ProRes to RAW formats with timeline precision measured in sub-frame increments. Its primary commercial purpose is enabling efficient post-production pipelines for feature films, streaming content, and advertising. Cloud-based deployment is capturing the fastest expansion as distributed production teams demand real-time collaboration capabilities. AI-driven tools are concentrating margin pools through automated scene detection and intelligent audio leveling. Professional software retains the largest revenue share due to subscription stickiness among studio clients.
The Federal Communications Commission oversees broadcast standards that shape output format requirements, while the Copyright Office influences licensing frameworks for stock asset integration. The European Union's AI Act is beginning to constrain automated content generation features in software distributed across member states. Stakeholders must monitor how export control classifications around AI inference engines affect cross-border software delivery.
Market Dynamics
AI inference engines embedded in editing suites are compressing post-production timelines from months to weeks, forcing incumbents to restructure subscription tiers around automated feature sets rather than seat counts alone.
Growth Catalysts
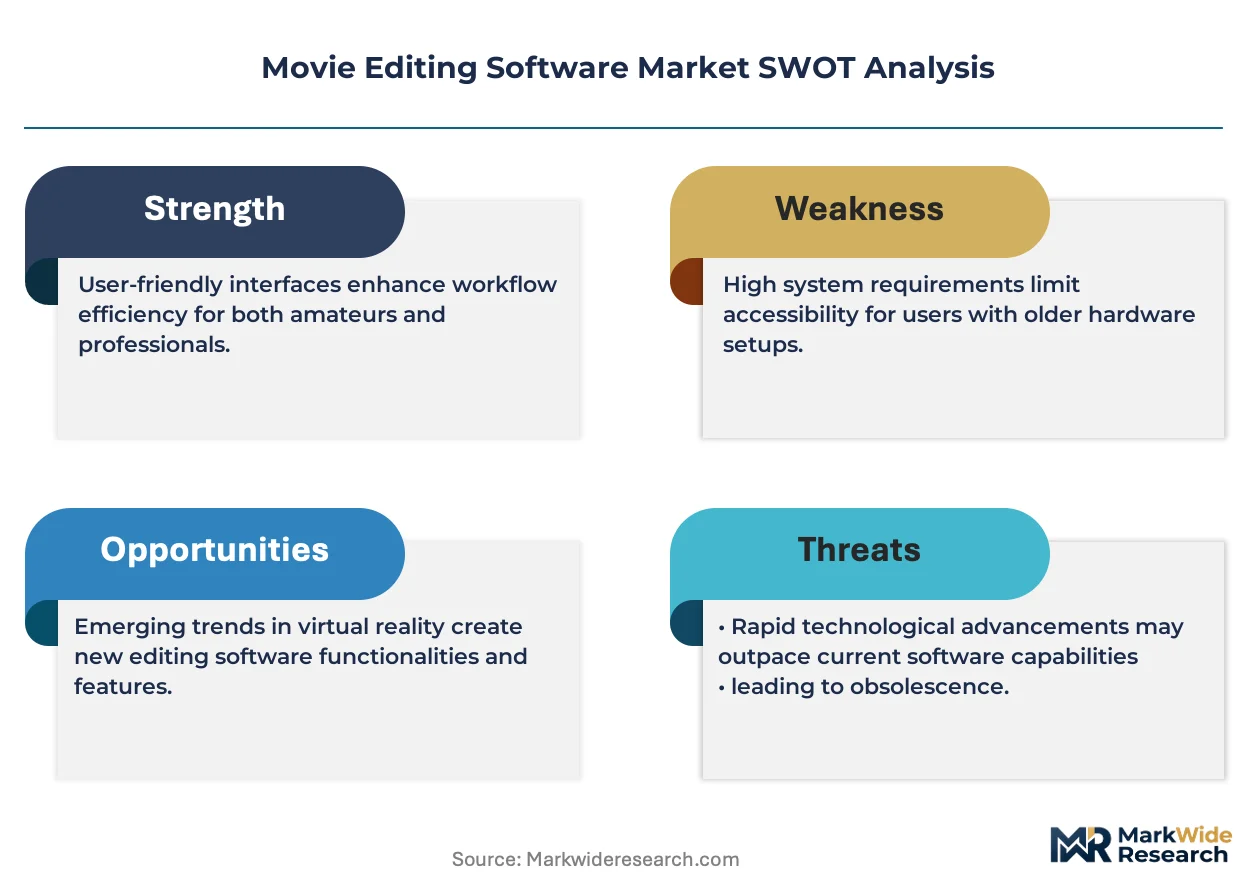
- EU AI Act compliance frameworks:Software vendors investing in transparent algorithmic auditing are securing preferential procurement status from European broadcasters and public funding bodies.
- Cloud-native collaboration pipelines:Distributed production teams across Los Angeles, London, and Seoul now demand frame-accurate remote editing, pulling infrastructure investment toward low-latency rendering farms.
- ProRes RAW codec proliferation:Camera manufacturers standardizing on this format are expanding the addressable base of editors requiring professional-grade debayering and color management tools.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan are lengthening hardware refresh cycles for AI-accelerated workstations, delaying software upgrades tied to new silicon.
- Perpetual license erosion:Adobe's subscription-only pivot has trained enterprise buyers to resist long-term vendor lock-in, compressing customer lifetime value across the competitive set.
- Cross-platform codec fragmentation:Inconsistent RED and ARRI RAW support between macOS and Windows builds forces studios to maintain redundant license pools.
Strategic Opportunities
- India post-production outsourcing:Mumbai and Hyderabad facilities are upgrading from service bureaus to creative partners, creating demand for localized software interfaces and rupee-denominated pricing.
- Spatial video finishing:Apple Vision Pro content pipelines require stereoscopic editing tools that existing suites have not fully instrumented, opening white space for specialized plugins.
- France's tax rebate schemes:The TRIP and recent increases in audiovisual production incentives are attracting foreign shoots to Paris, driving software procurement for temporary production offices.
Industry Challenges
- AI training data licensing:Unclear rights frameworks for using studio-owned footage to fine-tune generative fill and rotoscoping models are freezing feature deployment.
- Hybrid cloud security architecture:Studios handling unreleased theatrical content face SOC 2 and TPN compliance complexity when editors access projects from personal devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movie Editing Software Market |
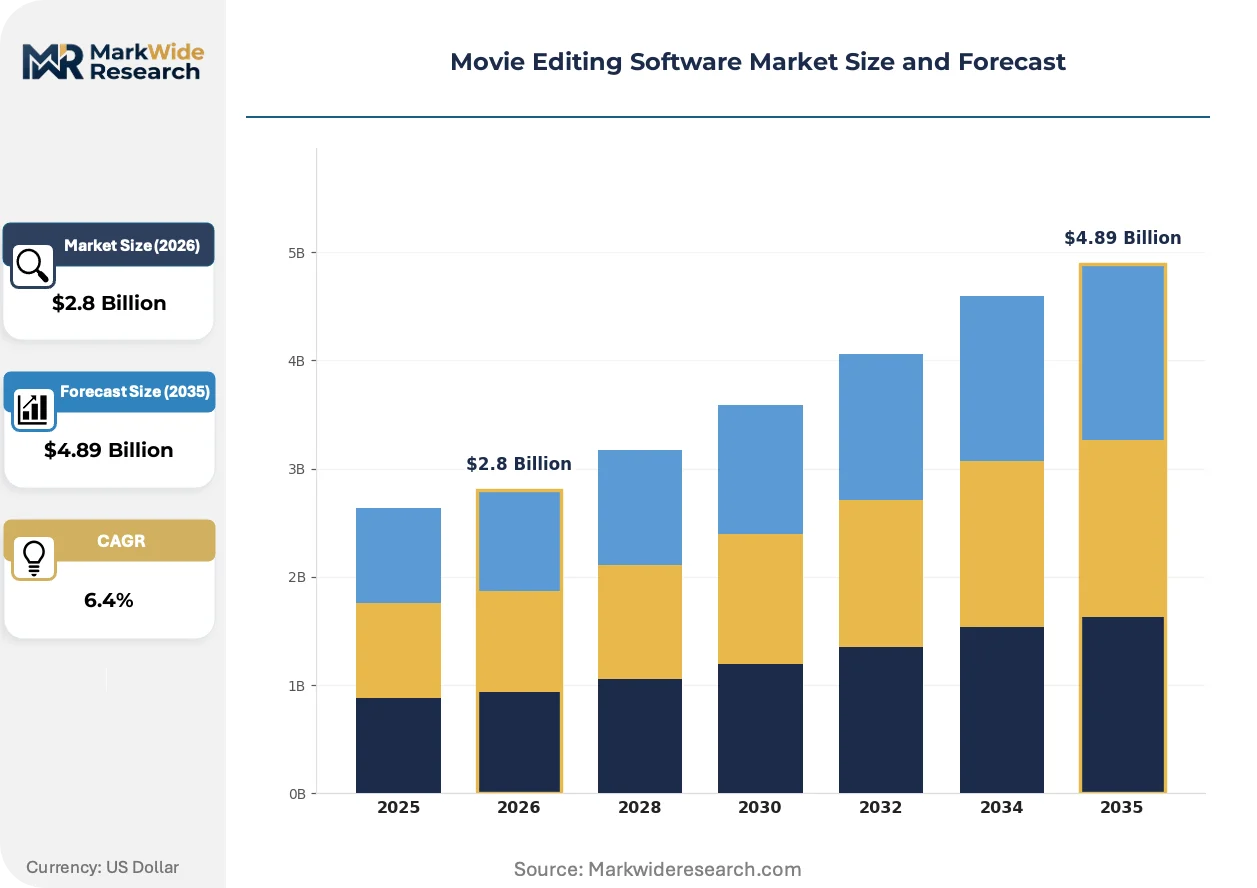
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional Software, Consumer Software, Cloud-based Software, Mobile Apps Technology: AI-driven Tools, Real-time Collaboration, 4K Editing, Color Grading End User: Filmmakers, YouTubers, Educators, Video Editors Deployment: On-premise, Cloud, Hybrid, Subscription-based |
| Companies Covered | Adobe Inc., Apple Inc., Avid Technology, Inc., Blackmagic Design, Autodesk Inc., CyberLink Corp., Corel Corporation, MAGIX Software GmbH, TechSmith Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movie Editing Software Market Trends and Innovations
Computational photography pipelines and neural rendering are dissolving the boundary between production and post, enabling decisions once deferred to editing suites to migrate onto set.
On-device machine learning inference is miniaturizing tasks previously requiring server farms. Local neural engines in M-series and Snapdragon silicon now handle real-time object segmentation and speech-to-text transcription. Independent creators operating from home studios in Austin and Berlin are adopting these workflows fastest, compressing the addressable market for cloud-rendered AI features among solo practitioners.
The EU AI Act's transparency requirements for automated decision-making are reshaping feature development roadmaps. Software vendors must now document training data provenance and provide opt-out mechanisms for generative tools. European public broadcasters in Copenhagen and Amsterdam are inserting these compliance clauses into RFPs, accelerating vendor investment in explainable AI interfaces.
Subscription fatigue among mid-market production companies is fragmentizing purchasing authority. Department heads now evaluate editing tools against per-project economics rather than enterprise-wide standardization, enabling niche challengers to secure departmental footholds. This pattern is most visible in Atlanta's booming commercial production sector, where freelance editors bring personal license preferences that override IT procurement policies.
Movie Editing Software Market Segmentation
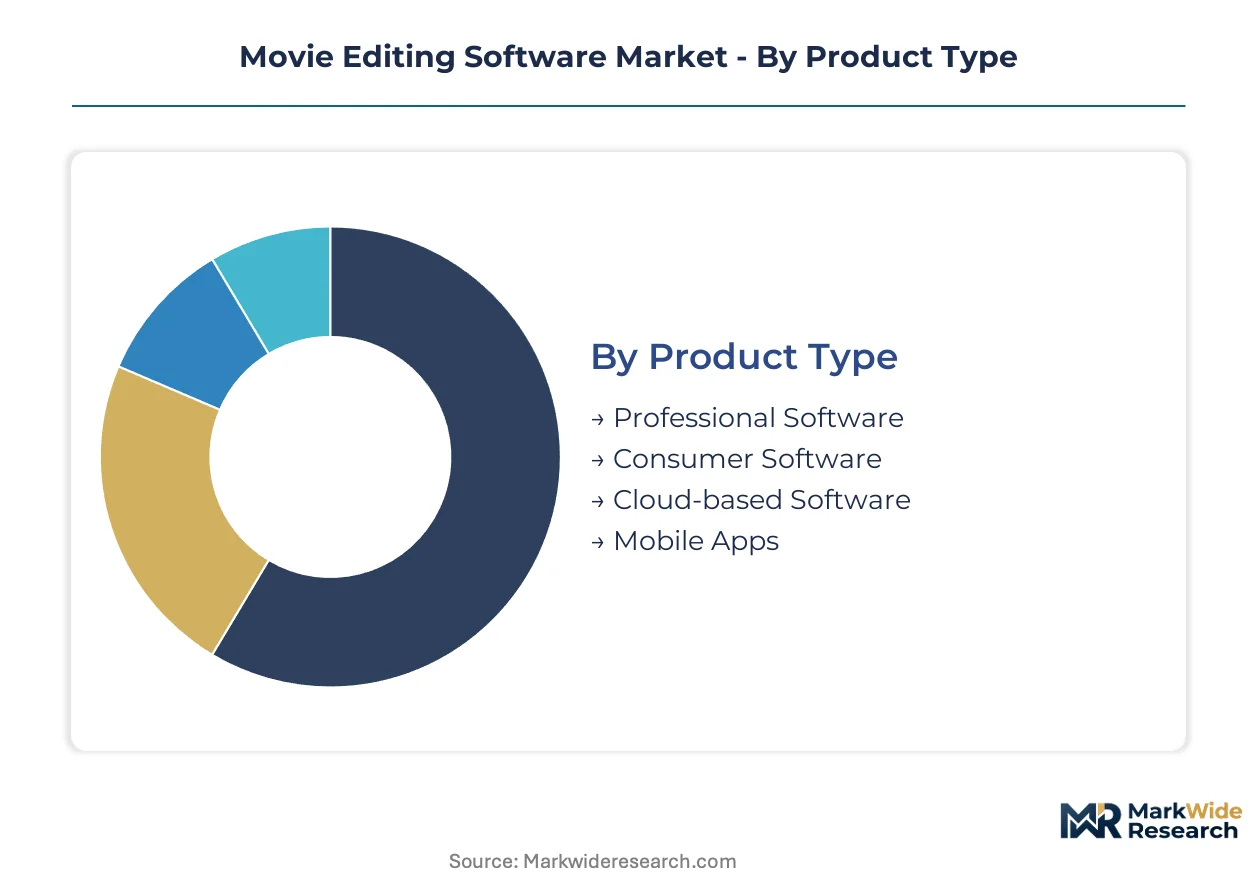
Segmentation in movie editing software reveals how purchasing authority fragments across professional hierarchies and technical requirements. Channel strategies diverge sharply between enterprise procurement teams and individual creator subscriptions.
Product Type:
Professional software flows through direct sales teams and value-added resellers serving studio procurement departments. Consumer titles distribute predominantly via app stores and retail bundles.
- Professional Software:Full-featured suites support RAW debayering, HDR grading, and multi-user project management with frame-accurate timeline precision. Major studios in Los Angeles and London standardize on these platforms, locking in multi-year enterprise agreements that resist churn despite subscription fatigue elsewhere.
- Cloud-based Software:Browser-native editing environments enable distributed teams to collaborate without local hardware investments. Post-production facilities in Mumbai and Seoul are adopting these fastest, driven by talent dispersion and infrastructure cost pressures.
- Consumer Software:Entry-level tools emphasize template-driven workflows and simplified export presets for social platforms. YouTube creators in Austin and Berlin purchase these through direct-to-consumer channels with minimal sales touch.
- Mobile Apps:Touch-optimized interfaces with automated clip assembly and music synchronization. Independent journalists and documentary shooters in conflict zones rely on these for field editing where laptop power is unavailable.
By volume, Consumer Software leads. By growth pace, Cloud-based Software is ahead.
Technology:
Technology segmentation tracks where R&D investment concentrates and which capabilities command pricing premiums. Margin pools cluster around automation features that compress skilled labor hours.
- AI-driven Tools:Neural engines automate scene detection, speech transcription, and generative fill operations. European broadcasters in Copenhagen now require algorithmic transparency documentation under EU AI Act procurement clauses, reshaping vendor development priorities.
- 4K Editing:High-resolution timeline processing with proxy workflows and hardware-accelerated decode. Streaming platforms mandating 4K delivery are pulling demand from traditional HD finishing across production categories.
- Real-time Collaboration:Frame-accurate multi-user editing with conflict resolution and version branching. Distributed productions spanning Los Angeles-London-Seoul time zones depend on these pipelines.
- Color Grading:Dedicated toolsets for HDR mastering, LUT management, and calibrated monitoring integration. Feature film finishing in Paris and Rome maintains premium pricing for specialized colorists using these modules.
AI-driven Tools capture the steepest expansion trajectory. Color Grading retains the highest margin per seat.
End User:
End user segmentation determines interface complexity, pricing tier, and support model. Procurement authority varies dramatically between institutional buyers and individual practitioners.
- Filmmakers:Feature and episodic directors requiring end-to-end post-production pipelines with deliverable compliance for theatrical and streaming distribution. These users anchor professional software revenue through studio-funded licenses.
- YouTubers:Platform-native creators optimizing for upload velocity and algorithmic performance metrics. This segment is fragmenting purchasing authority, with individual creators overriding IT standardization in Atlanta's commercial production sector.
- Educators:University film programs and training institutions requiring volume licensing with curriculum integration and student certification pathways. Institutions in Hyderabad and Mumbai are expanding these programs.
- Video Editors:Staff and freelance post-production professionals executing client-directed revisions. Freelance editors increasingly bring personal license preferences that complicate enterprise procurement consolidation.
Filmmakers generate the highest revenue per account. YouTubers are expanding most quickly.
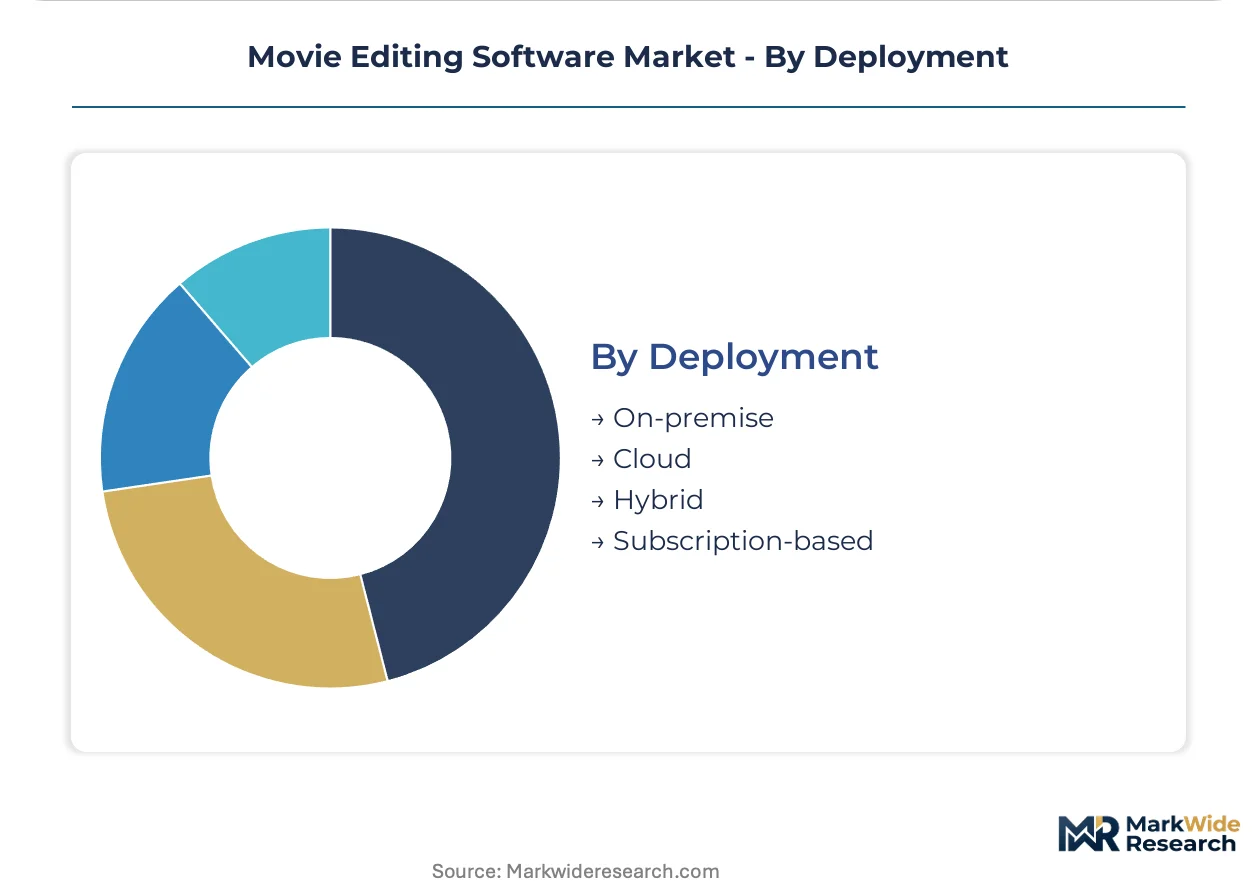
Deployment:
Deployment models reflect security requirements, capital constraints, and collaboration needs. Hybrid architectures are emerging where neither pure cloud nor on-premise satisfies studio risk protocols.
- Subscription-based:Recurring revenue models with tiered feature access and continuous update delivery. Adobe's pivot to this model has trained enterprise buyers to resist long-term lock-in, compressing customer lifetime value across competitors.
- On-premise:Perpetual licenses with local hardware dependencies and air-gapped security for unreleased content. Major studios handling theatrical releases maintain these for SOC 2 and TPN compliance.
- Cloud:Fully hosted environments with browser access and centralized asset storage. Independent creators in Austin and Berlin lacking IT infrastructure adopt these fastest.
- Hybrid:Split architectures keeping sensitive assets on-premise while leveraging cloud rendering for compute-intensive operations. This configuration addresses the security architecture challenges studios face when editors access projects from personal devices.
Subscription-based deployment leads by active seat count. Hybrid configurations are climbing the fastest as security-conscious studios seek compromise solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Independent creators in Berlin and Austin resist subscription escalations, while Los Angeles studios absorb premium tiers for enterprise-grade security. European broadcasters impose compliance premiums that reshape vendor pricing architecture.
United States
Streaming platform mandates for 4K delivery pull upgrade cycles forward. The FCC shapes broadcast output standards that ripple through post-production workflows. Los Angeles production clusters anchor professional software revenue through multi-year studio agreements.
Germany
Public broadcaster procurement under the EU AI Act favors vendors with algorithmic transparency documentation. The ECHA and national data protection authorities scrutinize cloud data residency. Munich and Hamburg post-production houses drive demand for hybrid deployment models.
India
Mumbai and Hyderabad facilities upgrade from service bureaus to creative partners, demanding localized interfaces. The BIS influences software import certification timelines. Bangalore's independent creator economy accelerates mobile-first editing adoption.
United Kingdom
London production clusters sustain premium pricing for real-time collaboration tools across distributed teams. The UK Information Commissioner's Office shapes cloud security requirements for unreleased content. Manchester's emerging commercial sector fragments purchasing authority toward freelance preferences.
South Korea
Seoul-based streaming platforms compress post-production timelines, accelerating AI tool integration. The MFDS and national broadcast regulator KCC influence content delivery standards. Busan film festival infrastructure drives temporary software procurement for international productions.
Movie Editing Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Adobe and Apple anchor the premium tier through ecosystem integration and silicon optimization, while Blackmagic Design captures price-sensitive professionals through hardware-software bundling. Strategic moves concentrate on AI feature deployment and cloud infrastructure partnerships rather than direct price competition.
Within the integrated ecosystem tier, Adobe Inc. and Apple Inc. exemplify platform-centric strategies that lock in creative workflows across multiple production stages. Blackmagic Design occupies a position as the hardware-coupled challenger, disrupting pricing norms through aggressive bundle economics. Avid Technology, Inc. sits within the specialized broadcast segment, serving institutional clients with entrenched infrastructure requirements. Autodesk Inc. represents the diversified design software conglomerate, leveraging cross-industry R&D spillovers into media production tools.
| Leading Market Players |
|---|
| Adobe Inc. |
| Apple Inc. |
| Avid Technology, Inc. |
| Blackmagic Design |
| Autodesk Inc. |
| CyberLink Corp. |
| Corel Corporation |
| MAGIX Software GmbH |
| TechSmith Corporation |
| Others |
Pricing and Supply Chain Analysis
FCC broadcast compliance certification gates both supplier qualification and tiered pricing differentiation in the movie editing software market. Studios demanding TPN and SOC 2 security attestations for unreleased theatrical content pay substantial premiums over independent creators operating without such mandates. This regulatory layering concentrates margin pools among vendors capable of documenting enterprise-grade security architecture.
Pricing Analysis
After-sales service contracts and extended technical support tiers drive lifetime value for professional editing suites. Subscription-based SaaS models dominate revenue architecture, with pricing stratifying across enterprise, professional, and independent creator tiers based on security certification level and multi-user collaboration scale. Cost compression in the mid-market segment intensifies as freelance editors resist vendor lock-in learned from Adobe's subscription-only pivot. Independent creators in Berlin and Austin exhibit highest price sensitivity, while Los Angeles studios absorb premium tiers for SOC 2 compliance.
Supply Chain Analysis
Taiwanese foundry capacity for AI-accelerated GPU silicon underwrites workstation refresh cycles and software upgrade timing. Software development concentrates in the United States, India, and Germany, with cloud infrastructure sourcing from hyperscaler regions in Virginia, Frankfurt, and Singapore. Supply chain risk centers on single-source vulnerability for neural inference engines trained on licensed studio footage. Distribution runs through direct enterprise sales teams, value-added resellers, and app store channels segmented by buyer scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where ecosystem interoperability determines competitive survival. Adobe's Creative Cloud integration and Apple's silicon-optimized pipelines demonstrate how workflow lock-in supersedes feature parity.
For Market Incumbents: Secure algorithmic transparency documentation to satisfy EU AI Act procurement clauses from European public broadcasters. Deepen backward integration into cloud rendering infrastructure to defend against niche challengers exploiting subscription fatigue among mid-market production companies in Atlanta. For New Entrants and Emerging Players: ISO 27001 and TPN certification fast-tracks unlock studio procurement doors otherwise closed to unproven vendors. Spatial video finishing tools for Apple Vision Pro pipelines represent the most penetrable white space, with localized rupee-denominated pricing for Mumbai post-production facilities as the primary go-to-market angle. For Investors and Strategic Acquirers: The EU AI Act's transparency requirements reshape the acquisition landscape toward vendors with documented training data provenance and explainable AI interfaces. Long-term viability favors specialized plugin developers with entrenched color grading or audio synchronization modules. Watch for inflection signals in hybrid cloud security architecture adoption rates among studios handling theatrical releases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Creative Cloud or Final Cut Pro ecosystem embedding locks enterprise workflows against churn. |
| AI Feature Deployment | Automated scene detection and generative fill tools command pricing premiums from streaming platforms. |
| Strategic Partnership | Hyperscaler alliances with AWS or Azure enable low-latency rendering farms for distributed productions. |
| Geographic Expansion | Localized interfaces and rupee pricing capture Mumbai and Hyderabad post-production upgrading from service bureaus. |
| Acquisition of Specialist Firm | Stereoscopic editing plugins for Apple Vision Pro fill capability gaps in existing suite architectures. |
Research Methodology
Cross-validation between CTO interviews at Los Angeles production studios and hyperscaler capex disclosures anchors the qualitative findings. Primary fieldwork engaged post-production facility directors, IT procurement officers at streaming platforms, color grading specialists, and channel partners distributing professional licenses. Secondary sources included SEC 10-K filings from publicly traded software vendors, App Store and Google Play revenue estimates, and European Broadcasting Union procurement databases. Bottom-up seat count estimates triangulated against top-down revenue segmentation.
Sensitivity analysis around AI adoption curves and subscription renewal rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derive from trend extrapolation of seat growth and average revenue per user movements, with ProRes RAW codec proliferation and cloud-native collaboration demand as key industry-specific inputs.
Underlying assumptions cover sustained streaming platform 4K mandates and stable GPU supply from Taiwanese foundries, with deviation risk concentrated in AI training data licensing disputes and export control reclassifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Municipal Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Document Management Software Market
Software & Services
Newsroom Software Market
Software & Services
3D Modeling Software Market
Software & Services
Tech Support Services Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Global Self-Service BI Market
Software & Services
Projector Software Market
Software & Services
PCB CAD Software Market