
 Human Resource Analytics Market | 2026-2036
Human Resource Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Human Resource Analytics Market Insights
Data science talent scarcity is bifurcating vendor capabilities across the Human Resource Analytics landscape. SAP SE leverages its embedded S/4HANA workforce modules to anchor enterprise accounts in manufacturing-heavy economies. Oracle Corporation competes through integrated Fusion Cloud HCM analytics that sustain renewal rates among Fortune 500 clients. Workday Inc. specializes in native AI-driven talent mobility scoring, differentiating its platform for technology and professional services buyers.
Human resource analytics encompasses the systematic application of statistical modeling, machine learning algorithms, and predictive diagnostics to workforce data sets spanning headcount planning, retention risk scoring, compensation equity analysis, and productivity optimization. Cloud-based deployment now leads functionality expansion, with SaaS delivery models capturing the fastest-growing margin pools as IT verticals prioritize API-first architectures. Workforce planning functionality maintains mature adoption curves among corporations, while recruitment analytics experiences accelerated uptake as talent acquisition teams demand real-time funnel diagnostics.
FCC guidelines on algorithmic transparency in employment screening intersect with EU AI Act risk classification requirements for automated hiring systems, compressing vendor compliance timelines. GDPR data residency rules and HIPAA workforce credentialing standards further fragment deployment architectures across regulated industries. Buyers must evaluate whether prospective platforms embed auditable bias-detection protocols before committing to multi-year contracts.
Market Dynamics
EU AI Act risk classification for automated employment systems is compressing vendor certification timelines while fragmenting procurement standards across multinational enterprises with dual US-EU footprints.
Growth Catalysts
- Cloud migration mandates:Financial services firms in the United States are accelerating SaaS adoption for workforce planning modules as IT verticals prioritize API-first architectures.
- GDPR data residency enforcement:European enterprises must maintain auditable workforce data localization, expanding demand for region-specific deployment architectures.
- Real-time funnel diagnostics:Talent acquisition teams now require instantaneous recruitment analytics, pulling functionality investment toward predictive screening algorithms.
Market Restraints
- Algorithmic transparency compliance costs:FCC guidelines on employment screening automation impose documentation burdens that inflate implementation timelines for mid-market buyers.
- Data science talent scarcity:Vendor capability bifurcation concentrates advanced machine learning development among firms with captive AI research pipelines.
- HIPAA workforce credentialing fragmentation:Healthcare sector buyers face divergent state-level privacy interpretations that complicate multi-tenant platform architectures.
Strategic Opportunities
- Compensation equity analytics:Unmet demand for pay-gap diagnostics creates white space for platforms embedding statistical bias-detection protocols.
- CSRD workforce disclosure mandates:European sustainability reporting requirements will force listed companies to adopt standardized human capital metrics by 2025 implementation deadlines.
- Edge AI deployment:Convergence of federated learning with on-device inference enables real-time productivity optimization without centralized data pooling.
Industry Challenges
- Multi-year contract lock-in:Enterprise buyers demand embedded bias-audit capabilities before committing to subscription terms, extending sales cycles.
- Legacy HCM integration friction:SAP and Oracle incumbent systems resist API interoperability, forcing analytics vendors to maintain expensive connector development.
Report Scope
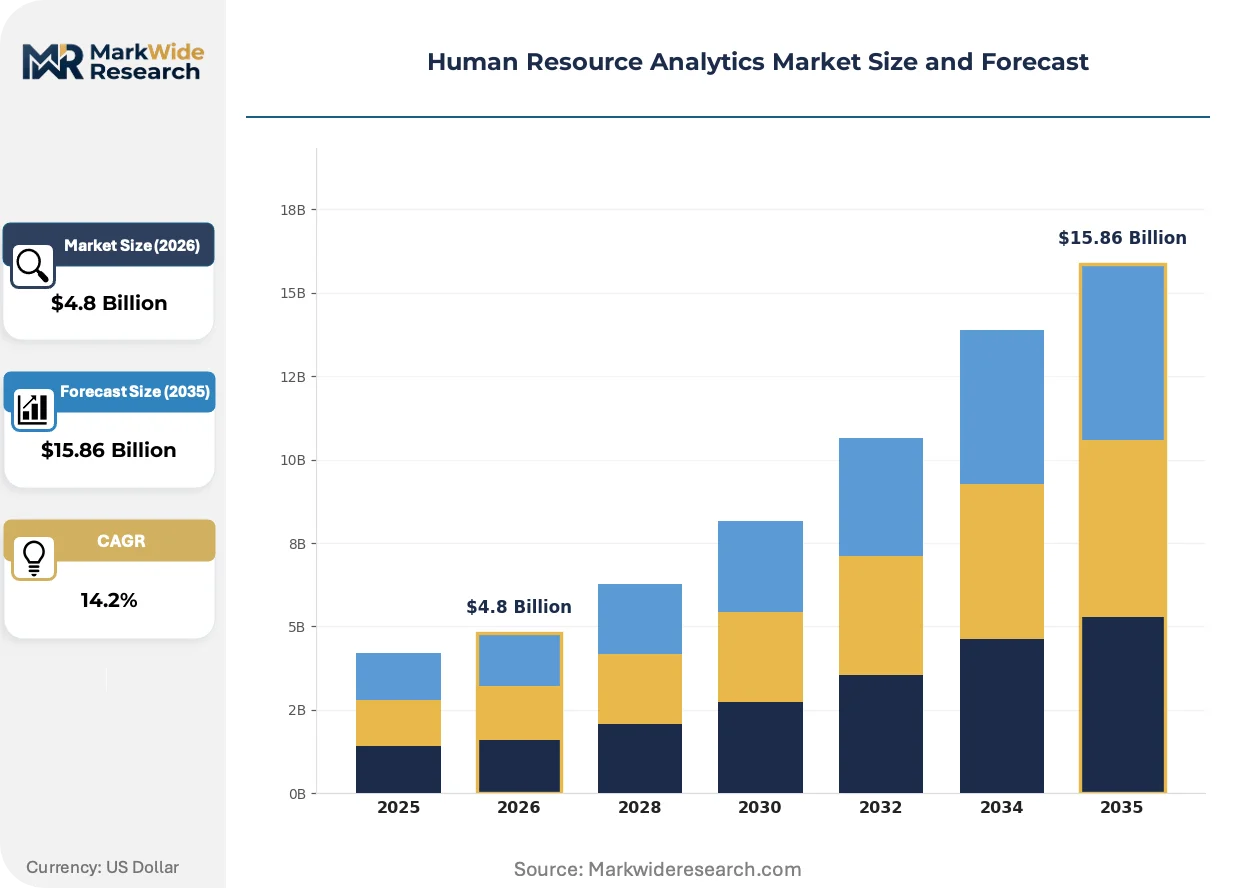
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Resource Analytics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Software-as-a-Service End User: Corporations, Small and Medium Enterprises, Consulting Firms, Educational Institutions Functionality: Workforce Planning, Recruitment Analytics, Employee Performance, Talent Management Industry Vertical: IT, Healthcare, Retail, Finance |
| Companies Covered | SAP SE, Oracle Corporation, Workday Inc., IBM Corporation, ADP Inc., Infor, UKG Inc., MicroStrategy Inc., Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Resource Analytics Market Trends and Innovations
Workforce analytics functionality is diverging along deployment-model lines as buyers prioritize either centralized cloud governance or edge-resident inference for sensitive biometric data streams.
Natural language processing for sentiment analysis of employee communications is fragmenting competitive positioning among vendors. Technology and professional services firms now deploy real-time mood-scoring across distributed teams. This capability is fragmenting traditional annual engagement surveys into continuous monitoring contracts with monthly pricing structures.
The EU AI Act's high-risk system designation for automated hiring tools is forcing algorithmic documentation standards across European deployments. Vendors must maintain technical files demonstrating bias mitigation for each screening model. France's CNIL and Germany's federal data protection authorities are issuing divergent guidance on legitimate interest assessments for workforce monitoring.
Subscription unbundling is separating analytics modules from core HCM platforms. Mid-market buyers now procure point solutions for retention risk scoring through specialized vendors rather than monolithic suites. This pattern concentrates in California and Texas technology hubs where talent mobility volatility demands rapid-deployment tooling.
Human Resource Analytics Market Segmentation
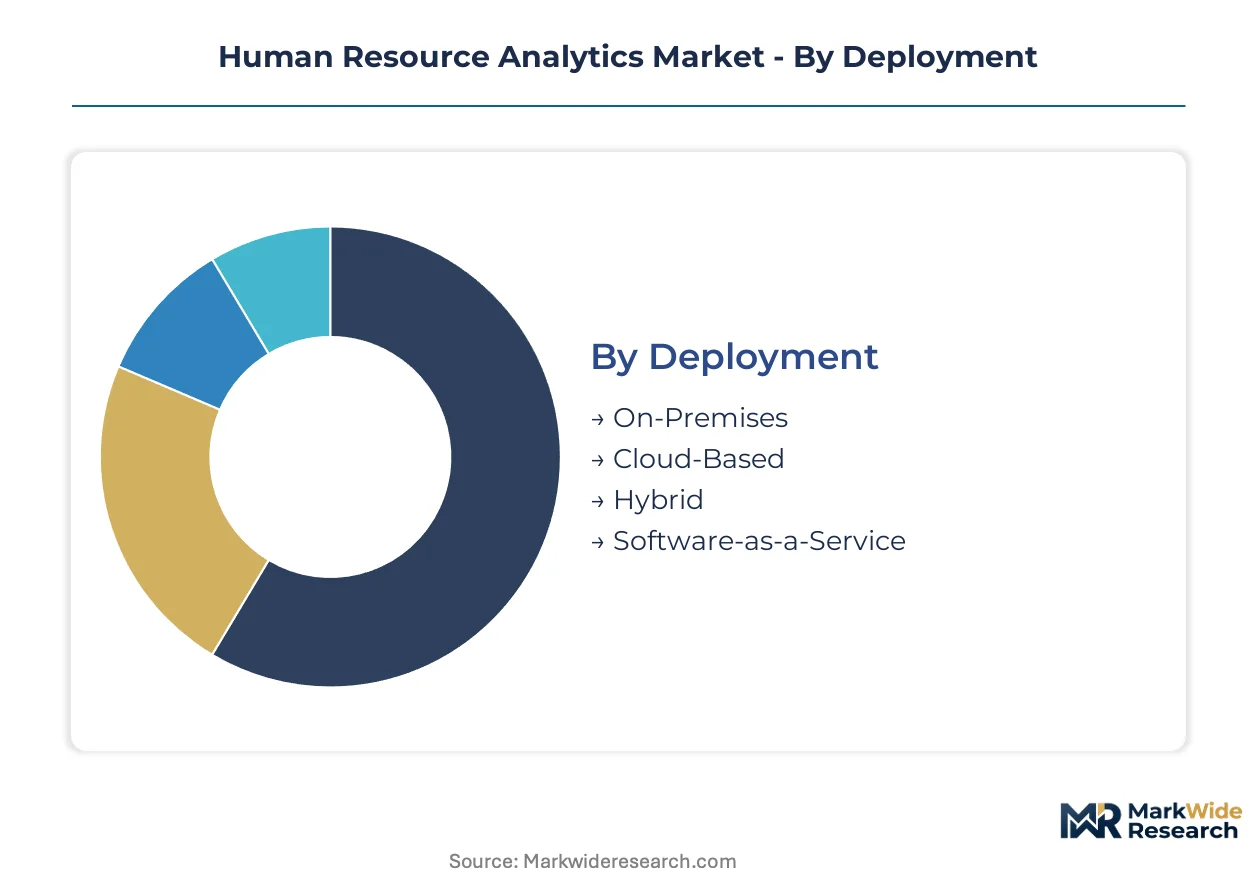
HR analytics procurement patterns diverge sharply by deployment model and buyer sophistication. Channel strategies must align with how corporations versus mid-market firms consume workforce intelligence tools.
Deployment:
Channel economics favor recurring revenue streams for cloud-native delivery, while on-premises retention concentrates among regulated buyers with captive IT infrastructure.
- Cloud-Based:Multi-tenant architectures with API-first design dominate new logo acquisition among technology and professional services firms. California and Texas technology hubs drive demand for real-time scalability without capital expenditure.
- Software-as-a-Service:Subscription bundling with automatic feature updates sustains renewal rates above legacy perpetual licenses. Financial services procurement teams prioritize SaaS for workforce planning modules to accelerate implementation timelines.
- On-Premises:Single-tenant installations persist among healthcare systems navigating HIPAA workforce credentialing fragmentation.
- Hybrid:Split architectures accommodate EU GDPR data residency enforcement for European employee records while maintaining US-based analytics engines.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Buyer sophistication tiers dictate sales cycle length and implementation complexity, with enterprise procurement demanding embedded compliance documentation.
- Corporations:Fortune 500 procurement mandates require algorithmic transparency documentation for FCC employment screening compliance. Multi-year contracts lock in advanced predictive diagnostics for retention risk scoring.
- Consulting Firms:White-label analytics resale creates secondary demand for configurable workforce planning dashboards serving client advisory engagements.
- Small and Medium Enterprises:Point-solution procurement through self-service marketplaces bypasses traditional enterprise sales motions.
- Educational Institutions:Budget-constrained buyers favor open-source integrations with existing student information systems.
Corporations capture the highest contract values. Small and Medium Enterprises represent the steepest expansion trajectory.
Functionality:
Feature adoption curves separate mature workforce planning from emerging recruitment analytics investment priorities.
- Workforce Planning:Headcount optimization algorithms with scenario modeling anchor enterprise deployments. Manufacturing-heavy economies sustain demand for S/4HANA-integrated modules.
- Recruitment Analytics:Real-time funnel diagnostics with predictive screening algorithms attract talent acquisition team investment. EU AI Act high-risk system designation forces bias-detection protocol documentation.
- Employee Performance:Continuous feedback systems displace annual review cycles among distributed technology teams.
- Talent Management:Succession planning with mobility scoring integrates with compensation equity analytics for retention strategy.
Workforce Planning dominates installed base. Recruitment Analytics is where expansion concentrates.
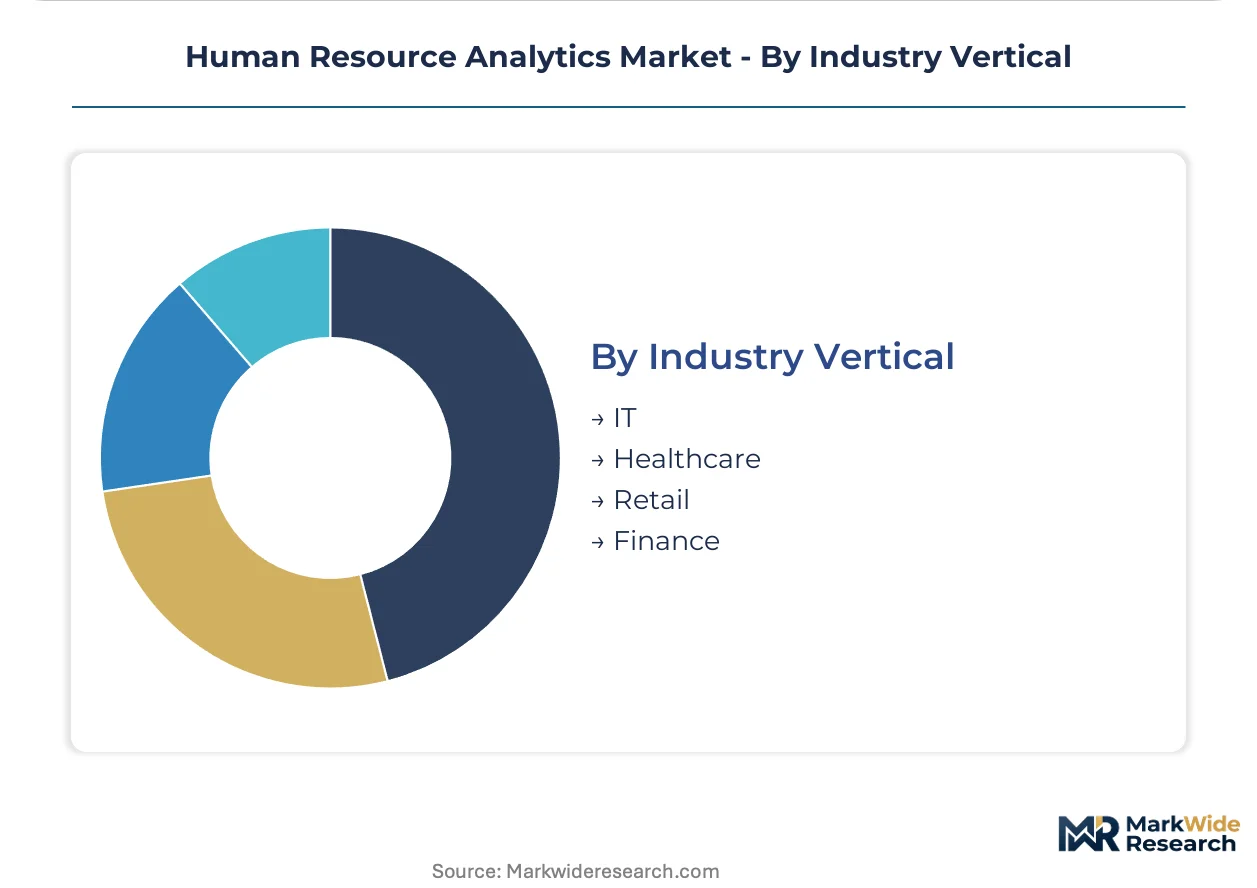
Industry Vertical:
Regulatory exposure and labor market volatility shape vertical-specific feature requirements and deployment preferences.
- IT:Native AI-driven talent mobility scoring addresses high churn rates in California and Texas technology clusters. API-first architectures align with internal engineering standards.
- Finance:FCC algorithmic transparency guidelines intersect with SEC disclosure requirements for workforce risk metrics. Cloud migration mandates accelerate SaaS adoption.
- Healthcare:HIPAA workforce credentialing standards fragment multi-tenant platform architectures across state-level privacy interpretations.
- Retail:Seasonal workforce volatility drives demand for rapid-deployment scheduling analytics with hourly labor optimization.
IT dominates installed base. Finance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure requirements for workforce risk metrics anchor procurement mandates in the United States, while EU AI Act high-risk system designations reshape vendor certification timelines across European deployments.
United States
Financial services firms in New York and Chicago accelerate cloud migration mandates for workforce planning modules. FCC algorithmic transparency guidelines intersect with SEC disclosure requirements for employment screening automation. California's Silicon Valley technology clusters drive demand for native AI-driven talent mobility scoring among high-churn software enterprises.
Germany
Manufacturing-heavy economies sustain demand for S/4HANA-integrated workforce planning modules among industrial conglomerates. The EU AI Act forces algorithmic documentation standards for automated hiring systems, with Germany's federal data protection authority issuing divergent guidance on legitimate interest assessments. Bavaria's automotive and machinery clusters anchor enterprise accounts requiring predictive retention risk scoring.
United Kingdom
GDPR data residency enforcement expands demand for region-specific deployment architectures among multinational enterprises with dual US-EU footprints. The Information Commissioner's Office scrutinizes workforce monitoring legitimate interest assessments. London's financial services sector procures real-time funnel diagnostics for talent acquisition teams navigating post-Brexit labor mobility constraints.
France
CSRD workforce disclosure mandates force listed companies to adopt standardized human capital metrics by implementation deadlines. France's CNIL issues granular guidance on algorithmic transparency for automated employment systems. Paris-based consulting firms create secondary demand for configurable workforce planning dashboards serving client advisory engagements.
India
IT verticals prioritize API-first architectures for cloud-native HR analytics delivery among Bangalore and Hyderabad technology clusters. The country's national data protection framework shapes workforce data localization requirements for multinational back-office operations. Mumbai financial services firms accelerate SaaS adoption for compensation equity analytics addressing pay-gap diagnostics.
Human Resource Analytics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with enterprise software conglomerates anchoring high-value accounts through embedded HCM modules. The mid-market fragments across point-solution vendors offering unbundled analytics modules for retention risk scoring and recruitment diagnostics. Two strategic archetypes dominate: integrated platform providers leveraging existing ERP relationships, and cloud-native specialists competing on deployment velocity. Competitive moves concentrate on API interoperability investments and bias-detection protocol certification to compress enterprise sales cycles.
Within the integrated platform tier, SAP SE and Oracle Corporation exemplify archetypes leveraging embedded workforce modules to anchor manufacturing and Fortune 500 accounts respectively. Workday Inc. occupies a specialist position native to cloud delivery, with its AI-driven talent mobility scoring differentiating among technology and professional services buyers in high-churn labor markets.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Workday Inc. |
| IBM Corporation |
| ADP Inc. |
| Infor |
| UKG Inc. |
| MicroStrategy Inc. |
| Tableau Software |
| Others |
Pricing and Supply Chain Analysis
EU AI Act high-risk system certification gates both vendor qualification and price differentiation across the Human Resource Analytics landscape, compressing procurement timelines while stratifying subscription tiers by compliance documentation depth. Buyers in regulated industries now face dual qualification hurdles that simultaneously inflate implementation costs and segment pricing power.
Pricing Analysis
Multi-year enterprise offtake contracts dominate procurement above mid-market thresholds, with Fortune 500 buyers locking in embedded bias-audit capabilities through three-to-five-year subscription terms. Pricing stratifies across premium, standard, and economy tiers based on API call volume allowances and algorithmic transparency documentation depth. Cost compression in the standard tier intensifies because SaaS-native entrants undercut legacy suite bundling with unbundled point solutions. Small and medium enterprises exhibit highest price sensitivity, while financial services procurement teams prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Inbound cloud infrastructure costs from hyperscaler data center concentration in Virginia, Oregon, and Frankfurt shape vendor margin structures across deployment architectures. Software development labor pools in India, Poland, and Romania feed engineering capacity for API-first platform builds. Single-source vulnerability rests on concentrated hyperscaler reliance for GPU-accelerated inference workloads. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by self-service marketplaces and consulting firm resale channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Human Resource Analytics market sits at a platform-economics inflection where API interoperability investments determine ecosystem captivity, with Workday's native cloud architecture demonstrating how embedded integration layers displace incumbent ERP lock-in.
For Market Incumbents: Shield embedded S/4HANA and Fusion Cloud HCM accounts through accelerated connector development for third-party analytics APIs, neutralizing the threat of unbundled point-solution poaching. Prioritize bias-detection protocol certification investment to compress enterprise sales cycles currently elongated by compliance documentation demands. For New Entrants and Emerging Players: Lead with compensation equity analytics modules targeting mid-market professional services firms in California and Texas, where pay-gap disclosure mandates create immediate procurement urgency. White-label through consulting firm channels to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed SaaS specialists possessing captive AI research pipelines but limited ERP integration depth, presenting rollup opportunities for platform consolidation. Watch for FCC algorithmic transparency rulemaking expansion as the inflection signal triggering accelerated vendor M&A.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Neutralizes legacy HCM lock-in by enabling seamless third-party analytics integration for Fortune 500 buyers. |
| Bias-Detection Protocol Certification | Accelerates EU AI Act compliance timelines for automated hiring system deployments across European footprints. |
| Edge AI Deployment Architecture | Enables real-time productivity optimization without centralized data pooling for GDPR-sensitive biometric streams. |
| Consulting Firm Channel Partnership | Creates secondary demand through white-label analytics resale for advisory engagements in London and Paris. |
| Compensation Equity Module Launch | Captures CSRD-mandated pay-gap disclosure demand among European listed companies facing workforce reporting deadlines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CHROs, IT procurement officers, talent acquisition directors, and workforce analytics vendors; and secondary validation against SEC 10-K workforce risk disclosures, EU AI Act technical documentation requirements, and hyperscaler capex deployment patterns. Bottom-up segment sizing triangulated against top-down macroeconomic labor market indicators across the analysis window.
Across the projection horizon, the forecasting framework modeled deployment model, organization size, vertical regulatory exposure, and regional compliance cluster segmentation. CAGRs derived from historical SaaS adoption curves in adjacent enterprise software categories, adjusted for EU AI Act implementation pacing and FCC algorithmic transparency rulemaking trajectory. Workforce planning module renewal rates and recruitment analytics new-logo acquisition velocity served as industry-specific demand inputs.
Forecasts assume regulatory continuity in EU AI Act risk classification and FCC employment screening guidelines; material policy shifts would require re-modeling. Model boundaries exclude macroeconomic recession scenarios exceeding labor market contraction thresholds observed in prior cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Business Intelligence (BI) Market
Analytics
Attribution Software Market
Analytics
North America Crowd Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Contact Center Analytics Market
Analytics
North America HR Analytics Market
Analytics
Complex Event Processing Market
Analytics
Global Data Visualization Tools Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Retail Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Process Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Global Analytics Software Market