
 India Big Data Technology and Service Market | 2026-2036
India Big Data Technology and Service Market Size, Share, and Industry Trends Forecast 2026-2036
India Big Data Technology and Service Market Foresight
Cloud-native data architecture is fragmenting traditional on-premises Hadoop deployments into distributed, microservices-based pipelines. TCS leverages its domestic delivery network to anchor large-scale data integration mandates for Indian banks and insurers. Fractal Analytics differentiates through AI-augmented analytics layers built atop Hadoop and Spark ecosystems. Tiger Analytics competes on specialized retail and CPG-focused predictive modeling for domestic conglomerates.
India Big Data Technology and Service encompasses the engineering, deployment, and management of distributed data platforms processing petabyte-scale structured and unstructured information through frameworks like Hadoop, Spark, and cloud-native warehouses with sub-second query latency targets. Its primary commercial purpose is enabling real-time decision intelligence across transactional, operational, and external data sources. Hadoop and data integration solutions sustain the largest revenue pools as enterprises modernize legacy data lakes, while cloud deployment and managed services represent the fastest-expanding margin corridors as CapEx-averse mid-market buyers shift to consumption-based pricing. Consulting and implementation services capture disproportionate value in early-stage digital transformation programs across banking and telecom verticals.
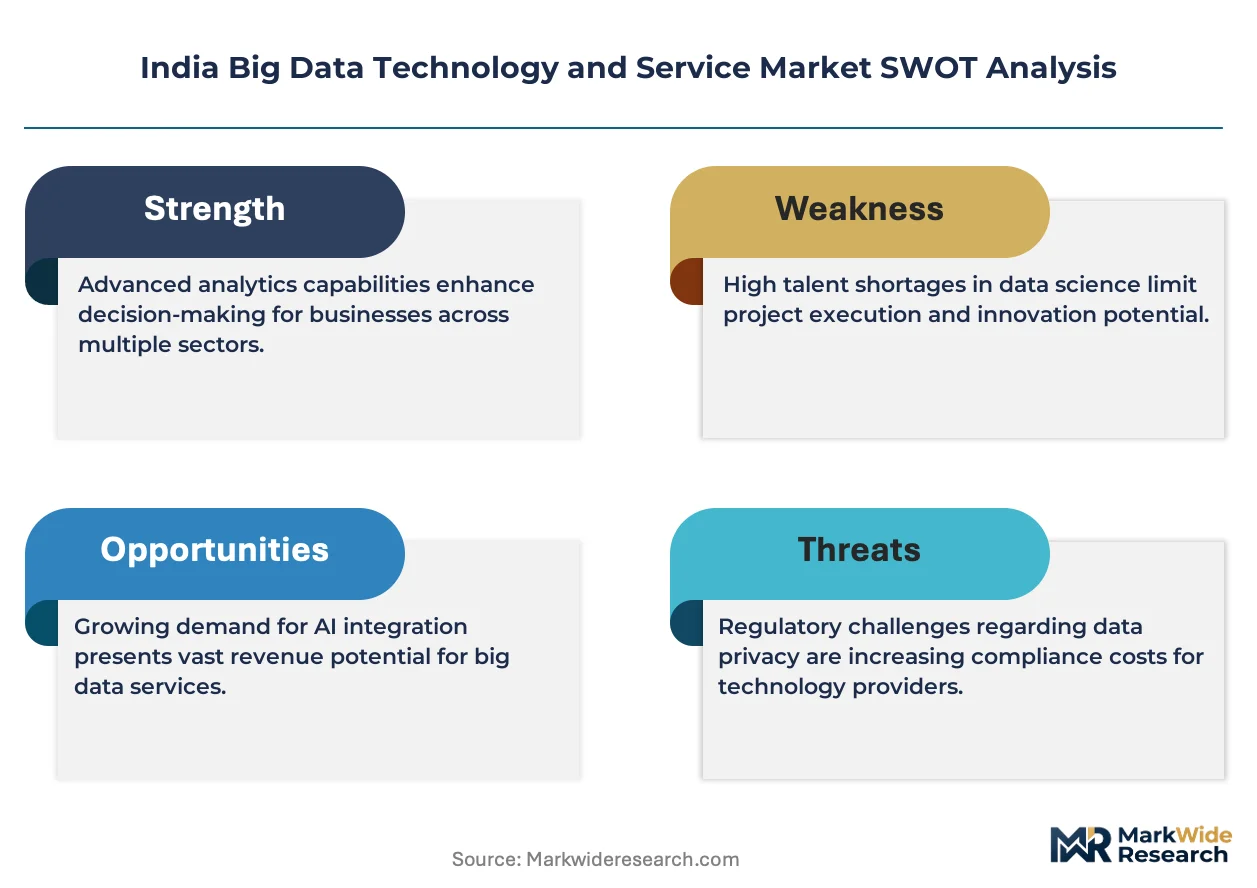
BIS data governance guidelines, the Digital Personal Data Protection Act, and RBI's cybersecurity frameworks for regulated entities collectively tighten compliance requirements for cross-border data flows and localized storage architectures. These standards compel vendors to engineer India-specific deployment configurations, accelerating hybrid and on-premises demand relative to pure public cloud. Stakeholders must weigh the trade-off between cloud scalability and sovereign data residency as regulatory granularity intensifies across state-level IT policies.
Market Dynamics
Cloud-native data architecture is collapsing traditional Hadoop-centric deployments into microservices-based pipelines across Indian enterprises. The Digital Personal Data Protection Act compels vendors to engineer localized storage configurations, reshaping procurement priorities for BFSI and telecom buyers in Mumbai, Bengaluru, and Hyderabad.
Growth Catalysts
- Digital Personal Data Protection Act:Mandates localized data residency for sensitive categories, accelerating hybrid cloud infrastructure investments among regulated entities.
- Real-time analytics demand in BFSI:Mumbai-based banks and insurers require sub-second query latency for fraud detection and customer personalization workloads.
- Spark ecosystem maturation:In-memory processing capabilities enable streaming analytics pipelines that Hadoop batch jobs cannot match, driving platform modernization cycles.
Market Restraints
- Specialized talent scarcity:Shortage of certified Hadoop administrators and cloud data engineers in Tier-2 cities limits enterprise scaling beyond Mumbai and Bengaluru.
- Cross-border data friction:RBI's cybersecurity frameworks for regulated entities impose strict approval requirements for offshore analytics processing, complicating multi-cloud strategies.
- Legacy integration burden:Mainframe data warehouses in established banks require expensive middleware layers to connect with modern data lakes.
Strategic Opportunities
- Telangana and Tamil Nadu expansion:Hyderabad and Chennai enterprise clusters show underpenetrated mid-market demand for managed analytics services.
- AI-augmented analytics convergence:Integration of machine learning pipelines with Spark streaming creates differentiated service offerings for retail and CPG conglomerates.
- PLI scheme for IT hardware:Domestic server manufacturing incentives reduce CapEx barriers for on-premises data lake deployments in compliance-sensitive sectors.
Industry Challenges
- Multi-framework skill gaps:Engineers proficient across Hadoop, Spark, and cloud-native warehouses command premium compensation, inflating project delivery costs.
- Compliance certification timelines:BIS data governance guidelines require lengthy audit cycles that delay production deployments for new analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Big Data Technology and Service Market |
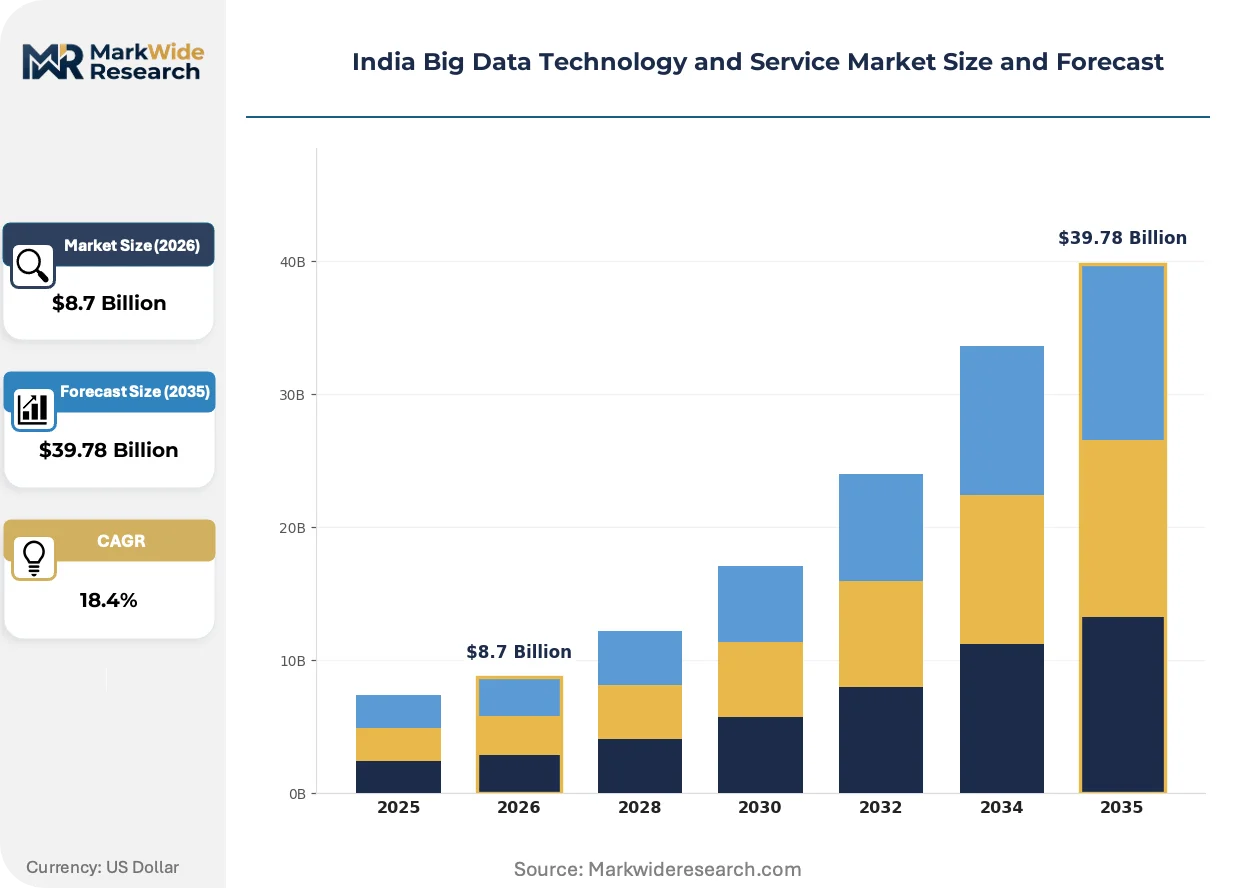
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Integration, Data Mining, Data Visualization, Hadoop Deployment: Cloud, On-Premises, Hybrid, Managed End User: Healthcare, Retail, Finance, Manufacturing Service Type: Consulting, Support, Implementation, Training |
| Companies Covered | TCS, Infosys, Wipro, Accenture, Mu Sigma, Fractal Analytics, Tiger Analytics, BRIDGEi2i, Ksolves India Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Big Data Technology and Service Market Shifts & Advancements
Real-time decision intelligence is displacing retrospective reporting as the primary value proposition for Indian enterprise data investments. Vendors are engineering specialized configurations to address sovereign data requirements while maintaining cloud scalability.
Apache Iceberg and Delta Lake table formats are collapsing proprietary data warehouse silos into open, interoperable lakehouse architectures. Large Indian conglomerates in retail and manufacturing are piloting these formats for unified batch and streaming analytics. The shift is collapsing vendor lock-in premiums and compressing migration timelines from legacy Teradata and Oracle installations.
BIS data governance guidelines, issued under the broader Digital India framework, mandate standardized metadata management and audit trail protocols for organizations above defined revenue thresholds. Financial services and healthcare providers face the steepest compliance curves, with RBI-regulated entities required to demonstrate localized encryption key management. Vendors are responding with India-specific deployment blueprints that pre-configure these controls.
Consumption-based pricing models are displacing perpetual license structures for mid-market buyers in Maharashtra and Karnataka. Managed service providers now offer pay-per-query arrangements for cloud data warehouses, transferring infrastructure risk from enterprise IT budgets. This shift is most visible among Series B and C technology startups in Bengaluru seeking to preserve cash runway while scaling analytics capabilities.
India Big Data Technology and Service Market Segmentation
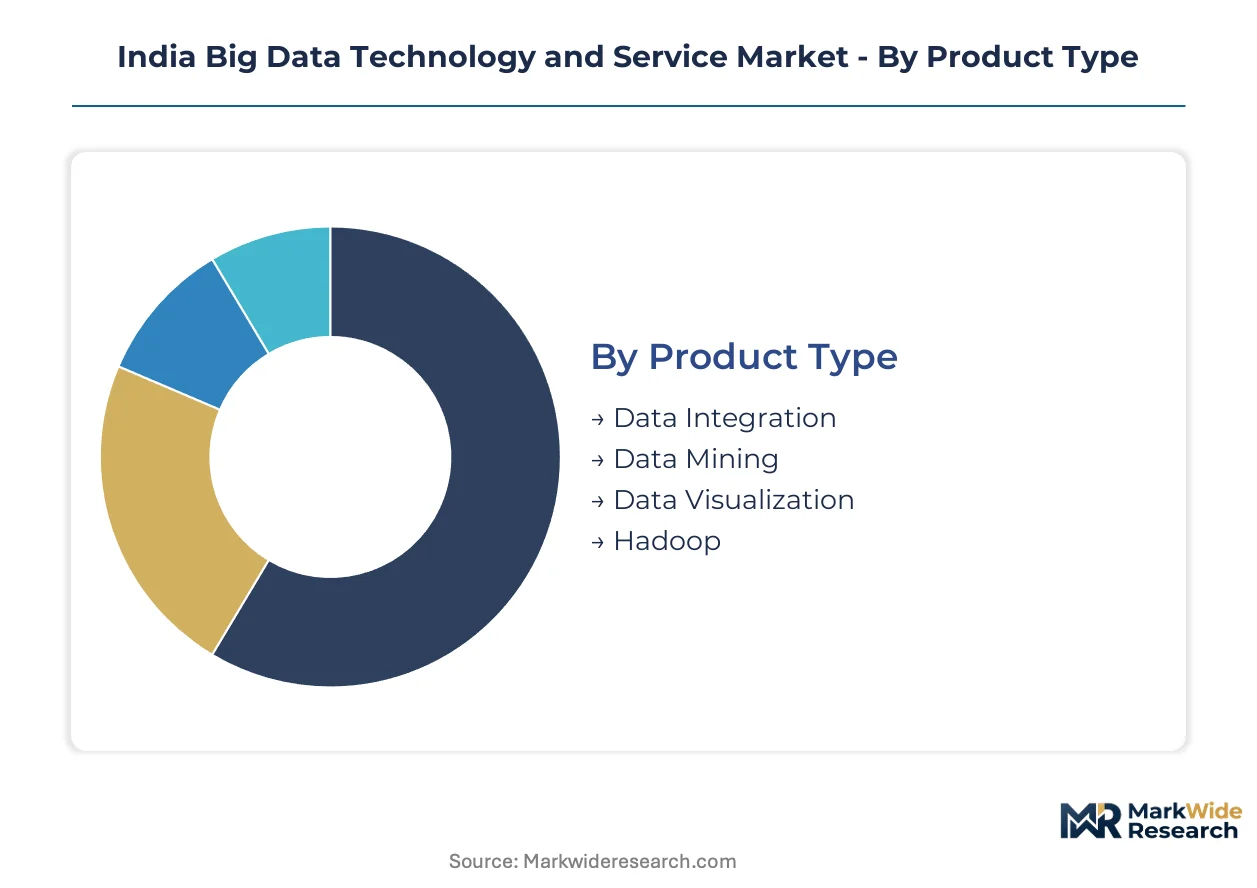
Segmentation in India's big data market reveals how technology maturity, deployment economics, and regulatory pressure reshape procurement patterns across BFSI, healthcare, and retail verticals. Understanding these divides exposes where margin pools concentrate and where vendor positioning must adapt.
Product Type:
Mature batch-processing platforms coexist with emerging real-time analytics layers, creating a bifurcated technology adoption curve across Indian enterprises.
- Data Integration:Middleware platforms harmonize disparate ERP, CRM, and legacy mainframe sources through ETL pipelines and API orchestration. Maharashtra and Karnataka banks drive demand as they consolidate branch-level data silos into unified lakehouse architectures under RBI data localization mandates.
- Hadoop:Distributed storage and batch processing frameworks handle petabyte-scale unstructured workloads across on-premises clusters. Telangana manufacturing conglomerates and Tamil Nadu automotive suppliers anchor deployment volumes, though cloud-native alternatives are compressing growth trajectories in new installations.
- Data Mining:Pattern recognition algorithms extract predictive signals from transactional and behavioral datasets.
- Data Visualization:Self-service BI dashboards democratize analytics access for non-technical business users.
Hadoop handles the majority of throughput; Data Integration is the fastest mover on share.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from consumption-priced cloud alternatives, with compliance requirements forcing a middle path.
- Cloud:Elastic compute and storage resources scale on demand without infrastructure ownership. Bengaluru SaaS startups and Mumbai fintechs dominate adoption, driven by cash preservation needs and the absence of legacy data center investments.
- Hybrid:Split architectures keep sensitive data on-premises while bursting analytics workloads to public cloud. BFSI entities in Mumbai and Hyderabad prioritize this model to satisfy RBI cybersecurity frameworks while retaining elasticity for non-regulated datasets.
- On-Premises:Dedicated hardware installations serve compliance-sensitive sectors with strict data residency requirements.
- Managed:Third-party operated platforms transfer operational burden to specialized service providers.
Cloud captures the largest addressable base; Hybrid is climbing the fastest as regulated entities navigate the sovereignty-scalability trade-off.
End User:
Application intensity varies sharply, with transaction-heavy sectors generating disproportionate data volumes and analytics sophistication.
- Finance:Real-time fraud detection, algorithmic trading, and customer personalization engines process sub-second latency workloads. Mumbai-based banks and insurers anchor this segment, with RBI-mandated cybersecurity frameworks accelerating platform modernization cycles.
- Healthcare:Electronic health record integration, clinical trial analytics, and population health management drive demand. Telangana and Karnataka hospital networks invest heavily as CDSCO and Digital Personal Data Protection Act requirements tighten patient data governance.
- Retail:Supply chain optimization and customer segmentation analytics support inventory and marketing decisions.
- Manufacturing:Predictive maintenance and quality control applications leverage IoT sensor streams.
Finance commands the deepest analytics investment; Healthcare is expanding most quickly as provider digitization accelerates.
Service Type:
Customer type segmentation separates advisory-led transformation engagements from operational support and capability-building programs.
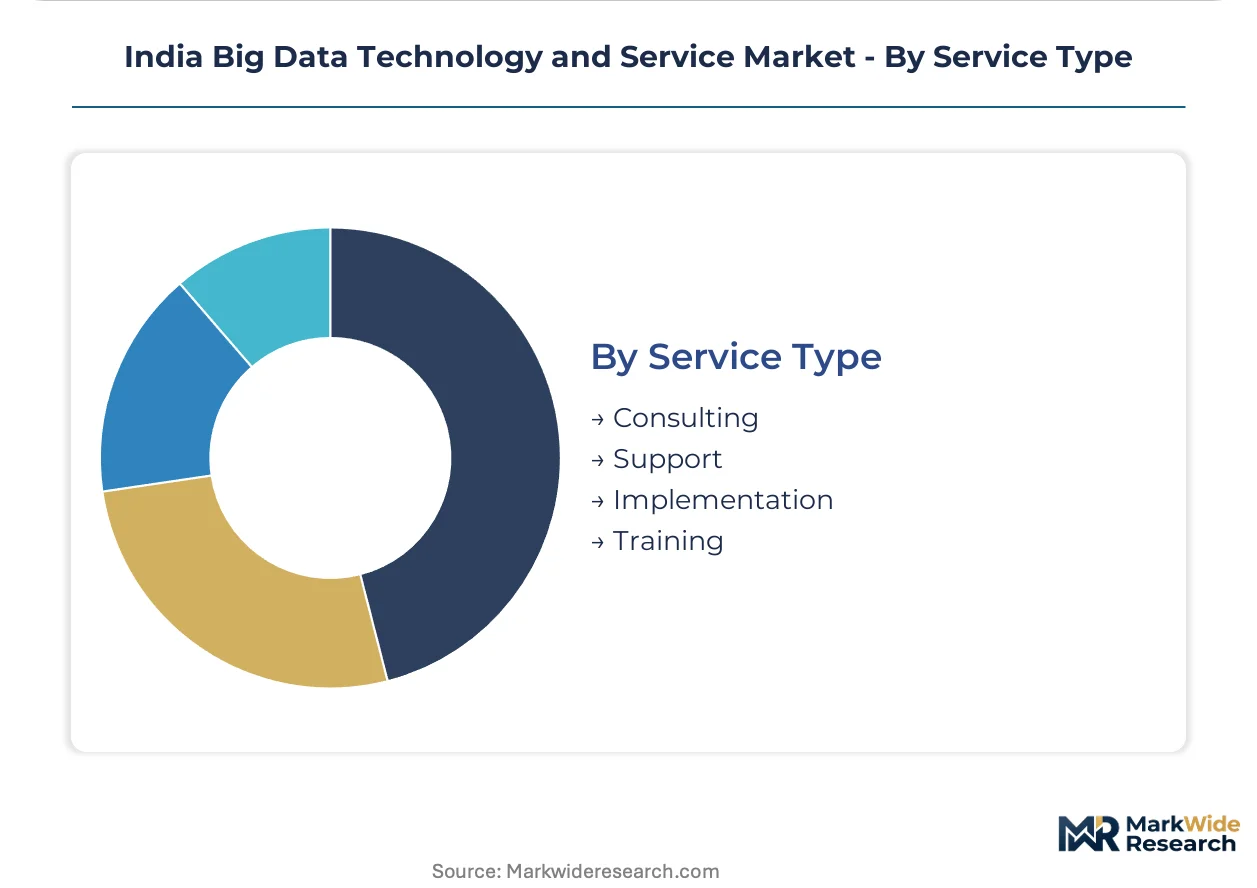
- Consulting:Strategic advisory services define data architecture roadmaps, governance frameworks, and platform selection criteria. Large domestic conglomerates in Maharashtra and Karnataka initiate these engagements to align analytics investments with board-level digital transformation mandates.
- Implementation:Deployment and integration services migrate legacy systems to modern data platforms. Mid-market enterprises across Tamil Nadu and Telangana drive volume as they bypass extended consulting phases for faster time-to-value.
- Support:Ongoing maintenance, troubleshooting, and platform optimization services.
- Training:Capability-building programs address the certified Hadoop administrator and cloud data engineer shortage.
Consulting captures the highest value per engagement; Implementation is gaining share fastest as deployment velocity prioritizes over strategic planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services enterprises in Mumbai and Bengaluru drive the bulk of procurement decisions, with mid-market technology firms in Hyderabad and Chennai emerging as the fastest-expanding buyer segment.
Maharashtra
Mumbai-based banks and insurers anchor demand for real-time fraud detection and customer personalization engines. RBI cybersecurity frameworks for regulated entities mandate localized encryption key management, compelling hybrid cloud investments. The Mumbai-Pune corridor concentrates implementation service providers serving BFSI modernization cycles.
Karnataka
Bengaluru's SaaS startups and fintechs prioritize consumption-based pricing for cloud data warehouses to preserve cash runway. The state's PLI scheme for IT hardware reduces CapEx barriers for on-premises deployments in compliance-sensitive sectors. Whitefield and Electronic City clusters house specialized Spark and Hadoop engineering talent pools.
Telangana
Hyderabad enterprise clusters show underpenetrated mid-market demand for managed analytics services across retail and pharmaceutical verticals. CDSCO requirements tighten patient data governance for healthcare providers investing in electronic health record integration. Genome Valley and HITEC City sub-regions attract data integration specialists targeting life sciences digitization.
Tamil Nadu
Chennai automotive suppliers and manufacturing conglomerates pilot Apache Iceberg and Delta Lake formats for unified batch and streaming analytics. BIS data governance guidelines mandate standardized metadata management for organizations above defined revenue thresholds. The Sriperumbudur-Oragadam industrial belt drives predictive maintenance applications leveraging IoT sensor streams.
India Big Data Technology and Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The vendor base clusters around large IT services conglomerates, mid-tier analytics boutiques, and emerging cloud-native specialists. Strategic archetypes include domestic delivery network operators, AI-augmented analytics layer builders, and vertical-specific predictive modelers. Competitive moves concentrate on geographic expansion into underpenetrated state clusters and portfolio diversification through managed service offerings.
Within the domestic delivery network tier, TCS anchors large-scale data integration mandates for Indian banks and insurers. Fractal Analytics and Tiger Analytics exemplify the AI-augmented specialization archetype, with the former building analytics layers atop distributed processing ecosystems and the latter competing on retail and CPG-focused predictive modeling for domestic conglomerates. These three occupy positions that reflect the market's bifurcation between scale-driven implementation and differentiated algorithmic capabilities.
| Leading Market Players |
|---|
| TCS |
| Infosys |
| Wipro |
| Accenture |
| Mu Sigma |
| Fractal Analytics |
| Tiger Analytics |
| BRIDGEi2i |
| Ksolves India Ltd |
| Others |
Supply & Pricing Matrix
Bengaluru's Whitefield and Electronic City clusters concentrate certified Hadoop administrators and cloud data engineers, creating localized talent scarcity that inflates project delivery costs for Tier-2 city deployments. This supply concentration grants established service providers pricing power over mid-market buyers while forcing cost compression through consumption-based models among cash-constrained SaaS startups.
Pricing Analysis
Cost-plus contracts with personnel cost indexation dominate implementation engagements, particularly for banks navigating RBI cybersecurity framework mandates. Three-tier pricing structure across premium, standard, and economy levels separates full-stack consulting from modular integration and self-service training tiers. Price differentiation hinges on certification density and vertical specialization depth. Pricing pressure stems from open-source Spark and Iceberg alternatives collapsing proprietary vendor lock-in premiums. Mid-market retail and pharmaceutical buyers in Telangana exhibit acute price sensitivity, while Mumbai BFSI entities prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become standard for managed analytics services targeting Series B and C technology startups. Engineering talent draws from India, the United States, and Singapore for specialized cloud-native architecture roles. Hardware dependencies center on domestic server manufacturing incentivized under the PLI scheme, imported GPU clusters, and licensed enterprise software stacks. Single-source vulnerability concentrates in certified data engineer pools across Mumbai and Bengaluru. Distribution runs through direct enterprise sales teams, hyperscaler marketplace listings, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native lakehouse architectures that collapse traditional Hadoop deployment timelines and compress migration service margins.
For Market Incumbents: Entrench hybrid cloud capabilities to defend against pure-play cloud-native specialists. Build captive training academies addressing multi-framework skill gaps in Tier-2 cities. Deepen vertical integration into managed services to capture recurring revenue streams as project-based consulting commoditizes. For New Entrants and Emerging Players: Pursue underpenetrated mid-market demand across Hyderabad and Chennai enterprise clusters. Target pharmaceutical and automotive verticals with AI-augmented analytics layers built atop open Iceberg and Delta Lake formats. Establish go-to-market presence through hyperscaler marketplace listings to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analytics boutiques with demonstrated Spark streaming expertise and healthcare compliance credentials. Long-term viability rests on capabilities spanning batch and real-time workloads as lakehouse architectures mature. Monitor CDSCO and RBI regulatory enforcement intensity as inflection indicators for compliance-sensitive sector demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Certification Investment | RBI-mandated localized encryption key management drives hybrid infrastructure procurement among Mumbai banks. |
| Academic Partnership for Talent Pipeline | Collaborations with Karnataka and Telangana engineering institutes address certified administrator scarcity. |
| Open Lakehouse Platform Integration | Apache Iceberg and Delta Lake adoption collapses proprietary vendor lock-in and accelerates migration timelines. |
| Vertical-Specific AI Layer Development | Retail and CPG-focused predictive modeling differentiates service offerings for domestic conglomerates. |
| Geographic Expansion to Tier-2 Clusters | Chennai and Hyderabad manufacturing hubs present underpenetrated demand for managed analytics services. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Maharashtra, Karnataka, and Telangana; and secondary validation through RBI cybersecurity circulars, BIS data governance guidelines, SEC filings of listed IT services firms, hyperscaler capex disclosures, and CDSCO regulatory updates. Bottom-up project pipeline analysis triangulated against top-down addressable market sizing from enterprise IT spend surveys.
Forecast inputs considered deployment model transitions, organization size tiering, vertical application intensity, integration complexity gradients, and regional regulatory adoption patterns across the analysis window. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Modeled variables included cloud migration velocity among mid-market buyers, PLI scheme impact on on-premises hardware economics, and Spark ecosystem maturation effects on Hadoop replacement cycles.
The forecast holds incumbent behavior within observed patterns; aggressive capability investments by global hyperscalers or abrupt regulatory enforcement shifts would shift outcomes. Macroeconomic credit tightening affecting Series B and C startup runway, unexpected Digital Personal Data Protection Act amendment timelines, or breakthrough quantum encryption commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Discovery Market
Analytics
TV Analytics Solutions Market
Analytics
Patent Analytics Market
Analytics
India Big Data Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Global in-Store Analytics Market
Analytics
Global Marketing Attribution Software Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Process Analytics Market
Analytics
Load (ETL) Market
Analytics
APAC Data Wrangling Market
Analytics
Speech and Voice Analytics Market
Analytics
Data Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Legal Analytics Market
Analytics
Customer Data Platform Market