
 North America AUV and ROV Market | 2026-2036
North America AUV and ROV Market Size, Share, and Industry Trends Forecast 2026-2036
North America AUV and ROV Market Analytics
Aftermarket service revenue is narrowing toward OEM-captive channels as original equipment manufacturers tighten control over proprietary software diagnostics and component calibration protocols. Fugro NV leverages its integrated survey and asset integrity divisions to bundle ROV deployment with data analytics subscriptions. Kongsberg Gruppen anchors its North American position through underwater navigation and acoustic positioning systems that command premium placement on third-party vehicle platforms. Oceaneering International Inc. dominates the Gulf of Mexico service layer with resident ROV systems permanently installed on subsea production hardware.
Autonomous underwater vehicles and remotely operated vehicles are self-propelled or tethered subsea craft operating at depths from shallow coastal zones to full ocean trenches, typically rated for pressures exceeding 600 bar and equipped with multibeam sonar, HD cameras, and manipulator arms for intervention tasks. Their primary commercial purpose centers on subsea infrastructure inspection, seabed mapping, and intervention work in environments that exceed human diver safety limits. ROV systems lead the product type category by installed base and recurring service attach rates, while AUV segments attract disproportionate R&D allocation for long-duration autonomous missions. The defense end user channel sustains above-average margins through classified program specifications and security-cleared maintenance requirements.
The US Bureau of Ocean Energy Management enforces platform inspection intervals that mandate ROV-based visual and ultrasonic testing of subsea wellheads and flowlines, directly shaping fleet utilization rates for Gulf of Mexico operators. The US Coast Guard and Transport Canada both classify certain AUV operations under maritime collision regulations, creating compliance thresholds for navigation lighting, acoustic pingers, and surface communications that add cost but also raise barriers for unqualified entrants. Stakeholders must monitor how evolving cybersecurity standards for autonomous maritime systems reshape software architecture requirements and vendor qualification protocols.
Market Dynamics
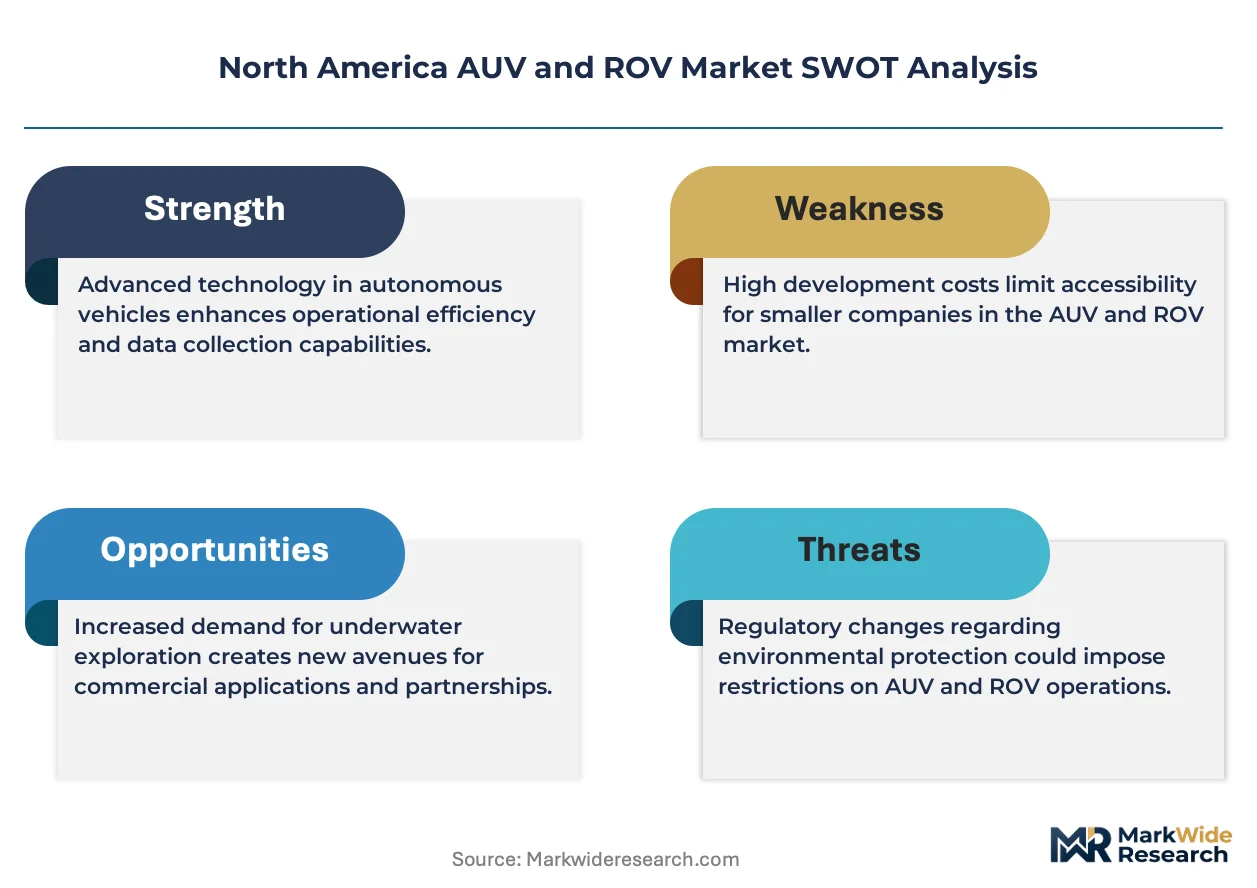
The US Bureau of Ocean Energy Management's updated decommissioning rules are compressing ROV fleet replacement cycles across Gulf of Mexico operators, forcing capital allocation toward inspection-grade systems with resident capabilities.
Growth Catalysts
- Subsea infrastructure aging:Mature offshore platforms across the Gulf of Mexico require continuous ROV-based visual and ultrasonic testing of wellheads and flowlines under mandated inspection intervals.
- Deepwater exploration resurgence:Ultra-deepwater drilling campaigns in US and Mexican territorial waters demand AUVs rated for pressures exceeding 600 bar with extended mission endurance.
- Defense classification requirements:Security-cleared maintenance protocols for classified programs sustain above-average margins and create captive service relationships.
Market Restraints
- Proprietary software lock-in:OEM-captive diagnostic channels restrict third-party service access, inflating lifecycle maintenance costs for operators without manufacturer relationships.
- High-grade titanium supply concentration:Pressure-hull material sourcing concentrates among specialty metallurgical suppliers, exposing vehicle manufacturers to input cost volatility.
- Acoustic positioning technical ceiling:Long-baseline navigation accuracy degrades in complex seabed topography, limiting AUV mission planning in certain Gulf of Mexico canyon systems.
Strategic Opportunities
- Canadian Arctic underpenetration:Ice-covered waters off Newfoundland and Labrador remain underserved by inspection-class AUVs despite expanding subsea cable and pipeline installations.
- Resident ROV-as-a-service models:Permanent installation on subsea production hardware shifts revenue from episodic deployment to recurring subscription structures.
- Maritime cybersecurity standards:Evolving autonomous system protection protocols create qualification barriers that favor established vendors with hardened software architectures.
Industry Challenges
- Subsea robotics technician scarcity:Deepwater ROV piloting and AUV mission planning require specialized training pipelines that North American institutions have not scaled to match fleet expansion.
- ISO 13628-8 certification timelines:Subsea production control system integration testing extends vehicle qualification periods, delaying revenue recognition for new platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America AUV and ROV Market |
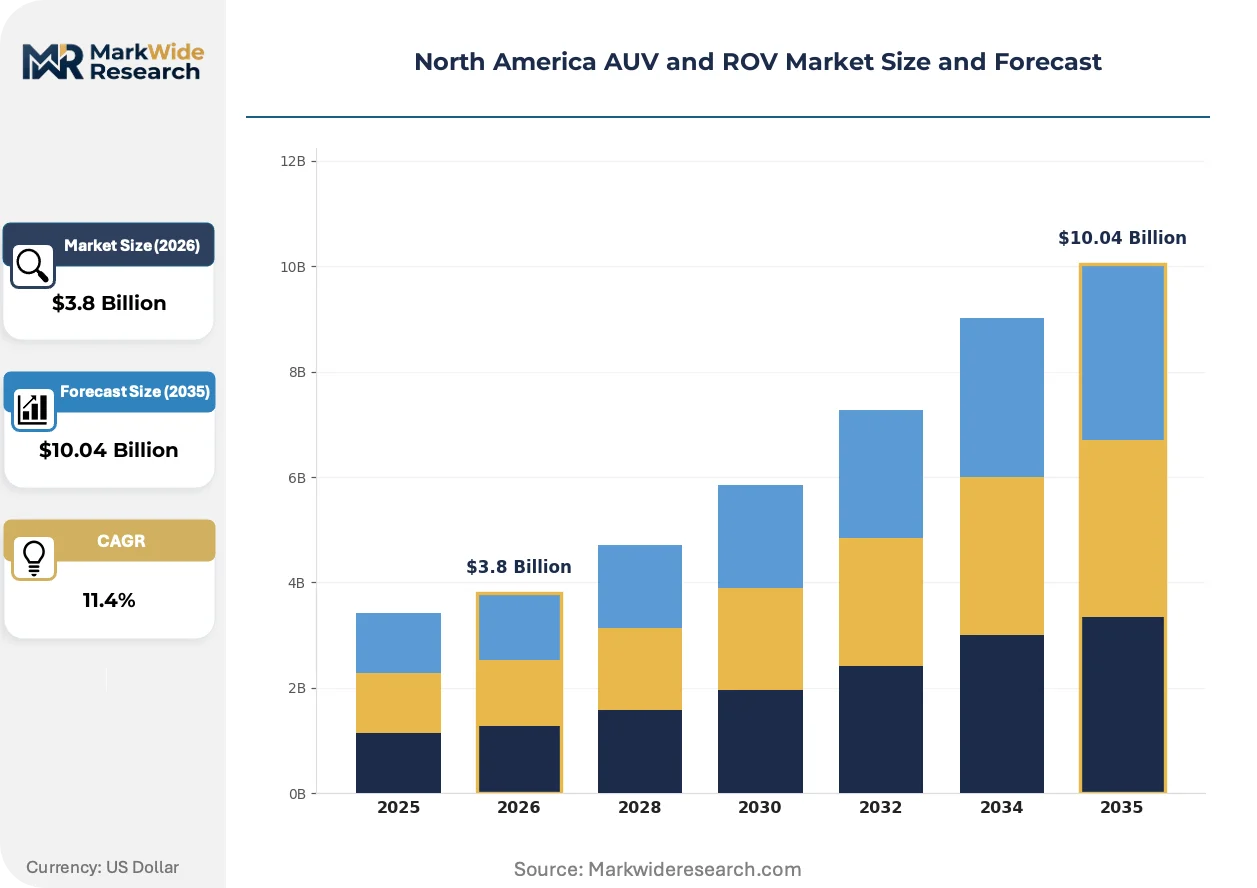
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Hybrid Systems, USV End User: Defense, Oil & Gas, Scientific Research, Marine Tourism Application: Inspection, Exploration, Surveying, Data Collection Technology: Electric, Hydraulic, Mechanical, Autonomous |
| Companies Covered | Fugro NV, TechnipFMC PLC, Subsea 7 SA, Oceaneering International Inc., Kongsberg Gruppen, Teledyne Marine, Helix Energy Solutions Group, Forum Energy Technologies Inc., General Dynamics Mission Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America AUV and ROV Market Evolving Landscape
Autonomous underwater vehicle architectures are hybridizing with resident ROV capabilities, blurring product category boundaries and reshaping how operators contract for subsea intervention services.
Resident vehicle systems are hybridizing tethered intervention reliability with autonomous transit endurance, enabling continuous subsea presence without surface vessel support. Offshore production operators in the Gulf of Mexico are adopting these configurations for wellhead monitoring, compressing the traditional spot-inspection model into always-on asset integrity coverage. This convergence is displacing episodic ROV charter contracts with permanent hardware installations backed by data analytics subscriptions.
The US Coast Guard's application of maritime collision regulations to certain AUV operations mandates navigation lighting, acoustic pingers, and surface communications that add hardware cost but raise competitive barriers. Vehicle operators must now certify compliance thresholds previously reserved for surface vessels, altering procurement specifications for shallow-water survey missions. Gulf of Mexico service providers are responding by integrating these systems into standard platform configurations, passing compliance overhead through to charter rates.
Aftermarket service unbundling is compressing as OEMs tighten control over proprietary diagnostics and component calibration protocols. Independent service providers face exclusion from software-dependent maintenance, forcing Gulf of Mexico operators into captive relationships with original equipment manufacturers. This channel consolidation is most visible in the resident ROV segment, where permanent installation creates long-term dependency on manufacturer-specified spare parts and firmware updates.
North America AUV and ROV Market Segmentation
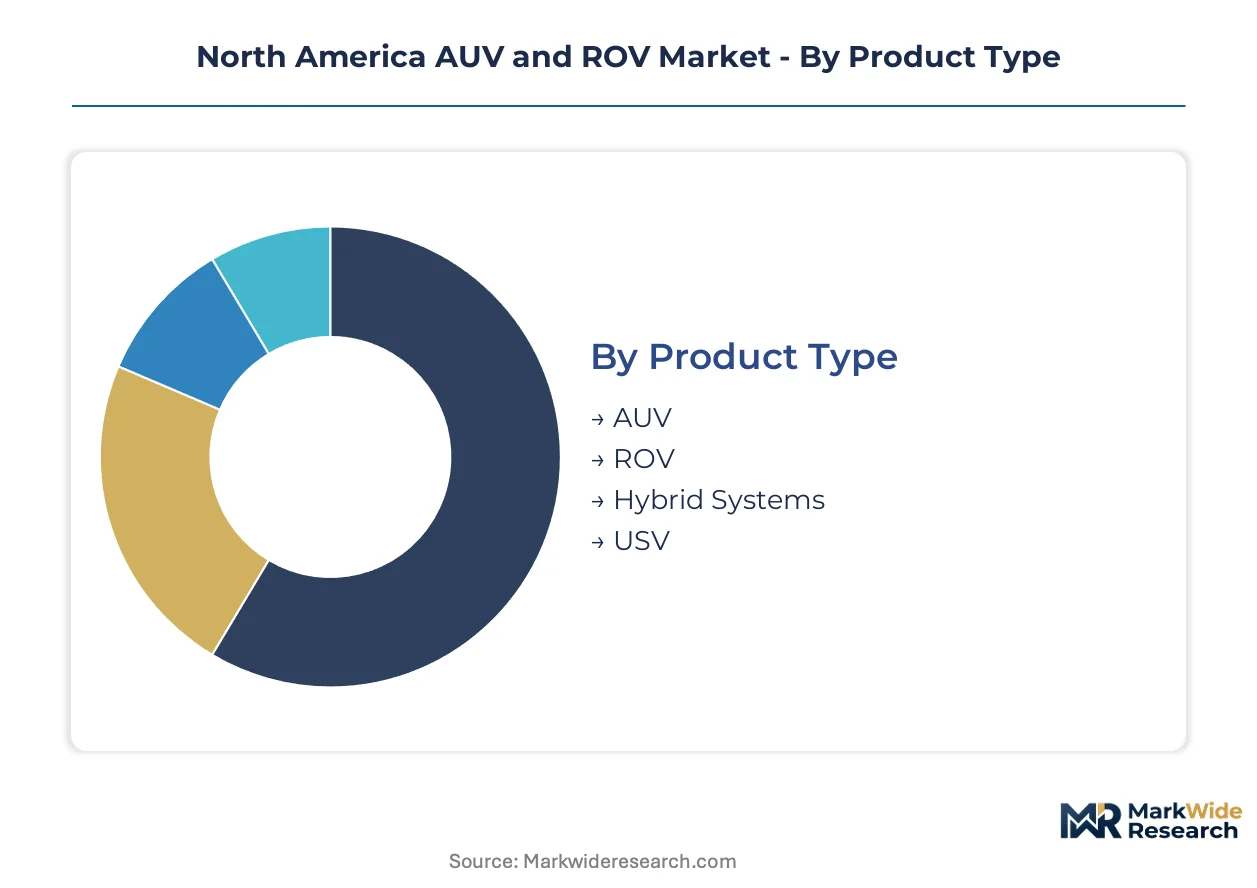
Segmentation in the North America AUV and ROV market reveals how capital deployment cycles differ dramatically across product architectures and end-use channels. Understanding these structural variations helps operators align fleet procurement with mission duration requirements and regulatory compliance obligations.
Product Type:
Replacement cycles stretch from 3-5 years for inspection-grade ROVs to 8-12 years for deep-rated AUV pressure hulls, creating distinct revenue recognition patterns for manufacturers and service providers.
- AUV:Self-propelled battery-powered vehicles operate without surface tether, carrying multibeam sonar and synthetic aperture radar for autonomous seabed mapping missions. Gulf of Mexico operators deploy these for pipeline route surveys where vessel day rates exceed intervention costs, though acoustic positioning limitations constrain canyon operations.
- ROV:Tethered systems with real-time pilot control dominate subsea intervention through hydraulic manipulators and high-definition video feeds. The US Bureau of Ocean Energy Management mandates ROV-based wellhead inspections at fixed intervals, cementing resident system installations on production hardware across the Gulf of Mexico.
- Hybrid Systems:Combines autonomous transit with tethered intervention modes for extended subsea presence.
- USV:Surface-deployed craft supporting AUV launch and recovery operations in coastal survey missions.
ROV dominates installed base. AUV is where expansion concentrates.
End User:
Defense procurement operates on classified program timelines with security-cleared maintenance requirements, while commercial oil and gas contracts track spot energy prices and decommissioning rule changes.
- Defense:Naval mine countermeasures and submarine rescue programs specify hardened communication protocols and encrypted data handling. Security-cleared technician requirements sustain above-average service margins and create multi-year sole-source relationships with vehicle manufacturers.
- Oil & Gas:Offshore operators in US and Mexican territorial waters deploy inspection-class systems for subsea infrastructure integrity management. Updated decommissioning rules from the US Bureau of Ocean Energy Management are compressing fleet replacement cycles and accelerating resident ROV adoption.
- Scientific Research:Academic institutions and oceanographic institutes operate shallow-rated vehicles for benthic ecology and climate monitoring studies.
- Marine Tourism:Submersible operators serve deep-sea sightseeing and wreck exploration markets with pressure-rated passenger capsules.
Oil & Gas commands the largest fleet deployment. Defense offers the steepest expansion trajectory.
Application:
Mission type determines sensor payload configuration and whether continuous surface communication is required for operational success.
- Inspection:Visual and ultrasonic testing of subsea wellheads, flowlines, and platform structures under regulatory mandate. Gulf of Mexico operators face compressed inspection intervals for aging infrastructure, driving demand for resident systems with always-on monitoring capabilities.
- Exploration:Geophysical and geotechnical surveys for frontier drilling prospects in ultra-deepwater zones. Mexican territorial waters and US Gulf lease blocks require AUVs rated for pressures exceeding 600 bar with extended mission endurance.
- Surveying:Seabed mapping for cable route planning and pipeline installation engineering.
- Data Collection:Long-duration oceanographic monitoring with sensor packages for temperature, salinity, and current profiling.
Inspection absorbs the majority of operating hours. Exploration is gaining share fastest.
Technology:
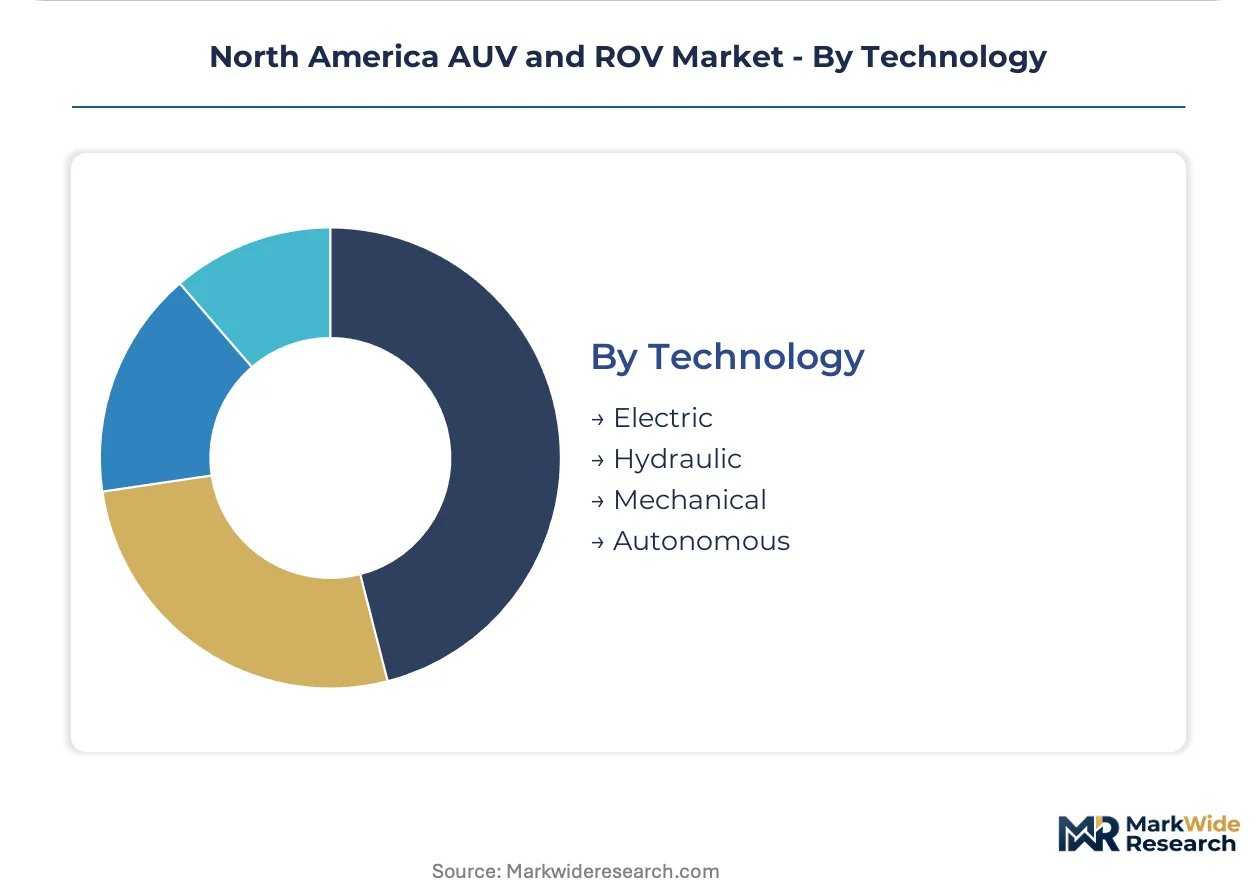
Power and control architectures segment by energy density requirements and the trade-off between tether reliability versus operational independence.
- Electric:Battery-powered propulsion and actuation systems deliver precise station-keeping for inspection tasks. Gulf of Mexico resident ROVs rely on electric thrusters for low-maintenance continuous operation on subsea production hardware.
- Hydraulic:High-force manipulator and heavy-lift functions for subsea construction and intervention work. Deepwater drilling contractors in US territorial waters specify hydraulic work-class systems for blowout preventer testing and wellhead maintenance.
- Mechanical:Direct-drive linkages for simplified maintenance in shallow-water survey applications.
- Autonomous:Artificial intelligence-driven navigation and decision-making for untethered long-duration missions.
Electric leads in unit volume. Autonomous is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian operators demonstrate the highest price elasticity as Arctic ice-class requirements inflate procurement budgets without corresponding utilization guarantees. US Gulf of Mexico buyers absorb premium pricing for resident systems given regulatory-mandated inspection intervals. Mexican territorial waters sit between these poles, with Pemex-led demand favoring mid-tier work-class ROVs over autonomous platforms.
United States
Deepwater exploration resurgence in the Gulf of Mexico drives replacement cycles for aging ROV fleets as operators confront the US Bureau of Ocean Energy Management's compressed decommissioning timelines. The Coast Guard's maritime collision regulations for AUV operations mandate navigation lighting and acoustic pingers, adding hardware costs that filter through to charter rates. Houston anchors the continental service infrastructure, with resident ROV systems permanently installed across subsea production hardware throughout the Gulf's ultra-deepwater lease blocks.
Canada
Ice-covered waters off Newfoundland and Labrador remain underserved by inspection-class AUVs despite expanding subsea cable and pipeline installations. Transport Canada classifies certain autonomous operations under maritime collision regulations, creating compliance thresholds that favor established vendors with hardened software architectures. St. John's concentrates Atlantic Canada's offshore oil services sector, where operators face extended certification timelines for subsea production control system integration.
Mexico
Pemex-led offshore campaigns in Mexican territorial waters demand work-class ROVs for wellhead maintenance and blowout preventer testing in ultra-deepwater zones. The country's national petroleum regulator enforces platform inspection intervals that mirror US standards, cementing tethered system deployment over autonomous alternatives. Ciudad del Carmen serves as the primary logistics hub for Gulf of Mexico operations, with service providers staging intervention equipment for cross-border campaigns.
North America AUV and ROV Market Competitive Landscape
Capability concentration sits with integrated survey-to-analytics providers; scale advantage sits with diversified industrial conglomerates with captive metallurgical supply chains. The vendor base organizes around three strategic archetypes: resident system specialists with permanent subsea hardware installations, full-service survey houses bundling vehicle deployment with data subscriptions, and defense-primed contractors with security-cleared maintenance protocols. Dominant competitive moves include backward integration into pressure-hull titanium sourcing and technology licensing partnerships for acoustic positioning systems.
Within the integrated survey tier, Fugro NV and Subsea 7 SA exemplify the bundled service model combining ROV deployment with long-term data analytics relationships. Oceaneering International Inc. anchors the resident system specialist position through permanent hardware installations on Gulf of Mexico production infrastructure. Kongsberg Gruppen occupies a premium placement role for underwater navigation and acoustic positioning systems that command integration onto third-party vehicle platforms.
| Leading Market Players |
|---|
| Fugro NV |
| TechnipFMC PLC |
| Subsea 7 SA |
| Oceaneering International Inc. |
| Kongsberg Gruppen |
| Teledyne Marine |
| Helix Energy Solutions Group |
| Forum Energy Technologies Inc. |
| General Dynamics Mission Systems |
| Others |
Value Network & Pricing Analysis
Undercapacity in high-grade titanium pressure-hull forging drives Gulf of Mexico operators toward multi-year resident ROV service contracts that bundle hardware deployment with proprietary software diagnostics, compressing third-party aftermarket access and inflating lifetime maintenance commitments.
Pricing Analysis
Aftermarket service revenue tiers—spanning firmware updates, component calibration protocols, and resident system monitoring subscriptions—now drive lifetime value capture beyond initial hardware placement. Three-tier pricing structure across premium navigation-grade, standard inspection-class, and economy survey-tier systems stratifies by acoustic positioning accuracy and pressure rating certification. Cost compression in the mid-tier inspection segment intensifies as OEMs tighten diagnostic channel control, forcing independent service providers toward marginal charter roles. Canadian Arctic operators demonstrate the steepest price sensitivity due to ice-class requirements without utilization guarantees, while US Gulf buyers absorb premiums for resident systems given Bureau of Ocean Energy Management-mandated inspection intervals.
Supply Chain Analysis
High-grade titanium feedstock for pressure hulls draws from specialty metallurgical suppliers concentrated in the United States, Japan, and Russia, with forging capacity anchored in aerospace-certified facilities. Battery cell production for extended-endurance AUV missions rests on South Korean and Chinese cathode material suppliers, while acoustic positioning transducers hinge on Norwegian and UK sensor fabrication. Single-source vulnerability in deep-rated pressure-window manufacturing exposes vehicle builders to 18-24 month qualification timelines for alternative forging sources. Distribution runs through OEM-direct channels for resident systems and specialized service contractors for episodic charter deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data analytics subscriptions attached to resident ROV hardware are expanding faster than autonomous vehicle unit sales, converting capital expenditure into recurring operational expenditure for Gulf of Mexico production operators.
For Market Incumbents: Insulate proprietary diagnostic channels by tightening firmware authentication protocols and calibrating component replacement schedules to resident system telemetry data, neutralizing independent service provider encroachment. Deepen backward integration into pressure-hull titanium sourcing through long-term offtake agreements with aerospace-certified forgers, securing input cost stability against commodity volatility. Prioritize certification investment in Transport Canada ice-class variants to preempt Arctic market entry by emerging competitors. For New Entrants and Emerging Players: Build out shallow-water survey capabilities targeting Mexican territorial waters, where Pemex-led demand favors mid-tier work-class ROVs over autonomous platforms and incumbent resident system penetration remains limited. Establish go-to-market partnerships with integrated survey houses for bundled data analytics offerings, avoiding direct hardware competition with OEM-captive service networks. Target the Canadian Arctic cable route survey segment, where ice-class AUV underpenetration creates white-space despite expanding subsea infrastructure installation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among resident system specialists with permanent subsea hardware installations and multi-year data subscription relationships, offering superior cash flow quality over episodic charter operators. Long-term viability over the 5-10 year horizon favors acquisition targets with security-cleared maintenance protocols for defense channel access and proprietary acoustic positioning intellectual property. Watch for inflection in maritime cybersecurity standard adoption, which would accelerate qualification barriers favoring established vendors with hardened software architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Resident ROV-as-a-Service Expansion | Converts episodic charter revenue into recurring subscriptions tied to subsea production hardware telemetry. |
| Backward Integration into Titanium Forging | Secures pressure-hull material supply chains against aerospace competition and metallurgical cost volatility. |
| Maritime Cybersecurity Certification | Aligns vehicle software architectures with Coast Guard autonomous system protection protocols. |
| Canadian Arctic Ice-Class Development | Addresses underpenetrated inspection demand off Newfoundland and Labrador with cold-rated AUV platforms. |
| Defense Channel Security Clearance Investment | Captures above-margin classified program maintenance through technician clearance infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ROV fleet managers at Gulf of Mexico production operators, AUV mission planners at survey contractors, subsea robotics technicians, and procurement leads at defense primes. Secondary validation drew from US Bureau of Ocean Energy Management decommissioning filings, Transport Canada maritime collision regulation notices, SEC 10-K disclosures from listed service providers, and customs records for pressure-hull titanium imports. Bottom-up unit deployment estimates were triangulated against top-down energy sector capital expenditure tracking.
Calibration against historical fleet replacement cycles and regulatory mandate timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include product architecture, end-user channel, application mission type, and powertrain technology, with cross-validation against pressure-rating certification tiers and acoustic positioning accuracy grades. CAGRs were derived from fitted growth curves adjusted for replacement cycle compression effects and defense procurement cycle phasing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated survey houses into resident system hardware manufacturing would shift outcomes substantially. Cross-checking against Bureau of Ocean Energy Management lease block decommissioning schedules and Pemex capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Humanoids Market