
 Certificates Market | 2026-2036
Certificates Market Size, Share, and Industry Trends Forecast 2026-2036
Certificates Market Intelligence
A shift from single-provider engagements to multi-source certification portfolios is recalibrating how large enterprises manage professional development and compliance. This trend impacts vendors like AWS, which leads in cloud infrastructure credentials. Google differentiates with its specialized certifications in data analytics and machine learning. Meanwhile, Microsoft sustains a broad user base through its long-standing enterprise software and Azure certifications, covering a wide spectrum of IT roles and functions.
Certificates are formal attestations issued by an authorized body, confirming that a product, service, individual, or system meets predefined requirements. This often involves verification against specific standards, such as ISO 9001 for quality management systems. The primary purpose is to provide independent validation, building trust and facilitating market access. The Information Technology and Pharmaceuticals industry verticals are major consumers of certification services. Within applications, Quality Assurance and Compliance Verification represent the largest segments by volume, while Environmental Certification is a rapidly expanding category.
Regulatory mandates are a primary structural driver for the market. The EU's CE marking and RoHS directive, for example, require specific product certifications for market entry, creating non-negotiable demand. Similarly, the US FCC imposes certification requirements on electronic devices to ensure they do not cause harmful interference. The core strategic decision for organizations now centers on balancing investment between globally recognized credentials for broad acceptance and niche certifications for specialized expertise.
Market Dynamics
The proliferation of non-negotiable regulatory mandates across distinct economic blocs represents the central structural driver. These rules, such as the EU's CE marking or the US FCC's requirements, create compulsory demand for specified product and system certifications, making market access contingent on compliance.
Growth Catalysts
- Sustainability Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) is compelling organizations to seek third-party verification for their environmental and social governance disclosures, creating a new category of certification demand.
- Digital Transformation:Pervasive cybersecurity threats and the shift to cloud infrastructure are driving intense demand from the Information Technology vertical for credentials verifying skills in data protection, cloud architecture, and threat mitigation.
- Quality Assurance:The United States' large manufacturing base continues to generate significant volume for quality management system certifications, such as ISO 9001, to ensure supply chain integrity and meet customer procurement requirements.
Market Restraints
- Cost of Compliance:The substantial financial investment and time required for obtaining and maintaining certifications, particularly in highly regulated sectors like pharmaceuticals and aerospace, can be a significant barrier for smaller enterprises.
- Regulatory Fragmentation:Divergent national or regional standards, such as differing requirements for electronic device safety in China versus Europe, create complexity and increase testing costs for companies operating across multiple jurisdictions.
- Credential Devaluation:The rise of non-accredited online courses and informal digital badges can, in some skill-based domains, present a low-cost alternative that dilutes the perceived value of more rigorous, formal professional certifications.
Strategic Opportunities
- AI Governance:Forthcoming regulations like the EU AI Act will create an entirely new market for the certification of artificial intelligence systems, focusing on ethics, bias, transparency, and risk management.
- Emerging Economies:Expanding certification infrastructure in Southeast Asian manufacturing hubs, including Vietnam and Indonesia, presents an opportunity as these nations increase exports to highly regulated Western markets.
- Digital Verification:The application of blockchain technology to create immutable and easily verifiable digital certificates offers a robust solution to combat fraud and streamline credential validation processes for employers and regulators.
Industry Challenges
- Auditor Talent Scarcity:A pronounced shortage of qualified auditors and assessors with deep expertise in new and complex fields, such as cybersecurity, ESG frameworks, and AI ethics, constrains the capacity of certification bodies.
- Pace of Standardization:The development of formal, consensus-based international standards often lags behind the rapid pace of technological innovation, creating a gap where no clear certification path exists for cutting-edge products.
- Certificate Fraud:The persistent challenge of combating counterfeit credentials and the unauthorized use of certification marks undermines the trust that is the fundamental asset of the entire certification industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Certificates Market |
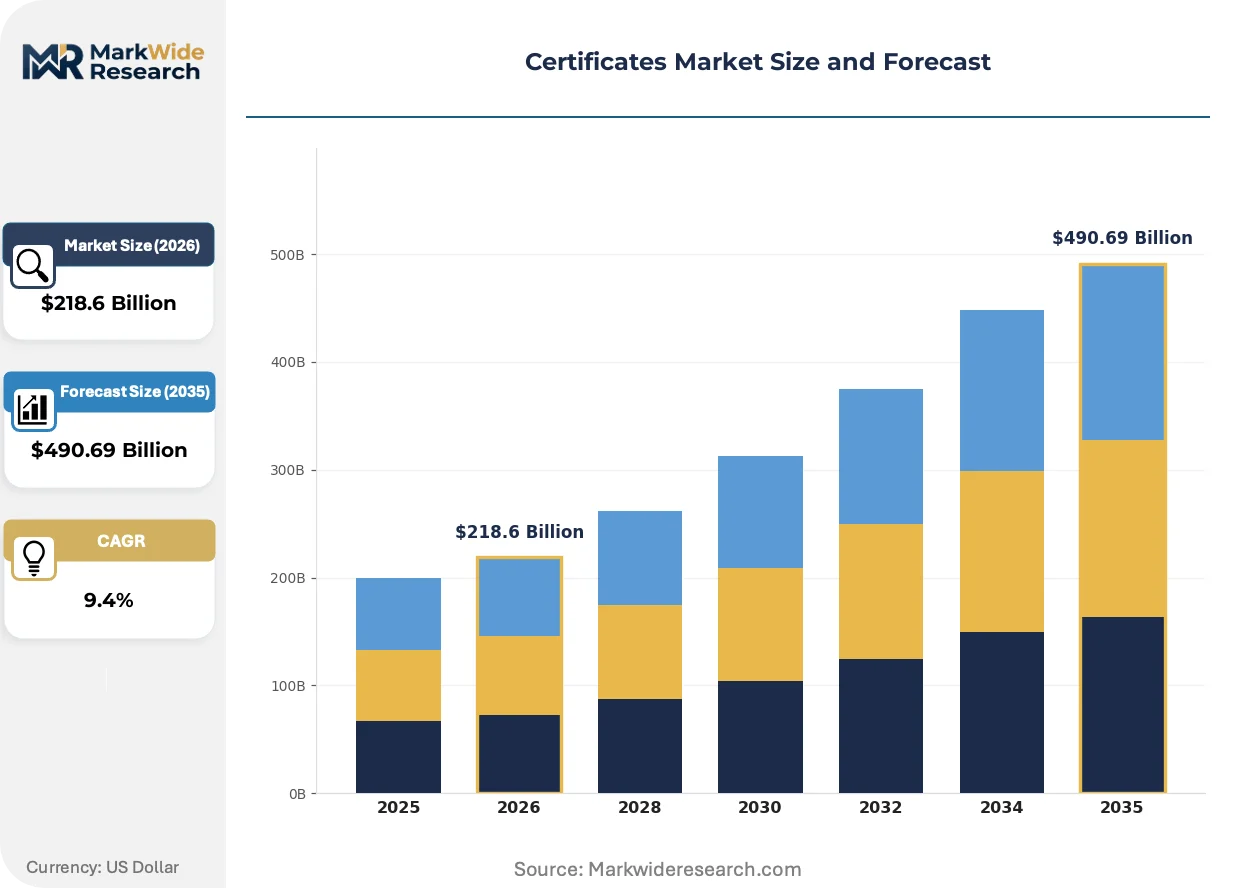
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $490.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: ISO, CE, UL, RoHS, FCC, GMP Industry Vertical: Manufacturing, Information Technology, Construction, Pharmaceuticals, Telecommunications, Food & Beverages Application: Quality Assurance, Compliance Verification, Safety Validation, Environmental Certification, Market Access, Regulatory Approval Customer Type: Small & Medium Enterprises, Large Enterprises, Startups, Government Agencies, Nonprofit Organizations |
| Companies Covered | IASSC, AWS, ISC2, Google, Microsoft, CompTIA, PMI, IBM, ASQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Certificates Market Strategic Shifts & Innovations
Verification mechanisms are evolving from static, point-in-time assessments to dynamic, continuous validation models. This shift emphasizes lifecycle compliance and data-driven proof over singular audits, altering how trust is established and maintained across product, system, and professional certifications.
Digital twinning, a virtual replica of a physical asset, serves as a platform for continuous product assessment. Aerospace and automotive manufacturers are adopting this for ongoing compliance monitoring of complex systems where physical inspection is impractical. This technology is integrating real-time performance data into the certification lifecycle, moving beyond one-time audits to a model of persistent verification.
Regulatory expansion in key markets creates non-negotiable demand for local certification. For instance, India's Bureau of Indian Standards (BIS) is broadening its mandatory certification scheme for electronics and IT hardware. This policy affects global supply chains, forcing manufacturers to incorporate local testing protocols and obtain BIS approval to access the large Indian market.
Enterprises are shifting their procurement of professional development credentials toward multi-source portfolios. This model disrupts the single-vendor lock-in common in corporate training, favoring a flexible, skill-specific approach where employees can gain credentials from various specialized providers. The Information Technology sector, particularly in cloud and data analytics roles, exhibits the most pronounced adoption of this strategy.
Certificates Market Segmentation
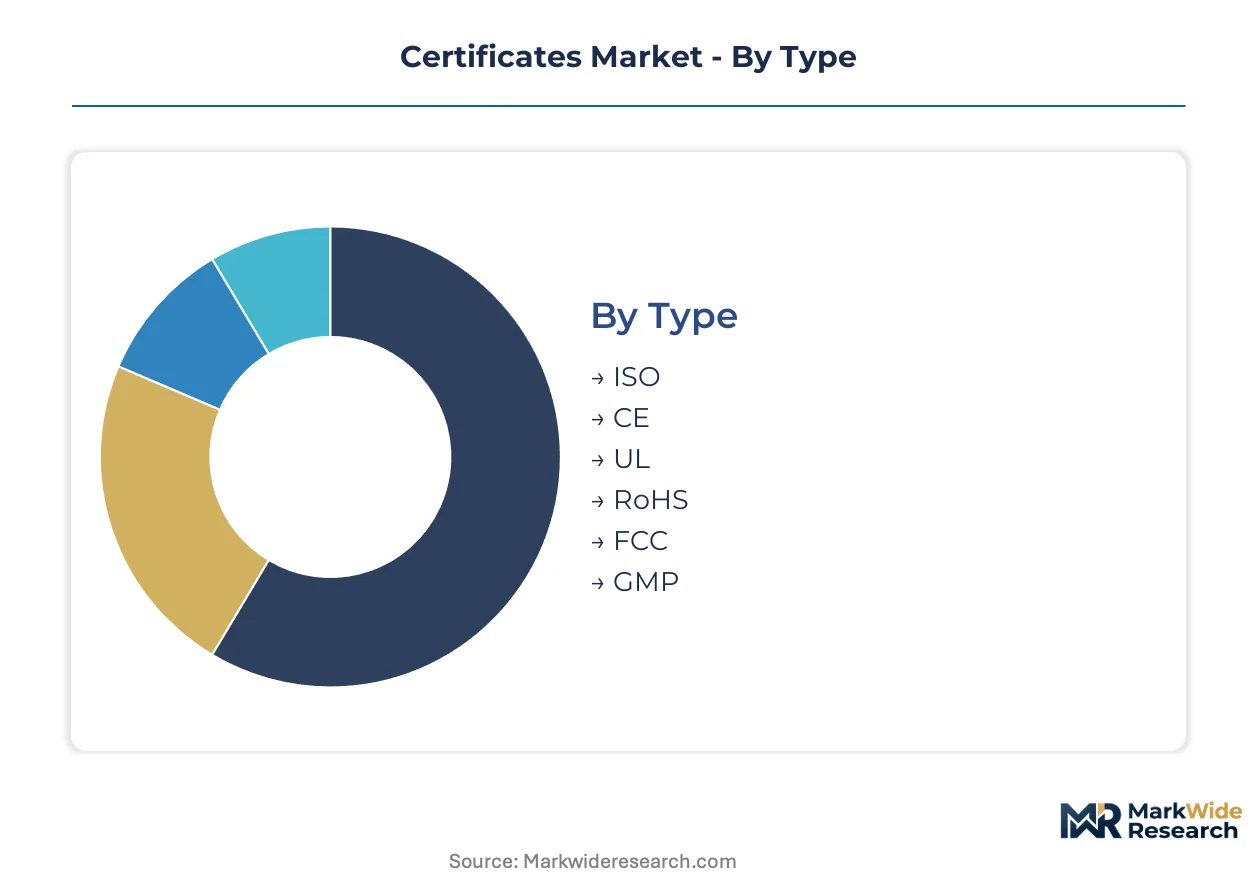
The Certificates Market categorizes diverse verification services that validate adherence to predefined standards across various sectors. Understanding these distinct segments illuminates the varying drivers and regulatory pressures shaping demand. Each category reflects unique compliance requirements and operational frameworks.
Type:
The market's certification types differ significantly in their integration depth, with some being standalone attestations and others embedded within broader regulatory frameworks.
- ISO:These are globally recognized standards for quality management systems, environmental management, or information security. Demand from manufacturing and service industries in the United States and Germany seeks operational excellence and supply chain integrity.
- CE:The CE marking denotes conformity with health, safety, and environmental protection standards for products sold within the European Economic Area. Demand is non-negotiable for manufacturers in China and Vietnam exporting electronics and machinery to EU markets.
- UL:Underwriters Laboratories certification primarily focuses on product safety testing and validation, particularly for electrical and electronic components. Manufacturers across North America prioritize UL listing for consumer trust and liability reduction.
- RoHS:This European directive restricts the use of specific hazardous materials in electrical and electronic equipment. Global electronics producers must comply for EU market entry.
- FCC:The US Federal Communications Commission certifies electronic devices for electromagnetic compatibility and radio frequency emissions. Manufacturers worldwide require FCC approval for products entering the US market.
- GMP:Good Manufacturing Practices are a system for ensuring products like pharmaceuticals and food are consistently produced and controlled according to quality standards. Pharmaceutical companies in India and Brazil strictly adhere to GMP regulations.
ISO leads volumes today; FCC is gaining share fastest.
Industry Vertical:
The industry verticals exhibit distinct certification application patterns, driven by sector-specific regulatory environments and operational complexities.
- Information Technology:This vertical demands credentials verifying skills and systems in cloud infrastructure, cybersecurity, and data protection. Demand from technology hubs in the United States and Singapore is intense due to pervasive digital transformation.
- Pharmaceuticals:This sector requires extensive certifications for drug development, manufacturing processes, and quality control to ensure product safety and efficacy. Regulatory bodies like the US FDA and Europe's EMA drive this stringent demand.
- Manufacturing:This segment focuses on quality management system certifications, such as ISO 9001, to ensure supply chain integrity and operational efficiency. Large manufacturing bases in Germany and Japan consistently require these validations.
- Construction:Certifications in this vertical validate adherence to building codes, safety standards, and material quality for infrastructure projects. Urban development in Canada and Australia drives demand for these attestations.
- Telecommunications:This industry certifies network infrastructure, communication equipment, and service quality. Global providers in the UK and South Korea seek compliance for interoperability and performance.
- Food & Beverages:Certifications here guarantee food safety, hygiene, and traceability from production to consumption. Consumers and regulators in France and Brazil demand these assurances.
The Manufacturing vertical drives significant revenue, while the Information Technology vertical shows rapid expansion.
Application:
The market's applications for certification services vary significantly in their volume, with some dominating the current landscape and others experiencing accelerated adoption.
- Quality Assurance:This application ensures products and processes consistently meet predefined standards and customer expectations. Demand from manufacturing and service industries in Germany and Japan seeks operational excellence.
- Compliance Verification:This application confirms adherence to specific laws, regulations, and industry mandates. Demand from sectors like finance and healthcare in the United States and the UK faces strict regulatory oversight.
- Safety Validation:This confirms products or systems operate without posing undue risk to users or the environment. Aerospace and automotive sectors in France and the United States rely heavily on safety validation.
- Environmental Certification:This attests to sustainable practices, reduced ecological impact, and adherence to green standards. Businesses in Scandinavia and Canada are increasingly seeking these credentials.
- Market Access:This provides necessary approvals for products to enter specific geographic markets, often mandated by local regulations. Manufacturers targeting India and Brazil prioritize these certifications.
- Regulatory Approval:This secures official permission from government bodies for product launch or operation. The pharmaceutical and medical device industries in Europe and the United States frequently pursue regulatory approvals.
The Quality Assurance application accounts for the largest share, with Environmental Certification experiencing the most dynamic growth.
Customer Type:
The customer types diverge in their purchasing patterns and motivations for seeking certifications, largely influenced by their operational scale and market positioning.
- Large Enterprises:These entities seek extensive certifications for complex global supply chains and stringent regulatory environments. Demand from multinational corporations in the United States and Germany requires broad compliance.
- Small & Medium Enterprises:These organizations often pursue certifications to gain credibility, access new markets, and meet procurement requirements. Demand from businesses in Italy and Spain scales operations and enhances competitive standing.
- Startups:These new ventures focus on foundational certifications to establish early market trust and secure initial funding. Technology startups in Israel and Singapore prioritize these attestations.
- Government Agencies:These bodies require certifications for procurement, public safety, and infrastructure projects. Public sector organizations in Canada and Australia demand certified solutions.
- Nonprofit Organizations:These groups utilize certifications to validate ethical practices, ensure donor confidence, and demonstrate accountability. Humanitarian organizations in Switzerland and the Netherlands seek these validations.
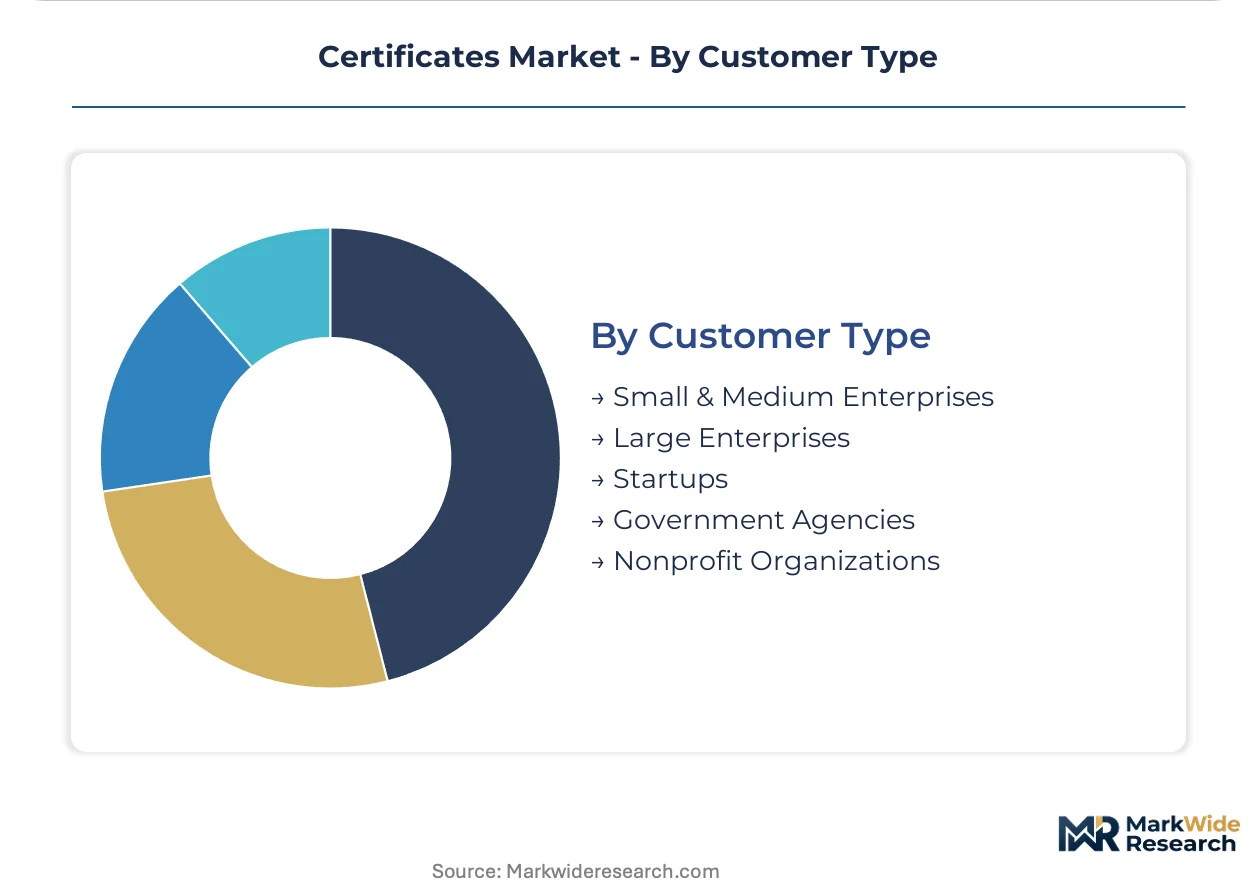
Large Enterprises dominate current expenditure, while Startups demonstrate increasing engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States' technology and manufacturing sectors drive significant demand for certifications. Regulatory frameworks and industry-specific standards shape market dynamics across various geographies. Enterprises prioritize both globally recognized credentials and niche expertise to ensure compliance and market access.
United States
Large technology and manufacturing sectors generate substantial demand for quality and compliance verification. The US FCC imposes certification requirements on electronic devices to ensure electromagnetic compatibility. Silicon Valley and the Midwest manufacturing belt consistently seek product and system certifications.
Germany
Germany's robust manufacturing base consistently requires certifications for operational excellence and supply chain integrity. The CE marking is essential for product market entry within the European Economic Area. Industrial clusters in Bavaria and North Rhine-Westphalia drive demand for ISO 9001 and environmental certifications.
China
China's export-oriented manufacturing industry necessitates certifications to access international markets. Compliance with the EU's RoHS directive is critical for electronic equipment producers targeting European consumers. The Yangtze River Delta region is a major hub for electronics manufacturing requiring global product certifications.
India
India's pharmaceutical industry strictly adheres to Good Manufacturing Practices (GMP) regulations to ensure product safety and efficacy. The Bureau of Indian Standards (BIS) is broadening its mandatory certification scheme for electronics and IT hardware. Hyderabad's pharmaceutical cluster and Bangalore's IT sector are key demand centers.
Singapore
Singapore's role as a technology hub creates intense demand for cloud infrastructure and cybersecurity credentials. The country's data protection frameworks align with global standards, requiring robust system certifications. One-north, a key research and business park, focuses on advanced tech and biomedical certifications.
Certificates Market Key Industry Players
Global majors compete with regional champions across technology and compliance verification services. The market exhibits a tiered structure, with large technology companies offering platform-specific credentials and specialized bodies focusing on regulatory compliance. Strategic archetypes include cloud infrastructure providers, professional development organizations, and product safety certifiers. Companies emphasize portfolio diversification and geographic expansion to meet evolving market needs.
Global technology leaders like AWS, Google, and Microsoft exemplify the convergence of platform services with certification offerings. AWS represents leadership in cloud infrastructure credentials, validating technical skills for its ecosystem. Google differentiates with specialized certifications in data analytics and machine learning, targeting niche technical expertise. Microsoft sustains a broad user base through its extensive enterprise software and Azure certifications, covering a wide spectrum of IT roles and functions. These entities continually evolve their credentialing to align with rapid technological shifts.
| Leading Market Players |
|---|
| IASSC |
| AWS |
| ISC2 |
| Microsoft |
| CompTIA |
| PMI |
| IBM |
| ASQ |
| Others |
Cost & Logistics Intelligence
Global technology leaders and specialized certification bodies, often backed by private equity, shape both supply behavior and pricing discipline within the Certificates Market. These entities invest heavily in accreditation and auditor networks, which directly influence their service delivery models and cost structures.
Pricing Analysis
Auditor expertise and accreditation costs are primary input-cost pass-throughs, influencing pricing across certification types. The dominant pricing structure combines project-based fees for complex system certifications with subscription models for ongoing professional credentials. Price differentiation stems from the specific certification level, such as ISO 9001 versus ISO 27001, and the brand premium associated with bodies like UL. Pricing pressure stems from the proliferation of non-accredited online courses. Small and Medium Enterprises often exhibit greater price sensitivity compared to large multinational corporations.
Supply Chain Analysis
Domestic-content mandates for certification, such as India's Bureau of Indian Standards (BIS) requirements for electronics, reshape the local presence of certification service providers. Geographic supply for certification services concentrates in countries with strong regulatory frameworks and high demand, including the United States, Germany, and China. The supply chain draws from a critical input: highly specialized auditors and subject matter experts. Regulatory fragmentation represents a structural supply chain risk, as different national standards create complexity. Distribution runs through direct client engagement and specialized training partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the forthcoming EU AI Act creating a foundational new demand category for system certification.
For Market Incumbents:Anchor existing market share by diversifying certification portfolios into emerging regulatory domains like ESG and AI governance. Invest in digital verification technologies to combat certificate fraud and enhance audit efficiency. The threat of credential devaluation from informal alternatives necessitates a focus on the rigor and global recognition of formal attestations. Expand auditor training programs to address the talent scarcity in specialized fields such as cybersecurity and AI ethics.
For New Entrants and Emerging Players:Online learning platforms represent a potent digital channel for market entry, offering specialized professional certifications in high-demand areas. Target white-space opportunities in AI ethics certification, leveraging forthcoming regulations like the EU AI Act. The most penetrable segment includes technology startups seeking rapid, niche attestations for market trust. A go-to-market angle focusing on agile, technology-driven verification solutions can differentiate new players.
For Investors and Strategic Acquirers:Valuations sit cheapest among traditional, geographically constrained certification bodies lacking digital transformation initiatives. The long-term viability of this market rests on the increasing complexity of global regulations and the imperative for independent validation. Target acquisition archetypes include specialized firms in ESG reporting verification or blockchain-based credentialing platforms. The signal to watch is the adoption rate of new international standards for emerging technologies, indicating future growth areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI Ethics Certification | This initiative addresses an entirely new regulatory mandate from the EU AI Act. |
| Expand Digital Verification Platforms | This move combats certificate fraud and streamlines credential validation for employers and regulators. |
| Acquire ESG Verification Specialists | This acquisition capitalizes on the growing demand driven by directives like the EU's CSRD. |
| Geographic Expansion into Southeast Asia | This strategy taps into expanding manufacturing hubs seeking access to regulated Western markets. |
| Partner with Cloud Providers for Credentials | This collaboration strengthens professional development offerings in high-demand IT skill areas. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, extensive secondary research, and proprietary database analysis — were reconciled for comprehensive market understanding. This study involved conversations with certification body executives, IT compliance officers, manufacturing quality leads, and pharmaceutical regulatory affairs specialists. Secondary validation drew from regulatory filings by the US FCC and India's BIS, industry association reports from ISO, and corporate sustainability disclosures, triangulating data from bottom-up and top-down perspectives.
The analytical framework reconciled these data streams to project market growth across the analysis window. Segmentation dimensions modeled included certification type (ISO, CE, UL), industry vertical (Information Technology, Pharmaceuticals), application (Quality Assurance, Compliance Verification), customer type (Large Enterprises, SMEs), and certification scope (product, system, professional). Compound Annual Growth Rates were derived from historical data and projected growth drivers such as regulatory mandate timelines and digital transformation spending.
The model assumes a particular technology adoption path; alternative pathways for digital verification and AI integration would alter the outlook. Forecasts reflect assumptions concerning the pace of standardization and the availability of qualified auditor talent. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
North America Strategic Consulting Market