
 Europe Sustainable Finance Market | 2026-2036
Europe Sustainable Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Finance Market Insights
Integration of AI-powered ESG scoring engines is rewriting how portfolio managers screen and weight sustainable assets across European capital markets. Deutsche Bank leverages its Frankfurt-based sustainable bond underwriting platform to anchor green issuance volumes in the DACH region. BlackRock competes through its Paris-aligned ETF framework, which controls index methodology standards for institutional passive flows. Amundi specializes in Article 9 fund construction under SFDR, occupying the highest regulatory tier for sustainable investment products.
Europe sustainable finance encompasses capital instruments, investment vehicles, and regulatory frameworks that direct financial flows toward environmentally beneficial and socially equitable outcomes, measured against EU Taxonomy technical screening criteria for climate adaptation and mitigation. Green bonds dominate funding type volumes due to established verification protocols and investor familiarity, while ESG funds face structural pressure from greenwashing litigation and regulatory reclassification. Private equity and venture capital within investment vehicles capture expanding margin pools as corporates seek transition financing outside public debt markets, particularly for energy efficiency project types in industrial portfolios.
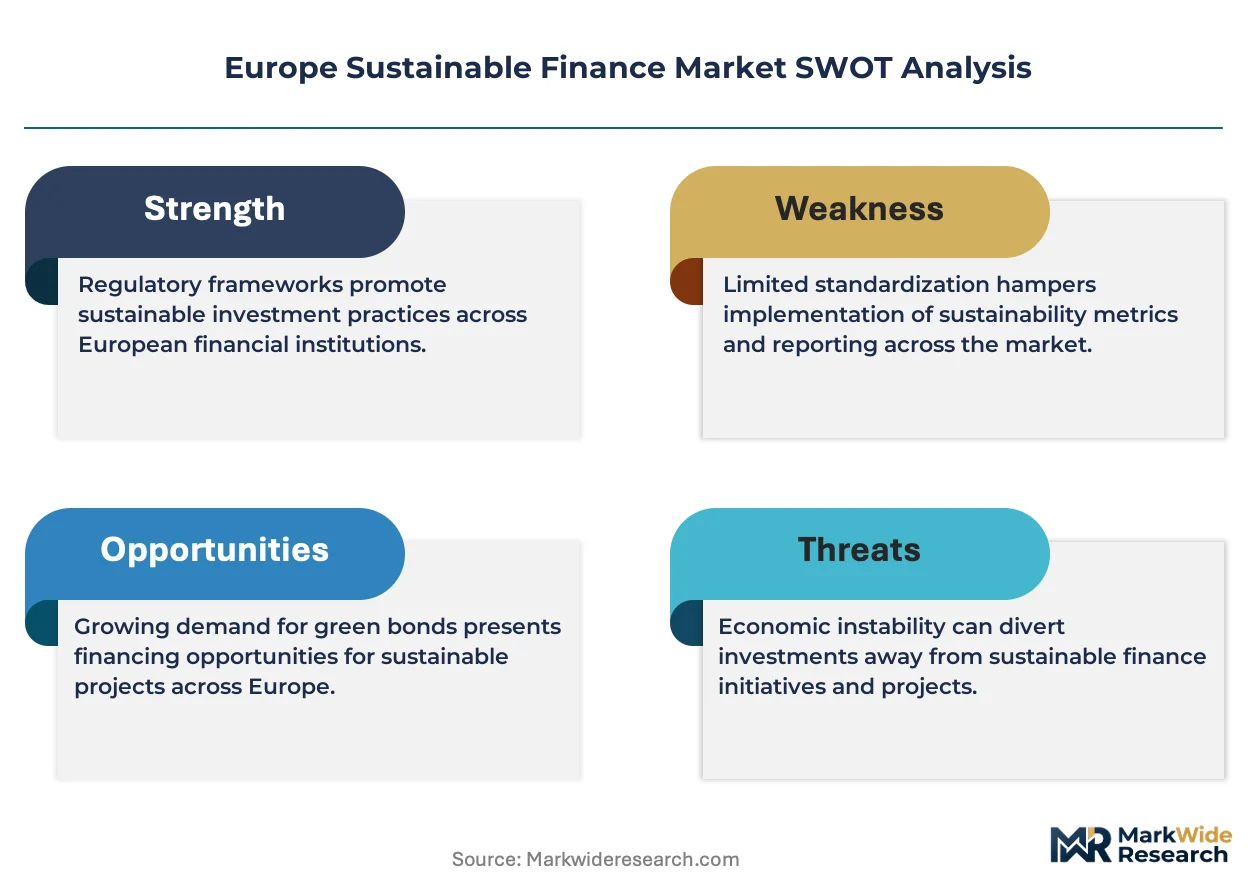
The European Securities and Markets Authority enforces SFDR disclosure consistency, while the EU Green Deal Taxonomy defines which economic activities qualify as environmentally sustainable for investment purposes, creating a compliance threshold that shapes product design and marketing claims. The European Banking Authority's green asset ratio requirements for lenders redirect balance sheet composition toward Taxonomy-aligned exposures. Stakeholders must monitor evolving delegated acts under the Taxonomy framework and anticipate how the EU AI Act will govern automated ESG data processing in investment workflows.
Market Dynamics
The EU Green Deal Taxonomy is compressing capital allocation timelines as institutional investors reweight portfolios toward climate-aligned assets ahead of delegated act expansions.
Growth Catalysts
- CSRD disclosure mandates:Corporate sustainability reporting obligations force asset managers to source verified ESG data, expanding demand for third-party verification services.
- Netherlands sovereign green issuance:Dutch government bond programs establish benchmark pricing curves that lower funding costs for corporate green bond issuers across the DACH corridor.
- Renewable energy project pipelines:Offshore wind capacity auctions in Denmark and Germany absorb long-dated institutional capital seeking inflation-linked yield profiles.
Market Restraints
- EU Taxonomy technical screening complexity:Delegated acts covering transitional activities create compliance uncertainty that delays product launches by 12-18 months.
- Verification service provider concentration:Four dominant ESG rating agencies control methodology standards, creating single-point-of-failure risk for fund classification disputes.
- Greenwashing litigation exposure:Plaintiff law firms in France and Germany file securities claims against Article 8 and 9 funds with ambiguous sustainability commitments.
Strategic Opportunities
- Polish industrial transition financing:Steel and cement sector decarbonization projects lack dedicated credit facilities, opening private debt fund formation opportunities.
- SFDR Article 9 fund whitespace:Regulatory reclassification of existing Article 8 products creates capacity for genuinely sustainable strategies to capture fee premiums.
- Blockchain-enabled green bond verification:Distributed ledger technology reduces settlement friction and enables fractional ownership of municipal green issuance.
Industry Challenges
- Sustainability data scientist scarcity:Portfolio construction teams lack personnel capable of integrating EU Taxonomy alignment calculations into risk models.
- Legacy IT system integration:Asset servicers struggle to embed SFDR disclosure templates into existing portfolio accounting platforms without vendor customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Finance Market |
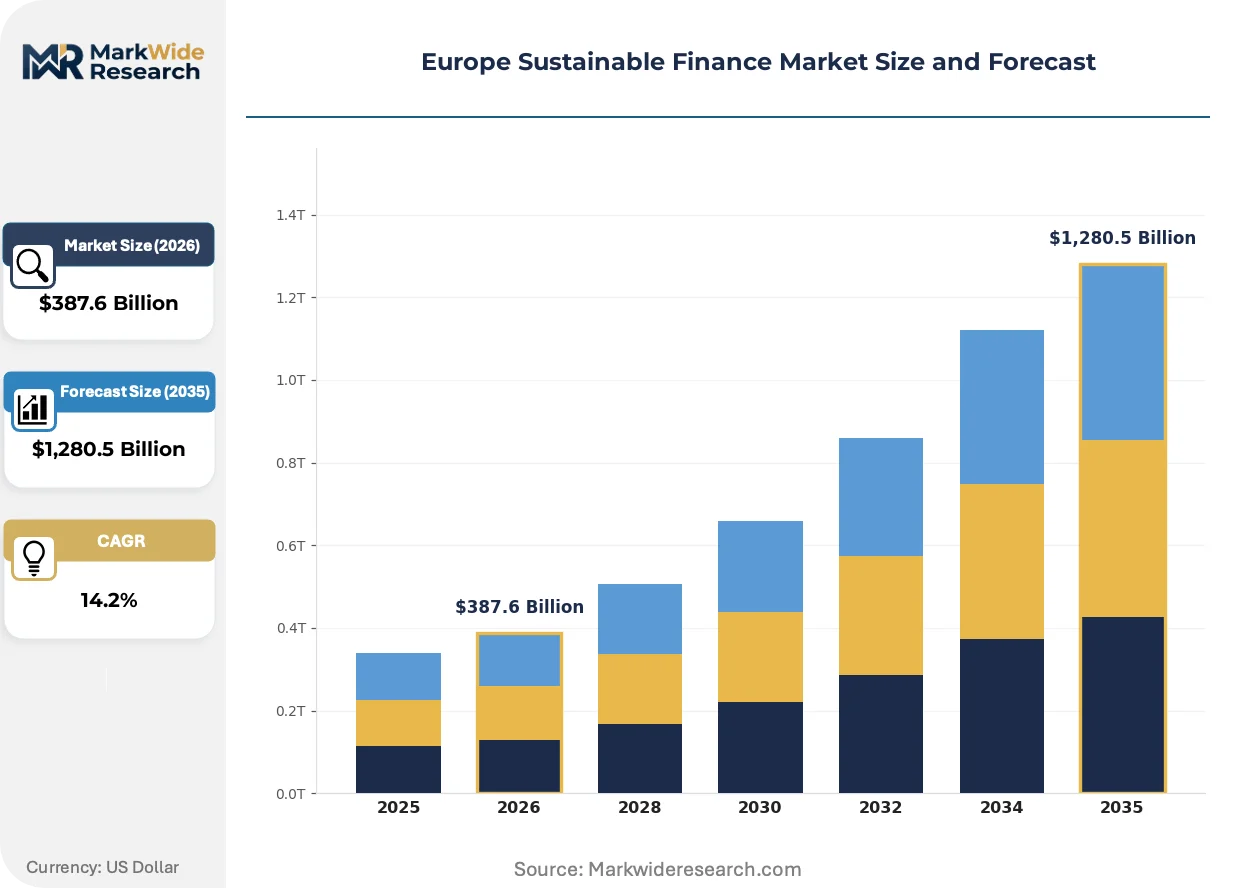
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Funding Type: Green Bonds, Social Bonds, Sustainability Bonds, ESG Funds Investment Vehicle: Public Equity, Private Equity, Venture Capital, Debt Financing Investor Type: Institutional Investors, Retail Investors, Family Offices, Sovereign Wealth Funds Project Type: Renewable Energy, Energy Efficiency, Sustainable Agriculture, Waste Management |
| Companies Covered | State Street Global Advisors, Deutsche Bank, BlackRock, Schroders, Amundi, BNP Paribas, HSBC, UBS Group, Vanguard Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Finance Market Trends and Innovations
Automated ESG scoring infrastructure is compressing due diligence cycles while regulatory classification frameworks force product architecture redesigns across European fund manufacturing.
Natural language processing engines trained on corporate disclosure documents now extract Taxonomy-relevant activity metrics without manual analyst review. Nordic pension funds deploy these tools across equity portfolios exceeding fifty billion euros in assets under management. Static ESG questionnaire methodologies are rendering obsolete as real-time signal extraction becomes cost-competitive.
The EU AI Act imposes transparency requirements on automated credit scoring systems that incorporate ESG factors into lending decisions. European Banking Authority guidance clarifies how green asset ratio calculations must treat exposures to AI-screened borrowers. French and German retail banks accelerate procurement of explainable AI modules to preserve regulatory capital treatment.
Corporate treasury departments now mandate second-party opinions for all labeled bond issuance regardless of investor targeting. Green bond underwriters in Amsterdam and Luxembourg compete on verification speed rather than pricing alone. This procurement pattern shift concentrates mandate flow toward platforms with integrated climate risk analytics capabilities.
Europe Sustainable Finance Market Segmentation
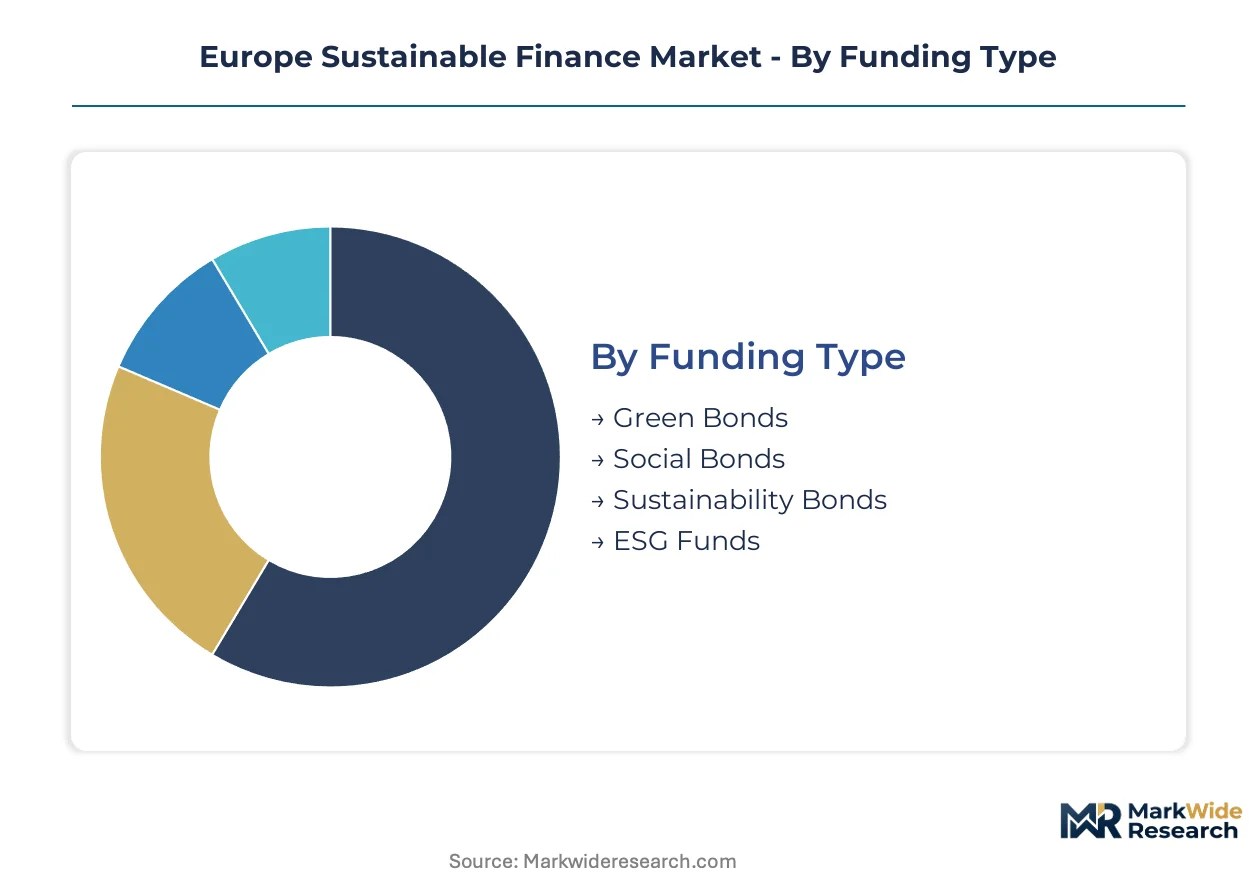
Segmentation reveals how capital flows fragment across instruments, vehicles, and beneficiary projects under Europe's regulatory architecture. Distinct compliance thresholds and return profiles separate institutional from retail participation, while project-level Taxonomy alignment determines fund eligibility.
Funding Type:
Cost tier differentiation separates established verification-heavy instruments from emerging formats still building investor familiarity.
- Green Bonds:Debt securities earmark proceeds exclusively for climate mitigation or adaptation projects per ICMA Green Bond Principles. Dutch sovereign issuance and supranational benchmarks from the European Investment Bank anchor pricing curves that compress corporate spreads across the DACH corridor.
- ESG Funds:Collective investment vehicles integrate environmental, social, and governance criteria into security selection, with SFDR Article 9 products facing intensified scrutiny for greenwashing exposure. Regulatory reclassification of Article 8 products is compressing fee premiums for genuinely sustainable strategies.
- Social Bonds:Proceeds finance affordable housing, education access, and healthcare infrastructure in underserved communities. French agency Caisse des Dépôts dominates European social bond issuance volume.
- Sustainability Bonds:Hybrid instruments combine green and social use-of-proceeds categories within single frameworks. Nordic municipalities favor this format for integrated climate and welfare project pipelines.
Green bonds command the established base. The steepest expansion runs through ESG funds as SFDR disclosure mandates deepen retail participation.
Investment Vehicle:
Application maturity separates liquid public market exposure from illiquid transition financing requiring specialized structuring.
- Debt Financing:Bank loans and private credit facilities fund mid-market corporate decarbonization outside public bond markets. Polish steel and cement sector transition projects absorb expanding private debt fund formation.
- Private Equity:Buyout and growth capital strategies target industrial portfolio energy efficiency retrofits and circular economy business models. French and German mid-cap sponsors compete for Article 9 fund mandates.
- Public Equity:Listed equity strategies integrate EU Taxonomy alignment metrics into portfolio construction. Nordic pension funds deploy natural language processing engines across equity portfolios exceeding fifty billion euros.
- Venture Capital:Early-stage capital flows to climate technology startups in carbon capture, green hydrogen, and sustainable materials. Amsterdam and Berlin cluster density attracts dedicated sustainability-focused fund managers.
Debt financing anchors current deployment volumes. Venture capital is gaining share fastest as technology cost curves steepen and EU innovation funding matches private commitments.
Investor Type:
Volume concentration and regulatory leverage differentiate wholesale institutional participation from fragmented retail channels.
- Institutional Investors:Pension funds, insurance companies, and asset managers channel long-dated liabilities into inflation-linked renewable energy infrastructure. Danish and German offshore wind capacity auctions absorb dedicated institutional capital seeking yield profiles uncorrelated with fixed income benchmarks.
- Sovereign Wealth Funds:State-owned investment vehicles from Norway and Gulf entities deploy capital into European green bond benchmarks and direct infrastructure stakes. Their scale influences pricing in primary issuance windows.
- Family Offices:Single and multi-family structures pursue direct co-investment in private transition financing outside fund fee structures. Swiss and Luxembourg domiciles concentrate family office sustainable finance advisory services.
- Retail Investors:Individual savers access sustainable finance through UCITS funds, structured products, and savings-linked green bonds. French and Italian retail banks compete on ESG fund distribution platforms.
Institutional investors command the established base. Retail channels are expanding most quickly as MiFID II suitability rules embed sustainability preferences into advisory workflows.
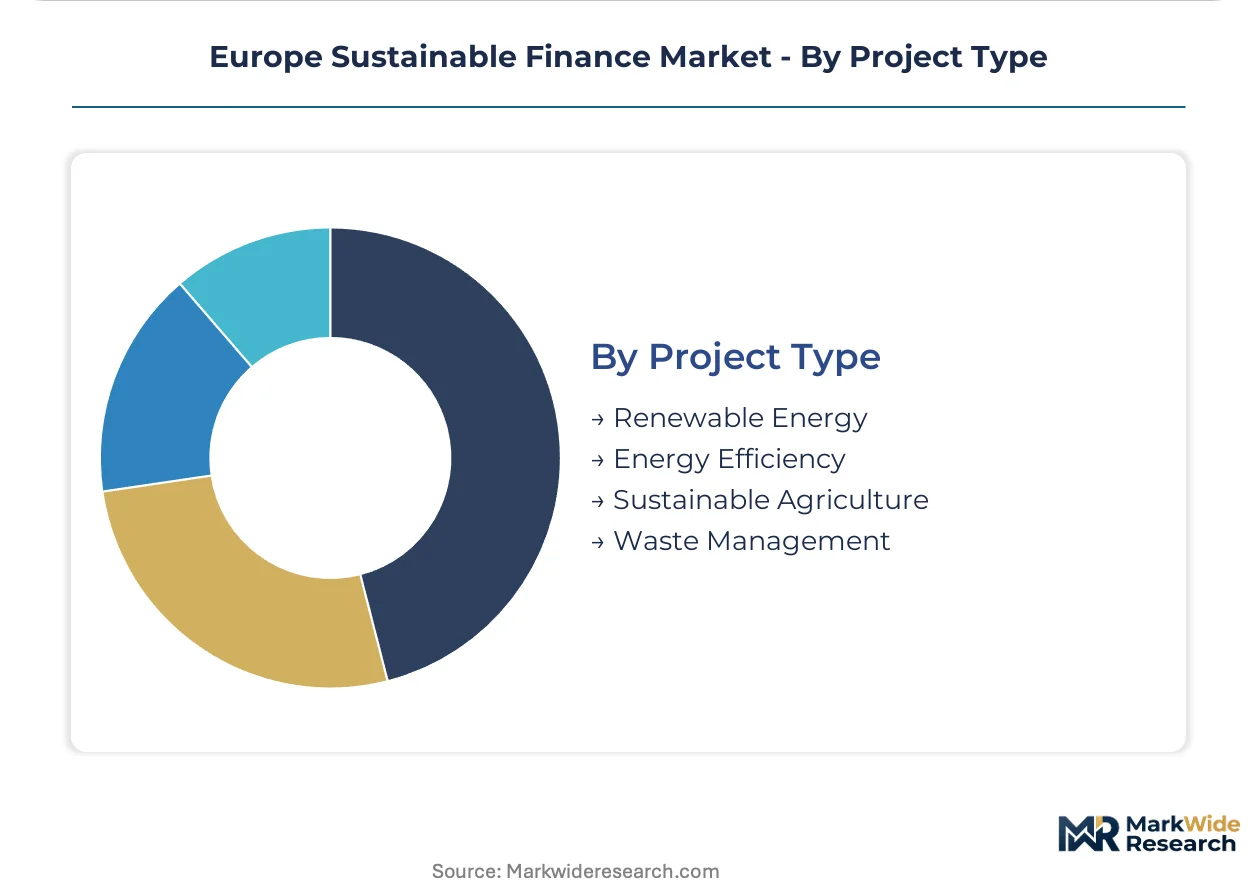
Project Type:
Customer-type alignment with EU Taxonomy technical screening criteria determines capital access and green asset ratio treatment for lenders.
- Renewable Energy:Wind, solar, and green hydrogen generation assets qualify for streamlined Taxonomy alignment verification. Danish and German offshore wind auctions attract long-dated institutional capital.
- Energy Efficiency:Building retrofit, industrial process optimization, and smart grid infrastructure reduce energy consumption intensity. Polish and Czech industrial portfolios lack dedicated credit facilities for comprehensive efficiency programs.
- Sustainable Agriculture:Regenerative farming practices, precision agriculture technology, and supply chain traceability systems qualify for blended finance structures. Dutch agricultural banks pioneer sustainability-linked loan pricing for farm cooperatives.
- Waste Management:Circular economy infrastructure including recycling facilities, waste-to-energy plants, and packaging reuse systems. Nordic extended producer responsibility frameworks concentrate project development expertise.
Renewable energy commands the established base. Energy efficiency is climbing the fastest as building renovation wave targets and industrial decarbonization deadlines compress project timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German institutional capital exports into Dutch sovereign green bonds and Nordic offshore wind auctions, establishing the Rhine-Ruhr corridor as Europe's primary sustainable finance origination hub.
Germany
Frankfurt-based asset servicers and DAX-listed corporates drive green bond underwriting volumes through the EU Green Deal Taxonomy compliance frameworks. The Federal Financial Supervisory Authority enforces SFDR disclosure standards for domestic fund manufacturers. North Rhine-Westphalia's industrial belt absorbs transition financing for steel and cement decarbonization projects.
France
Paris-aligned ETF frameworks and Article 9 fund construction dominate institutional product architecture under SFDR mandates. The Autorité des Marchés Financiers monitors greenwashing litigation exposure across retail distribution channels. Île-de-France concentrates ESG data science talent and sustainable bond verification service providers.
Netherlands
Dutch pension funds and sovereign issuance programs establish benchmark pricing curves that compress corporate spreads across neighboring markets. The Dutch Authority for the Financial Markets supervises MiFID II sustainability preference integration into advisory workflows. Amsterdam anchors green bond underwriting platforms competing on verification speed.
Nordic Region
Danish and Swedish offshore wind capacity auctions absorb long-dated institutional capital seeking inflation-linked yield profiles uncorrelated with fixed income benchmarks. National pension regulators mandate EU Taxonomy alignment reporting for domestic asset pools. Copenhagen and Stockholm cluster natural language processing engines for automated ESG scoring across equity portfolios.
Poland
Steel sector decarbonization and industrial energy efficiency retrofits generate demand for private debt facilities lacking dedicated credit structures. The Polish Financial Supervision Authority implements CSRD disclosure mandates for Warsaw Stock Exchange-listed entities. Silesian industrial corridors seek transition financing outside public bond markets.
Europe Sustainable Finance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale-driven asset managers, bank-affiliated underwriters, and independent verification platforms occupy distinct competitive positions. The vendor base separates into three strategic archetypes: index methodology standard-setters, regulatory compliance service providers, and transition financing specialists. Dominant competitive moves include strategic partnerships between data providers and fund manufacturers, plus portfolio diversification into private market transition vehicles.
Among US-based asset managers, BlackRock and State Street Global Advisors occupy positions as scale-driven index methodology anchors, while Deutsche Bank exemplifies the bank-affiliated underwriting archetype within the DACH region. These entities represent contrasting approaches to sustainable finance market participation—passive flow capture versus origination infrastructure control.
| Leading Market Players |
|---|
| State Street Global Advisors |
| Deutsche Bank |
| BlackRock |
| Schroders |
| Amundi |
| BNP Paribas |
| HSBC |
| UBS Group |
| Vanguard Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in green bond verification services across Amsterdam and Luxembourg is compressing fee margins while forcing providers to differentiate through speed-to-market rather than pricing alone. This utilization dynamic reshapes how underwriters and data vendors compete for mandate flow across European capital markets.
Pricing Analysis
The verification-technology pricing gap separates legacy second-opinion providers from AI-augmented platforms capable of real-time Taxonomy alignment scoring. Three-tier pricing structure across premium, standard, and economy levels dominates green bond issuance, with premium tiers commanding faster turnaround and enhanced climate risk analytics. Cost compression in standard-tier verification is intensifying because automated NLP engines reduce analyst hours required for disclosure review. Retail ESG fund distributors exhibit highest price sensitivity, while sovereign wealth funds prioritize certification credibility over fee minimization.
Supply Chain Analysis
EU AI Act transparency requirements for automated ESG scoring systems function as de facto export controls limiting technology flows from non-compliant jurisdictions. Geographic supply concentration centers on France, Germany, and the Netherlands for ESG data science talent and verification infrastructure. Raw material dependencies include proprietary climate datasets, regulatory interpretation software, and explainable AI modules. Single-source vulnerability runs through the four dominant ESG rating agencies controlling SFDR classification methodology. Distribution runs through bank-affiliated platforms in Frankfurt and Paris plus independent fintech channels in Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sustainable finance market represents a high-growth disruption propelled by CSRD disclosure mandates forcing asset managers to source verified ESG data at scale.
For Market Incumbents: Pre-empt regulatory reclassification risk by accelerating Article 9 fund construction ahead of delegated act expansions covering transitional activities. Fortify data infrastructure through backward integration into climate risk analytics capabilities, reducing dependence on third-party verification providers facing concentration risk. Deutsche Bank and Amundi demonstrate how origination platform control preserves fee premiums amid standardization pressure. For New Entrants and Emerging Players: Polish industrial transition financing for steel and cement decarbonization represents the most penetrable entry point, given absence of dedicated credit facilities and EU innovation funding matches. Blockchain-enabled fractional green bond ownership for municipal issuance offers second white-space target with lower incumbent saturation. Go-to-market positioning should emphasize speed-to-verification against legacy providers anchored to manual analyst workflows. For Investors and Strategic Acquirers: Capital is best deployed toward regulatory compliance service providers with embedded AI scoring infrastructure and established European Banking Authority relationships. Long-term viability hinges on capturing recurring revenue from SFDR disclosure mandates rather than transactional green bond fees. The signal to watch is European Securities and Markets Authority enforcement action against Article 8 fund reclassifications, which would accelerate demand for genuinely sustainable strategies.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered ESG Scoring Platform Deployment | Natural language processing engines trained on corporate disclosures compress due diligence cycles for Nordic pension funds exceeding fifty billion euros. |
| SFDR Article 9 Fund Construction | Highest regulatory tier qualification captures fee premiums as reclassification of Article 8 products creates capacity for genuine sustainable strategies. |
| Blockchain Green Bond Verification Infrastructure | Distributed ledger technology reduces settlement friction and enables fractional ownership of municipal issuance in Amsterdam and Luxembourg markets. |
| Polish Industrial Transition Debt Facility Formation | Steel and cement sector decarbonization projects lack dedicated credit structures, opening private debt fund opportunities in Silesian corridors. |
| Explainable AI Module Procurement | French and German retail banks accelerate adoption to preserve regulatory capital treatment under EU AI Act transparency requirements. |
Research Methodology
Initial hypotheses were tested against primary input from portfolio construction heads, ESG data scientists, sustainable bond underwriters, and regulatory compliance officers at asset servicers and refined through secondary validation. Primary fieldwork captured workflow integration challenges for SFDR disclosure templates and Taxonomy alignment calculation methods. Secondary sources encompassed European Securities and Markets Authority enforcement patterns, European Banking Authority green asset ratio guidance, EU delegated acts under the Taxonomy framework, and fund flow data from UCITS registration databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling capital flows across funding types, investment vehicles, investor categories, and project-level Taxonomy alignment. Segmentation dimensions included instrument maturity, liquidity profile, regulatory classification tier, and regional regulatory cluster. CAGRs were derived through regression analysis of historical issuance volumes against policy implementation timelines and institutional mandate growth trajectories. Forecast inputs incorporated EU Green Deal Taxonomy expansion schedules and CSRD phased implementation deadlines.
Practitioners should monitor delegated act revisions for transitional activities and European Securities and Markets Authority reclassification enforcement for early signals of forecast deviation. Forecasts reflect assumptions regarding policy implementation continuity and institutional capital reallocation velocity. Material shifts in EU Taxonomy technical screening criteria or greenwashing litigation precedent would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Global Credit Risk Rating Software Market