
 Stress Testing Services Market | 2026-2036
Stress Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Testing Services Market Analytics
CCAR is decoupling stress testing from static spreadsheet workflows and forcing institutions into real-time computational architectures. IBM Corporation leverages its mainframe-to-cloud migration suites to anchor institutional clients navigating Fed compliance timelines. Moody's Analytics competes through scenario library depth that extends across macroeconomic shocks and idiosyncratic risk factors. SAS Institute Inc. specializes in high-performance analytics grids that dominate the on-premise segment among North American banks with data sovereignty requirements.
Stress Testing Services encompass systematic evaluation of portfolio resilience, capital adequacy, and operational continuity under adverse conditions, typically employing Monte Carlo simulations, agent-based models, and regulatory scenario libraries at confidence intervals of 99.9 percent. These services enable financial institutions to quantify tail-risk exposures and satisfy prudential capital requirements mandated by supervisory frameworks. The service type dimension shows regulatory compliance occupying the largest revenue pool due to mandatory submission cycles, while risk analysis represents the fastest-expanding category as insurers and asset managers adopt bank-grade methodologies. Cloud-based delivery models are capturing disproportionate growth among mid-tier investment firms seeking elastic compute without captive infrastructure, though hybrid architectures sustain margin premiums at tier-one banks with legacy core systems.
The Federal Reserve, the European Central Bank, and the Bank of England collectively shape demand through divergent scenario design timelines, disclosure granularity rules, and countercyclical buffer triggers that determine model complexity thresholds. Basel III endgame revisions are forcing recalibration of risk-weighted asset engines across jurisdictions, directly expanding service scopes for validation and audit functions. Stakeholders must monitor whether supervisory convergence or fragmentation wins the transatlantic regulatory dialogue, as this determines whether platform standardization or bespoke national deployments capture the next wave of procurement budgets.
Market Dynamics
The Federal Reserve's CCAR mandates are forcing US banks to abandon static spreadsheet workflows and migrate toward real-time computational architectures capable of dynamic scenario modeling at 99.9 percent confidence intervals.
Growth Catalysts
- Basel III Endgame Revisions:Risk-weighted asset recalibration requirements across US, UK, and EU jurisdictions are expanding validation and audit service scopes for stress testing providers.
- Cloud Elasticity Demand:Mid-tier investment firms in the United Kingdom are adopting cloud-based delivery models to access Monte Carlo simulation capacity without captive infrastructure investments.
- Insurance Sector Methodology Migration:Asset managers and insurers are importing bank-grade stress testing frameworks to quantify tail-risk exposures previously unmeasured in portfolio construction.
Market Restraints
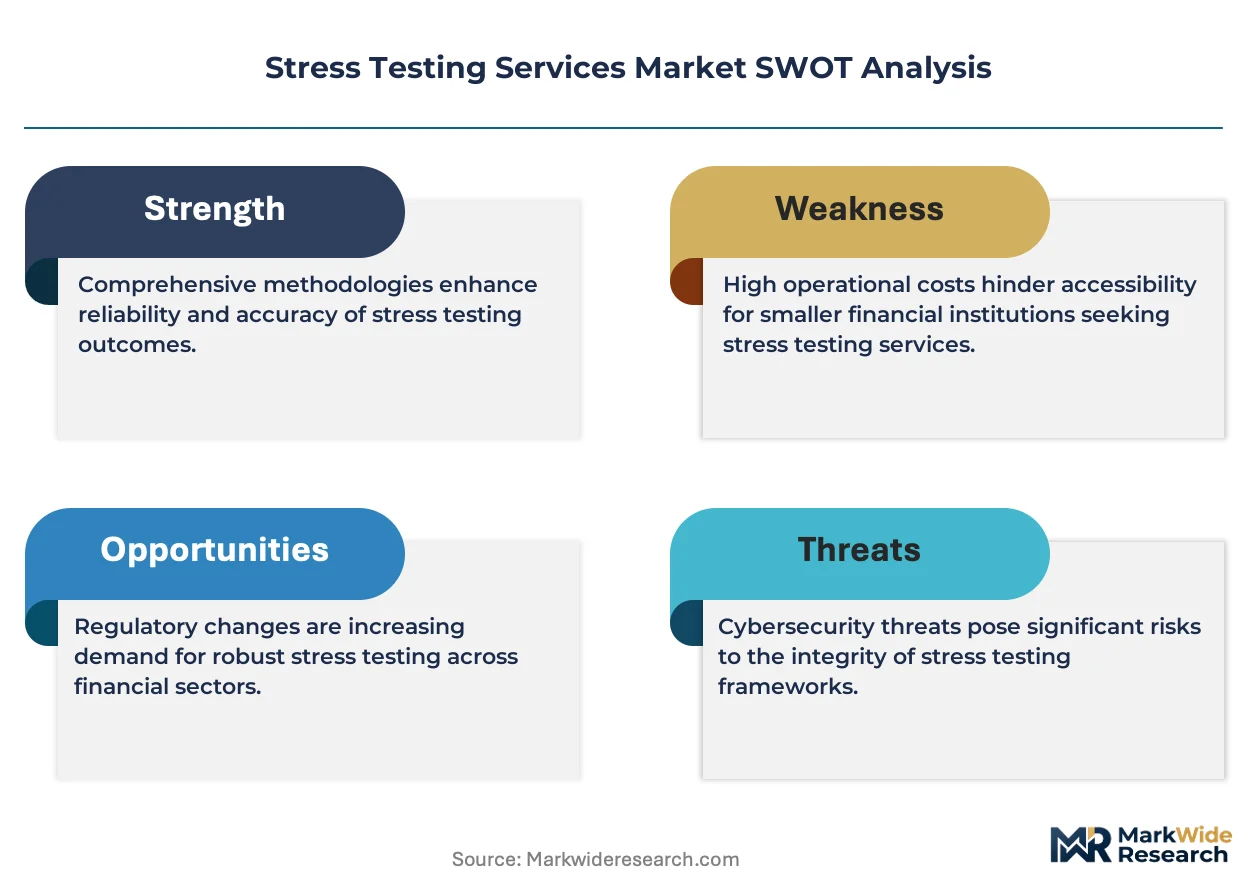
- Legacy Core System Inertia:Tier-one banks maintain hybrid architectures due to data sovereignty requirements, sustaining margin premiums that compress vendor profitability.
- Computational Cost Escalation:Agent-based models and granular scenario libraries require specialized high-performance analytics grids that strain mid-tier firm IT budgets.
- Regulatory Timeline Divergence:The Federal Reserve, European Central Bank, and Bank of England operate mismatched scenario design calendars that fragment platform standardization efforts.
Strategic Opportunities
- Operational Continuity Services:Stress testing providers can extend beyond capital adequacy into operational resilience validation as supervisory frameworks expand scope.
- Scenario Library Licensing:Deep macroeconomic shock repositories represent defensible IP assets that institutions will license rather than build internally.
- Mainframe Migration Suites:Technology vendors can capture institutional clients navigating compressed Fed compliance timelines through mainframe-to-cloud transition services.
Industry Challenges
- Quantitative Modeler Scarcity:The specialized workforce capable of building and validating agent-based models at prudential standards remains concentrated among incumbent vendors.
- Cross-Jurisdictional Compliance Complexity:Service providers must maintain parallel scenario engines to satisfy divergent disclosure granularity rules across the transatlantic regulatory dialogue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Testing Services Market |
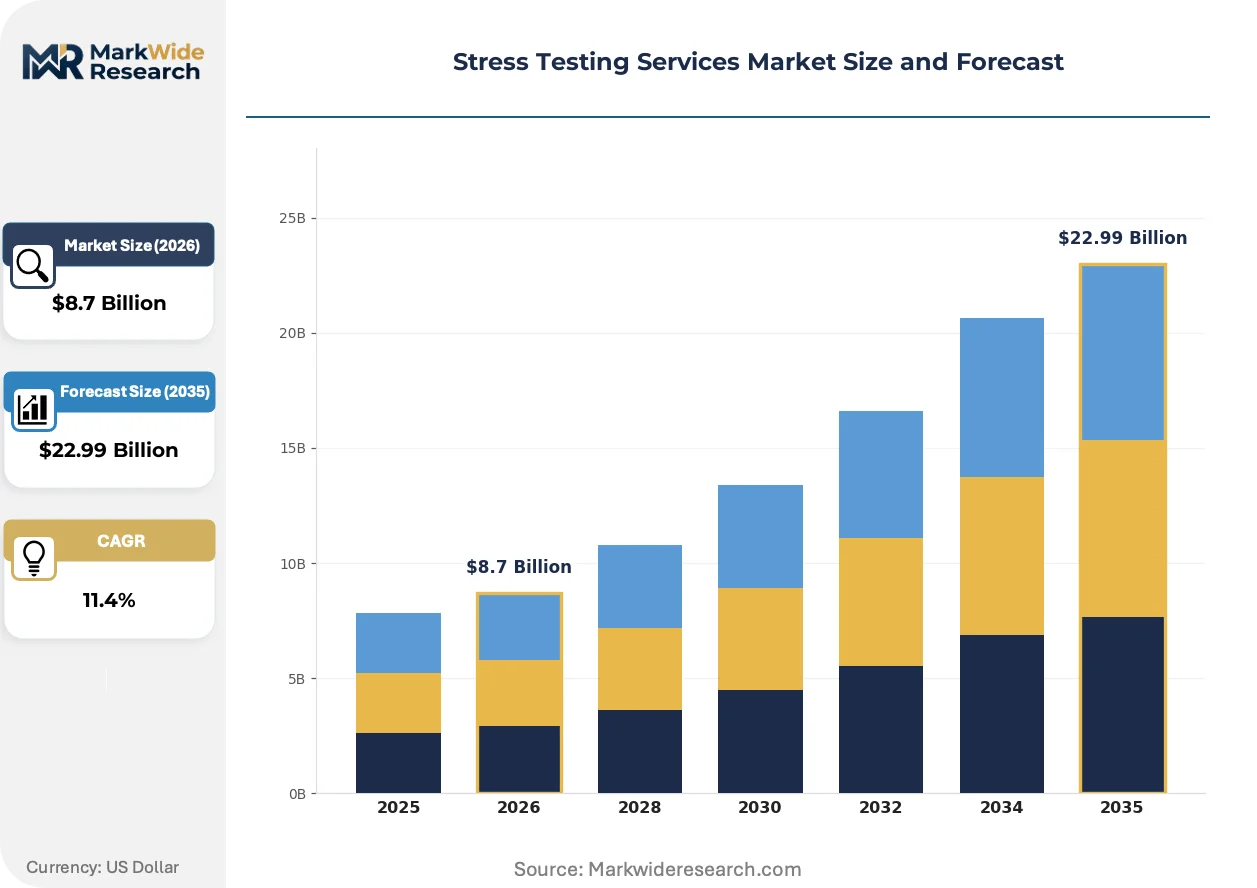
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regulatory Compliance, Performance Evaluation, Capacity Assessment, Risk Analysis Customer Type: Financial Institutions, Insurance Companies, Investment Firms, Corporates Industry Vertical: Banking, Insurance, Healthcare, Telecommunications Delivery Model: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, SAP SE, SAS Institute Inc., FIS, Moody's Analytics, Murex S.A.S., TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Testing Services Market Evolving Landscape
Monte Carlo simulation architectures are converging with cloud-native delivery models, compressing the historical trade-off between computational intensity and infrastructure accessibility that previously segmented the vendor landscape.
Graphical processing unit acceleration is converging with containerized deployment frameworks to enable elastic scenario computation. Tier-two investment firms are adopting these stacks at accelerated procurement cycles. The technology is converging with regulatory submission timelines to compress model execution windows from quarterly batches to continuous monitoring.
The European Central Bank's climate risk stress testing mandates are embedding environmental transition scenarios into prudential frameworks. Banks must now model correlated credit and market risks under disorderly decarbonization pathways. Continental European institutions are responding by licensing specialized scenario libraries rather than building internal climate-econometric capabilities.
After-sales service unbundling is fragmenting the traditional bundled consulting model. Asset managers are purchasing standalone model validation services separate from scenario design or computational infrastructure. This pattern is most visible among London-based alternative investment firms modernizing legacy risk infrastructure.
Stress Testing Services Market Segmentation
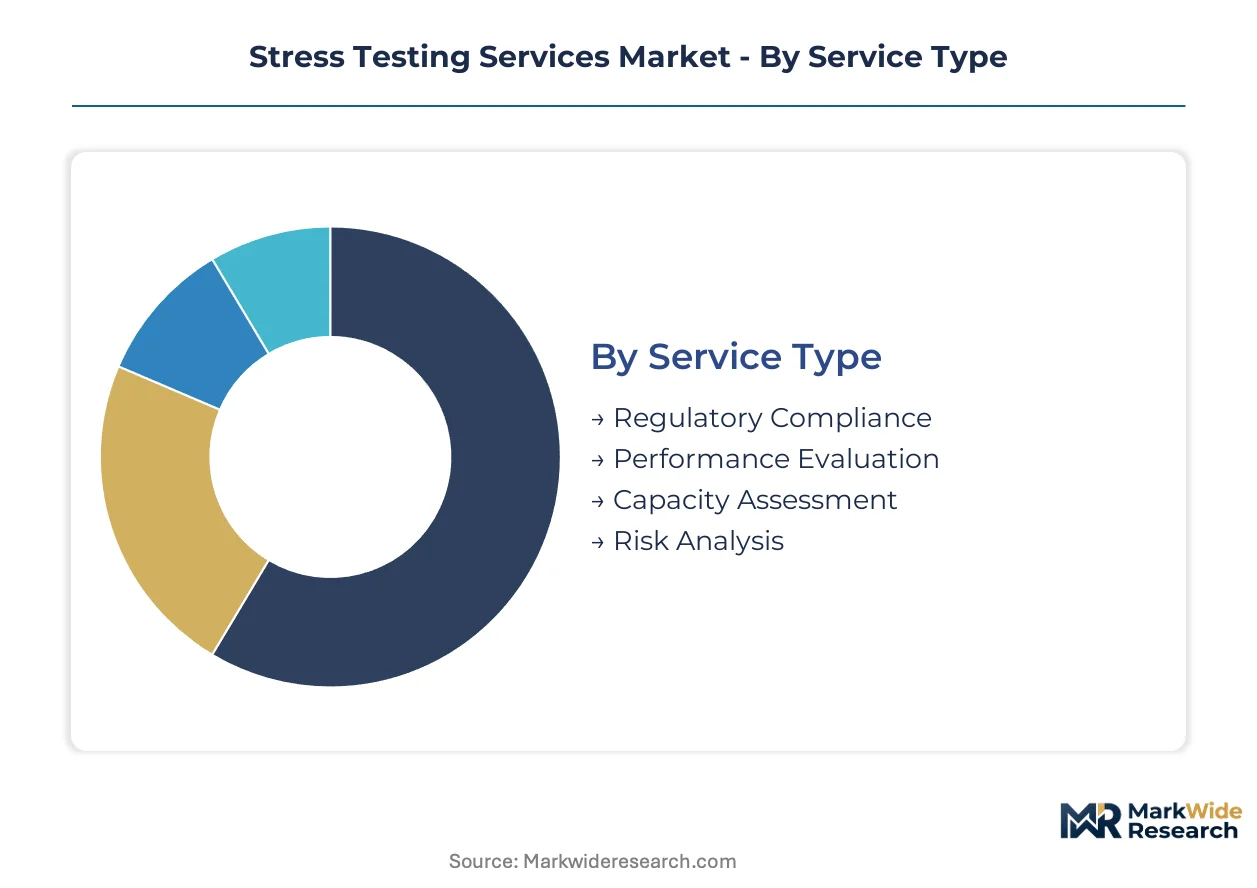
Segmentation reveals how stress testing services bifurcate between mandatory regulatory workflows and discretionary risk analytics. Procurement patterns diverge sharply across delivery models and customer sophistication tiers.
Service Type:
Supply concentration tilts heavily toward compliance-centric offerings as institutions face unmovable supervisory deadlines.
- Regulatory Compliance:Encompasses CCAR, EBA stress test, and Pillar 2 submission packages with pre-built scenario libraries and validation documentation. United States banks dominate procurement volumes as Federal Reserve timelines compress model development cycles. Mandatory submission requirements eliminate price elasticity among tier-one institutions.
- Risk Analysis:Covers tail-risk quantification, portfolio sensitivity mapping, and idiosyncratic shock modeling for trading book and banking book exposures. Investment firms in the United Kingdom are importing these methodologies to satisfy investor due diligence beyond regulatory minimums. Asset managers prize scenario granularity that extends beyond standard supervisory templates.
- Performance Evaluation:Benchmarks capital efficiency and risk-adjusted returns against peer institutions using proprietary scoring frameworks.
- Capacity Assessment:Measures operational resilience and liquidity buffer adequacy under sustained stress conditions.
Regulatory Compliance absorbs the bulk of installed capacity; Risk Analysis is expanding most quickly.
Customer Type:
Cost tier stratification separates captive infrastructure spenders from elastic compute renters.
- Financial Institutions:Universal banks, regional banks, and credit unions with mandatory CCAR, EBA, or Pillar 2 obligations. These entities maintain the largest in-house model risk management functions and drive demand for hybrid deployment architectures. Data sovereignty requirements sustain premium pricing for on-premise compute nodes.
- Investment Firms:Hedge funds, private equity sponsors, and asset managers adopting bank-grade stress testing for limited partner reporting. Mid-tier firms in London are bypassing capital expenditure through cloud-native Monte Carlo platforms. Procurement cycles compress as investor mandates harden around tail-risk disclosure.
- Insurance Companies:Life, property-casualty, and reinsurance carriers integrating Solvency II and ORSA stress testing into capital modeling.
- Corporates:Non-financial enterprises assessing liquidity, covenant, and counterparty exposure concentrations.
Financial Institutions command the deepest procurement budgets; Investment Firms are climbing the fastest.
Industry Vertical:
Application intensity varies by prudential framework maturity and supervisory examination frequency.
- Banking:The foundational vertical with continuous supervisory stress testing mandates across the United States, United Kingdom, and European Union. Scenario complexity escalates as climate risk and cyber risk modules embed into standard exercises. Model validation teams at major banks represent the largest employer of specialized quantitative talent.
- Insurance:Growing vertical as Solvency II, ORSA, and NAIC requirements harden around stochastic reserving and asset-liability matching. European carriers license specialized longevity and catastrophe scenario libraries rather than building internal econometric capabilities. Climate transition risk is forcing recalibration of traditional actuarial models.
- Healthcare:Emerging vertical addressing operational continuity and reimbursement stress under pandemic or regulatory payment shocks.
- Telecommunications:Niche vertical focused on network resilience and subscriber churn modeling under economic contraction scenarios.
Banking retains the steepest concentration of vendor relationships; Insurance is gaining share fastest.
Delivery Model:
Volume distribution reflects a structural migration away from captive infrastructure toward consumption-based alternatives.
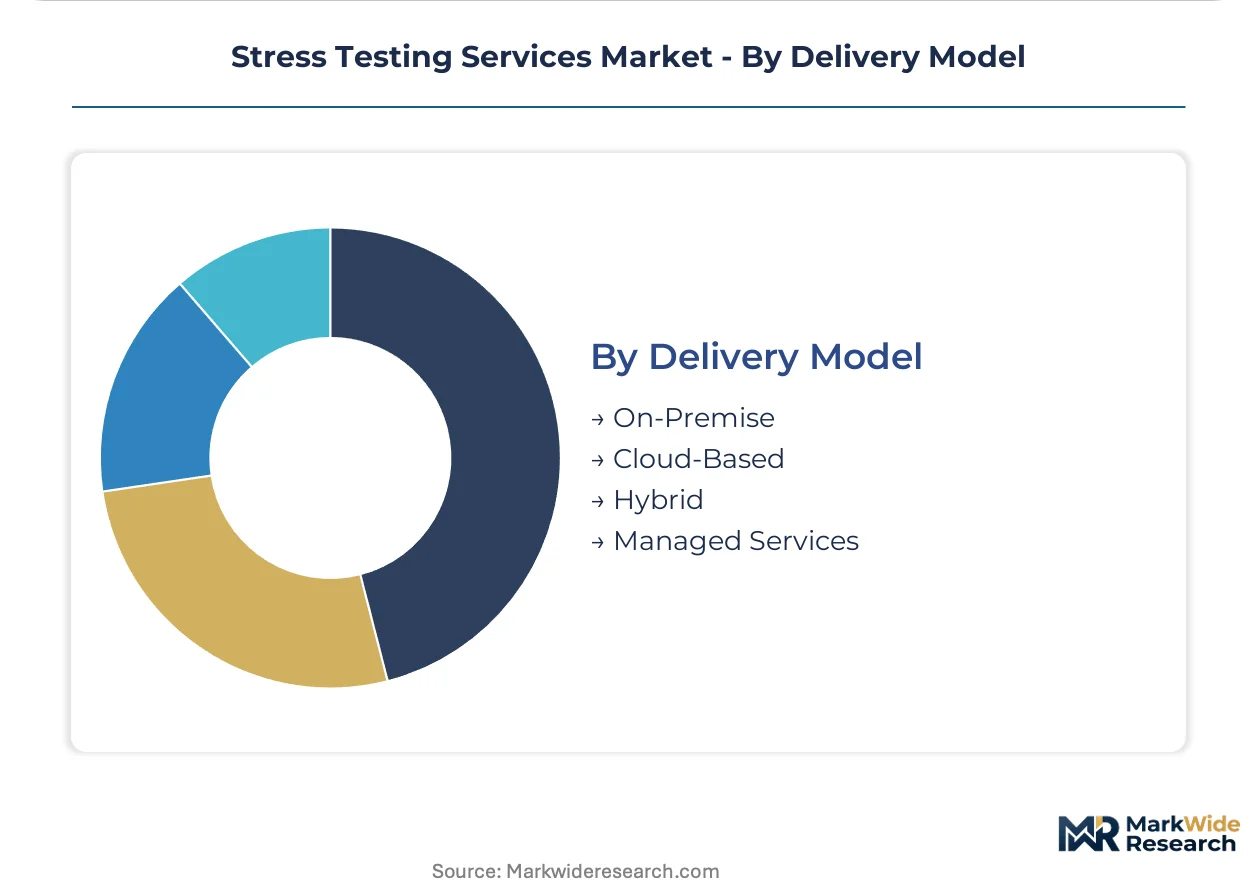
- Cloud-Based:Elastic compute provisioning for Monte Carlo simulation grids without hardware depreciation or data center overhead. United Kingdom mid-tier investment firms are standardizing on containerized deployment frameworks to compress scenario execution windows. Pay-per-simulation pricing lowers barriers for firms below CCAR threshold assets.
- Hybrid:Split architectures retaining sensitive data on-premise while bursting compute-intensive simulations to cloud nodes. Tier-one banks with legacy core systems sustain this model to satisfy data residency requirements. Margin premiums persist where sovereign cloud instances are mandated.
- On-Premise:Dedicated high-performance analytics grids for institutions with strict data sovereignty or latency requirements.
- Managed Services:Fully outsourced stress testing operations including scenario design, model execution, and regulatory submission preparation.
Hybrid deployments retain the largest committed expenditure base; Cloud-Based is accelerating most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States banks concentrate the largest procurement budgets for stress testing services as Federal Reserve CCAR mandates compress compliance timelines. United Kingdom institutions are accelerating cloud migration to modernize legacy risk infrastructure. Continental European carriers are licensing specialized scenario libraries to satisfy emerging climate risk requirements.
United States
New York-based universal banks are expanding model risk management teams to handle dynamic scenario modeling at 99.9 percent confidence intervals. The Federal Reserve's CCAR submission cycles eliminate price elasticity among tier-one institutions. Chicago and Charlotte regional banking clusters are adopting hybrid cloud architectures to satisfy data sovereignty while bursting compute-intensive simulations.
United Kingdom
London mid-tier investment firms are standardizing on containerized deployment frameworks to access Monte Carlo capacity without captive infrastructure. The Bank of England's divergent scenario design calendar fragments platform standardization efforts with transatlantic counterparts. The City of London risk infrastructure modernization wave is driving disproportionate cloud-based delivery model adoption.
Germany
Frankfurt-based universal banks are recalibrating risk-weighted asset engines to accommodate Basel III endgame revisions. The European Central Bank's climate risk stress testing mandates are embedding environmental transition scenarios into prudential frameworks. Bavarian insurance carriers are licensing specialized longevity and catastrophe scenario libraries rather than building internal econometric capabilities.
France
Parisian banking groups are maintaining parallel scenario engines to satisfy disclosure granularity rules that diverge from UK and US standards. The Autorité de Contrôle Prudentiel et de Résolution examines model validation documentation with increasing frequency. Île-de-France institutions are importing bank-grade stress testing frameworks previously concentrated among Anglo-Saxon peers.
Switzerland
Zurich private banks and asset managers are adopting tail-risk quantification methodologies for limited partner reporting beyond regulatory minimums. Swiss FINMA requirements around operational resilience validation are expanding service scopes for domestic providers. Geneva wealth management clusters are purchasing standalone model validation services separate from bundled consulting packages.
Stress Testing Services Market Competitive Landscape
United States technology conglomerates anchor one tier; European specialized analytics firms hold differentiated positions in scenario library depth. The vendor base separates into consolidated platform providers with mainframe migration capabilities and niche quantitative specialists with agent-based modeling expertise. Three strategic archetypes dominate: full-stack technology vendors, risk analytics pure-plays, and managed service operators. Competitive moves concentrate on strategic partnerships for cloud elasticity and portfolio diversification into operational continuity services.
Within the full-stack tier, IBM Corporation represents legacy infrastructure incumbents navigating institutional clients through compressed compliance timelines. Moody's Analytics occupies a position exemplifying scenario library depth across macroeconomic shocks and idiosyncratic risk factors. SAS Institute Inc. anchors the high-performance analytics grid segment among North American banks with strict data sovereignty requirements.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| SAS Institute Inc. |
| FIS |
| Moody's Analytics |
| Murex S.A.S. |
| TIBCO Software Inc. |
| Others |
Value Network & Pricing Analysis
The European Central Bank's climate risk stress testing mandates gate qualified supply for scenario library providers and anchor premium-tier pricing access for vendors with validated environmental transition models. Institutions lacking certified climate-econometric capabilities face exclusion from continental European procurement cycles while commanding lower price realization.
Pricing Analysis
Short lead-time premiums apply to Monte Carlo simulation capacity during Federal Reserve CCAR submission windows, while spot inventory of pre-built scenario libraries trades at discounted rates during off-cycle periods. Three-tier pricing structure across premium, standard, and economy levels separates validated regulatory submission packages from self-service cloud compute and basic documentation templates. Price differentiation rests on certification depth and geographic data residency compliance. Cost compression in the mid-tier is intensifying because containerized deployment frameworks commoditize elastic compute. Regional banks below CCAR asset thresholds exhibit highest price sensitivity; tier-one universal banks with mandatory submission obligations show least elasticity.
Supply Chain Analysis
Dual-sourcing requirements from tier-one banks mandate multi-supplier qualification for both scenario library content and computational infrastructure to mitigate model risk concentration. Supply concentrates in the United States for high-performance analytics grids, the United Kingdom for cloud-native deployment frameworks, and Germany for climate-econometric modeling capabilities. Raw material dependencies include graphical processing units from Taiwan, specialized quantitative talent from Anglo-Saxon academic pipelines, and regulatory scenario templates from ECB and Federal Reserve publications. Single-source vulnerability persists where agent-based model expertise concentrates among incumbent vendors. Distribution runs through direct enterprise sales for on-premise installations and hyperscaler marketplaces for cloud-based consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stress testing services market sits in a technology-transition phase as cloud-native Monte Carlo architectures displace legacy mainframe-dependent computational workflows. Containerized deployment frameworks are compressing infrastructure accessibility barriers that previously segmented vendor tiers.
For Market Incumbents: Anchor institutional relationships through mainframe-to-cloud migration suites that capture compressed Federal Reserve compliance timelines. Defend scenario library intellectual property through exclusive licensing arrangements with European regulators embedding climate risk modules. Capacity addition in sovereign cloud instances for tier-one banks with data residency requirements protects margin premiums against commodity compute erosion.
For New Entrants and Emerging Players: The European Central Bank's climate risk stress testing mandates in Continental Europe opens a window for specialized environmental transition scenario providers lacking legacy infrastructure baggage. White-space targets include mid-tier investment firms in London bypassing capital expenditure through pay-per-simulation pricing and Bavarian insurance carriers licensing longevity and catastrophe models. The most penetrable segment comprises alternative investment firms modernizing legacy risk infrastructure with unbundled model validation services.
For Investors and Strategic Acquirers: Tier-one bank procurement committee approval of cloud-native stress testing platforms is the leading indicator that infrastructure transition budgets are unlocking at scale. Long-term viability favors vendors with defensible scenario library depth rather than commodity compute providers. Acquisition target archetype includes niche quantitative specialists with agent-based modeling expertise and validated regulatory relationships. The signal to monitor is vendor consolidation among scenario library providers as institutions prefer licensing over internal build decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Scenario Library Licensing Agreement | Deep macroeconomic shock repositories represent defensible IP assets that institutions license rather than build internally. |
| Mainframe-to-Cloud Migration Service | Technology vendors capture institutional clients navigating compressed Federal Reserve CCAR compliance timelines. |
| Climate Risk Module Development | European Central Bank mandates embed environmental transition scenarios into prudential frameworks across Continental Europe. |
| GPU-Accelerated Compute Partnership | Graphical processing unit vendors enable elastic scenario computation for tier-two investment firms at accelerated procurement cycles. |
| Operational Continuity Service Extension | Stress testing providers expand beyond capital adequacy into operational resilience validation as supervisory frameworks broaden scope. |
Research Methodology
Document review covered Federal Reserve CCAR submission guidelines, European Central Bank stress testing methodologies, Basel Committee regulatory texts, and vendor SEC filings, complemented by interviews with chief risk officers at universal banks, model risk management directors at regional banks, quantitative analysts at investment firms, procurement leads at insurance carriers, and cloud infrastructure specialists at technology providers. Secondary validation drew from regulatory disclosure databases, supervisory examination reports, and industry association publications. Bottom-up service revenue estimates triangulated against top-down market sizing across delivery models.
Cross-referencing historical procurement patterns with panel input from risk technology buyers anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type, customer sophistication tier, industry vertical, and deployment architecture. CAGRs were derived from regression analysis of expenditure trajectories against regulatory timeline intensity. Industry-specific forecast inputs incorporated CCAR submission cycle frequency and climate risk mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for mainframe persistence would alter the outlook if data sovereignty requirements harden beyond current baselines. Forecasts reflect assumptions around supervisory convergence versus fragmentation in transatlantic regulatory dialogue. A model refresh is warranted upon material change in Federal Reserve scenario design timelines or Basel III endgame implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market