
 Gene Editing Technology Market | 2026-2036
Gene Editing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Editing Technology Market Foresight
Academic laboratories is collapsing as contract research organizations capture larger procurement volumes in gene editing services. Thermo Fisher Scientific leverages its reagent and instrument portfolio to anchor upstream workflow control. Lonza sustains manufacturing scale advantages in viral vector and electroporation-based cell engineering. CRISPR Therapeutics differentiates through therapeutic specialization, competing directly with Editas Medicine in immuno-oncology and rare disease pipelines.
Gene editing technology encompasses programmable nuclease systems, including CRISPR-Cas9, TALEN, and base editing platforms, that introduce site-specific DNA modifications through guided RNA-DNA recognition and double-strand break repair mechanisms. These systems enable precise genomic alterations for therapeutic correction, trait enhancement, and microbial strain optimization across pharmaceutical, agricultural, and industrial applications. CRISPR-Cas9 dominates technology adoption due to its design simplicity and multiplexing capacity, while base editing gains traction where double-strand break avoidance preserves cell viability. Therapeutic development anchors application-level revenue, though agricultural improvement accelerates as seed companies integrate gene editing into varietal development pipelines.
FDA oversight of gene therapy investigational new drug applications shapes clinical trial design and manufacturing quality standards in the United States, while EMA's advanced therapy medicinal products framework governs European market authorization pathways. China's NMPA has issued technical guidelines for gene editing therapeutics that accelerate domestic biotech filing timelines. Stakeholders must monitor regulatory divergence between jurisdictions to align platform development with divergent evidentiary requirements for safety and efficacy.
Market Dynamics
Contract research organizations are consolidating gene editing procurement away from academic laboratories, redirecting platform development toward standardized, scalable service models that prioritize regulatory compliance and manufacturing repeatability over exploratory research flexibility.
Growth Catalysts
- Advanced Therapy Medicinal Products framework:EMA's centralized approval pathway accelerates European market entry for CRISPR-based therapeutics, reducing regulatory fragmentation across member states.
- Immuno-oncology pipelines:CAR-T and TCR-T cell engineering programs drive sustained demand for electroporation and viral vector manufacturing capacity.
- Shenzhen biotech cluster:Concentrated venture capital deployment and NMPA guideline alignment attract platform companies seeking accelerated domestic filing timelines.
Market Restraints
- GMP-grade reagent supply concentration:Limited qualified suppliers for clinical-grade Cas9 proteins and guide RNA create input bottlenecks and price volatility.
- Off-target mutagenesis liability:Persistent technical limitations in predictive fidelity models constrain therapeutic applications where safety margins are narrow.
- Dual-use export controls:Cross-border restrictions on gene editing tools and know-how fragment collaborative research and technology transfer.
Strategic Opportunities
- Brazilian agricultural biotechnology:Underpenetrated seed editing market offers expansion potential as CTNBio establishes streamlined trait approval pathways for non-transgenic varieties.
- Base editing-CRISPR convergence:Integration of cytosine and adenine base editors with prime editing platforms enables precise correction without double-strand breaks.
- Japan's regenerative medicine sandbox:PMDA's conditional early approval framework creates regulatory tailwind for in vivo gene editing therapeutics targeting rare diseases.
Industry Challenges
- Cell engineering workforce scarcity:Shortage of GMP-compliant process development scientists constrains manufacturing scale-up timelines.
- IND-enabling study complexity:Extended pharmacology and toxicology requirements for novel delivery modalities delay clinical trial initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Editing Technology Market |
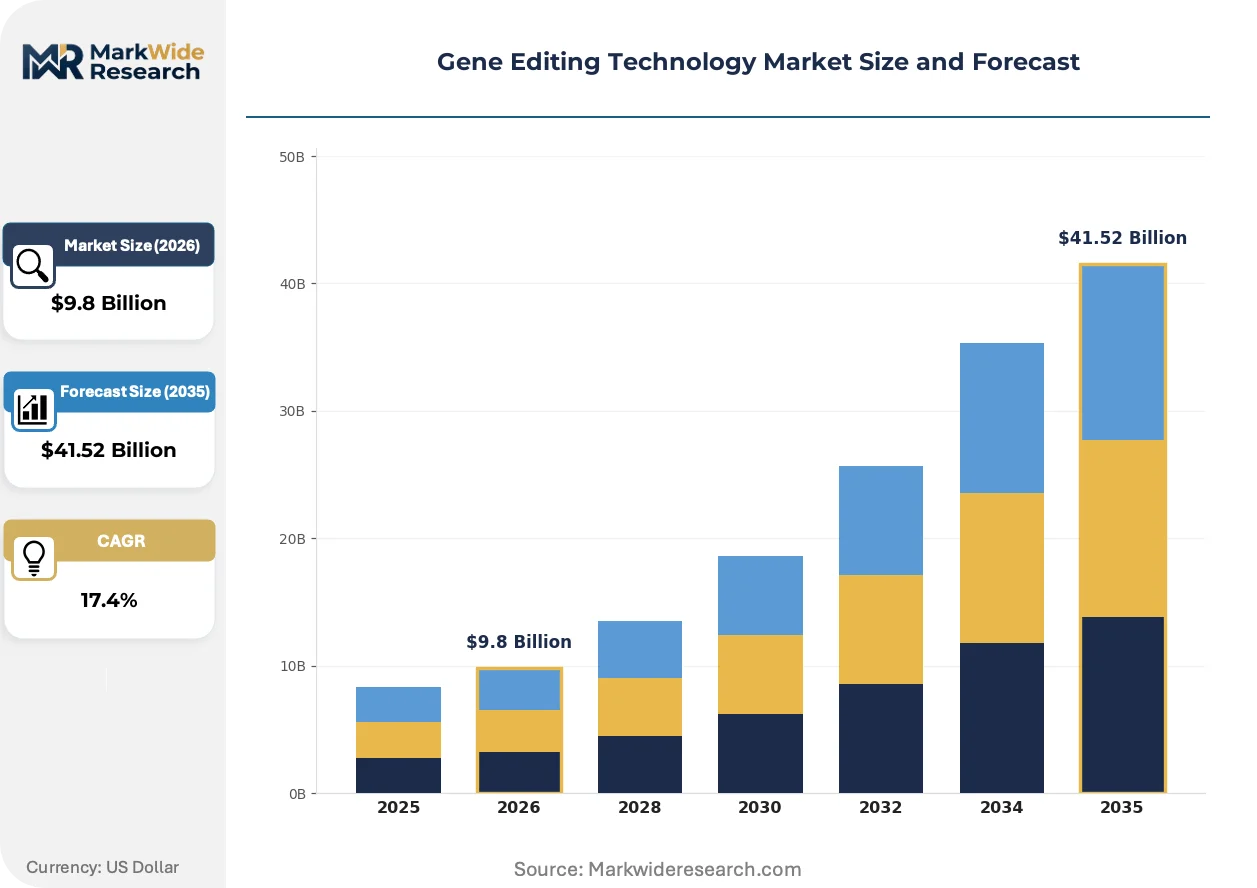
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $41.52 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CRISPR-Cas9, TALEN, ZFN, MegaTAL, ARCUS, Base Editing Application: Therapeutic Development, Agricultural Improvement, Industrial Biotechnology, Synthetic Biology, Animal Genetics, Environmental Management End User: Biopharmaceutical Companies, Agricultural Firms, Research Institutes, Biotech Startups, Contract Research Organizations, Academic Laboratories Delivery Mode: Viral Vector, Electroporation, Microinjection, Lipid Nanoparticles, Physical Injection, Cell-Penetrating Peptides |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, CRISPR Therapeutics, Intellia Therapeutics, Editas Medicine, Lonza, GenScript, Beam Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Editing Technology Market Shifts & Advancements
Gene editing platforms are converging with automated liquid handling and AI-guided guide RNA design, compressing development timelines while raising the technical bar for competitive differentiation.
Prime editing systems are displacing conventional CRISPR-Cas9 in precision medicine applications where double-strand break avoidance preserves genomic stability. Biopharmaceutical process development groups are adopting prime editors for therapeutic correction of point mutations at accelerating pace. This transition is displacing first-generation nuclease platforms from orphan disease pipelines and forcing reagent suppliers to reconfigure manufacturing priorities.
REACH registration requirements for novel synthetic guide RNA chemistries are tightening supply chain documentation standards across European manufacturing networks. Industrial consequence includes mandatory substance volume tracking and extended safety data sets for imported reagents. Contract manufacturers serving EMA-bound therapeutics are responding by qualifying domestic oligonucleotide synthesis partners.
Biopharma procurement teams are consolidating vendor relationships around integrated workflow providers that bundle instruments, reagents, and regulatory support. Academic core facilities and emerging biotechs are the segments most disrupted, shifting from à la carte purchasing to multi-year platform agreements. This pattern is most visible in the United States, where NIH funding pressures and venture-backed startup density accelerate buying rationalization.
Gene Editing Technology Market Segmentation
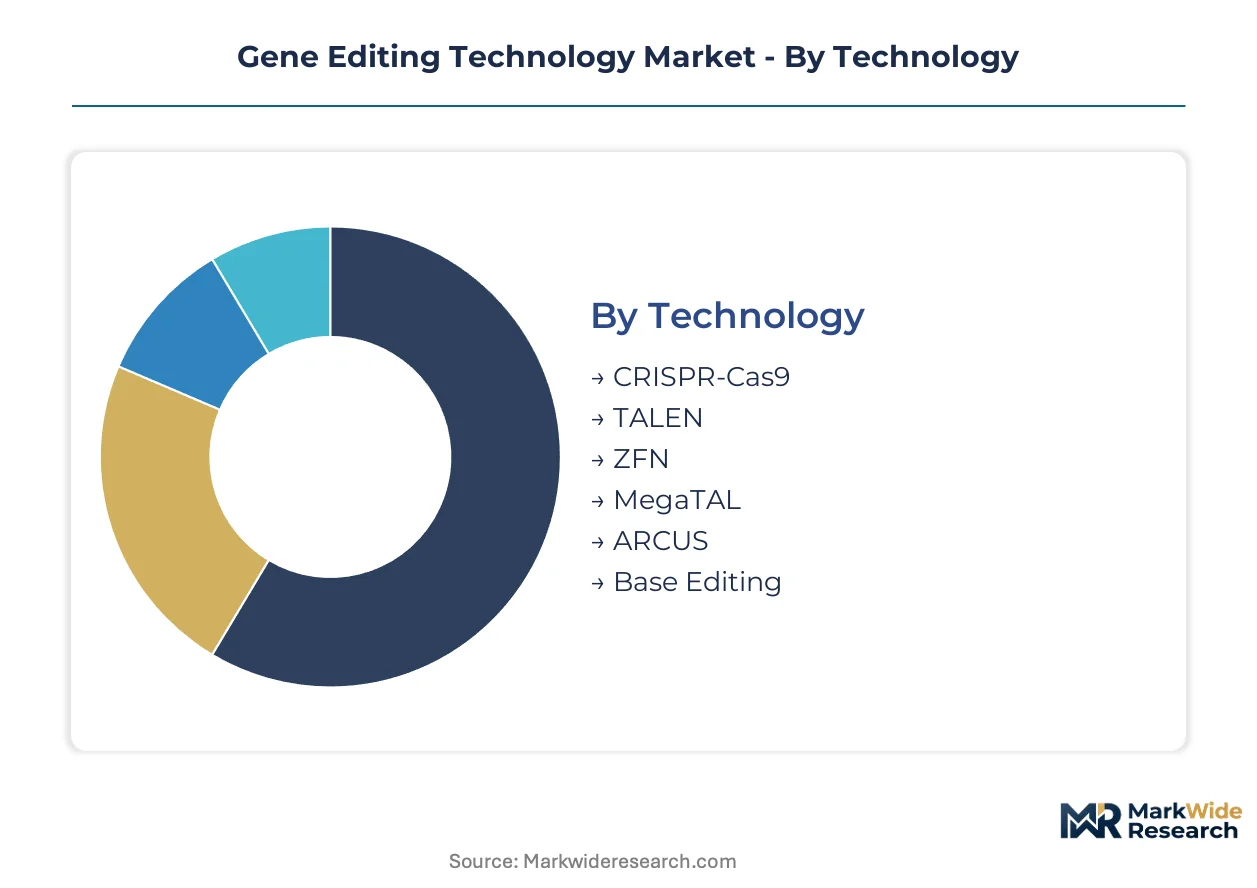
Segmentation in gene editing technology reveals distinct procurement patterns across therapeutic, agricultural, and industrial domains. Technology choice determines regulatory pathway complexity and manufacturing scale requirements. Delivery mode selection directly constrains which cell types and tissues remain addressable for each application.
Technology:
CRISPR-Cas9 dominates domestic R&D procurement across the United States, China, and European research clusters, while TALEN and base editing platforms concentrate in export-oriented therapeutic manufacturing.
- CRISPR-Cas9:Programmable dual-RNA-guided nuclease system enabling multiplexed genomic editing through double-strand break induction. Demand concentrates in United States biotech corridors and Shenzhen manufacturing zones, driven by FDA and NMPA framework maturation for investigational gene therapies.
- Base Editing:Cytosine and adenine deaminase fusions enabling C-to-T or A-to-G transitions without double-strand breaks. Japanese and European biopharmaceutical pipelines prioritize this platform for point mutation correction where cell viability preservation determines therapeutic index.
- TALEN:Transcription activator-like effector nucleases offering reduced off-target profiles for agricultural trait engineering.
- ZFN:Zinc finger nuclease platforms retaining niche presence in legacy therapeutic programs and industrial strain optimization.
- MegaTAL:Hybrid meganuclease-TALEN architecture for large gene insertion applications in cell therapy manufacturing.
- ARCUS:Precision biosciences-derived homing endonuclease platform for allogeneic CAR-T development.
CRISPR-Cas9 commands the established base. The steepest expansion runs through base editing platforms.
Application:
Cost tier stratification separates high-investment therapeutic development from margin-compressed agricultural improvement programs.
- Therapeutic Development:In vivo and ex vivo gene correction for monogenic diseases, oncology immunotherapy, and regenerative medicine. United States and European biopharmaceutical companies drive procurement through centralized GMP manufacturing networks requiring EMA and FDA quality alignment.
- Agricultural Improvement:Crop trait enhancement for yield, disease resistance, and climate adaptation. Brazilian and Argentine seed markets accelerate adoption as CTNBio streamlines non-transgenic variety approval pathways.
- Industrial Biotechnology:Microbial strain engineering for enzyme production, biofuel synthesis, and pharmaceutical precursor manufacturing.
- Synthetic Biology:Metabolic pathway construction and genetic circuit design for specialty chemical production.
- Animal Genetics:Livestock breeding improvement and disease resistance trait introduction.
- Environmental Management:Bioremediation organism development and invasive species control applications.
Therapeutic development absorbs the highest absolute investment. Agricultural improvement is climbing the fastest as regulatory barriers fall in major grain-producing economies.
End User:
Customer type determines procurement sophistication, with contract research organizations consolidating volumes previously fragmented across academic laboratories.
- Biopharmaceutical Companies:Integrated therapeutic developers with captive process development and GMP manufacturing capabilities. United States and Swiss headquarters locations concentrate decision-making for global platform selection.
- Contract Research Organizations:Scaled service providers capturing standardized editing workflows from fragmented academic procurement. Lonza and Thermo Fisher manufacturing networks in Singapore, Switzerland, and Maryland anchor this segment's supply concentration.
- Biotech Startups:Venture-funded platform companies prioritizing speed-to-IND over manufacturing ownership.
- Agricultural Firms:Seed and trait developers integrating editing into varietal pipelines.
- Research Institutes:NIH, Max Planck, and Chinese Academy of Sciences facilities maintaining exploratory editing programs.
- Academic Laboratories:Individual investigator-led projects facing funding pressure and core facility consolidation.
Biopharmaceutical companies command the established base. Contract research organizations are gaining share fastest through procurement rationalization.
Delivery Mode:
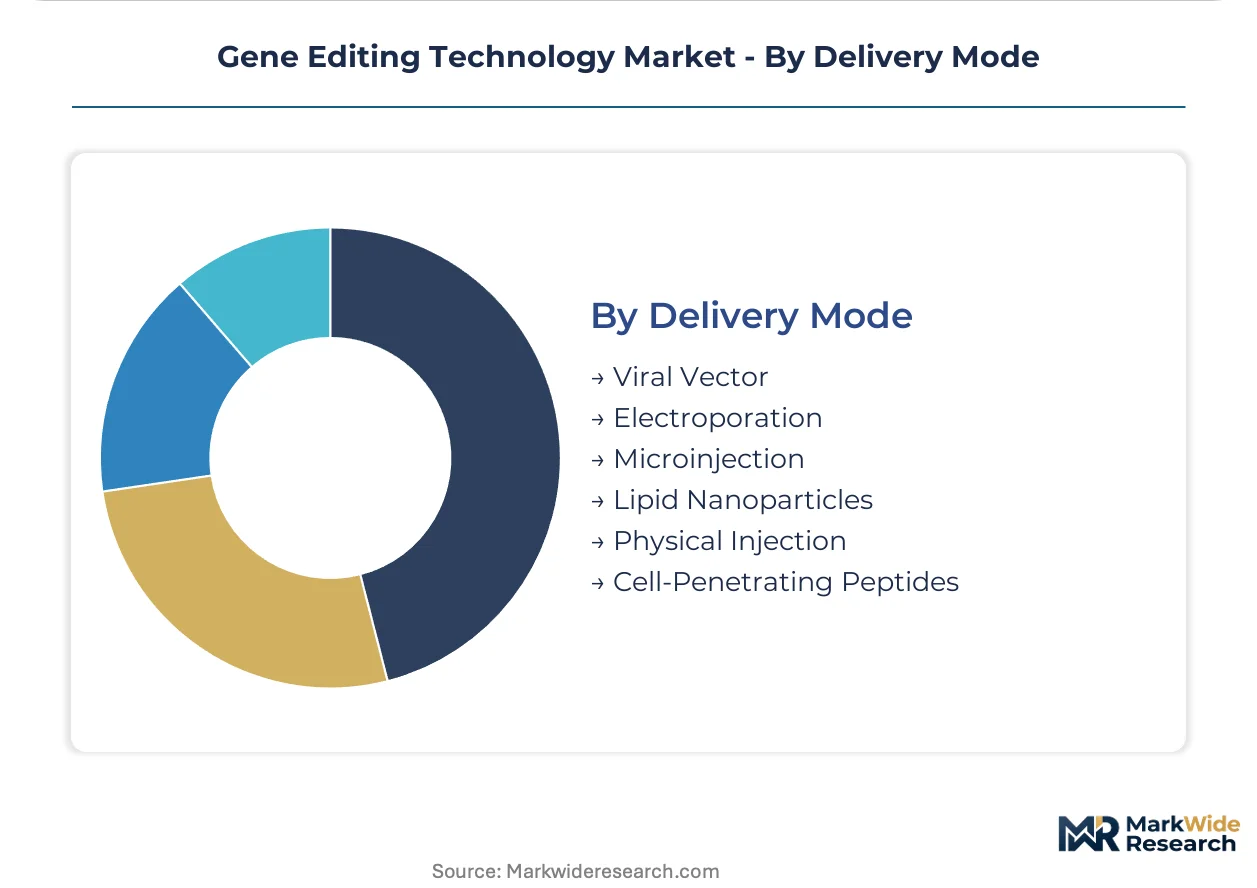
Supply concentration in viral vector manufacturing creates margin tiering between electroporation-based cell engineering and lipid nanoparticle in vivo approaches.
- Viral Vector:Adeno-associated and lentiviral particle-mediated delivery for ex vivo cell modification and direct in vivo administration. United States and European manufacturing networks face capacity constraints as immuno-oncology pipelines expand.
- Electroporation:Electrical pulse-mediated membrane permeabilization for ribonucleoprotein complex delivery to primary cells. Singapore and Maryland manufacturing hubs scale this modality for allogeneic cell therapy production.
- Lipid Nanoparticles:mRNA and guide RNA encapsulation for hepatic and splenic targeting in vivo.
- Microinjection:Physical DNA/protein delivery for embryo editing in agricultural and animal genetics applications.
- Physical Injection:Direct tissue administration of editing reagents for accessible anatomical sites.
- Cell-Penetrating Peptides:Protein transduction domain fusion for non-viral cargo delivery across membrane barriers.
Viral vector platforms command the established base. Electroporation is expanding most quickly as allogeneic cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reagent manufacturing and GMP-grade viral vector production concentrate in the United States, Switzerland, and Singapore, creating input dependencies for therapeutic developers across secondary markets. Platform commercialization follows venture capital density and regulatory pathway clarity.
United States
FDA's evolving gene therapy guidance and Breakthrough Therapy designation attract CRISPR-based therapeutic developers to the Boston-Cambridge and San Francisco Bay corridors. NIH funding compression redirects academic procurement toward core facility consolidation. Maryland and North Carolina manufacturing hubs scale electroporation capacity for allogeneic cell therapy production.
Switzerland
Swissmedic's alignment with EMA centralized procedures positions Basel and Zurich as European GMP manufacturing anchors for viral vector and cell engineering workflows. Lonza's manufacturing networks concentrate process development talent in the Lake Geneva region. Swiss biopharmaceutical headquarters locations drive global platform selection decisions.
China
NMPA technical guidelines for gene editing therapeutics accelerate domestic filing timelines in the Shenzhen and Shanghai biotech clusters. Venture capital deployment concentrates in the Greater Bay Area, attracting platform companies seeking conditional approval pathways. Beijing-Tianjin research institutes maintain exploratory editing programs alongside commercial translation.
Japan
PMDA's regenerative medicine sandbox creates regulatory tailwind for in vivo gene editing therapeutics targeting rare diseases, with Kanto region biopharmaceutical developers prioritizing base editing platforms. Osaka-based manufacturing networks specialize in point mutation correction workflows. METI funding programs support prime editing technology adoption.
Germany
REACH registration requirements for novel synthetic guide RNA chemistries tighten supply chain documentation standards across European manufacturing networks. EMA's Advanced Therapy Medicinal Products framework governs market authorization for Munich and Heidelberg therapeutic developers. German chemical synthesis capabilities anchor oligonucleotide reagent qualification programs.
Gene Editing Technology Market Competitive Landscape
Concentration sits with diversified life science conglomerates controlling upstream reagent and instrument workflows. The vendor base stratifies between integrated platform providers and therapeutic-specialized developers. Three archetypes dominate: workflow-integrated conglomerates, manufacturing-scale service organizations, and clinical-stage therapeutic developers. Competitive moves center on manufacturing capacity expansion and regulatory compliance certification rather than price-based rivalry.
Within the therapeutic developer tier, CRISPR Therapeutics, Editas Medicine, and Intellia Therapeutics exemplify clinical-stage specialization competing directly in immuno-oncology and rare disease pipelines. Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions anchoring reagent and instrument procurement rationalization. Lonza represents the manufacturing-scale archetype sustaining viral vector and electroporation-based cell engineering advantages.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Agilent Technologies |
| CRISPR Therapeutics |
| Intellia Therapeutics |
| Editas Medicine |
| Lonza |
| GenScript |
| Beam Therapeutics |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for GMP-grade Cas9 proteins concentrate pricing power with qualified suppliers in Switzerland and Maryland, compressing margins for downstream contract manufacturers while amplifying procurement leverage for biopharmaceutical companies with multi-year platform agreements.
Pricing Analysis
REACH registration requirements for novel synthetic guide RNA chemistries dictate the pricing tier structure across European manufacturing networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified clinical-grade reagents from research-use-only and custom-synthesis tiers. Cost compression in the research-use segment is intensifying because academic funding pressures redirect procurement toward core facility consolidation. Contract research organizations exhibit the highest price sensitivity due to volume consolidation, while biopharmaceutical companies with captive GMP capabilities show relative inelasticity.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes amplify inbound logistics costs for oligonucleotide synthesis feedstocks sourced from Asian chemical manufacturers. Supply concentration rests on the United States, Switzerland, and Singapore for specialized reagent manufacturing and viral vector production. Raw material dependencies include synthetic guide RNA chemistries, recombinant Cas9 proteins, and lipid nanoparticle formulations. Single-source vulnerability characterizes qualified GMP-grade reagent suppliers, constraining manufacturing scale-up timelines. Distribution runs through integrated workflow providers bundling instruments, reagents, and regulatory support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as contract research organizations consolidate procurement volumes previously fragmented across academic laboratories, shifting negotiation leverage toward scaled service providers with multi-year platform agreements.
For Market Incumbents: Consolidate manufacturing scale advantages in viral vector and electroporation-based cell engineering through capacity expansion in Singapore and Maryland hubs. Deepen upstream control over GMP-grade reagent supply by qualifying captive oligonucleotide synthesis partners. Threat from base editing platform displacement demands accelerated prime editing technology adoption to defend therapeutic pipeline relevance. For New Entrants and Emerging Players: Differentiate on regulatory compliance velocity by targeting the Brazilian agricultural biotechnology segment where CTNBio streamlines non-transgenic variety approval pathways. White-space opportunities concentrate in base editing-CRISPR convergence for point mutation correction and Japan's regenerative medicine sandbox for in vivo therapeutics. Go-to-market angle should emphasize conditional early approval framework navigation. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capacity play because therapeutic pipeline expansion outpaces GMP-compliant process development scientist supply. Acquisition target archetype: mid-scale electroporation-focused contract manufacturers with EMA and FDA quality alignment. Signal to watch is viral vector manufacturing capacity utilization rates as immuno-oncology pipelines mature.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands electroporation capacity in Maryland and Singapore to serve allogeneic cell therapy demand. |
| Regulatory Approval Pathway | Navigates PMDA's regenerative medicine sandbox for accelerated rare disease therapeutic entry. |
| Backward Integration | Captures in-house production of synthetic guide RNA chemistries to mitigate REACH documentation burdens. |
| Pipeline Diversification | Integrates base editing platforms to displace first-generation nucleases from orphan disease programs. |
| Strategic Partnership | Aligns with Shenzhen biotech clusters to leverage NMPA guideline acceleration for domestic filing timelines. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with gene therapy development executives, regulatory affairs leads at EMA-bound biopharmaceuticals, GMP manufacturing scientists, and venture capital investors specializing in platform biotechnology informed demand-side dynamics. Secondary validation drew from FDA gene therapy guidance documents, EMA Advanced Therapy Medicinal Products framework publications, NMPA technical guidelines, ClinicalTrials.gov protocol registrations, and NIH funding disbursement records. Bottom-up therapeutic pipeline analysis and top-down venture capital deployment tracking provided triangulation.
Sensitivity analysis around regulatory pathway timelines and manufacturing capacity expansion schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology platform, application domain, end-user archetype, and delivery modality. CAGRs were derived from therapeutic pipeline advancement rates, agricultural trait approval velocity, and reagent procurement volume trajectories. Industry-specific inputs incorporated IND filing momentum, GMP facility commissioning timelines, and seed company R&D budget allocations.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA frameworks; material policy shifts would require re-modeling. Specific risk factors include off-target mutagenesis liability constraining therapeutic applications, dual-use export controls fragmenting collaborative research, and cell engineering workforce scarcity delaying manufacturing scale-up. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market