
 US Gene Editing Market | 2026-2036
US Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
US Gene Editing Market Insights
Capital-intensity divergence between platform developers and tool suppliers is rotating competitive advantage toward integrated end-to-end providers. Thermo Fisher Scientific leverages its reagent manufacturing scale to dominate consumables supply for academic and contract research laboratories. Beam Therapeutics differentiates through base-editing chemistry that reduces off-target liability in therapeutic programs. Editas Medicine anchors its position in ocular and ex vivo hematopoietic indications with proprietary delivery formulations.
Gene editing encompasses programmable nuclease systems that introduce site-specific DNA modifications through directed double-strand breaks or base conversions, with CRISPR-Cas9 complexes requiring guide RNA design within 20-nucleotide specificity windows to achieve target recognition. The technology serves therapeutic development, agricultural trait engineering, and fundamental biological discovery across industrial and academic settings. CRISPR product lines command the largest revenue share due to licensing accessibility and protocol standardization, while TALEN systems retain structural importance in therapeutic contexts requiring reduced off-target profiles. Application demand concentrates in oncology and rare diseases where unmet medical need justifies premium development costs and accelerated regulatory pathways.
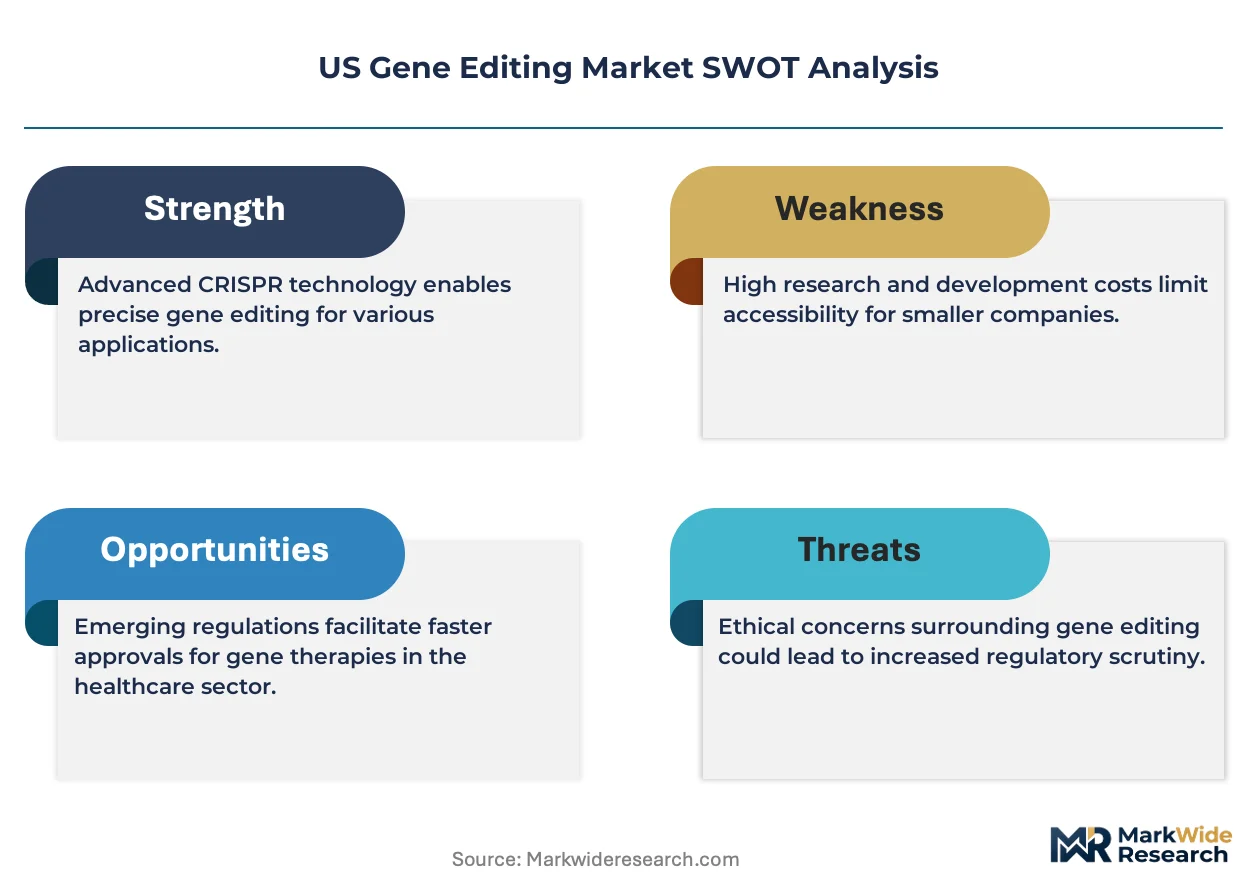
FDA oversight through the Office of Tissues and Advanced Therapies shapes IND requirements and long-term follow-up protocols for gene-edited therapeutics, while NIH guidelines on recombinant DNA research govern institutional biosafety containment levels for academic investigators. The IRA's Medicare price negotiation provisions constrain revenue assumptions for approved gene therapies, altering capital allocation toward earlier-stage platform investments. Stakeholders must monitor evolving FDA guidance on genome editing CMC expectations and state-level germline editing prohibitions that could reshape permissible research boundaries.
Market Dynamics
The IRA's Medicare price negotiation provisions are compressing revenue timelines for approved gene therapies, forcing developers to accelerate platform monetization strategies and redirect capital toward earlier-stage discovery engines rather than late-stage clinical assets.
Growth Catalysts
- Oncology therapeutic pipelines:Pharmaceutical sponsors are expanding investment in CAR-T and TCR-engineered cell therapies, drawn by accelerated FDA approval pathways for breakthrough-designated oncology products.
- NIH recombinant DNA guidelines:Institutional biosafety framework updates are streamlining containment-level determinations for academic CRISPR research, reducing protocol approval timelines at major research universities.
- Massachusetts and California demand clusters:Concentrated venture deployment in Boston-Cambridge and San Francisco-San Diego corridors is creating dense supplier ecosystems and specialized talent pools for gene editing operations.
Market Restraints
- Guide RNA synthesis cost volatility:Oligonucleotide manufacturing capacity constraints and raw nucleotide supply fluctuations are elevating input costs for CRISPR reagent production.
- Single-source supplier concentration:Critical viral vector manufacturing for therapeutic delivery remains dependent on a limited network of contract development organizations, creating capacity bottlenecks for IND-enabling studies.
- Off-target liability ceiling:Double-strand break repair mechanisms introduce chromosomal translocation risks that limit therapeutic index in indications requiring high editing efficiency.
Strategic Opportunities
- Ex vivo hematopoietic applications:Autologous cell therapy manufacturing models are opening addressable markets in sickle cell disease and beta-thalassemia where allogeneic approaches face immune barriers.
- Base-editing chemistry convergence:Cytosine and adenine base editors are enabling precise point mutations without double-strand breaks, expanding targetable disease alleles previously inaccessible to nuclease platforms.
- State-level research incentives:California's stem cell research funding agency and Massachusetts life sciences tax credits are subsidizing preclinical development infrastructure for platform companies.
Industry Challenges
- Cell therapy manufacturing talent scarcity:Shortages of process development scientists with viral vector and cell culture expertise are extending CMC timeline execution.
- FDA CMC documentation burden:Evolving chemistry, manufacturing, and controls expectations for gene-edited products are requiring iterative IND amendments and extended regulatory dialogue.
- Guide RNA IP licensing complexity:Fragmented patent estates covering CRISPR-Cas9 delivery methods and guide design algorithms are creating royalty stacking and freedom-to-operate uncertainties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Gene Editing Market |
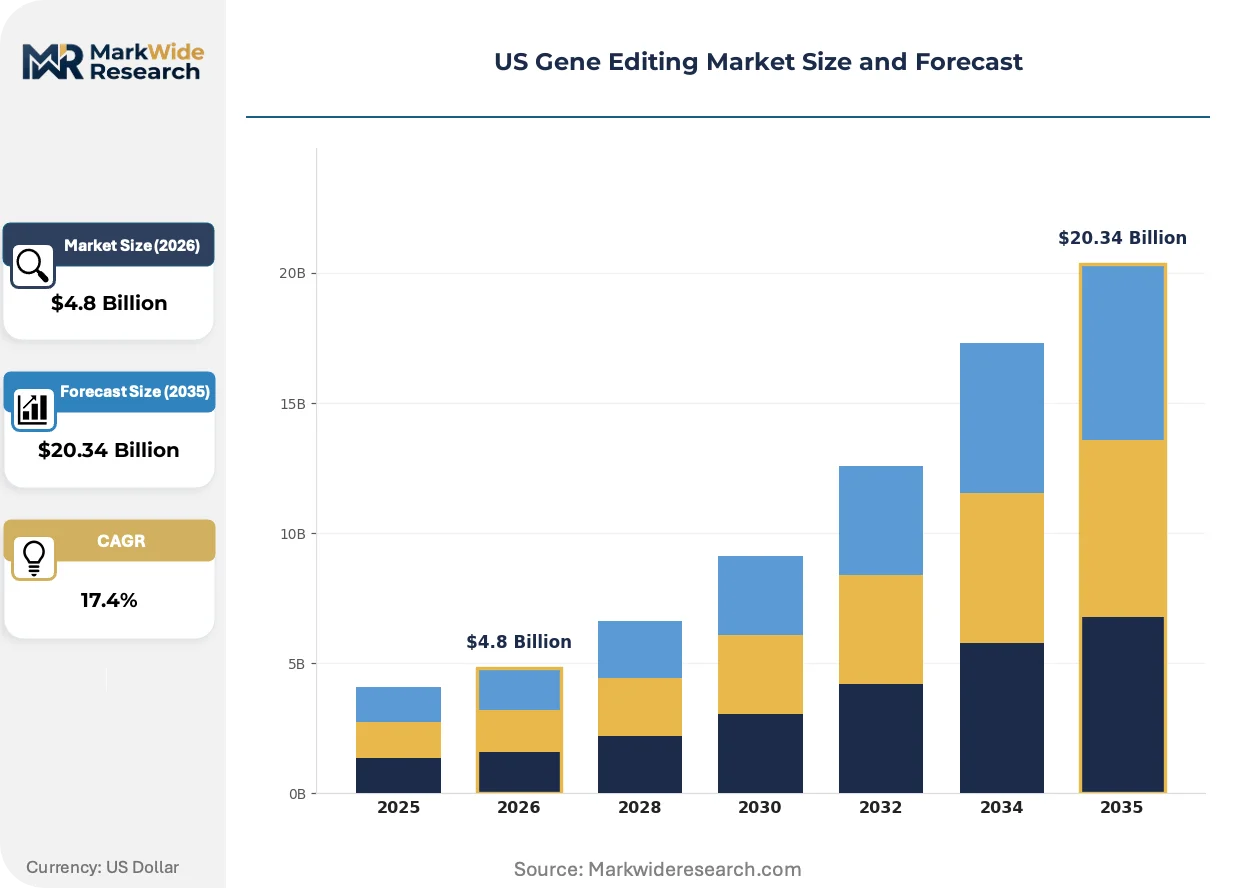
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.34 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, TALEN, ZFN, Ribonucleoprotein Application: Oncology, Rare Diseases, Genetic Disorders, Therapeutics End User: Academic Research, Pharmaceutical Companies, Biotech Firms, Contract Research Organizations Technology: Gene Synthesis, Sequencing, Delivery Systems, Editing Tools |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, GenScript, Intellia Therapeutics, Beam Therapeutics, Editas Medicine, Synthego, CRISPR Therapeutics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Gene Editing Market Trends and Innovations
Base-editing and prime-editing platforms are displacing first-generation nuclease systems across therapeutic pipelines, while FDA guidance evolution and sponsor procurement model changes are restructuring competitive economics.
Prime-editing technology is displacing conventional CRISPR-Cas9 in precision medicine applications requiring single-nucleotide corrections without double-strand breaks. Large pharmaceutical sponsors are integrating prime editors into discovery workflows at accelerating pace. The technology is displacing homology-directed repair dependency, enabling editing in non-dividing cell types previously resistant to correction.
FDA guidance on long-term follow-up protocols for gene-edited therapeutics is extending post-marketing surveillance obligations to 15-year horizons. The policy is elevating pharmacovigilance infrastructure costs and favoring sponsors with established rare disease patient registries. Oncology indications face the steepest compliance burden, with sponsors in Massachusetts and California corridors investing in dedicated real-world evidence platforms.
Biopharma procurement patterns are consolidating reagent supply relationships around integrated platform providers capable of guide RNA design, synthesis, and analytical validation. Academic core facilities and contract research organizations are displacing fragmented vendor relationships with single-source partnerships. The shift is most pronounced in California's Bay Area, where multi-institutional purchasing cooperatives are negotiating enterprise licensing terms with reagent suppliers.
US Gene Editing Market Segmentation
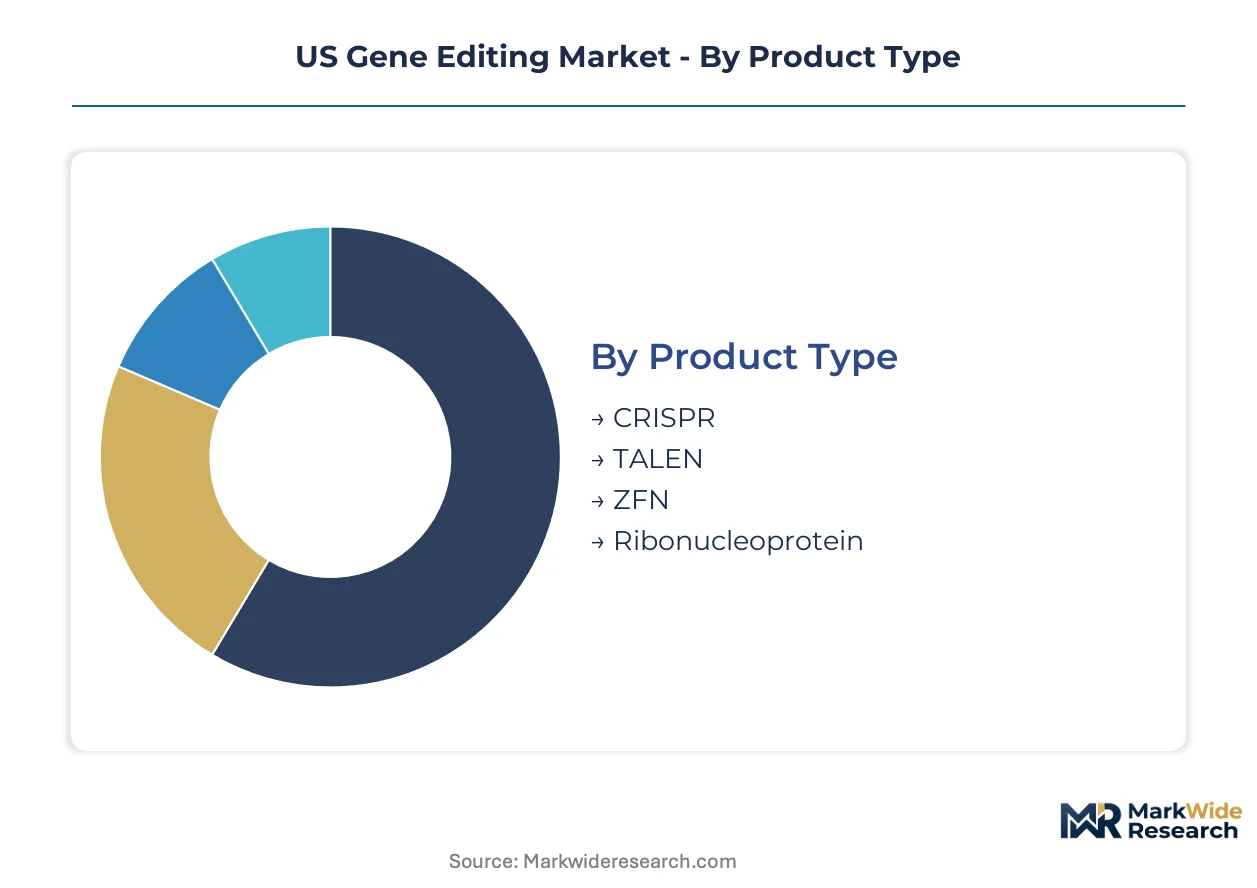
Gene editing market segmentation reveals distinct procurement patterns across research and therapeutic development settings. Platform selection varies sharply between exploratory academic work and regulated pharmaceutical manufacturing, with FDA compliance requirements driving technology choices in commercial applications.
Product Type:
CRISPR systems dominate domestic research consumption, while TALEN and ZFN platforms retain specialized therapeutic roles where reduced off-target liability justifies higher manufacturing costs.
- CRISPR:Programmable nuclease complexes utilizing guide RNA-directed Cas9 cleavage achieve target recognition within 20-nucleotide specificity windows. Massachusetts and California biotech corridors absorb the majority of domestic reagent procurement, driven by NIH-funded academic core facilities and venture-backed platform companies. FDA breakthrough therapy designations for CRISPR-based oncology products are accelerating pharmaceutical sponsor adoption.
- TALEN:Transcription activator-like effector nucleases deploy modular DNA-binding domains for targeted cleavage with reduced off-target profiles compared to CRISPR-Cas9. Therapeutic developers in Boston-Cambridge cluster favor TALEN systems for indications requiring high editing precision, particularly ex vivo hematopoietic applications where chromosomal translocation risks constrain therapeutic index.
- ZFN:Zinc finger nucleases represent the earliest commercialized platform, retaining niche deployment in legacy therapeutic programs and agricultural trait engineering pipelines.
- Ribonucleoprotein:Pre-assembled Cas9-guide RNA complexes enable transient editing activity with reduced DNA integration risks, gaining traction in clinical-grade cell therapy manufacturing workflows.
CRISPR commands the established base. The steepest expansion runs through ribonucleoprotein formats optimized for therapeutic manufacturing.
Application:
Cost tier stratification separates premium-priced therapeutic development from exploratory research applications, with oncology commanding the highest per-patient development investment.
- Oncology:CAR-T and TCR-engineered cell therapies targeting hematologic malignancies absorb the largest share of gene editing R&D expenditure. FDA accelerated approval pathways for breakthrough-designated oncology products are compressing development timelines and elevating platform licensing values in Massachusetts and California sponsor clusters.
- Rare Diseases:Sickle cell disease and beta-thalassemia programs leverage ex vivo autologous editing with established reimbursement frameworks. Vertex Pharmaceuticals and CRISPR Therapeutics have validated commercial models in this segment, though IRA Medicare price negotiation provisions are constraining revenue assumptions for approved therapies.
- Genetic Disorders:Inherited metabolic and neuromuscular indications present delivery challenges for in vivo editing platforms, with ocular and liver-directed programs advancing through early-phase trials.
- Therapeutics:Broad category encompassing clinical-stage programs across all disease areas, distinguished from research-tool applications by FDA IND requirements and GMP manufacturing standards.
Oncology absorbs the dominant investment share. Rare diseases are climbing the fastest as reimbursement pathways mature.
End User:
Customer type determines procurement scale and regulatory burden, with pharmaceutical companies operating under FDA cGMP requirements distinct from academic research exemptions.
- Academic Research:University core facilities and principal investigator laboratories drive high-volume, low-margin reagent consumption. NIH recombinant DNA guidelines govern institutional biosafety containment levels, with streamlined protocol approvals at major research universities reducing procurement friction.
- Pharmaceutical Companies:Large-cap sponsors including Bristol Myers Squibb and Novartis are integrating gene editing platforms into discovery workflows through strategic platform acquisitions. These entities bear full FDA CMC documentation burdens for IND-enabling studies and commercial manufacturing.
- Biotech Firms:Venture-backed platform developers in Boston-Cambridge and San Francisco-San Diego corridors concentrate therapeutic pipeline advancement, with Beam Therapeutics and Editas Medicine representing specialized pure-play models.
- Contract Research Organizations:CDMOs including Thermo Fisher Scientific's viral vector manufacturing network are critical single-source suppliers for IND-enabling studies, creating capacity bottlenecks that extend CMC timelines.
Academic research commands the established base. Pharmaceutical companies are gaining share fastest as therapeutic approvals accumulate.
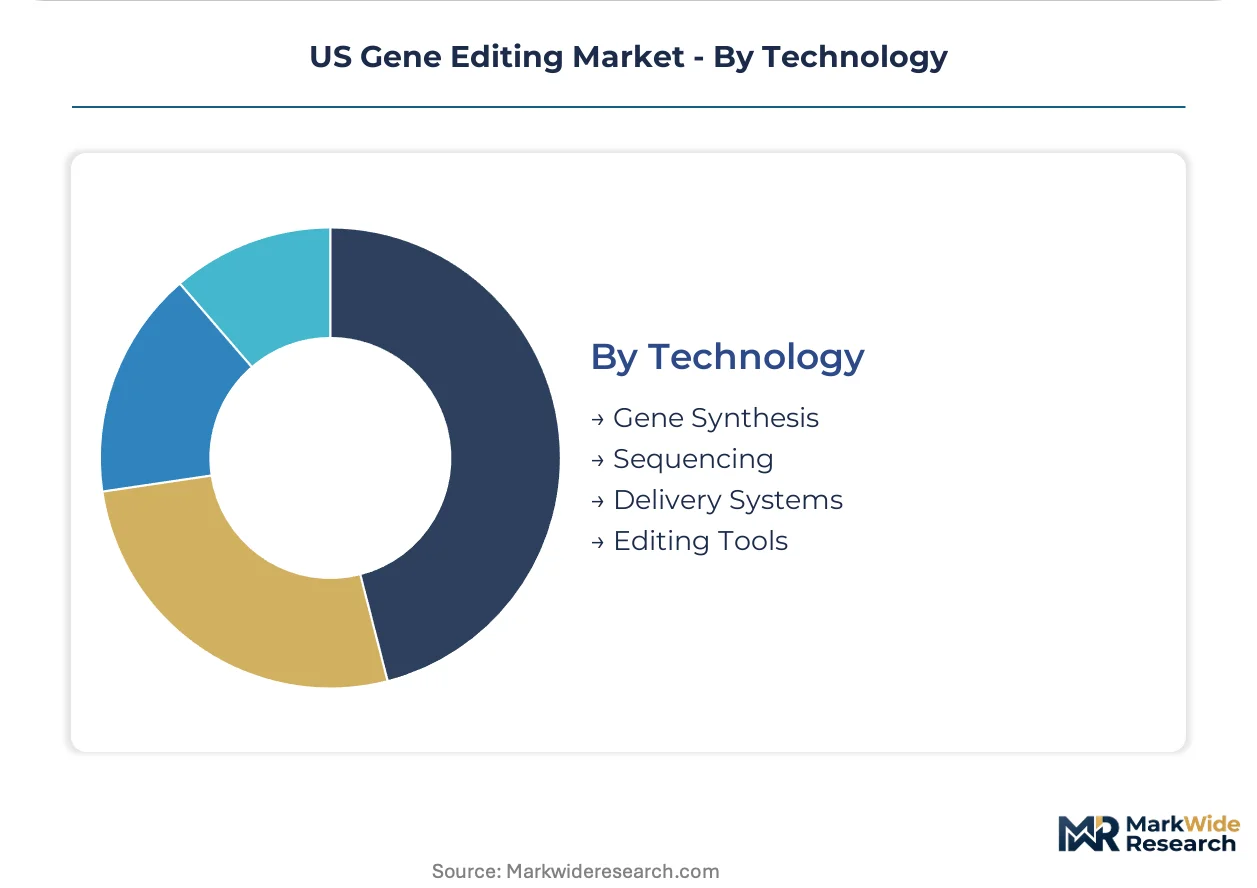
Technology:
Maturity gradients separate established sequencing and synthesis infrastructure from emerging delivery and editing modalities still navigating regulatory qualification.
- Gene Synthesis:Oligonucleotide manufacturing capacity constraints and raw nucleotide supply fluctuations are elevating input costs for guide RNA production, with procurement concentrating around integrated providers capable of design-through-validation workflows.
- Sequencing:Next-generation sequencing platforms enable editing outcome validation and off-target detection, forming essential analytical infrastructure for both research and regulated therapeutic development.
- Delivery Systems:Viral vector manufacturing for lentiviral and AAV platforms remains capacity-constrained across a limited network of contract development organizations. Lipid nanoparticle formulations for mRNA-encoded editors are expanding addressable tissue targets.
- Editing Tools:Base-editing and prime-editing chemistries are displacing first-generation nuclease systems across therapeutic pipelines, enabling precise point mutations without double-strand breaks.
Sequencing commands the established base. Delivery systems are expanding most quickly as in vivo therapeutic programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Massachusetts and California biotech corridors, where venture deployment density creates supplier ecosystems that command premium reagent costs unavailable to investigators in secondary research markets.
Massachusetts
Harvard and MIT spinouts drive CRISPR reagent procurement at scale, with NIH-funded academic core facilities absorbing substantial consumables volume. The state's life sciences tax credits subsidize preclinical infrastructure for platform developers. The Boston-Cambridge cluster anchors therapeutic pipeline advancement, with Beam Therapeutics and Editas Medicine maintaining headquarters operations there.
California
Stanford and UCSF institutional biosafety frameworks streamline CRISPR protocol approvals, accelerating research timelines relative to jurisdictions with heavier administrative burden. The California Institute for Regenerative Medicine channels state funding toward stem cell and gene editing research. The San Francisco-San Diego corridor concentrates venture-backed platform companies and multi-institutional purchasing cooperatives negotiating enterprise reagent licensing.
North Carolina
Research Triangle Park anchors gene therapy manufacturing expansion, with contract development organizations establishing viral vector production capacity to serve IND-enabling studies. The state's biotechnology center provides workforce training grants addressing cell therapy talent scarcity. Durham and Chapel Hill host satellite operations for platform developers seeking lower operational costs than coastal corridors.
Washington
Seattle's Fred Hutchinson Cancer Center drives ex vivo hematopoietic editing research, with clinical trial infrastructure supporting autologous cell therapy development. The state's absence of germline editing prohibitions permits broader research boundaries than jurisdictions with restrictive statutes. The Pacific Northwest biotech cluster attracts platform developers seeking proximity to clinical research organizations specializing in oncology indications.
Texas
Houston's Texas Medical Center hosts gene therapy clinical trial sites benefiting from diversified patient populations and established rare disease registries. The state's business-friendly regulatory environment attracts manufacturing investment from sponsors seeking alternatives to coastal operational costs. The Dallas-Fort Worth corridor emerges as a secondary hub for contract research organizations serving pharmaceutical sponsors.
US Gene Editing Market Competitive Landscape
Concentration sits with diversified life sciences conglomerates controlling reagent manufacturing scale and specialized platform developers possessing proprietary editing chemistries. Thermo Fisher Scientific leverages consumables supply relationships across academic and contract research markets. Three archetypes dominate: integrated reagent manufacturers, base-editing specialists, and ocular/hematopoietic pure-plays. Competitive moves center on strategic platform acquisitions and capacity expansion in viral vector manufacturing.
Within the integrated reagent tier, Thermo Fisher Scientific anchors supply relationships through manufacturing scale. Among platform developers, Beam Therapeutics and Editas Medicine exemplify specialized pure-play models, with Beam representing base-editing chemistry differentiation and Editas occupying a position in proprietary delivery formulations. CRISPR Therapeutics sits within the therapeutic development archetype, reflecting validated commercial models in rare disease indications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| GenScript |
| Intellia Therapeutics |
| Beam Therapeutics |
| Editas Medicine |
| Synthego |
| CRISPR Therapeutics |
| Others |
Pricing and Supply Chain Analysis
Ribonucleoprotein format substitution for plasmid-based reagent delivery is redrawing procurement geography toward Massachusetts and California manufacturing clusters while compressing price premiums for clinical-grade editing inputs. This chemistry transition simultaneously elevates biosynthesis capacity requirements and concentrates pricing power among integrated providers capable of design-through-validation workflows.
Pricing Analysis
The customization-premium spread separates standard catalog CRISPR reagents from configured-to-order guide RNA designs with analytical validation packages. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by GMP certification grade and volume scale commitments. Cost compression in standard research-grade reagents is intensifying because oligonucleotide manufacturing capacity expansion outpaces academic demand growth. Biotech firms exhibit the highest price sensitivity due to venture funding constraints, while pharmaceutical companies absorb premium pricing for IND-enabling documentation.
Supply Chain Analysis
Strategic stockpile preferences dominate viral vector procurement, with sponsors maintaining six-to-twelve month safety inventories to mitigate single-source CDMO bottlenecks. Supply concentration centers on the United States, Switzerland, and Singapore for clinical-grade manufacturing, with raw nucleotide feedstocks drawing from South Korean and Japanese chemical suppliers. Single-source vulnerability pervades lentiviral vector capacity, where a limited contract development organization network creates IND-enabling study delays. Distribution runs through direct manufacturer relationships for pharmaceutical sponsors and multi-institutional purchasing cooperatives for academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US gene editing market sits in early-cycle expansion, with base-editing and prime-editing platform maturation driving therapeutic pipeline acceleration beyond historical nuclease limitations.
For Market Incumbents: Shield proprietary delivery formulations through patent estate reinforcement and captive viral vector manufacturing capacity in Research Triangle Park. Beam Therapeutics and Editas Medicine demonstrate how chemistry differentiation and geographic manufacturing control defend margin position against emerging platform developers with comparable editing precision. Regulatory documentation depth serves as the priority lever for IND-enabling study capture. For New Entrants and Emerging Players: Anchor in ex vivo hematopoietic applications where autologous cell therapy manufacturing complexity deters large pharmaceutical sponsor vertical integration. The Texas Medical Center corridor offers the most penetrable geography, with diversified patient populations and established rare disease registries supporting accelerated clinical trial enrollment. A CDMO partnership model with viral vector capacity guarantees enables competitive IND timelines without capital-intensive manufacturing buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed platform developers possessing validated base-editing or prime-editing chemistry but facing IRA-constrained revenue assumptions for late-stage therapeutic programs. Five-to-ten year viability hinges on successful pivot toward discovery engine licensing models and early-stage pharmaceutical sponsor partnerships. The signal to watch is FDA breakthrough therapy designation velocity for non-oncology indications, indicating platform versatility beyond hematologic malignancies.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough designation for sickle cell programs validates commercial pathway assumptions. |
| Manufacturing Scale-Up | Viral vector capacity expansion in North Carolina reduces IND-enabling study bottlenecks. |
| Regulatory Approval Pathway | Long-term follow-up protocol investments anticipate fifteen-year pharmacovigilance obligations. |
| Licensing Agreement | Guide RNA IP portfolio monetization addresses fragmented patent estate royalty stacking. |
| Pipeline Diversification | Ocular and liver-directed in vivo programs expand addressable disease alleles. |
Research Methodology
Cross-validation between regulatory filing analysis and primary stakeholder interviews anchors the qualitative findings in documented compliance requirements and operational constraints. Conversations with gene therapy development executives, FDA regulatory affairs leads, academic core facility directors, and CDMO procurement managers informed platform adoption timelines and manufacturing capacity assessments. Secondary validation drew from FDA Office of Tissues and Advanced Therapies guidance documents, NIH recombinant DNA research protocol databases, ClinicalTrials.gov gene editing trial records, and state-level life sciences incentive program filings. Bottom-up reagent procurement modeling and top-down therapeutic pipeline valuation approaches were reconciled through iterative triangulation.
Sensitivity analysis tested forecast robustness across alternative IRA Medicare price negotiation implementation scenarios and viral vector manufacturing capacity expansion trajectories. The analytical framework segments by product type, application, end user, and technology across the analysis window, with CAGRs derived from therapeutic approval velocity assumptions and research reagent consumption elasticity. Modeled inputs include pharmaceutical sponsor R&D allocation shifts, academic NIH funding patterns, and state-level research infrastructure subsidy programs.
Underlying assumptions cover sustained FDA breakthrough therapy pathway availability and stable NIH recombinant DNA guideline frameworks, with deviation risk concentrated in germline editing prohibition legislative activity and oligonucleotide raw material supply disruptions. Revision becomes warranted when base-editing clinical efficacy data crosses thresholds that displace first-generation nuclease platform economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market