
 Microbial Gene Editing Services Market | 2026-2036
Microbial Gene Editing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Gene Editing Services Market Foresight
CGMP-compliant microbial strain development is unwinding legacy quality bottlenecks in contract gene editing. Thermo Fisher Scientific leverages its end-to-end synthetic biology infrastructure to dominate plasmid-to-protein workflows. GenScript Biotech Corp anchors Asia-Pacific capacity with automated CRISPR library construction. Charles River Laboratories competes through its specialized microbial host engineering for toxic protein expression.
Microbial gene editing services encompass targeted DNA modification of bacterial and yeast hosts using programmable nucleases, typically achieving knock-in efficiencies above 50% in optimized Escherichia coli chassis strains. These services enable rapid generation of production organisms for recombinant therapeutics, industrial enzymes, and bio-based chemicals. CRISPR-based service lines command premium pricing due to multiplexing capability and reduced turnaround times versus TALEN or ZFN alternatives. Synthetic biology integration now drives margin expansion as clients demand complete pathway engineering rather than single-gene modifications. Research applications retain the largest volume share while industrial bioprocessing represents the fastest-growing demand segment as bio-manufacturers seek microbial alternatives to mammalian systems.
The FDA oversees gene-edited microbial strains used in investigational new drug applications through its Office of Therapeutic Biologics and Cosmetics, while the EMA's ATMP classification determines whether edited microbes trigger centralized marketing authorization pathways. China's NMPA issued technical guidelines for gene-edited microorganisms in agricultural and industrial applications, creating dual-track compliance for service providers operating across jurisdictions. Stakeholders must monitor evolving biosafety classifications for gene-edited microbes as these determinations reshape which service tiers require enhanced containment infrastructure and which qualify for streamlined regulatory pathways.
Market Dynamics
CRISPR multiplexing is compressing project timelines from months to weeks, forcing service providers to reconfigure laboratory workflows and pricing architectures around speed tiers rather than complexity tiers.
Growth Catalysts
- Biologics manufacturing expansion:Pharmaceutical developers in the United States are commissioning microbial chassis strains for biosimilar production, creating sustained demand for knock-in precision above 50% efficiency thresholds.
- EMA ATMP framework acceleration:The European Medicines Agency's streamlined qualification pathways for gene-edited microorganisms are reducing service provider onboarding cycles for centralized marketing authorization.
- Synthetic biology integration:Clients now contract for complete metabolic pathway engineering rather than isolated gene modifications, expanding average project scope and service revenue per engagement.
Market Restraints
- Specialized containment infrastructure:Enhanced biosafety level requirements for certain edited microbial classifications demand capital-intensive facility upgrades that smaller contract research organizations cannot finance.
- Skilled technician scarcity:The pool of scientists proficient in both CRISPR guide RNA design and microbial fermentation optimization remains concentrated in Germany, the United States, and China.
- Regulatory fragmentation:Divergent classification standards between the FDA's Office of Therapeutic Biologics and Cosmetics and China's NMPA force service providers to maintain parallel compliance documentation for cross-border projects.
Strategic Opportunities
- Industrial bioprocessing pivot:Bio-manufacturers seeking alternatives to mammalian expression systems are commissioning yeast and bacterial platforms for complex therapeutic protein production.
- Automated library construction:High-throughput CRISPR screening services for enzyme discovery represent an underdeveloped revenue layer beyond traditional strain engineering.
- Dual-track compliance expertise:Service providers mastering both pharmaceutical-grade CGMP standards and agricultural application guidelines can capture cross-sector contracts without facility duplication.
Industry Challenges
- CGMP certification timelines:Strain documentation packages for investigational new drug applications require 12-18 months of stability and characterization data, compressing project profitability windows.
- Intellectual property navigation:Licensing CRISPR-Cas9 systems from competing patent estates creates contractual complexity and royalty stacking for service providers offering multiplexed editing.
- Legacy quality system integration:Contract manufacturers with established mammalian cell culture workflows face technical debt when retrofitting microbial contamination control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Gene Editing Services Market |
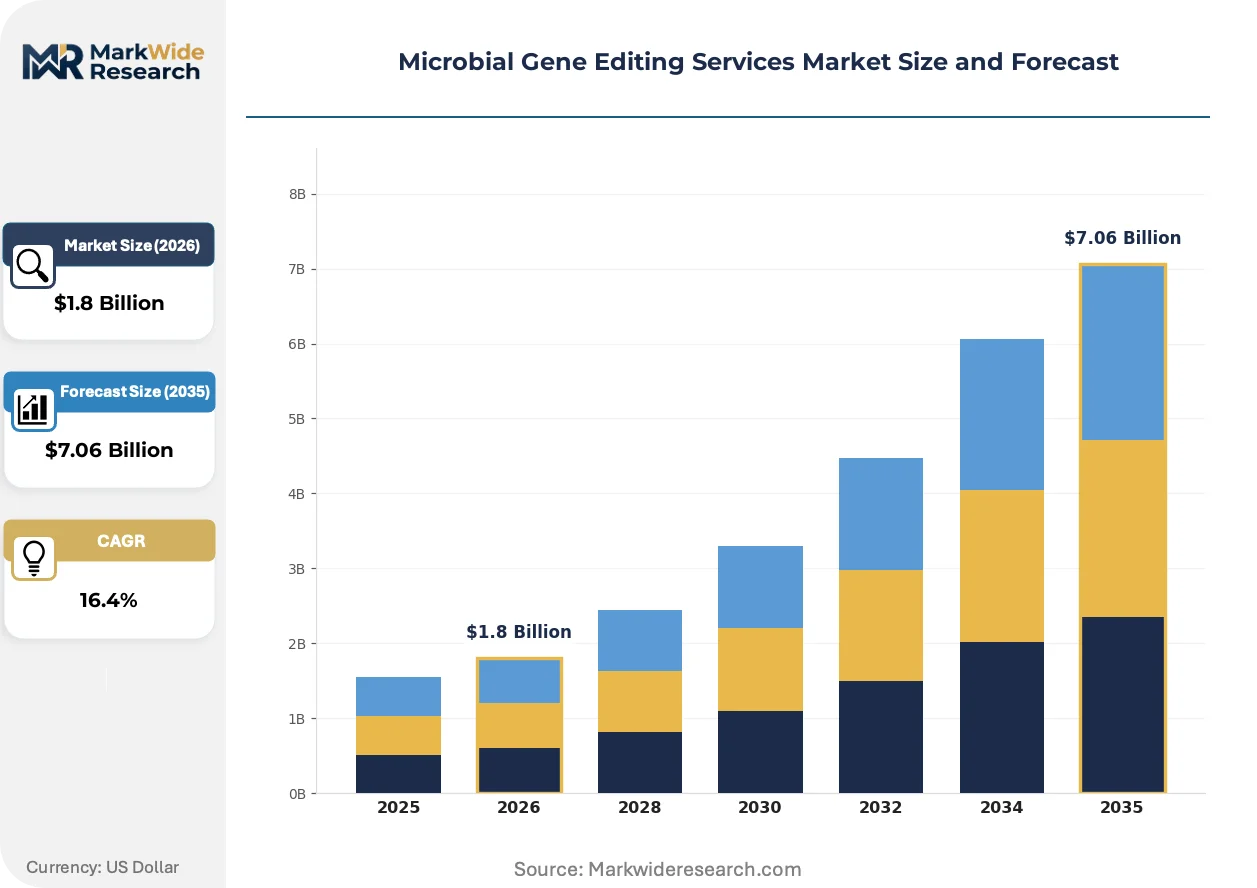
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: CRISPR, TALEN, ZFN, Prime Editing Technology: Genome Editing, Synthetic Biology, Bioinformatics, Molecular Cloning Application: Research, Therapeutics, Agriculture, Industrial Bioprocessing End User: Research Institutions, Pharmaceuticals, Biotechnology Companies, Crop Producers |
| Companies Covered | Thermo Fisher Scientific, Creative Biogene, GenScript Biotech Corp, GeneCopoeia, Inc., Synbio Technologies, ProteoGenix, Vigene Biosciences, Cellecta, Inc., Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Gene Editing Services Market Shifts & Advancements
Base editing and prime editing variants are displacing conventional CRISPR-Cas9 in precision-critical applications, while artificial intelligence tools for guide RNA prediction are compressing experimental design cycles. These convergent forces are redrawing competitive boundaries between pure-play gene editing shops and integrated synthetic biology platforms.
Prime editing is fragmenting the technical specifications that previously unified microbial engineering service tiers. The technology enables precise nucleotide substitutions without double-strand breaks, attracting pharmaceutical developers with stringent off-target thresholds. Contract research organizations lacking prime editing capabilities are retreating to commodity knock-out services while premium positioning consolidates with providers offering both Cas9 and engineered reverse transcriptase fusion platforms.
China's NMPA technical guidelines for gene-edited microorganisms are creating regulatory arbitrage opportunities for service providers with dual US-China operational footprints. The guidelines distinguish pharmaceutical from industrial applications, permitting streamlined environmental release assessments for the latter category. Multinational bio-manufacturers are routing non-therapeutic strain development through Chinese contract research organizations to exploit faster approval timelines.
Buyer consolidation among large pharmaceutical developers is forcing tiered service contracting based on speed guarantees rather than unit pricing. Major biologics manufacturers now demand dedicated laboratory capacity with 24-hour turnaround commitments for critical path strain modifications. This compression of service-level expectations is squeezing mid-size providers unable to guarantee redundant staffing or equipment availability.
Microbial Gene Editing Services Market Segmentation
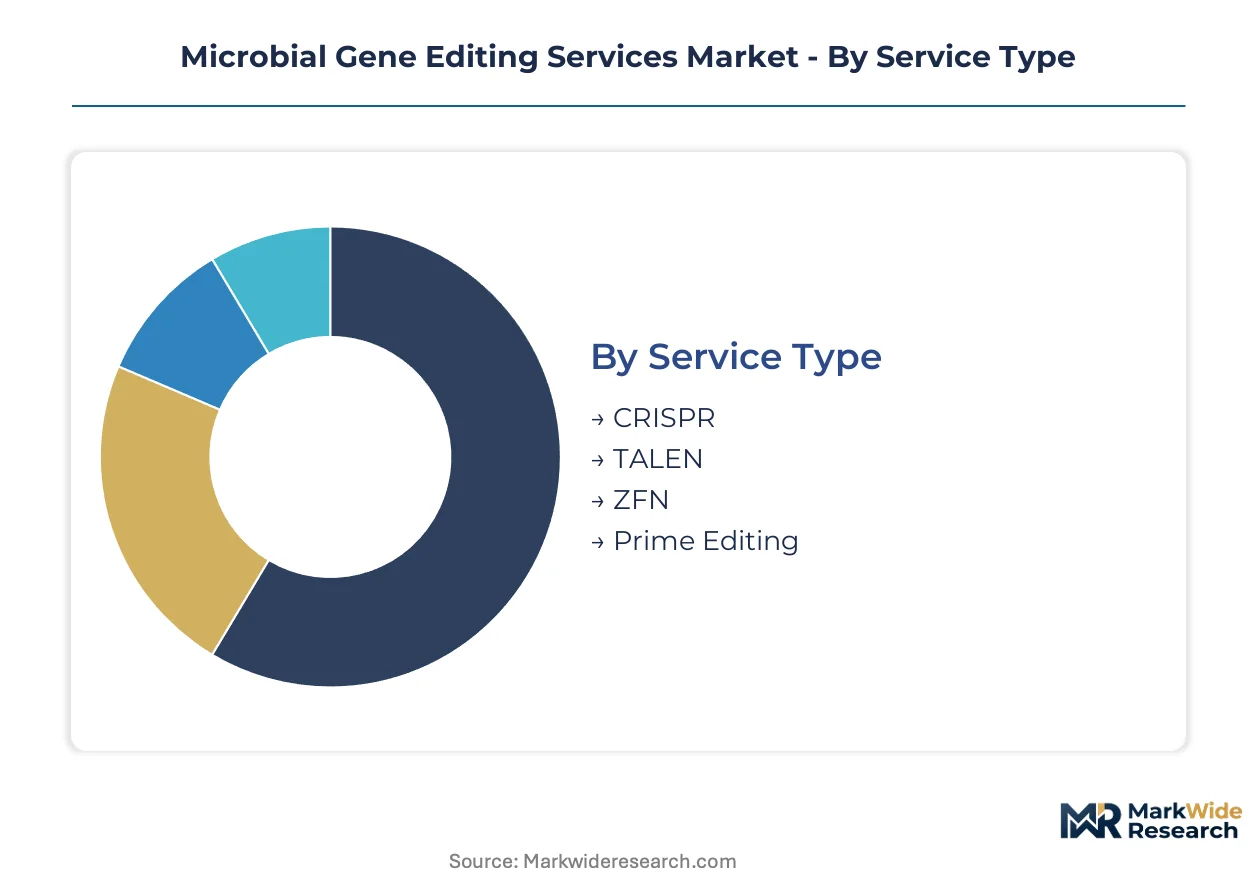
Service differentiation in microbial gene editing creates distinct margin pools based on technical complexity, regulatory burden, and client scale. Understanding how these segments intersect reveals where providers can defend pricing power versus commoditization pressure.
Service Type:
CRISPR multiplexing commands premium pricing tiers due to reduced turnaround times and stacked modification capability, while legacy nuclease platforms compete on cost for simpler knock-out applications.
- CRISPR:Programmable nuclease systems achieve knock-in efficiencies above 50% in optimized Escherichia coli chassis through guide RNA-directed Cas9 cleavage. Pharmaceutical developers in the United States commission CRISPR-based microbial strain engineering for biosimilar production, driving sustained demand for multiplexed editing services that compress project timelines from months to weeks.
- Prime Editing:Engineered reverse transcriptase fusion platforms enable precise nucleotide substitutions without double-strand breaks, attracting clients with stringent off-target thresholds. Contract research organizations lacking prime editing capabilities are retreating to commodity knock-out services while premium positioning consolidates with dual-platform providers.
- TALEN:Transcription activator-like effector nucleases retain niche demand for regulatory environments with restrictive CRISPR intellectual property licensing.
- ZFN:Zinc finger nucleases persist in legacy manufacturing workflows where validated protocols resist platform migration costs.
The dominant share belongs to CRISPR, while prime editing is closing the gap fastest.
Technology:
Integration depth determines client stickiness, with end-to-end synthetic biology platforms capturing larger project scopes than point-solution providers.
- Genome Editing:Targeted DNA modification services using programmable nucleases form the core revenue layer for most contract research organizations.
- Synthetic Biology:Complete metabolic pathway engineering rather than isolated gene modifications now drives margin expansion as average project scope widens.
- Bioinformatics:Artificial intelligence tools for guide RNA prediction are compressing experimental design cycles and redrawing competitive boundaries between pure-play gene editing shops and integrated platforms.
- Molecular Cloning:Traditional recombinant DNA methods retain volume in research applications but face displacement by CRISPR-based alternatives in commercial workflows.
Synthetic biology integration captures expanding project scopes, though bioinformatics is gaining share fastest through AI-assisted design automation.
Application:
Regulatory classification intensity varies dramatically across applications, with pharmaceutical-grade services requiring 12-18 month stability documentation versus streamlined industrial pathways.
- Research:Academic and exploratory applications retain the largest volume share in microbial gene editing services, though pricing pressure from institutional budget constraints limits margin expansion.
- Therapeutics:CGMP-compliant microbial strain development for biologics manufacturing unwinds legacy quality bottlenecks, with the FDA's gene therapy guidance revisions accelerating service provider qualification timelines for investigational new drug applications.
- Agriculture:China's NMPA technical guidelines distinguish pharmaceutical from industrial applications, permitting streamlined environmental release assessments that create regulatory arbitrage opportunities for cross-border projects.
- Industrial Bioprocessing:Bio-manufacturers seeking microbial alternatives to mammalian expression systems are commissioning yeast and bacterial platforms for complex therapeutic protein production.
Research commands volume leadership, while industrial bioprocessing is expanding most quickly as bio-manufacturers pivot from mammalian systems.
End User:
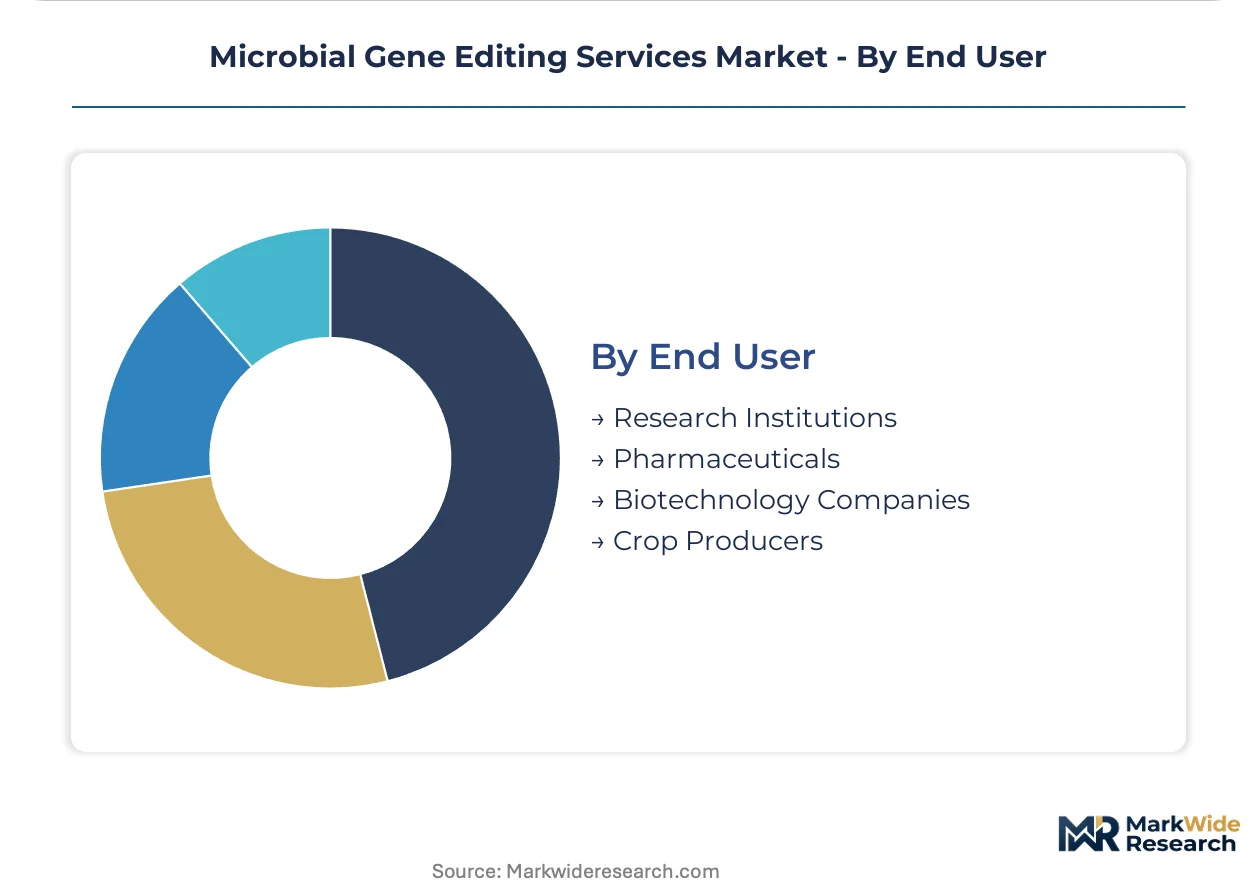
Buyer consolidation among large pharmaceutical developers is forcing tiered service contracting based on speed guarantees rather than unit pricing.
- Pharmaceuticals:Major biologics manufacturers now demand dedicated laboratory capacity with 24-hour turnaround commitments for critical path strain modifications, squeezing mid-size providers unable to guarantee redundant staffing.
- Biotechnology Companies:Venture-backed developers prioritize CRISPR-based service lines for rapid prototype iteration, accepting premium pricing for reduced turnaround times.
- Research Institutions:Academic clients drive volume in automated CRISPR library construction but face persistent budget constraints that limit pricing power.
- Crop Producers:Agricultural end users route non-therapeutic strain development through Chinese contract research organizations to exploit faster NMPA approval timelines for environmental release.
Pharmaceuticals dominate revenue concentration, while biotechnology companies are climbing the fastest as venture funding flows into microbial chassis development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CGMP-compliant microbial strain development clusters concentrate in the United States, Germany, and China, with each jurisdiction cultivating distinct regulatory specializations and contract research manufacturing ecosystems.
United States
Pharmaceutical developers commission microbial chassis strains for biosimilar production at scale. The FDA's Office of Therapeutic Biologics and Cosmetics oversees gene-edited microbial strains through investigational new drug application pathways. Greater Boston and San Diego host the largest contract research manufacturing clusters for microbial expression systems, with facilities expanding dedicated laboratory capacity for 24-hour turnaround commitments.
Germany
Industrial bioprocessing demand for yeast and bacterial alternatives to mammalian systems drives service provider qualification. The EMA's ATMP framework accelerates centralized marketing authorization timelines for gene-edited microorganisms. The Rhine-Main and Upper Bavaria regions concentrate containment infrastructure investments as enhanced biosafety level requirements reshape facility upgrade priorities.
China
Bio-manufacturers route non-therapeutic strain development through domestic contract research organizations to exploit faster approval timelines. The NMPA technical guidelines distinguish pharmaceutical from industrial applications, permitting streamlined environmental release assessments. Shanghai and Suzhou anchor Asia-Pacific capacity with automated CRISPR library construction platforms serving cross-border projects.
United Kingdom
Venture-backed biotechnology companies prioritize rapid prototype iteration through CRISPR-based service lines. The Medicines and Healthcare products Regulatory Agency aligns with EMA ATMP classifications for gene therapy products while maintaining independent assessment pathways. The Cambridge-Oxford-London triangle concentrates skilled technicians proficient in both guide RNA design and microbial fermentation optimization.
Switzerland
Precision-critical applications attract demand for prime editing capabilities with stringent off-target thresholds. Swissmedic maintains pharmaceutical-grade standards for microbial strain documentation packages requiring extended stability data. The Basel biotech corridor hosts specialized providers offering both Cas9 and engineered reverse transcriptase fusion platforms for multiplexed editing services.
Microbial Gene Editing Services Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized contract research organizations. The market structure divides between integrated synthetic biology platforms commanding premium positioning and pure-play gene editing shops competing on turnaround speed. Three archetypes dominate: end-to-end infrastructure owners, automated library construction specialists, and microbial host engineering boutiques. Capacity expansion and technology licensing constitute the dominant competitive moves as providers retrofit legacy mammalian workflows for microbial contamination control.
Among diversified infrastructure owners, Thermo Fisher Scientific exemplifies the plasmid-to-protein workflow archetype through its synthetic biology integration. GenScript Biotech Corp anchors Asia-Pacific positioning with automated CRISPR library construction capabilities. Charles River Laboratories occupies a specialized tier focused on microbial host engineering for demanding protein expression applications. These three entities represent distinct strategic postures—comprehensive integration, regional scale automation, and technical specialization—without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Creative Biogene |
| GenScript Biotech Corp |
| GeneCopoeia, Inc. |
| Synbio Technologies |
| ProteoGenix |
| Vigene Biosciences |
| Cellecta, Inc. |
| Charles River Laboratories |
| Others |
Supply & Pricing Matrix
CGMP certification requirements gate both supply qualification and price differentiation in microbial gene editing services, forcing contract research organizations to recover validation costs through tiered service premiums while pharmaceutical buyers absorb extended timelines as non-negotiable quality thresholds.
Pricing Analysis
FDA investigational new drug application standards dictate the pricing tier structure across microbial gene editing services. Three-tier pricing stratifies across pharmaceutical-grade, research-grade, and industrial-grade certification levels. Price differentiation rests on CGMP documentation depth and multiplexed editing capability. Cost compression in research-grade services is intensifying because automated CRISPR library construction platforms are commoditizing basic knock-out workflows. Academic institutions exhibit highest price sensitivity, while large biologics manufacturers prioritize speed guarantees over unit economics.
Supply Chain Analysis
Container availability fluctuations on trans-Pacific trade lanes intermittently strain inbound logistics for specialized reagent shipments. Supply concentrates in the United States, Germany, and China as these jurisdictions host dominant contract research manufacturing clusters. Raw material dependencies include synthetic oligonucleotides, engineered Cas9 variants, and CGMP-compliant fermentation media. Single-source vulnerability sits with patented guide RNA chemistries controlled by limited licensing estates. Distribution runs through direct contractual relationships rather than distributor networks, reflecting project-specific customization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in microbial gene editing services, as CGMP qualification timelines and proprietary strain documentation packages embed switching costs that pharmaceutical buyers cannot easily circumvent.
For Market Incumbents: Consolidate specialized containment infrastructure investments in the Rhine-Main and Greater Boston corridors to preempt capacity constraints from enhanced biosafety level requirements. Deepen backward integration into synthetic oligonucleotide manufacturing to reduce royalty stacking exposure from competing CRISPR patent estates. Lock in exclusive fermentation media supply agreements before commodity price volatility propagates through input costs. For New Entrants and Emerging Players: China's NMPA technical guideline fast-tracks for industrial applications offer the most penetrable regulatory pathway for non-therapeutic strain development. Target automated CRISPR library construction services for enzyme discovery as an underdeveloped revenue layer beyond traditional strain engineering. Lead with bioinformatics-enabled guide RNA prediction as a differentiated go-to-market angle to compress experimental design cycles for venture-backed biotechnology clients. For Investors and Strategic Acquirers: EMA ATMP framework acceleration reshapes the acquisition landscape by reducing centralized marketing authorization timelines for qualified service providers. Long-term viability favors diversified synthetic biology platforms with end-to-end plasmid-to-protein workflows over pure-play gene editing shops facing commoditization pressure. Monitor prime editing capability adoption as the inflection signal separating premium-positioned providers from retreating commodity competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CGMP Certification Investment | FDA qualification timelines for investigational new drug applications compress competitive qualification windows for late entrants. |
| Prime Editing Platform Integration | Engineered reverse transcriptase fusion capabilities attract pharmaceutical developers with stringent off-target thresholds. |
| Dual-Track Compliance Expertise | Mastering both pharmaceutical-grade standards and agricultural guidelines captures cross-sector contracts without facility duplication. |
| Automated Library Construction Scale-Up | High-throughput CRISPR screening services for enzyme discovery represent underdeveloped revenue beyond strain engineering. |
| Containment Infrastructure Expansion | Enhanced biosafety level investments in Germany and the United States preempt regulatory classification reshaping. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical development executives, regulatory affairs leads at contract research organizations, microbial fermentation specialists, and procurement managers at biotechnology companies. Secondary validation drew from FDA gene therapy guidance documents, EMA ATMP framework updates, NMPA technical guidelines, and SEC filings from diversified life science conglomerates. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Across the projection horizon, the analytical framework modeled service type, technology integration depth, application regulatory intensity, and end-user scale segmentation. CAGRs were derived from weighted scenario analysis across qualification timeline acceleration and biosafety classification evolution scenarios. Forecast inputs incorporated CRISPR multiplexing adoption curves and prime editing capability diffusion patterns.
Underlying assumptions cover sustained biologics manufacturing expansion and stable regulatory classification standards for gene-edited microorganisms, with deviation risk concentrated in intellectual property licensing disputes and biosafety level reclassification events. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market