
 Global Product Information Management (PIM) Software Market | 2026-2036
Global Product Information Management (PIM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Information Management (PIM) Software Market Foresight
The convergence of PIM platforms with composable commerce architectures is narrowing the gap between product data management and real-time customer experience delivery. SAP anchors its position through deep ERP integration that binds product records to supply chain execution. Salsify competes by extending native marketplace connectivity that reduces manual syndication overhead for brand manufacturers.
Product Information Management (PIM) Software constitutes a centralized system for aggregating, enriching, and distributing structured product data across sales channels, typically handling SKU-level attributes, digital assets, and localization rules through API-first or federated data architectures. Its primary commercial purpose is to eliminate data fragmentation that produces inconsistent pricing, incomplete specifications, and compliance gaps across e-commerce storefronts, marketplaces, and physical retail systems. Cloud-Based deployment leads solution delivery by removing infrastructure barriers for mid-market entrants, while Data Syndication commands disproportionate attention as brands face escalating channel expansion requirements from retailers like Amazon and Walmart. Workflow Automation represents the fastest-growing solution type as organizations seek to compress time-to-market for seasonal product lines.
FDA 21 CFR Part 11 requirements for electronic records in pharmaceuticals, GDPR data portability mandates in Europe, and India's DPDP Act obligations for consumer data handling collectively elevate auditability and consent management within PIM implementations. ISO 8000 data quality standards further shape how enterprises validate product attribute completeness before channel publication. Stakeholders must monitor how generative AI content generation interfaces with existing governance frameworks without eroding regulatory defensibility.
Market Dynamics
The convergence of generative AI with composable commerce architectures is collapsing the latency between product data updates and live customer experiences, forcing vendors to rearchitect around real-time API meshes rather than batch-synchronized records.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for automated content generation are compelling enterprises to deploy auditable PIM workflows that log every AI-assisted attribute modification.
- Omnichannel apparel syndication:Brand manufacturers managing seasonal SKU rotations across Amazon, Zalando, and TikTok Shop require automated channel-specific formatting that PIM platforms now embed natively.
- India's DPDP Act data localization:Consumer consent management obligations are accelerating replacement of legacy product databases with governance-ready systems that enforce granular access controls.
Market Restraints
- Cloud infrastructure cost volatility:Mid-market PIM deployments face margin pressure from escalating compute and egress fees charged by hyperscale providers.
- Legacy ERP integration friction:SAP ECC and Oracle E-Business Suite instances require expensive middleware layers to expose product master data through modern REST interfaces.
- ISO 8000 certification timelines:Data quality standard validation stretches implementation cycles by 8-14 months for pharmaceutical and medical device manufacturers.
Strategic Opportunities
- German automotive aftermarket digitization:Teilehersteller supplying replacement parts through Amazon and eBay Kleinanzeigen lack structured fitment data, creating whitespace for VIN-specific PIM modules.
- Generative AI + DAM convergence:Automated asset variant generation for regional campaigns compresses localization from weeks to hours for beauty and CPG brands.
- US FDA 21 CFR Part 11 electronic records:Pharmaceutical serialization and track-and-trace mandates are expanding addressable market for audit-trail-enabled PIM systems.
Industry Challenges
- Data steward talent scarcity:Hybrid roles combining taxonomy design, SQL proficiency, and regulatory knowledge command 40% salary premiums in competitive labor markets.
- Multi-tenant architecture security audits:SaaS PIM vendors face prolonged procurement cycles as enterprise buyers demand SOC 2 Type II and ISO 27001 evidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Information Management (PIM) Software Market |
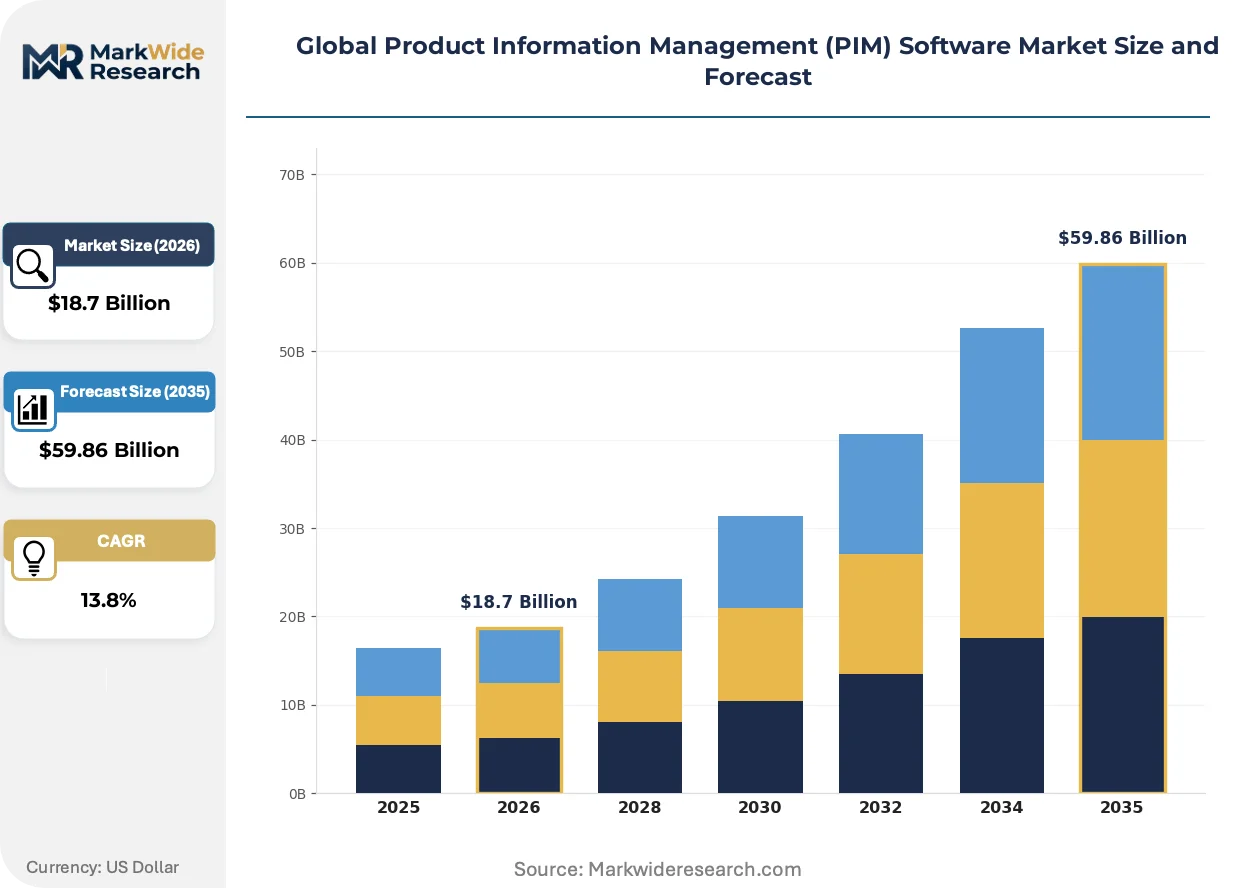
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $59.86 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS-Only Solution Type: Master Data Management, Digital Asset Management, Data Syndication, Workflow Automation, Analytics Integration End User Industry: Consumer Electronics, Apparel & Accessories, Pharmaceuticals, Publishing, Food & Beverage, Electrical Equipment Integration Level: Basic, Intermediate, Advanced, Enterprise-Grade |
| Companies Covered | Oracle, SAP, IBM, Informatica, Salsify, Akeneo, inriver, Pimcore, Stibo Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Information Management (PIM) Software Market Shifts & Advancements
Real-time data synchronization is displacing nightly batch processes as the default operational pattern, with edge-computing deployments enabling millisecond-latency updates at physical retail endpoints.
GraphQL federation is collapsing the distinction between product information management and customer-facing commerce APIs. Retailers including Walmart and Target now ingest enriched attributes directly from brand-owned data meshes rather than intermediary aggregators. This architectural shift compresses time-to-shelf from days to minutes for seasonal assortments.
The EU AI Act's risk-based classification system is mandating explainability logs for any automated product description generation. Cosmetics and food supplement brands deploying large language models must now maintain immutable audit trails linking AI outputs to source attribute records. German and French regulators are already inspecting these logs during market surveillance activities.
Brand manufacturers are consolidating vendor relationships around platforms that bundle PIM with digital asset management and syndication capabilities. Procurement teams at apparel and home goods companies now evaluate total cost of ownership across content creation, enrichment, and distribution rather than licensing fees alone. This bundling preference is most pronounced in the United States and United Kingdom where marketing operations teams hold consolidated technology budgets.
Global Product Information Management (PIM) Software Market Segmentation
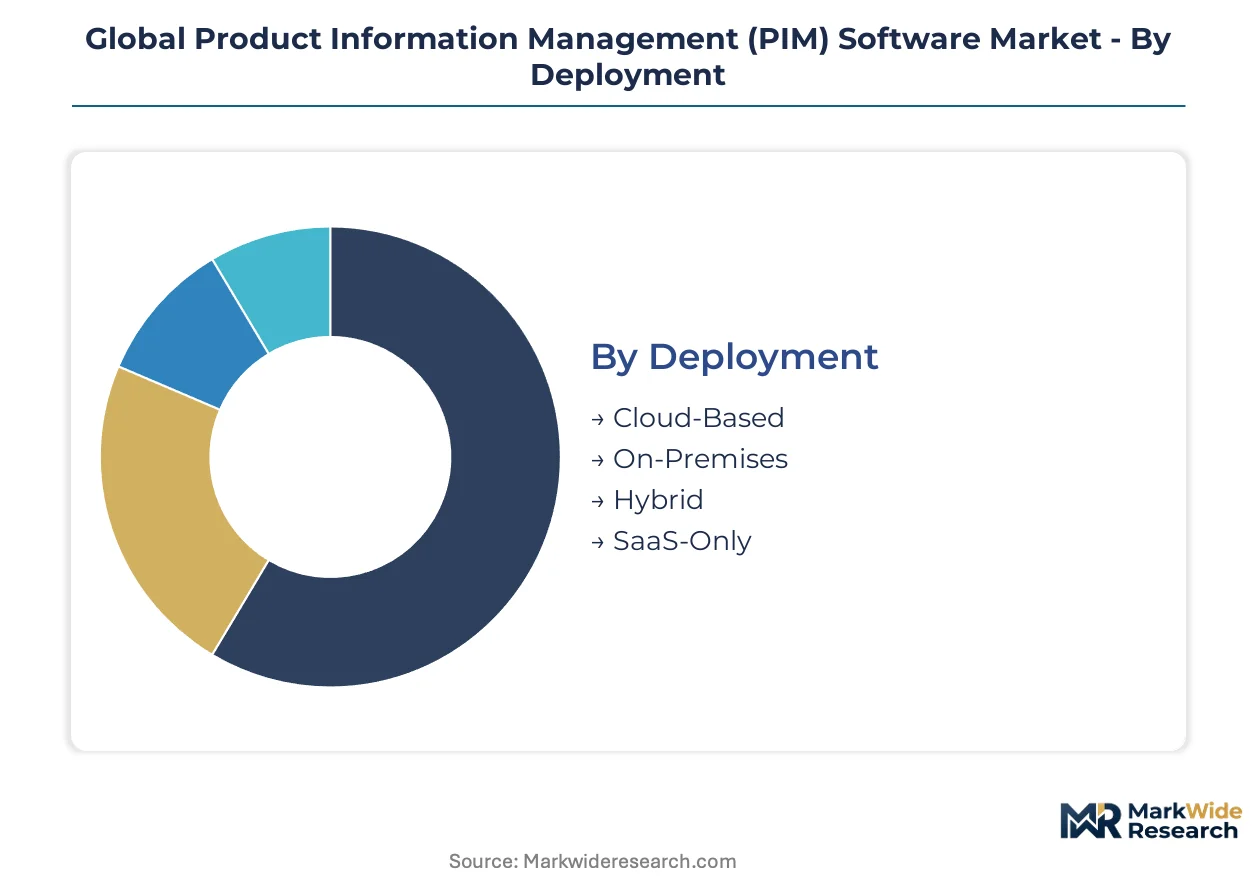
PIM software segmentation reveals how deployment architectures, functional modules, and integration depth map to distinct buyer risk profiles and implementation timelines. Procurement patterns diverge sharply between mid-market entrants prioritizing speed-to-value and enterprise incumbents demanding governance depth.
Deployment:
Mature cloud infrastructure dominates new procurement, while hybrid architectures address emerging data sovereignty requirements across regulated industries.
- Cloud-Based:Multi-tenant architectures eliminate capital expenditure barriers and compress implementation cycles from quarters to weeks. Demand concentrates among mid-market apparel brands in Germany and India scaling TikTok Shop and Amazon marketplace presence without infrastructure overhead.
- On-Premises:Air-gapped installations serve pharmaceutical manufacturers facing FDA 21 CFR Part 11 audit requirements and India's DPDP Act data localization mandates. Capital intensity and 12-18 month deployment timelines restrict adoption to enterprises with captive IT operations.
- Hybrid:Sensitive product master data resides on-premises while syndication layers operate in cloud environments. European automotive suppliers leverage this model to satisfy GDPR data residency rules while maintaining real-time marketplace connectivity.
- SaaS-Only:Pure subscription models with zero infrastructure footprint target rapid channel expansion for direct-to-consumer brands. Beauty and CPG manufacturers in the United States adopt this tier for seasonal campaign velocity.
Cloud-Based deployments retain volume leadership; SaaS-Only configurations hold the steepest expansion curve as composable commerce architectures mature.
Solution Type:
Functional specialization tracks buyer maturity, with integrated suites displacing point solutions as total cost of ownership calculations incorporate content creation and distribution labor.
- Master Data Management:Centralized golden record creation for SKU attributes, supplier hierarchies, and localization rules. SAP-anchored enterprises in Germany and the United States deploy these modules to bind product data to ERP-driven supply chain execution.
- Digital Asset Management:Repository and transformation engines for imagery, video, and 3D assets. Apparel and accessories brands concentrate investment here to automate variant generation for regional campaigns across Zalando, Amazon, and TikTok Shop.
- Data Syndication:Channel-specific formatting engines that map enriched attributes to retailer ingestion schemas. Reduces manual overhead for brand manufacturers managing Walmart, Target, and Amazon compliance simultaneously.
- Workflow Automation:Business process orchestration for seasonal line reviews, regulatory approval gates, and translation workflows. Compresses time-to-market from concept to channel publication.
- Analytics Integration:Attribution and performance measurement linking product content quality to conversion rates. Emerging demand from consumer electronics brands optimizing Amazon A+ content ROI.
Data Syndication commands the largest installed base; Workflow Automation is expanding most quickly as seasonal velocity pressures intensify.
End User Industry:
Industry-specific compliance requirements and channel complexity create divergent functional priorities across vertical procurement.
- Consumer Electronics:High SKU velocity and specification density demand automated attribute inheritance and competitive intelligence integration. United States and Chinese brands prioritize real-time price monitoring across Amazon and direct channels.
- Apparel & Accessories:Seasonal rotation cycles and omnichannel complexity drive investment in workflow automation and digital asset variant generation. German and Indian brands lead adoption for Zalando and Myntra marketplace expansion.
- Pharmaceuticals:FDA 21 CFR Part 11 and EMA serialization mandates require immutable audit trails and electronic signature workflows. Implementation timelines stretch 18-24 months due to validation protocols.
- Publishing:Metadata enrichment for discoverability across Amazon Kindle, Apple Books, and library distribution networks. Rights management and territorial licensing complexity shape functional requirements.
- Food & Beverage:EU AI Act risk classification for automated content generation and FSSAI labeling compliance in India. Nutritional claim validation and allergen disclosure workflows dominate procurement criteria.
- Electrical Equipment:CE marking documentation and REACH substance declarations require technical specification management. German industrial distributors leverage PIM for B2B marketplace integration.
Apparel & Accessories retains volume leadership; Pharmaceuticals holds the steepest expansion curve as serialization mandates proliferate.
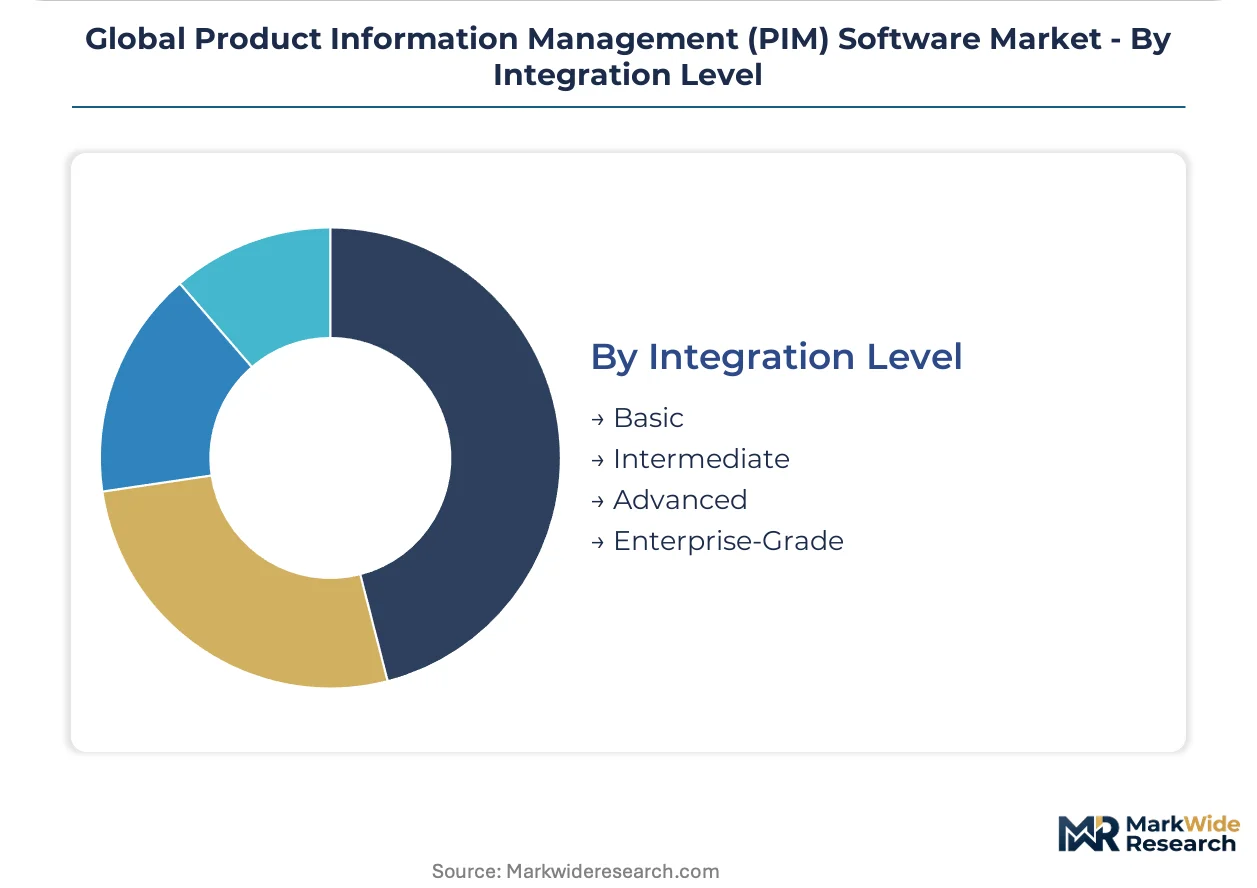
Integration Level:
Architectural sophistication correlates directly with data governance maturity and cross-functional workflow complexity.
- Basic:Standalone PIM with manual CSV import/export and limited API connectivity. Targets single-channel retailers with sub-10,000 SKU catalogs and minimal ERP dependency.
- Intermediate:REST API integration with major e-commerce platforms and ERP systems. Mid-market manufacturers in India and the United States adopt this tier for Shopify and Magento connectivity.
- Advanced:Real-time bidirectional synchronization with composable commerce stacks, DAM systems, and marketplace aggregators. GraphQL federation enables millisecond-latency attribute updates.
- Enterprise-Grade:Multi-domain master data management spanning product, customer, and supplier records with embedded data quality scoring and ISO 8000 compliance validation. Global CPG and pharmaceutical conglomerates mandate this tier.
Intermediate integrations retain volume leadership; Enterprise-Grade configurations hold the steepest expansion curve as regulatory audit requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German PIM vendors export workflow automation solutions to apparel manufacturers scaling TikTok Shop presence across India and the United States. This trade corridor reflects how European data governance expertise transfers to high-velocity digital commerce markets.
United States
Consumer electronics brands and CPG manufacturers drive cloud-native PIM procurement for Amazon marketplace syndication. FDA 21 CFR Part 11 requirements shape pharmaceutical implementations with immutable audit trails. Seattle and San Francisco Bay Area clusters concentrate SaaS vendors serving direct-to-consumer beauty brands.
Germany
Automotive aftermarket suppliers and industrial distributors demand VIN-specific fitment data modules for Amazon and eBay Kleinanzeigen integration. EU AI Act risk classification mandates explainability logs for automated content generation. Munich and Stuttgart engineering clusters anchor Teilehersteller digitization initiatives.
India
Apparel exporters and domestic marketplace sellers adopt SaaS PIM for Myntra and Amazon India scaling. DPDP Act data localization obligations accelerate replacement of legacy product databases with consent-managed systems. Bangalore and Mumbai technology corridors concentrate implementation partners for mid-market manufacturers.
United Kingdom
Beauty and home goods brands consolidate vendor relationships around bundled PIM-DAM-syndication platforms. GDPR data portability requirements influence cross-border product content governance. London marketing operations teams hold consolidated technology budgets driving procurement decisions.
China
Cross-border e-commerce exporters serving Amazon Europe and North America require automated localization and compliance formatting. SAMR data governance guidelines intersect with destination market regulations for product labeling. Shenzhen and Hangzhou digital commerce clusters concentrate PIM adoption among consumer electronics brands.
Global Product Information Management (PIM) Software Market Competitive Landscape
On the supply side, the industry is consolidating around platforms that bundle master data management with digital asset and syndication capabilities. Enterprise software conglomerates anchor the premium tier through deep ERP integration, while specialized vendors compete on composable architecture and channel-specific connectivity. Two strategic archetypes dominate: full-suite incumbents leveraging installed base relationships, and API-first challengers targeting mid-market velocity. Competitive moves center on generative AI feature integration and geographic expansion through local implementation partnerships.
Within the full-suite tier, Oracle and SAP exemplify enterprise-grade positioning through multi-domain master data capabilities. Salsify occupies a position among cloud-native specialists emphasizing marketplace connectivity for brand manufacturers. These three companies represent the spectrum from legacy ERP-anchored deployments to modern SaaS architectures, with each archetype serving distinct buyer risk profiles and implementation timelines.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| IBM |
| Informatica |
| Salsify |
| Akeneo |
| inriver |
| Pimcore |
| Stibo Systems |
| Others |
Supply & Pricing Matrix
Frankfurt-Mumbai air freight corridors carry SaaS implementation kits and custom integration modules, with cargo cost volatility compressing margins for mid-market vendors while amplifying price differentiation between ERP-anchored enterprise suites and API-first challenger platforms.
Pricing Analysis
Current-generation cloud-native architectures command subscription premiums against prior-generation on-premises licenses and next-generation edge-computing deployments still in pilot phase. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and workflow automation scope, with ISO 27001 certification tiers adding further differentiation. Pricing pressure stems from hyperscale compute cost escalation, particularly egress fees that squeeze SaaS-only providers serving high-velocity apparel brands. Mid-market manufacturers in India exhibit highest price sensitivity due to DPDP Act compliance budget allocation, while pharmaceutical conglomerates in Germany show lowest sensitivity given FDA 21 CFR Part 11 validation requirements.
Supply Chain Analysis
Supply-chain finance facilities extended by cloud infrastructure providers enable smaller vendors to bridge payment gaps with implementation partners across Germany, India, and the United States. Software development draws from engineering talent pools in Bangalore, Berlin, and Austin, with customer success operations anchored in London and Singapore. Single-source vulnerability concentrates in hyperscale compute provisioning, where AWS, Azure, and GCP dominance creates lock-in risk. Distribution runs through direct enterprise sales forces for SAP and Oracle, while API-first vendors rely on channel partners and marketplace listings for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PIM platforms are approaching a platform-economics inflection where GraphQL federation and composable commerce interoperability determine competitive survival, with Walmart and Target's direct brand data mesh ingestion signaling ecosystem consolidation.
For Market Incumbents: Pre-empt composable architecture displacement by embedding real-time API mesh capabilities that collapse batch synchronization latency, while consolidating DAM and syndication modules to defend against bundled challenger platforms. SAP and Oracle must accelerate REST interface modernization to reduce middleware friction that drives mid-market defections to Salsify and Akeneo. For New Entrants and Emerging Players: Mid-market apparel manufacturers in India managing Myntra and Amazon India marketplace expansion represent the most penetrable entry point, given DPDP Act-driven database replacement cycles and limited incumbent workflow automation penetration. SaaS-only deployment with zero infrastructure footprint, paired with TikTok Shop-native syndication templates, offers rapid time-to-value positioning against ERP-anchored alternatives. For Investors and Strategic Acquirers: API-first specialists with proven GraphQL federation implementations and established channel partnerships in Germany or India present the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on generative AI feature integration that satisfies EU AI Act explainability mandates without eroding regulatory defensibility. Monitor FDA 21 CFR Part 11 audit trail adoption rates among pharmaceutical PIM deployments as signal for enterprise-grade compliance premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GraphQL federation with Walmart and Target data meshes compresses time-to-shelf from days to minutes. |
| Acquisition of Specialist Firm | DAM-native vendors with automated variant generation capabilities address beauty brand localization velocity requirements. |
| Geographic Expansion | Implementation partnerships in Bangalore and Mumbai capture DPDP Act-driven database replacement demand. |
| Product Launch | VIN-specific fitment modules for German automotive aftermarket suppliers unlock Amazon and eBay Kleinanzeigen connectivity. |
| Strategic Partnership | Hyperscaler alliances with AWS or Azure mitigate compute cost volatility squeezing SaaS-only margins. |
Research Methodology
Operator-level perspectives from PIM implementation leads, enterprise IT procurement officers, channel integration specialists, and regulatory compliance directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, and FDA 21 CFR Part 11 guidance documents. Bottom-up deployment modeling across cloud, on-premises, hybrid, and SaaS-only architectures triangulated against top-down market sizing derived from SAP, Oracle, and Salesforce segment disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning deployment architecture, solution type, end-user industry, and integration complexity tiers. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act compliance timelines, India's DPDP Act implementation phases, and pharmaceutical serialization mandate expansion. Forecast inputs included channel expansion velocity at TikTok Shop and Amazon, plus data steward salary premium trajectories affecting mid-market implementation feasibility.
Practitioners should monitor hyperscale compute pricing volatility, EU AI Act enforcement precedent in Germany and France, and FDA 21 CFR Part 11 audit intensity for early signals of vendor margin compression or compliance cost escalation. Forecasts reflect documented assumptions regarding composable commerce adoption rates and regulatory implementation timelines; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Licensing Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Session Support Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Simulation Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Output Management Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Digital Signage Software Market