
 Thermal Inkjet Inks Market | 2026-2036
Thermal Inkjet Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Inkjet Inks Market Analytics
Specialized ink distribution through regional converter networks is reconfiguring as direct procurement from manufacturers gains share. HP Development Company, L.P. leverages its printhead-ink ecosystem to sustain recurring revenue streams across industrial installations. Sun Chemical anchors European supply through backward integration into pigment manufacturing. TOYO INK Corporate dominates Asian electronics labeling with localized formulation facilities.
Thermal inkjet inks are aqueous or solvent-based fluid formulations designed for vaporization via resistive heating elements at 300–600°C, ejecting droplets through precision nozzles to deposit alphanumeric codes, barcodes, or graphics onto porous and non-porous substrates. The technology serves primary industrial functions in variable data printing, traceability marking, and short-run customization where mechanical contact would damage sensitive surfaces. Water-based inks lead volume in corrugated and paper packaging applications where porosity enables rapid absorption, while UV-curable formulations capture margin pools in electronics manufacturing and pharmaceutical serialization by delivering instant polymerization on non-porous synthetics. Solvent-based inks retain structural importance in flexible film and foil coding despite regulatory pressure on volatile organic compound emissions.
EPA regulations in the United States restrict hazardous air pollutant content in industrial ink formulations, compelling reformulation investments and filtering smaller compounders from approved supplier lists. REACH and RoHS frameworks in Europe impose substance disclosure and restriction protocols that extend compliance burdens through the entire packaging supply chain. FDA serialization mandates for pharmaceutical packaging create structural demand for high-adhesion, smear-resistant batch coding inks that withstand distribution chain abrasion. Stakeholders must monitor evolving chemical restriction schedules and assess captive ink formulation capabilities against third-party supply reliability.
Market Dynamics
Water-based ink formulations are displacing solvent chemistry across packaging lines as REACH and EPA frameworks tighten permissible volatile organic compound thresholds, forcing converters to rebuild supply relationships around compliant pigment systems.
Growth Catalysts
- FDA Serialization Mandates:Pharmaceutical packaging regulations in the United States require unit-level traceability, creating structural pull for smear-resistant batch coding inks that survive distribution abrasion.
- Electronics Labeling Scale:China's export manufacturing zones demand variable data printing on synthetic substrates as production volumes expand, concentrating ink procurement near Shenzhen and Dongguan clusters.
- Water-Based Chemistry Maturation:Advances in latex and hybrid polymer binders now enable comparable adhesion on non-porous films without solvent content, satisfying ECHA substance restriction protocols.
Market Restraints
- Pigment Supply Concentration:Specialty colorant production clusters in Germany and Japan, exposing formulators to freight cost volatility and single-source risk for high-performance blacks and metallics.
- Printhead Interoperability Lock-In:Proprietary nozzle architectures from dominant equipment vendors restrict third-party ink compatibility, compressing margin pools for independent chemical suppliers.
- UV Monomer Cost Structure:Photoinitiator and oligomer inputs track petrochemical indices, creating formulation cost instability that UV-curable segment producers cannot fully pass to price-sensitive corrugated converters.
Strategic Opportunities
- Indian Pharmaceutical Export Growth:CDSCO serialization requirements for export-bound generics create demand for high-adhesion coding inks as Mumbai and Hyderabad packaging hubs expand capacity.
- Biodegradable Substrate Compatibility:Compostable flexible films emerging in European food packaging require novel ink chemistries that maintain code integrity through anaerobic decomposition testing protocols.
- Direct Procurement Platforms:Converter networks are experimenting with manufacturer-bypass purchasing for high-volume black inks, disintermediating regional distributors in North American corrugated segments.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in colloidal stability and rheology tuning for thermal inkjet applications concentrates among aging specialists in Basel and Osaka, constraining R&D expansion.
- REACH Pre-Registration Timelines:New substance notification protocols extend compliance lead times to 18-24 months, delaying market entry for novel bio-based binder chemistries.
- Legacy Printhead Integration:Retrofitting aqueous ink systems onto solvent-configured production lines demands capital expenditure in drying infrastructure and substrate pretreatment stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Inkjet Inks Market |
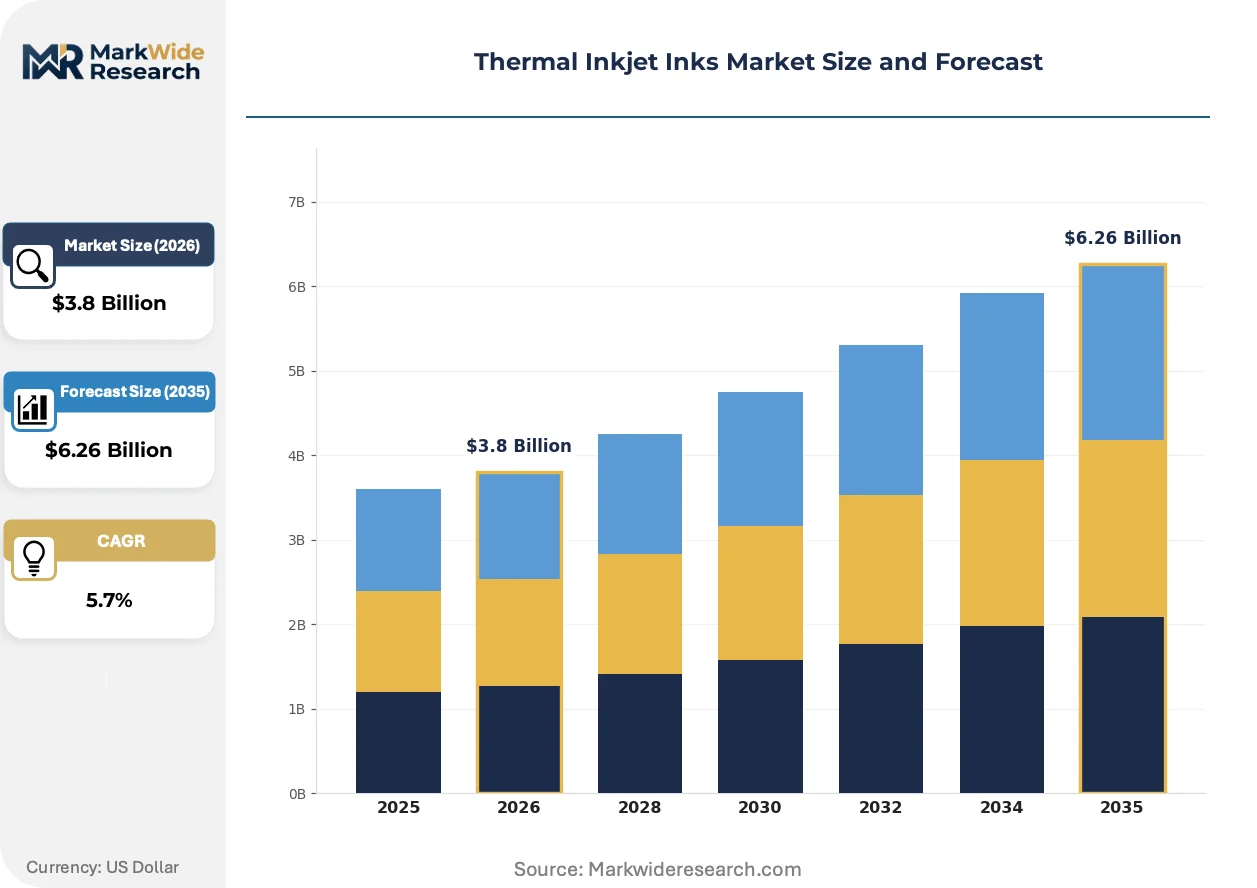
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based Inks, Solvent-based Inks, UV-curable Inks, Dye-based Inks End User: Packaging Industry, Textile Industry, Printing Services, Electronics Manufacturing Ink Composition: Colorant, Additives, Solvent, Polymer Application: Label Printing, Direct-to-Object Printing, QR Code Printing, Batch Coding |
| Companies Covered | Videojet Technologies, Inc., HP Development Company, L.P., TOYO INK Corporate, Sun Chemical, Mylan Group, Union Chemicar Co., Ltd, Rex-Tone Industries Ltd, Linx Printing Technologies Ltd., INX International Ink Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Inkjet Inks Market Evolving Landscape
Reformulation investments now dominate R&D allocation as regulatory chemistry restrictions outpace incremental nozzle engineering gains, redirecting competitive advantage toward pigment synthesis and binder polymerization expertise.
Nano-pigment dispersion technology is rendering obsolete conventional micron-scale colorant grinding for high-resolution barcode applications. Pharmaceutical contract packagers in Switzerland and Germany are adopting sub-100nm particle systems to achieve 600dpi legibility on blister foil micro-text. This particle size compression is rendering obsolete legacy formulation equipment designed for standard grind specifications, forcing capital retooling among mid-tier ink compounders.
REACH Annex XVII expansion is restricting additional solvent families across European flexible packaging operations. ECHA substance evaluation schedules now target N-methyl-2-pyrrolidone and specific glycol ethers, compelling converters to validate water-based alternatives ahead of sunset dates. Electronics labeling facilities in Slovakia and Hungary are most affected, accelerating qualification programs for UV-curable drop-in replacements.
Regional converter networks are consolidating procurement authority as direct manufacturer relationships yield volume pricing advantages previously captured by distributors. Mid-sized folding carton operations in the US Midwest and northern Italy are forming purchasing cooperatives to standardize on single ink platforms, compressing SKU complexity. This concentration is most visible in German pharmaceutical packaging clusters, where three converter groups now control majority ink specification decisions for serialization lines.
Thermal Inkjet Inks Market Segmentation
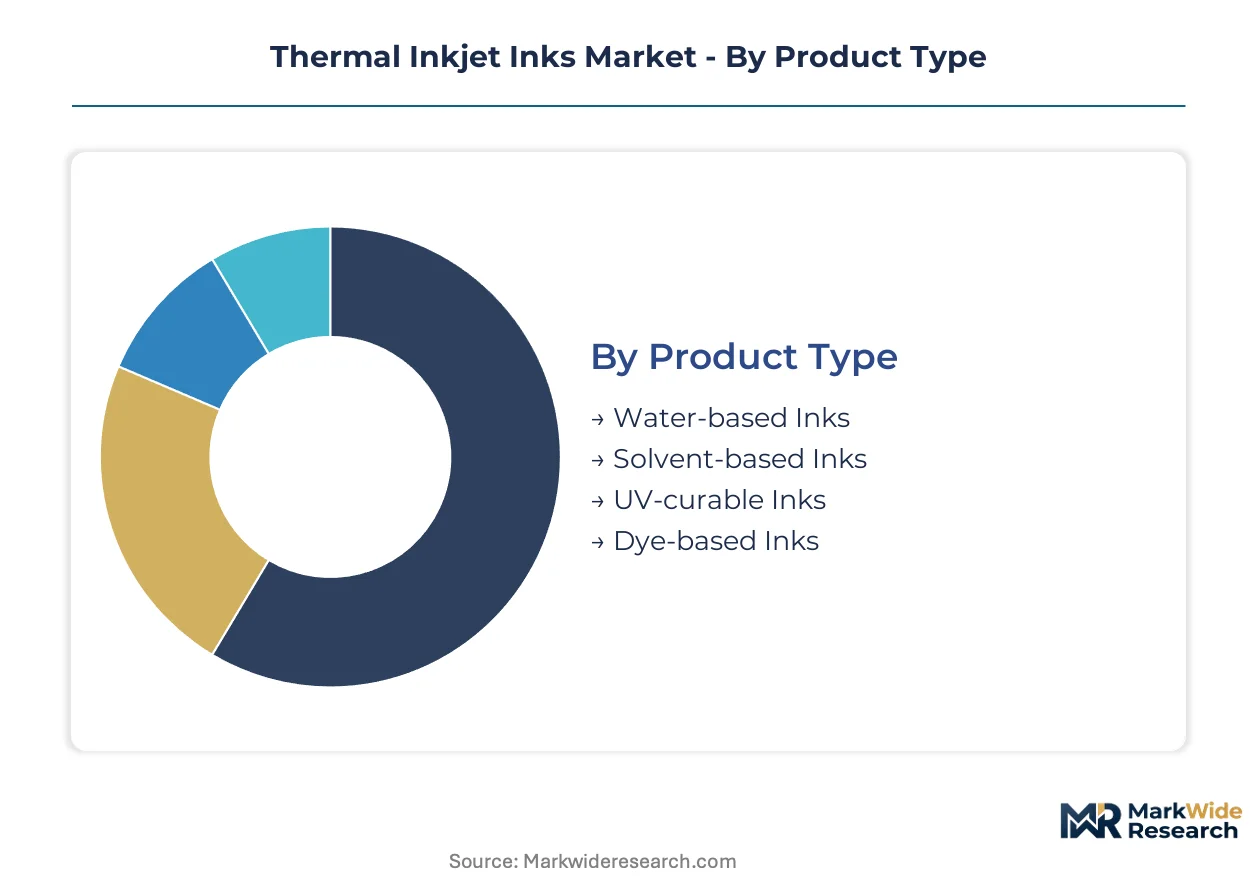
Thermal inkjet inks segment across formulation chemistry, end-use substrate compatibility, and regulatory compliance tiers. Procurement decisions hinge on porosity requirements, drying infrastructure, and volatile organic compound thresholds specific to each application environment.
Product Type:
Use cases span from absorbent corrugated substrates requiring rapid penetration to non-porous synthetics demanding instant cure chemistry.
- Water-based Inks:Aqueous formulations with latex or hybrid polymer binders penetrate porous paper and board substrates through capillary action. Pharmaceutical contract packagers in the United States deploy these systems for FDA-compliant serialization on folding cartons, though drying station capital limits retrofit adoption on legacy solvent-configured lines.
- UV-curable Inks:Photoinitiator-oligomer systems polymerize instantly under LED or mercury arc exposure, enabling adhesion on polyethylene and polypropylene films without solvent content. Electronics labeling facilities in Shenzhen and Dongguan clusters specify these formulations for synthetic substrate durability, despite petrochemical-indexed input cost volatility.
- Solvent-based Inks:VOC-containing formulations retain structural importance in flexible film coding where rapid evaporation prevents smearing on non-porous surfaces.
- Dye-based Inks:Molecular colorant solutions deliver high chroma on coated papers for short-run graphic applications where lightfastness requirements remain moderate.
The dominant share belongs to Water-based Inks, while UV-curable Inks is closing the gap fastest.
End User:
Customer procurement authority concentrates where serialization mandates and export volume scaling create structural ink demand.
- Packaging Industry:Corrugated converters and folding carton operations specify inks for variable data printing, batch coding, and traceability marking. Indian pharmaceutical export growth through Mumbai and Hyderabad hubs is pulling high-adhesion formulations for CDSCO-compliant serialization.
- Electronics Manufacturing:Component labeling and device marking operations demand smear-resistant codes on synthetic substrates. China's export manufacturing zones concentrate procurement near production clusters, with formulation facilities localized to Shenzhen industrial corridors.
- Printing Services:Commercial print providers source inks for short-run customization and graphic applications across mixed substrate portfolios.
- Textile Industry:Direct-to-garment and fabric marking applications specify dye-based or pigment systems compatible with cotton and synthetic fiber absorbency profiles.
Packaging Industry commands the largest procurement volume, though Electronics Manufacturing is expanding most quickly.
Ink Composition:
Component cost structures and supply concentration risks differentiate formulation tiers across the value chain.
- Colorant:Pigment and dye inputs determine optical density, lightfastness, and barcode legibility specifications. Nano-pigment dispersion technology is displacing conventional micron-scale grinding for 600dpi pharmaceutical micro-text applications in Swiss and German contract packaging facilities.
- Solvent:Carrier fluid selection dictates evaporation rate, viscosity, and regulatory compliance profile. REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and glycol ethers are accelerating validation of water-based alternatives in Slovakian and Hungarian electronics labeling plants.
- Additives:Surfactants, defoamers, and rheology modifiers stabilize colloidal systems and optimize droplet formation at 300–600°C vaporization temperatures.
- Polymer:Binder systems including latex, acrylic, and hybrid chemistries control adhesion, flexibility, and rub resistance on target substrates.
Colorant represents the highest-value input category, while Polymer is gaining specification share fastest.
Application:
Functional requirements range from static graphic reproduction to dynamic variable data insertion at production line speeds.
- Batch Coding:Alphanumeric and date stamp applications require smear-resistant adhesion through distribution chain abrasion. FDA serialization mandates in the United States create structural demand for high-durability formulations that survive pharmaceutical supply chain handling.
- QR Code Printing:Two-dimensional matrix codes demand precise droplet placement and substrate contrast for reliable machine readability. Sub-100nm pigment systems enable 600dpi legibility on blister foil micro-text in Swiss pharmaceutical packaging operations.
- Label Printing:Adhesive-backed substrate marking spans paper, film, and synthetic face stocks with varying absorbency and cure requirements.
- Direct-to-Object Printing:Non-label marking on three-dimensional surfaces requires inkjet systems with throw distance tolerance and curved surface adhesion.
Batch Coding retains the dominant application share, while QR Code Printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's ink formulation hub status, while Shenzhen's Yantian container terminals anchor Asia-Pacific electronics labeling supply chains.
United States
FDA serialization mandates for pharmaceutical packaging pull high-adhesion batch coding inks through distribution networks. EPA hazardous air pollutant restrictions compel reformulation investments among compounders serving Midwest corrugated converters. Chicago and Milwaukee packaging clusters are retrofitting aqueous systems onto legacy solvent-configured lines.
Germany
REACH Annex XVII expansion targets N-methyl-2-pyrrolidone and glycol ethers in flexible film operations. ECHA substance evaluation protocols extend compliance burdens through pharmaceutical packaging supply chains. Basel-centered formulation chemists concentrate expertise in colloidal stability for nano-pigment dispersion systems.
China
Export manufacturing zones in Shenzhen and Dongguan scale electronics labeling requirements with production volume. SAMR standardization frameworks and dual carbon goals pressure converters toward water-based alternatives. Pearl River Delta industrial corridors localize formulation facilities to serve synthetic substrate marking demand.
India
CDSCO serialization requirements for export-bound generics create structural demand for smear-resistant coding inks. Mumbai and Hyderabad pharmaceutical packaging hubs expand capacity to capture contract manufacturing flows. DGFT trade facilitation programs accelerate ink qualification timelines for EU-bound shipments.
Switzerland
Swissmedic pharmaceutical serialization standards drive 600dpi micro-text legibility specifications on blister foil. Contract packagers in Basel and Zurich adopt sub-100nm pigment systems for high-resolution barcode applications. Alpine logistics corridors connect formulation facilities to German and French pharmaceutical clusters.
Thermal Inkjet Inks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pigment synthesis and binder polymerization. The vendor base organizes around three archetypes: printhead-ink ecosystem operators, backward-integrated pigment manufacturers, and regional formulation compounders. Consolidation pressures concentrate among mid-tier ink suppliers lacking captive colorant production. Dominant competitive moves include strategic partnerships for nano-pigment dispersion licensing and geographic expansion through localized blending facilities.
Among diversified chemical conglomerates, HP Development Company, L.P. and Sun Chemical occupy positions spanning equipment-ink integration and backward-integrated pigment supply respectively. TOYO INK Corporate exemplifies the Asia-Pacific electronics labeling specialist archetype with localized formulation infrastructure. These three anchors represent distinct competitive vectors: ecosystem lock-in, upstream supply control, and regional market proximity.
| Leading Market Players |
|---|
| Videojet Technologies, Inc. |
| HP Development Company, L.P. |
| TOYO INK Corporate |
| Sun Chemical |
| Mylan Group |
| Union Chemicar Co., Ltd |
| Rex-Tone Industries Ltd |
| Linx Printing Technologies Ltd. |
| INX International Ink Co |
| Others |
Value Network & Pricing Analysis
Pigment synthesis concentration in Germany and Japan anchors margin capture at the colorant tier, leaving downstream formulators exposed to freight volatility and single-source premiums for high-performance blacks and metallics. Ink procurement authority is shifting toward converter cooperatives that leverage volume aggregation to compress distributor markups and standardize specification decisions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical serialization inks from general industrial coding formulations and commodity black inks for corrugated applications. Price differentiation rests on certification grade and volume scale, with REACH-compliant water-based formulations commanding premiums over solvent alternatives. Cost compression in standard-tier products is intensifying as Chinese export manufacturers consolidate procurement through direct manufacturer relationships. Corrugated converters in North American Midwest clusters exhibit highest price sensitivity, while Swiss pharmaceutical contract packagers prioritize legibility specifications over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electronics labeling facilities sourcing UV-curable formulations. Specialty colorant production clusters in Germany, Japan, and select Swiss facilities, with photoinitiator and oligomer inputs tracking petrochemical indices. Single-source vulnerability concentrates in nano-pigment dispersion equipment and legacy printhead architectures. Distribution runs through regional converter networks that are consolidating procurement authority, though direct manufacturer platforms are gaining share in high-volume black ink segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through purchasing cooperatives among mid-sized folding carton operations, fragmenting historical distributor control over specification decisions and compressing margin pools for independent chemical suppliers.
For Market Incumbents: Pre-empt proprietary printhead lock-in erosion by deepening captive pigment synthesis capabilities and securing REACH pre-registration timelines for novel bio-based binder chemistries. HP Development Company, L.P.'s printhead-ink ecosystem model offers a defensive template against independent formulation competitors. Backward integration into nano-pigment dispersion technology represents the priority lever for margin defense. For New Entrants and Emerging Players: Indian pharmaceutical export growth through Mumbai and Hyderabad packaging hubs represents the most penetrable entry point for high-adhesion coding inks meeting CDSCO serialization requirements. Compostable flexible film compatibility for European food packaging presents a second white-space target requiring novel anaerobic decomposition-resistant chemistries. Direct procurement platform partnerships with North American corrugated cooperatives offer the most viable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional formulation compounders lacking captive colorant production and exposed to pigment supply concentration risks. Long-term viability over a five-to-ten year window favors backward-integrated specialists with REACH compliance infrastructure and localized blending facilities. Monitor ECHA substance evaluation schedules for N-methyl-2-pyrrolidone and glycol ether restrictions as the critical inflection signal for water-based formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Sun Chemical's captive colorant production anchors European supply against freight volatility from German and Japanese specialty producers. |
| Localized Formulation Facilities | TOYO INK Corporate's Shenzhen corridor presence captures electronics labeling demand scaling with China's export manufacturing zones. |
| REACH Pre-Registration Investment | ECHA substance notification protocols extending to 18-24 months create compliance barriers favoring incumbents with established regulatory infrastructure. |
| Direct Procurement Platform Development | Manufacturer-bypass purchasing experiments among North American corrugated converters threaten regional distributor margins and SKU complexity. |
| Nano-Pigment Dispersion Licensing | Sub-100nm particle systems enabling 600dpi pharmaceutical micro-text legibility render obsolete legacy grinding equipment among mid-tier compounders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ink formulation chemists, pharmaceutical packaging procurement managers, corrugated converter operations directors, and electronics manufacturing supply chain leads. Secondary validation drew from ECHA substance evaluation databases, FDA serialization guidance documents, SEC filings of diversified chemical conglomerates, and customs trade data tracking pigment and photoinitiator flows. Bottom-up volume modeling across formulation chemistry tiers and end-use applications was triangulated against top-down market sizing from equipment installation bases and printhead replacement cycles.
Calibration against historical pricing trajectories and regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include formulation chemistry, substrate compatibility class, regulatory compliance tier, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand projections incorporating FDA and CDSCO serialization mandate phase-ins, SAMR standardization frameworks, and dual carbon goal pressures on water-based adoption. Industry-specific inputs captured printhead interoperability constraints and REACH Annex XVII substance restriction schedules.
Stress conditions across pigment supply disruption scenarios, REACH timeline accelerations, and electronics export volume contractions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation fidelity and converter capital expenditure availability for aqueous system retrofits. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Squid Ink Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Functional Printing Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Printing Plate Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Specialty Ink Market
Printing Inks
Global Light Changing Packaging Inks Market